
 Paper Napkins Converting Machines Market | 2026-2036
Paper Napkins Converting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Napkins Converting Machines Market Analytics
Digital servo control integration is rewriting the performance envelope for paper napkin converting equipment, replacing mechanical cam systems with programmable multi-axis motion profiles. Gambini leverages deep expertise in high-speed embossing configurations to anchor premium positioning across European foodservice supply chains. PCMC competes through modular platform architectures that reduce changeover intervals for private-label converters. Jiuhyan Precision Machinery dominates cost-optimized segments in Asia through vertically integrated casting and machining operations.
Paper napkins converting machines are industrial equipment designed to transform parent tissue rolls into folded, embossed, and cut napkin products at speeds typically ranging from 300 to 1,200 pieces per minute, employing rotary knives, vacuum transfer systems, and servo-actuated folding mechanisms to achieve dimensional consistency. Multi-servo machines command attention from operators seeking format flexibility without mechanical retooling, while automatic machines sustain volume leadership in dedicated high-throughput installations serving quick-service restaurant supply contracts. Hybrid technology configurations that blend pneumatic actuation with electronic control are gaining traction where legacy mechanical infrastructure constrains full digital retrofit budgets.
CE marking under the EU Machinery Directive shapes design requirements for equipment sold across European member states, while China's GB standards and SAMR oversight govern safety interlocks and electromagnetic compatibility for domestic and export-bound machinery. The US OSHA machinery guarding standards influence North American equipment specifications, particularly regarding nip-point protection and emergency stop circuit redundancy. Stakeholders must monitor how evolving servo safety protocols and energy efficiency benchmarks reshape capital equipment specifications and aftermarket upgrade cycles.
Market Dynamics
Digital servo control architectures are displacing mechanical cam systems across paper napkin converting equipment, compressing changeover times from hours to minutes while forcing incumbent manufacturers to reengineer legacy platforms or cede share to modular competitors.
Growth Catalysts
- CE marking compliance:EU Machinery Directive requirements for safety interlocks and emergency stop redundancy are accelerating replacement cycles among European tissue converters seeking uninterrupted market access.
- Quick-service restaurant expansion:Southeast Asian foodservice chains in Vietnam, Indonesia, and Thailand are procuring high-throughput machines to match dine-in volume recovery trajectories.
- Servo-driven automation:Multi-axis motion control systems enable format flexibility without mechanical retooling, attracting private-label converters managing diverse SKU portfolios.
Market Restraints
- Parent roll supply concentration:Specialty tissue substrate availability clusters among integrated pulp producers, exposing converters to input cost volatility and allocation constraints during demand surges.
- GB standards harmonization:China's SAMR electromagnetic compatibility and safety interlock requirements create friction for European and North American equipment exporters seeking market entry.
- Mechanical infrastructure lock-in:Legacy pneumatic and cam-based installations constrain full digital retrofit economics, delaying automation adoption among capital-constrained mid-tier operators.
Strategic Opportunities
- Hybrid technology configurations:Blending pneumatic actuation with electronic control creates accessible upgrade pathways for operators with legacy infrastructure budget constraints.
- Aftermarket servo retrofit kits:Modular upgrade packages targeting installed base machines in Italy and Germany extend equipment lifecycles while capturing recurring revenue streams.
- OSHA-aligned safety packages:North American quick-service restaurant supply chains demand nip-point protection and redundant emergency stop circuits, creating specification premiums for compliant equipment.
Industry Challenges
- Multi-axis motion programming expertise:Servo system commissioning and troubleshooting require specialized automation engineering skills scarce among traditional mechanical maintenance teams.
- CE marking certification timelines:EU Machinery Directive conformity assessment processes for novel servo safety protocols extend time-to-market for equipment introductions.
- Legacy system integration complexity:Vacuum transfer and folding mechanism synchronization with new digital controls demands custom mechanical-electrical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Napkins Converting Machines Market |
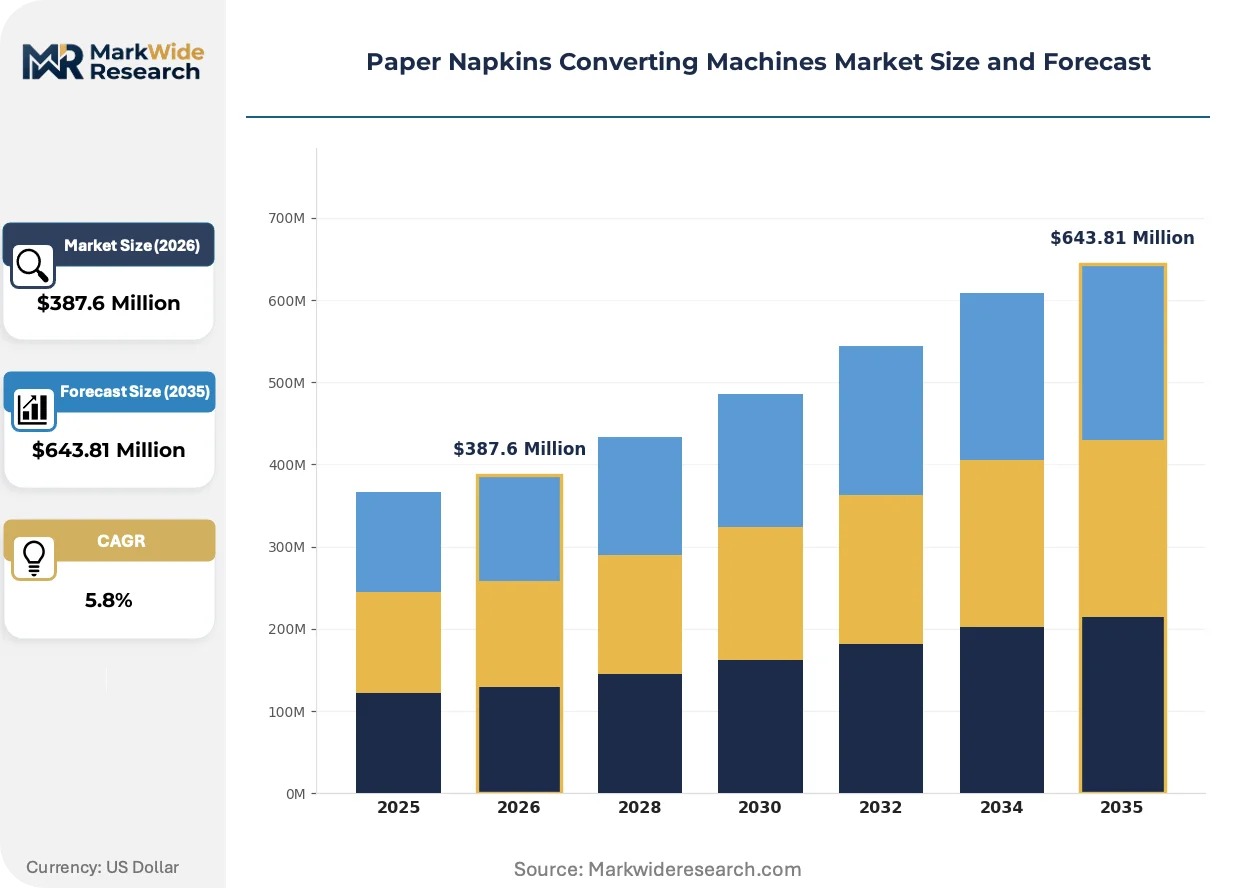
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Servo Machines, Multi-Servo Machines, Manual Machines, Automatic Machines End User: Restaurants, Hotels, Catering Services, Household Application: Disposable Products, Hygienic Napkins, Industrial Use, Custom Printed Napkins Technology: Mechanical Technology, Electronic Technology, Pneumatic Technology, Hybrid Technology |
| Companies Covered | Gambini, PCMC, Jiuhyan Precision Machinery, Foshan Baosuo Machinery Manufacturing, Andritz, Valmet, Futura, Birla Hi Tech Machines, Dechangyu Paper Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Napkins Converting Machines Market Evolving Landscape
Servo-actuated control architectures are rewriting operational benchmarks across napkin converting, enabling programmable motion profiles that mechanical systems cannot replicate. Three developments are compressing competitive differentiation timelines.
Multi-servo machine platforms are digitizing format changeover workflows by replacing fixed mechanical cams with software-configurable motion profiles. Mid-scale converters in Poland and Spain are adopting these systems to service fragmented private-label contracts without production downtime. This digitizing capability is compressing minimum efficient scale thresholds and enabling shorter-run economics previously exclusive to dedicated high-volume lines.
EU Machinery Directive amendments emphasizing functional safety for servo-driven equipment are reshaping design specifications. Manufacturers must now integrate certified safety PLCs and redundant encoder feedback loops to maintain CE marking validity. European foodservice supply chain equipment procurement is tightening qualification criteria, favoring suppliers with documented safety integrity level certifications.
After-sales service unbundling is disrupting traditional equipment procurement patterns. Vietnamese and Indonesian tissue converters are separating hardware acquisition from commissioning, training, and spare parts agreements, treating these as distinct commercial decisions. Quick-service restaurant supply contractors in Bangkok and Ho Chi Minh City are driving this fragmentation, demanding transparent lifecycle cost structures rather than bundled turnkey pricing.
Paper Napkins Converting Machines Market Segmentation
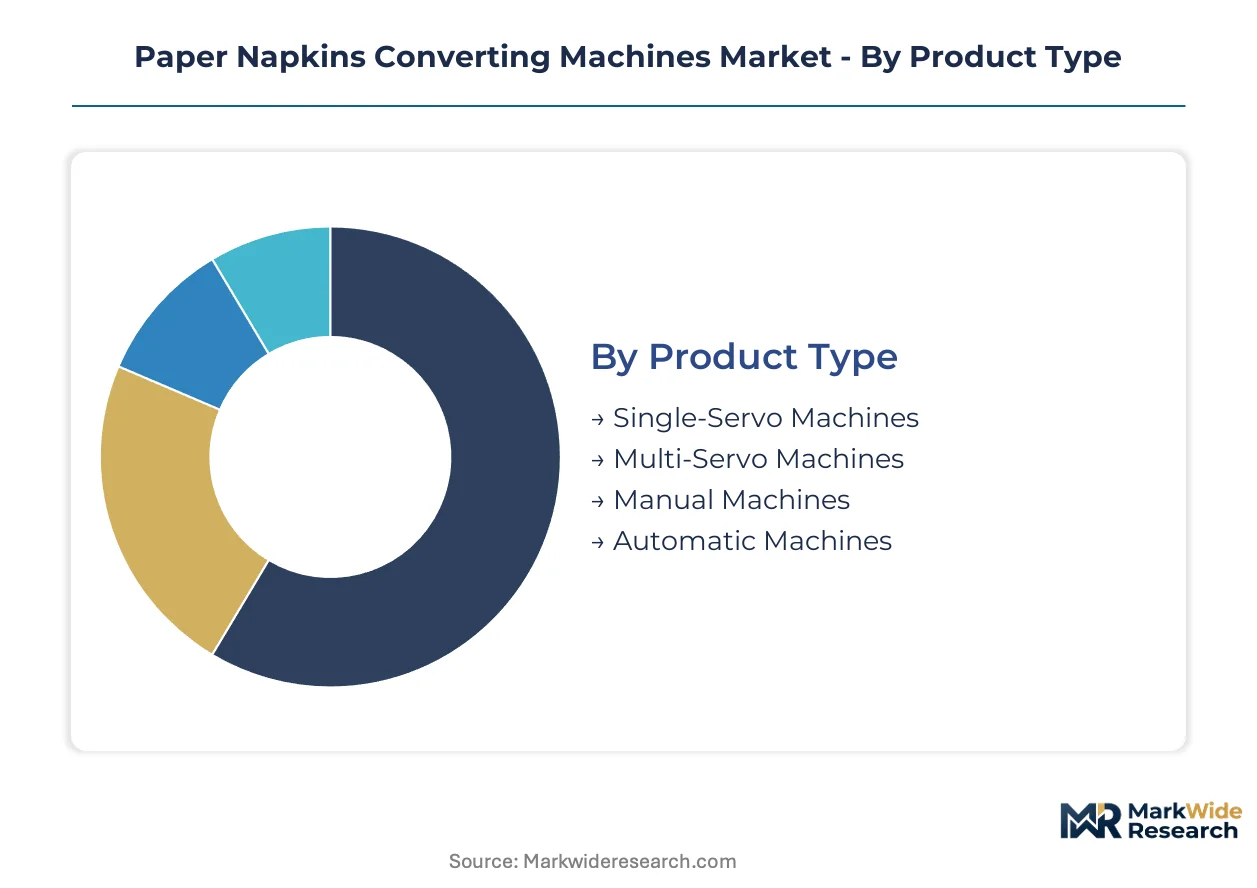
Paper napkin converting machines segment across four dimensions that shape procurement patterns and technology investment cycles. Product type and technology architecture determine capital intensity and operational flexibility, while end-user concentration and application requirements dictate regional equipment specifications.
Product Type:
Cost tier stratification separates entry-level mechanical systems from premium servo-driven platforms with programmable motion control.
- Multi-Servo Machines:Programmable multi-axis motion profiles replace fixed mechanical cams, enabling format changes without retooling. Polish and Spanish private-label converters deploy these systems to service fragmented SKU portfolios with minimal downtime.
- Automatic Machines:Dedicated high-throughput configurations sustain volume leadership in quick-service restaurant supply contracts across Vietnam and Thailand, where dine-in recovery drives capacity expansion.
- Single-Servo Machines:Entry-level automation for mid-tier operators bridging mechanical and fully digital platforms.
- Manual Machines:Low-capital configurations serving artisanal producers and micro-converters in emerging markets.
Automatic machines command the established base. The steepest expansion runs through multi-servo platforms.
End User:
Customer type concentration clusters around foodservice procurement with divergent volume and customization requirements.
- Restaurants:Quick-service chains in Indonesia and Thailand procure high-speed automatic lines to match dine-in volume trajectories, with CE marking compliance mandatory for European supply chain integration.
- Catering Services:Event and institutional foodservice operators demand rapid format flexibility for seasonal volume spikes and custom branding requirements.
- Hotels:Premium hospitality specifications emphasize embossing quality and aesthetic finishing for guest-facing table settings.
- Household:Retail-packaged napkin producers serving supermarket private-label contracts with standardized formats and high-volume economics.
Restaurant procurement anchors current installed capacity. Catering services are climbing the fastest as event volumes normalize post-pandemic.
Application:
Volume and margin characteristics diverge sharply between commodity disposables and value-added specialized outputs.
- Disposable Products:Standard folded napkins for foodservice represent the volume anchor, with converters in Ho Chi Minh City and Bangkok optimizing throughput over customization.
- Custom Printed Napkins:Branded hospitality and promotional applications command specification premiums, with European foodservice supply chains tightening qualification criteria under amended EU Machinery Directive safety protocols.
- Hygienic Napkins:Medical and institutional specifications requiring certified substrate handling and contamination control.
- Industrial Use:Wiping and process applications with lower finishing requirements but demanding substrate durability.
Disposable products retain the volume base. Custom printed applications gain share fastest through premium positioning.
Technology:
Maturity and automation level segment the installed base from legacy mechanical through emerging hybrid configurations.
- Electronic Technology:Full digital servo control with safety PLC integration and redundant encoder feedback, now mandatory for CE marking validity under amended EU Machinery Directive requirements.
- Hybrid Technology:Blends pneumatic actuation with electronic control, creating accessible upgrade pathways for Italian and German operators with legacy infrastructure budget constraints.
- Mechanical Technology:Cam-driven legacy platforms concentrated in mature European installed bases facing replacement cycles.
- Pneumatic Technology:Compressed-air actuation systems prevalent in cost-optimized Asian manufacturing configurations.
Mechanical technology holds the legacy installed base. Electronic platforms are expanding most quickly through regulatory compliance mandates and performance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian equipment manufacturers export servo-driven converting platforms to Southeast Asian tissue converters, while Chinese fabricators supply cost-optimized mechanical systems to emerging markets across Africa and Latin America.
Italy
CE marking compliance under the EU Machinery Directive accelerates replacement cycles among domestic tissue converters seeking uninterrupted market access. Gambini and PCMC anchor premium positioning through high-speed embossing expertise and modular platform architectures. The Lucca tissue cluster drives machinery innovation as local manufacturers integrate certified safety PLCs and redundant encoder feedback loops to maintain conformity validity.
Germany
OSHA-aligned safety specifications from North American quick-service restaurant supply chains create export demand for nip-point protection and emergency stop circuit redundancy. The country's national machinery safety regulator enforces functional safety protocols for servo-driven equipment. Industrial concentrations in Baden-Württemberg and North Rhine-Westphalia host aftermarket servo retrofit specialists targeting legacy installed bases with modular upgrade packages.
China
GB standards and SAMR electromagnetic compatibility requirements govern safety interlocks for domestic machinery and export-bound equipment. Jiuhyan Precision Machinery dominates cost-optimized segments through vertically integrated casting and machining operations. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate capacity expansion as local tissue converters scale to serve foodservice chain procurement.
Vietnam
Quick-service restaurant dine-in volume recovery drives machinery procurement from Ho Chi Minh City-based converters expanding capacity. The country's national standards body implements technical regulations harmonizing with ASEAN machinery safety frameworks. Southern industrial zones around Bình Dương and Đồng Nai attract equipment investment as supply contractors demand transparent lifecycle cost structures.
Indonesia
Foodservice chain expansion across Jakarta and Surabaya metropolitan areas sustains demand for high-throughput automatic machines. Local content requirements in government procurement influence equipment sourcing decisions for state-linked hospitality projects. The Cikarang manufacturing corridor hosts tissue converting operations scaling to match regional dine-in recovery trajectories.
Paper Napkins Converting Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into consolidated premium-tier suppliers with documented safety certifications and fragmented cost-optimized fabricators serving price-sensitive procurement. Three archetypes dominate: European precision-engineering specialists, Asian scale-driven manufacturers, and hybrid-technology integrators bridging pneumatic legacy with electronic control. Geographic expansion and technology licensing represent the dominant competitive moves as incumbents reengineer platforms to defend position against modular competitors.
Among European precision-engineering specialists, Gambini and PCMC occupy positions anchored by deep expertise in high-speed embossing configurations and modular platform architectures respectively. Jiuhyan Precision Machinery exemplifies the Asian scale-driven archetype through cost-optimized manufacturing configurations. These three companies represent distinct competitive vectors: premium positioning through technical specification, format flexibility through modular design, and volume leadership through integrated production economics.
| Leading Market Players |
|---|
| Gambini |
| PCMC |
| Jiuhyan Precision Machinery |
| Foshan Baosuo Machinery Manufacturing |
| Andritz |
| Valmet |
| Futura |
| Birla Hi Tech Machines |
| Dechangyu Paper Machinery |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed equipment pricing for Asian fabricators exporting to European tissue converters, compressing margins for mid-tier operators while amplifying price differentiation between CE-certified servo platforms and legacy mechanical systems.
Pricing Analysis
The multi-generational pricing gap separates electronic servo platforms from hybrid configurations and legacy mechanical systems. Three-tier pricing structure across premium CE-certified, standard automatic, and economy mechanical levels anchors the market, with differentiation driven by safety PLC certification and after-sales service bundling. Cost compression in the mechanical tier is intensifying because Vietnamese and Indonesian buyers are unbundling commissioning and spare parts agreements from hardware acquisition. Private-label converters in Poland and Spain exhibit the highest price sensitivity, while quick-service restaurant supply chains in Thailand prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with vertically integrated fabricators in China's Yangtze River Delta and Pearl River Delta, where Jiuhyan Precision Machinery and Foshan Baosuo control cost-optimized casting and machining capacity. Geographic supply concentration clusters in China, Italy, and Germany, with raw material dependencies on specialty steel alloys, precision bearings, and servo motor drives. Single-source vulnerability runs through European safety PLC and redundant encoder suppliers subject to CE marking certification backlogs. Distribution runs through direct OEM sales for premium tiers and regional equipment distributors serving emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-driven automation is disrupting paper napkin converting equipment procurement patterns, with amended EU Machinery Directive safety protocols forcing replacement cycles that favor certified suppliers over legacy mechanical incumbents.
For Market Incumbents: Pre-empt modular competitors by accelerating aftermarket servo retrofit kit deployment across Italy and Germany's installed base, while integrating certified safety PLCs to defend CE marking validity against emerging Asian entrants with faster certification timelines. Capacity addition in Vietnam's Bình Dương industrial zone offers geographic hedge against European replacement cycle volatility.
For New Entrants and Emerging Players: Indonesia's Cikarang manufacturing corridor offers the most penetrable geography for cost-optimized hybrid technology platforms, where local content requirements in state-linked hospitality procurement create specification entry points. Target event and institutional catering services for rapid format flexibility demand, deploying transparent lifecycle cost structures to displace bundled turnkey incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant tissue machinery divisions holding dormant CE marking expertise and Lucca cluster engineering talent. Long-term viability hinges on servo safety protocol certification depth rather than mechanical legacy scale. Watch for EU Machinery Directive amendment implementation timelines as the signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Retrofit Kit Development | Captures recurring revenue from Italy and Germany's legacy installed base while extending equipment lifecycles. |
| CE Marking Fast-Track Certification | Accelerates time-to-market for novel safety PLC integrations under amended EU Machinery Directive requirements. |
| Hybrid Technology Platform Launch | Bridges pneumatic legacy infrastructure with electronic control for capital-constrained mid-tier operators. |
| After-Sales Service Unbundling | Matches Vietnamese and Indonesian procurement patterns demanding transparent lifecycle cost structures. |
| ASEAN Manufacturing Footprint Expansion | Positions capacity near Ho Chi Minh City and Bangkok quick-service restaurant supply chain demand. |
Research Methodology
Operator-level perspectives from tissue converting plant managers, OEM procurement teams, aftermarket service heads, and foodservice supply chain contractors anchored the qualitative base. Primary interviews combined with secondary validation from EU Machinery Directive conformity assessment databases, SAMR electromagnetic compatibility filings, and ASEAN machinery safety framework harmonization documents. Bottom-up equipment shipment tracking and top-down foodservice capacity expansion modeling provided triangulation.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, end-user concentration, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and foodservice dine-in volume recovery trajectories. Parent roll supply concentration indices and servo motor drive cost curves fed industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese scale-driven fabricators or European precision-engineering specialists would shift outcomes. Cross-checking against EU Machinery Directive certification pipeline data and ASEAN quick-service restaurant expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Pick Fill Seal Machines Market