
 Asia-Pacific Digital Printing Packaging Market | 2026-2036
Asia-Pacific Digital Printing Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Printing Packaging Market Analytics
Food and beverage is pivoting toward premium personalized packaging, while pharmaceuticals and consumer electronics are gaining share as regulated serialization and unboxing experiences reshape procurement priorities. HP Inc leverages its inkjet technology leadership to anchor high-volume corrugated operations across East Asia. Canon Inc competes through sustained R&D intensity in UV-curable ink systems for flexible substrates. Mondi Plc specializes in fiber-based barrier materials that integrate with digital print lines for food-grade applications.
Asia-Pacific digital printing packaging encompasses the application of variable-data print technologies—inkjet, laser, electrophotography, and digital flexography—to primary and secondary packaging substrates at resolutions typically exceeding 600 dpi, enabling lot sizes as small as a single unit without plate changes. Its primary purpose is to collapse lead times between design iteration and shelf presence while embedding traceability codes directly during the print pass. Labels and flexible packaging capture the deepest margin pools, as pharmaceutical serialization and snack-food personalization command premium pricing for short-run jobs. Folding cartons are maturing in Japan and South Korea, where established offset infrastructure creates competitive tension with digital alternatives. Corrugated boxes represent the fastest-growing technology insertion point, driven by e-commerce unboxing requirements and regional logistics expansion.
China's MEE enforces plastic reduction timelines that reshape substrate selection, while India's CDSCO mandates track-and-trace codes on pharmaceutical exports that digital print lines natively accommodate. Japan's METI promotes smart packaging standards that integrate printed sensors with QR-linked consumer interfaces, creating compliance-driven technology pull. Stakeholders must monitor how BIS certification requirements for food-contact materials in India and evolving ASEAN harmonization on packaging recyclability reshape equipment investment cycles and ink chemistry roadmaps.
Market Dynamics
China's MEE plastic reduction timelines are forcing substrate diversification across corrugated and flexible packaging lines, collapsing traditional plate-making lead times while pulling inkjet investment toward fiber-based barrier materials.
Growth Catalysts
- India's CDSCO serialization mandate:Pharmaceutical exporters must embed track-and-trace codes on every secondary pack, favoring digital print lines that integrate variable data without plate changes.
- Snack-food personalization:Fragmented consumer preferences in Japan and South Korea are pulling short-run flexible packaging jobs onto inkjet systems for limited-edition seasonal releases.
- Japan's METI smart packaging standards:Printed sensors with QR-linked interfaces create compliance-driven demand for digital presses capable of conductive ink deposition.
Market Restraints
- UV-curable ink cost volatility:Photoinitiator supply concentrates in German and Chinese chemical clusters, exposing converters to input price swings that compress job-level margins.
- Legacy offset infrastructure lock-in:Japan and South Korea maintain depreciated sheet-fed capacity that undercuts digital per-unit economics on runs above five thousand impressions.
- Water-based ink performance gaps:Food-grade barrier requirements for retort pouches exceed current aqueous ink adhesion limits, restricting digital penetration in high-temperature sterilization applications.
Strategic Opportunities
- Vietnam's underpenetrated pharmaceutical corridor:Export-oriented generic drug manufacturing is scaling serialization capacity ahead of EU FMD-equivalent requirements, creating first-mover equipment slots.
- E-commerce unboxing experience:Corrugated converters serving Alibaba and Shopee logistics networks are retrofitting post-print inkjet stations for variable graphics and regional language customization.
- Indonesia's BIS food-contact certification pipeline:Accelerated approval timelines for digitally printed fiber-based materials open shelf-ready packaging substitution away from multi-layer plastics.
Industry Challenges
- Color management skill scarcity:ICC profile optimization for expanded-gamut ink sets requires operators trained in spectrophotometric calibration, a function thinly distributed across Southeast Asian converter workforces.
- Legacy MIS integration friction:ERP systems designed for offset job ticketing lack native APIs for digital press job streaming, forcing middleware development that delays ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Printing Packaging Market |
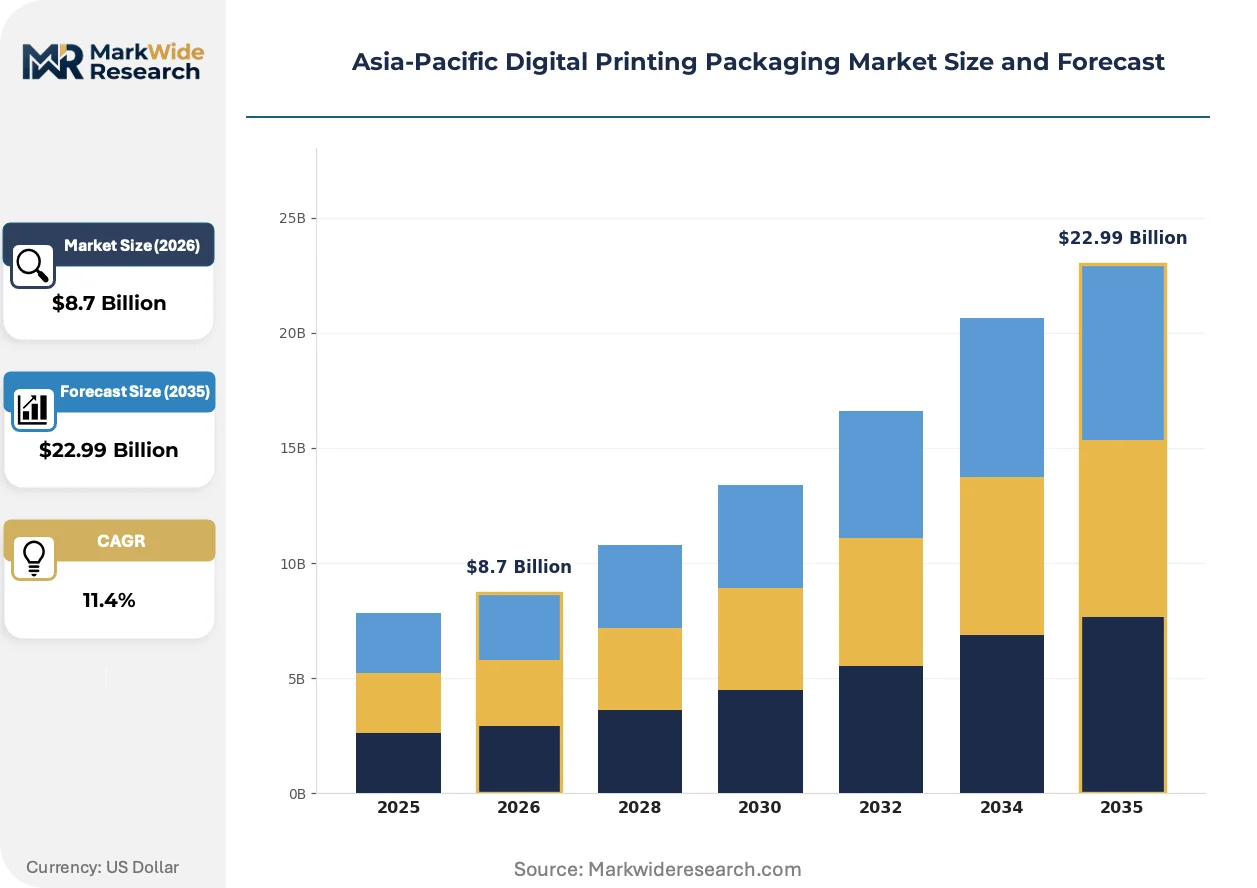
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Corrugated Boxes, Folding Cartons Technology: Inkjet, Laser, Digital Flexography, Electrophotography End User: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Electronics Material: Paper, Plastic, Metal, Composite Materials |
| Companies Covered | HP Inc, DS Smith Plc, Canon Inc, Ricoh Company Ltd, Quad/Graphics Inc, Mondi Plc, Xerox Holdings Corp, Xeikon BV, Amcor plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Printing Packaging Market Evolving Landscape
Digital print technology is compressing design-to-shelf cycles while regulatory mandates embed traceability deeper into primary packaging. Three forces are restructuring competitive capability requirements across the region.
Inkjet printbar architecture is modularizing around single-pass arrays that swap aqueous, UV, and hybrid ink modules within identical chassis footprints. Japanese corrugated converters serving beverage export markets are adopting these reconfigurable lines to alternate between water-based food-grade jobs and UV-enhanced shelf-appeal graphics. This modularity is collapsing capital risk for mid-volume converters who previously committed to single-ink chemistries.
China's MEE enforcement of plastic waste reduction timelines is accelerating substrate substitution toward molded fiber and paper-based barrier materials. Domestic converters in Zhejiang and Guangdong provinces are retrofitting existing digital lines with plasma surface treatment stations to achieve food-grade adhesion on these lower-energy substrates. Pharmaceutical blister packs and chilled ready-meal trays represent the most affected categories, with export-oriented manufacturers front-running compliance to maintain EU market access.
Brand procurement patterns are fragmenting toward micro-lot contracts that specify single-SKU minimums with 48-hour turnaround windows. Indonesian and Thai snack-food distributors are bypassing traditional broker networks to contract directly with digital converters for TikTok-commerce seasonal campaigns. This disintermediation is most visible in Jakarta's Cikarang industrial zone, where dedicated short-run facilities now cluster within same-day delivery radius of e-commerce fulfillment centers.
Asia-Pacific Digital Printing Packaging Market Segmentation
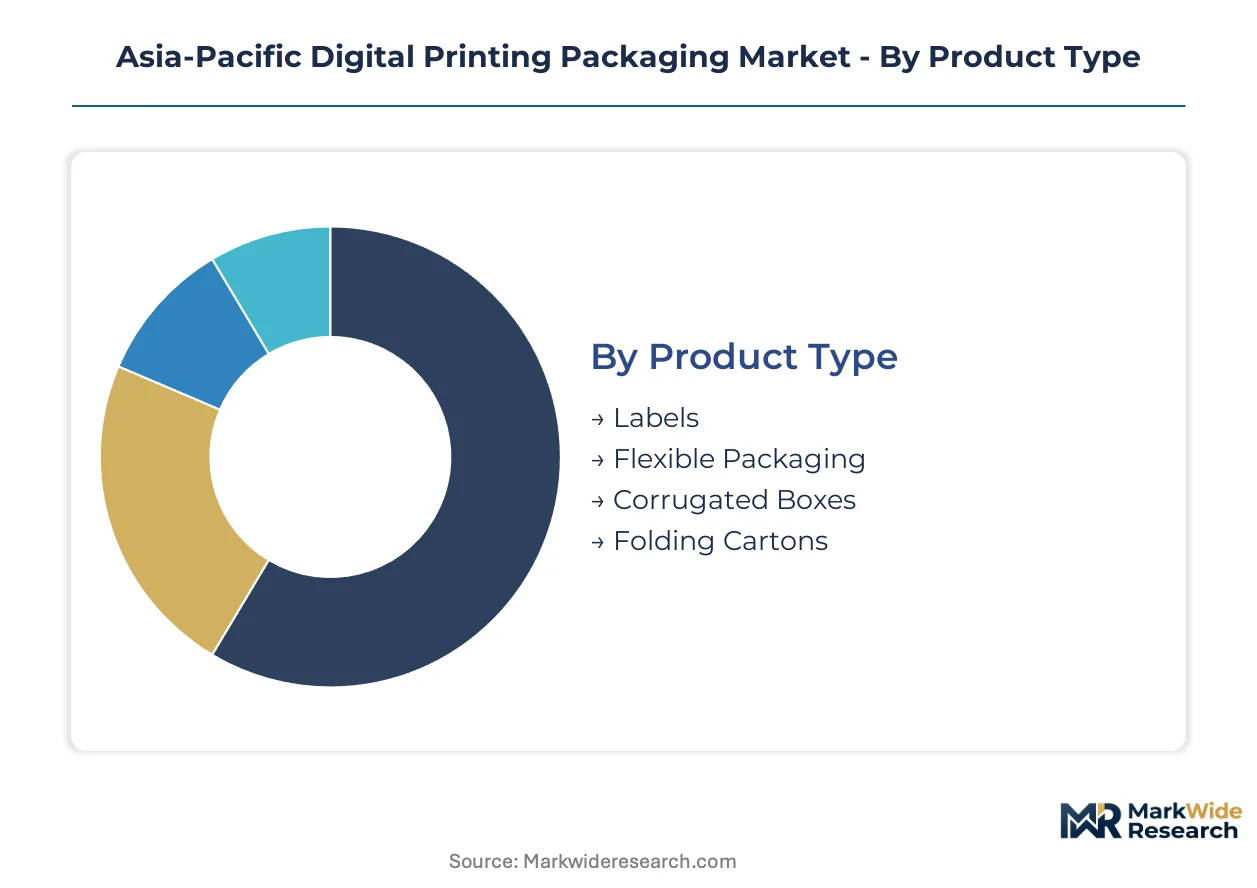
Segmentation in Asia-Pacific digital printing packaging reveals how regulatory certification burdens and substrate compatibility requirements concentrate margin pools. Each dimension carries distinct approval pathways that reshape equipment investment and ink chemistry roadmaps across the region.
Product Type:
Certification requirements vary sharply across product categories, with pharmaceutical labels demanding CDSCO serialization compliance while food-contact flexible packaging requires BIS approval cycles in India and FSSAI clearance timelines.
- Labels:Pressure-sensitive and shrink-sleeve formats dominate pharmaceutical serialization mandates. India's export corridor concentrates demand where track-and-trace codes must survive tropical humidity exposure during ocean freight to African and Latin American markets.
- Flexible Packaging:Stand-up pouches and flow wraps for snack foods command premium short-run economics. Japanese and South Korean seasonal campaigns pull inkjet investment toward expanded-gamut systems capable of brand-color matching across 500-unit minimums.
- Corrugated Boxes:Post-print inkjet stations retrofit existing box lines for e-commerce variable graphics. Alibaba and Shopee fulfillment networks in China and Southeast Asia drive regional language customization at carton scale.
- Folding Cartons:Pharmaceutical leaflets and cosmetic rigid boxes compete with depreciated offset capacity in Japan and South Korea. Digital penetration remains constrained by sheet-fed economics above five thousand impressions.
Leading the category by volume: Labels. Growing fastest: Flexible packaging.
Technology:
Cost tiers separate entry-level electrophotography from capital-intensive single-pass inkjet, with laser systems occupying a narrow niche for security applications.
- Inkjet:Single-pass arrays with modular aqueous/UV/hybrid ink stations anchor mid-volume corrugated operations. Japanese beverage exporters in Shizuoka and Aichi prefectures adopt reconfigurable lines to alternate food-grade and shelf-appeal jobs without chassis replacement.
- Laser:Ablation and marking systems serve anti-counterfeiting serialization where tamper-evident destruction is mandatory. South Korean pharmaceutical exporters deploy fiber laser stations for permanent code embedding on blister foil.
- Digital Flexography:Hybrid workflows combine flexo base coats with digital variable-data overprinting. Thai snack-food converters in Pathum Thani leverage this architecture for metallic backgrounds with personalized promotional codes.
- Electrophotography:Toner-based systems dominate entry-level label production below 300mm web widths. Indonesian SME converters in Surabaya favor this technology for pharmaceutical leaflet compliance before scaling to inkjet.
Volume leadership sits with inkjet technology. Steepest expansion trajectory: Digital flexography hybrid systems.
End User:
Application requirements fragment procurement patterns, with regulated industries demanding audit trails that commodity sectors ignore.
- Food & Beverage:Premium personalization and seasonal versioning dominate procurement. Japanese confectionery brands commission 48-hour turnaround campaigns for convenience store exclusives, bypassing traditional broker networks.
- Pharmaceuticals:CDSCO serialization mandates and EU FMD-equivalent preparations concentrate investment in India and Vietnam. Export-oriented generic manufacturers in Hyderabad and Ahmedabad retrofit lines for aggregated shipment reporting.
- Personal Care:Cosmetic sampling and travel-size versioning drive short-run folding carton demand. South Korean K-beauty brands deploy micro-lot contracts for influencer collaboration packaging.
- Consumer Electronics:Unboxing experience specifications pull corrugated investment toward variable graphics and regional warranty inserts. China's Xiaomi and Oppo supply chains specify Mandarin-English-Hindi trilingual cartons for India-bound shipments.
Pharmaceuticals lead by margin per square meter. Food and beverage expands most quickly by job count.
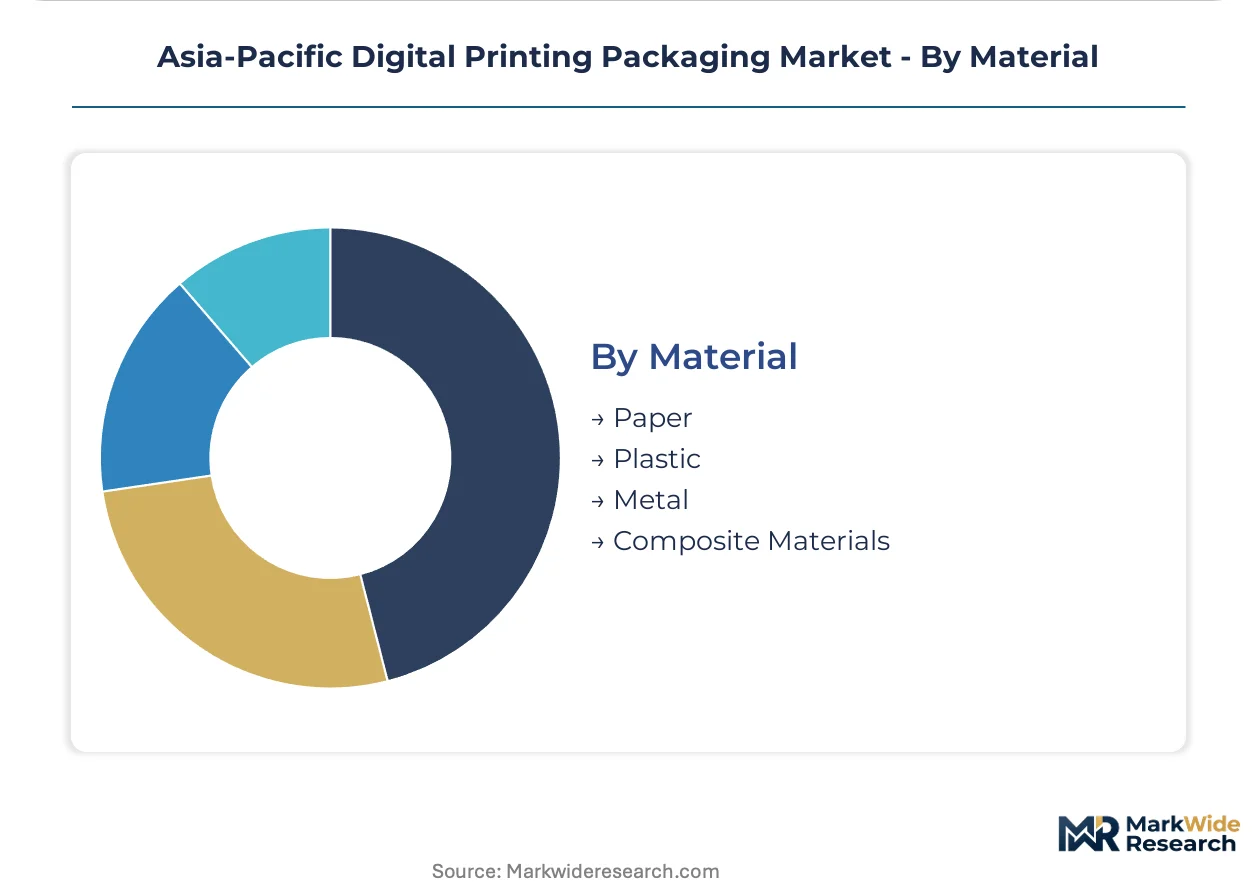
Material:
Substrate selection tracks MEE plastic reduction enforcement and BIS fiber-based certification pipeline acceleration.
- Paper:Molded fiber and kraft-based barrier materials gain share as China's MEE timelines force substitution. Zhejiang converters deploy plasma surface treatment to achieve food-grade ink adhesion on lower-energy substrates.
- Plastic:Multi-layer films and shrink sleeves retain pharmaceutical and personal care share where moisture barrier performance is non-negotiable. Retort pouch applications remain digitally constrained by aqueous ink adhesion limits under high-temperature sterilization.
- Metal:Aluminum blister foil and aerosol cans serve pharmaceutical and cosmetic applications requiring absolute light and oxygen barrier. Laser marking dominates this substrate where mechanical durability exceeds print durability requirements.
- Composite Materials:Fiber-plastic hybrid structures for chilled ready-meal trays front-run EU market access compliance. Export-oriented Chinese manufacturers in Guangdong pilot these substrates to maintain shelf presence under evolving EPR schemes.
Paper substrates dominate by tonnage throughput. Composite materials climb fastest as compliance-driven substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang's Qiantang New Area and Vietnam's VSIP industrial parks concentrate digital press installations through tax-abated equipment import schemes. These zones anchor regional capacity expansion as converters chase pharmaceutical serialization contracts and e-commerce fulfillment mandates.
China
MEE plastic reduction timelines force substrate substitution toward molded fiber and kraft-based barriers. Zhejiang and Guangdong converters retrofit digital lines with plasma surface treatment to achieve food-grade adhesion on lower-energy substrates. Export-oriented manufacturers in these provinces front-run compliance to maintain EU market access for chilled ready-meal packaging.
India
CDSCO serialization mandates and EU FMD-equivalent preparations concentrate investment in Hyderabad and Ahmedabad. Generic drug exporters retrofit lines for aggregated shipment reporting with track-and-trace codes surviving tropical humidity during ocean freight. The pharmaceutical packaging corridor anchors regional digital press deployment.
Japan
METI smart packaging standards pull demand for presses capable of conductive ink deposition and printed sensor integration. Shizuoka and Aichi beverage exporters adopt reconfigurable single-pass arrays to alternate food-grade and shelf-appeal jobs. Seasonal confectionery campaigns commission 48-hour turnaround for convenience store exclusives.
South Korea
K-beauty brands deploy micro-lot contracts for influencer collaboration packaging, driving short-run folding carton demand. Depreciated offset capacity in Seoul and Busan undercuts digital economics above five thousand impressions. Fiber laser stations serve pharmaceutical exporters for permanent code embedding on blister foil.
Vietnam
Export-oriented generic drug manufacturing scales serialization capacity ahead of EU-equivalent requirements. VSIP industrial zones near Ho Chi Minh City attract first-mover equipment slots as pharmaceutical converters front-run compliance deadlines. E-commerce logistics networks drive corrugated retrofitting for regional language customization.
Asia-Pacific Digital Printing Packaging Market Competitive Landscape
Top-tier vendors anchor high-volume corrugated and pharmaceutical serialization contracts, while mid-tier specialists occupy flexible packaging and label niches. The vendor base stratifies across inkjet hardware manufacturers, integrated packaging converters, and substrate specialists with digital line integration capabilities. Three archetypes dominate: technology licensors with modular printbar platforms, fiber-based material suppliers retrofitting barrier coatings, and hybrid workflow integrators combining flexo base units with digital overprinting. Competitive moves concentrate on strategic partnerships between equipment OEMs and substrate developers, plus capacity expansion into underpenetrated pharmaceutical corridors.
Among technology licensors, HP Inc and Canon Inc exemplify divergent platform strategies—HP anchors high-volume corrugated operations through aqueous inkjet leadership, while Canon occupies UV-curable specialization for flexible substrates. Ricoh Company Ltd sits within the mid-tier electrophotography segment serving entry-level label compliance. These three represent the competitive spectrum from premium single-pass arrays to toner-based serialization systems.
| Leading Market Players |
|---|
| HP Inc |
| DS Smith Plc |
| Canon Inc |
| Ricoh Company Ltd |
| Quad/Graphics Inc |
| Mondi Plc |
| Xerox Holdings Corp |
| Xeikon BV |
| Amcor plc |
| Others |
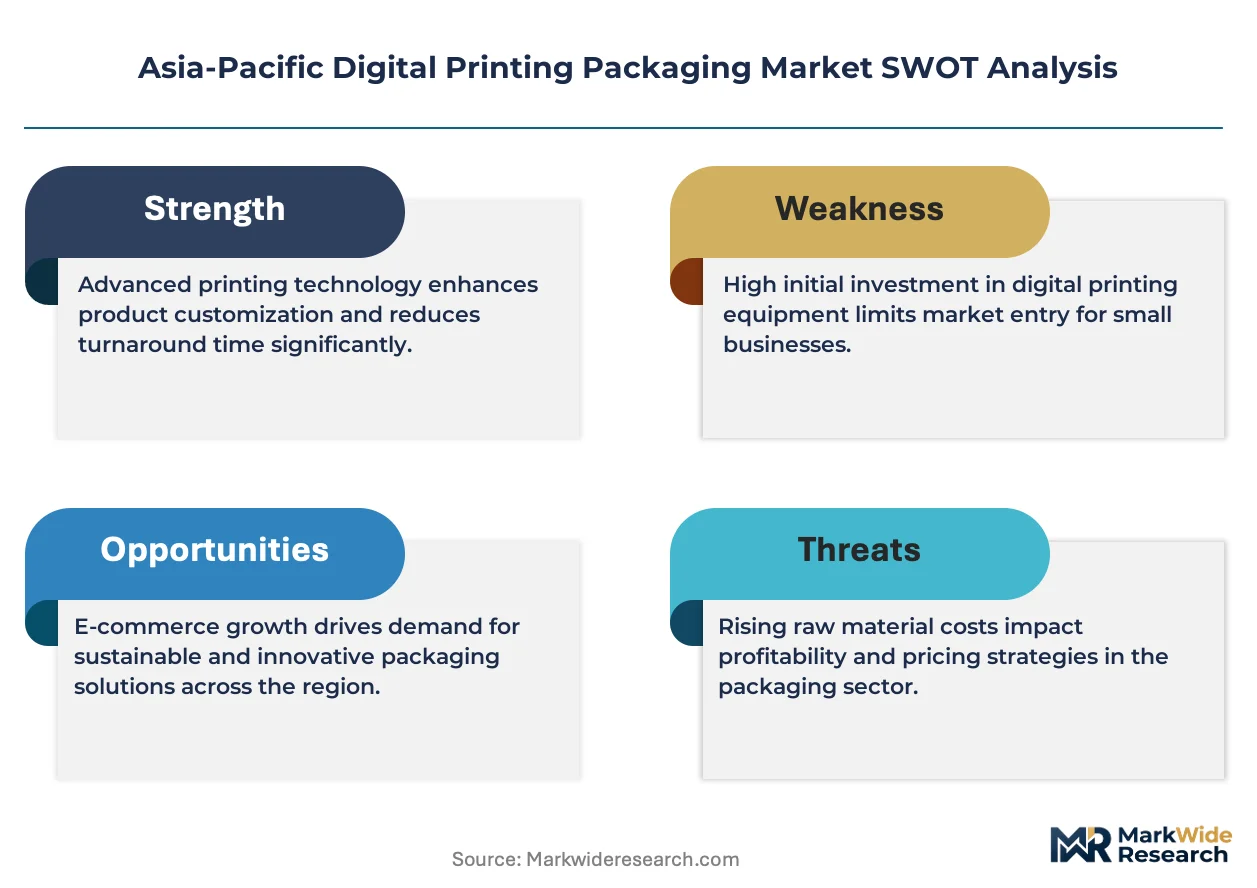
Value Network & Pricing Analysis
ICC profile optimization specialists concentrated in Japan and South Korea command wage premiums that widen spreads between premium-tier serialization contracts and economy-grade label jobs across Southeast Asian converter networks.
Pricing Analysis
Lead-time compression commands premium pricing tiers, with 48-hour turnaround specifications for pharmaceutical serialization contracts in India and Vietnam carrying 40-60 percent markups over standard two-week offset plate cycles. Three-tier pricing structure across premium certification-grade, standard compliance-tier, and economy spot-inventory levels separates CDSCO-validated lines from uncertified converters in Surabaya and Jakarta. Cost compression in economy-tier electrophotography is intensifying because Indonesian SME converters are absorbing photoinitiator volatility to maintain share. Pharmaceutical exporters exhibit lowest price sensitivity due to regulatory non-negotiability, while snack-food distributors in Thailand show highest elasticity, switching converters on single-digit percentage differentials.
Supply Chain Analysis
Dual-sourcing mandates from HP Inc and Canon Inc equipment buyers require qualified secondary suppliers for printbar modules and UV-curable ink stations, preventing single-source lock-in across Zhejiang and Guangdong installation bases. Manufacturing concentrates in China, Japan, and Germany for inkjet hardware; photoinitiator chemicals draw from Chinese and German chemical clusters; fiber-based barrier substrates rest on Nordic and Southeast Asian pulp supply. Distribution runs through converter-direct relationships with pharmaceutical exporters and e-commerce fulfillment networks, bypassing traditional broker layers. Tariff exposure on German photoinitiator imports threatens margin stability for UV-curable dependent operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified spectrophotometric calibration technicians represent the binding capacity constraint, propping pricing power for certified converters in Japan and South Korea while uncertified competitors in Indonesia and Vietnam absorb margin compression.
For Market Incumbents: Lock in backward integration into photoinitiator buffer stockpiling and captive ICC profile training academies to defend against emerging Chinese equipment OEMs offering subsidized hardware with bundled ink supply. Prioritize CDSCO and BIS certification maintenance in Hyderabad and Ahmedabad corridors where regulatory expiration threats concentration.
For New Entrants and Emerging Players: Capture Vietnam's underpenetrated pharmaceutical serialization corridor ahead of EU FMD-equivalent deadline clustering, leveraging VSIP tax abatements for first-mover equipment slots. Lead with digital flexography hybrid workflows for Thai snack-food metallic-background jobs where incumbent inkjet saturation leaves white space.
For Investors and Strategic Acquirers: Re-rating potential sits with fiber-based barrier material specialists given China's MEE enforcement acceleration and EU EPR scheme alignment, as substrate substitution outpaces equipment OEM margin recovery. Monitor BIS approval velocity for molded-fiber chilled ready-meal trays as inflection signal for Guangdong export-oriented manufacturer valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Printbar Platform Deployment | Japanese beverage exporters in Shizuoka reduce chassis replacement capital by 60 percent through reconfigurable aqueous-UV swap stations. |
| Plasma Surface Treatment Retrofit | Zhejiang converters achieve food-grade adhesion on molded fiber substrates ahead of MEE compliance deadlines. |
| CDSCO Serialization Line Upgrade | Hyderabad generic drug exporters secure aggregated shipment reporting capabilities for African and Latin American ocean freight. |
| Conductive Ink Deposition Capability | Japanese converters capture METI smart packaging standards compliance for printed sensor integration with QR-linked interfaces. |
| Direct-to-E-Commerce Converter Model | Jakarta Cikarang facilities within same-day delivery radius of TikTok-commerce fulfillment centers bypass traditional broker networks. |
Research Methodology
Multi-period observation of digital press installation rates, ink chemistry patent filings, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with converter operations directors, pharmaceutical packaging procurement managers, OEM equipment sales engineers, and BIS certification auditors. Secondary validation drew from China MEE enforcement notices, India CDSCO serialization advisories, Japan METI smart packaging standards documentation, and ASEAN harmonization drafts on packaging recyclability. Bottom-up equipment shipment aggregation and top-down end-use demand modeling were triangulated against trade flow data.
Input-output matrices mapped technology adoption curves against substrate substitution elasticities and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions modeled include product type, print technology, end-use industry, material substrate, and country-level regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and forward-looking capacity expansion announcements. Forecast inputs incorporated MEE plastic reduction timeline phasing and CDSCO serialization mandate rollout sequencing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photoinitiator supply concentration, ICC technician training pipeline expansion, and ASEAN regulatory harmonization velocity. Deviation in China's dual carbon goal acceleration or EU EPR scheme enforcement tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Label Printing Software Market