
 United Arab Emirates Flexible Plastic Packaging Market | 2026-2036
United Arab Emirates Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Flexible Plastic Packaging Market Insights
Food-grade barrier specifications are rotating toward higher oxygen and moisture resistance as Emirates-based processors extend shelf-life requirements for export-oriented goods. ENPI Group leverages integrated film extrusion and printing capabilities to serve regional dairy and meat clients. Hotpack Packaging LLC anchors the foodservice disposables segment with extensive Gulf distribution reach. Amber Packaging Industries LLC differentiates through specialized pharmaceutical-grade cleanroom pouch production.
Flexible plastic packaging comprises polymer-based materials manufactured through blown film extrusion, cast film, or lamination processes, engineered to provide barrier protection, seal integrity, and printability for consumer and industrial goods. Polyethylene formulations dominate volume throughput due to cost efficiency in bag and wrap applications, while multilayer polyester-polypropylene laminates command premium positioning in retort pouch and pharmaceutical strip formats. Pouch configurations represent the fastest-growing packaging type as brand owners replace rigid containers with lightweight, shelf-ready alternatives across beverage and condiment lines.
MOHAP pharmaceutical packaging standards and Emirates Authority for Standardization and Metrology (ESMA) food-contact material regulations govern product approval pathways and testing protocols for local manufacturers. The UAE's Ministry of Climate Change and Environment extended producer responsibility guidelines are reshaping material selection criteria, pushing converters toward mono-material recyclable structures and post-consumer recycled content verification. Stakeholders must evaluate compliance-ready substrate portfolios against evolving federal sustainability mandates and import substitution incentives.
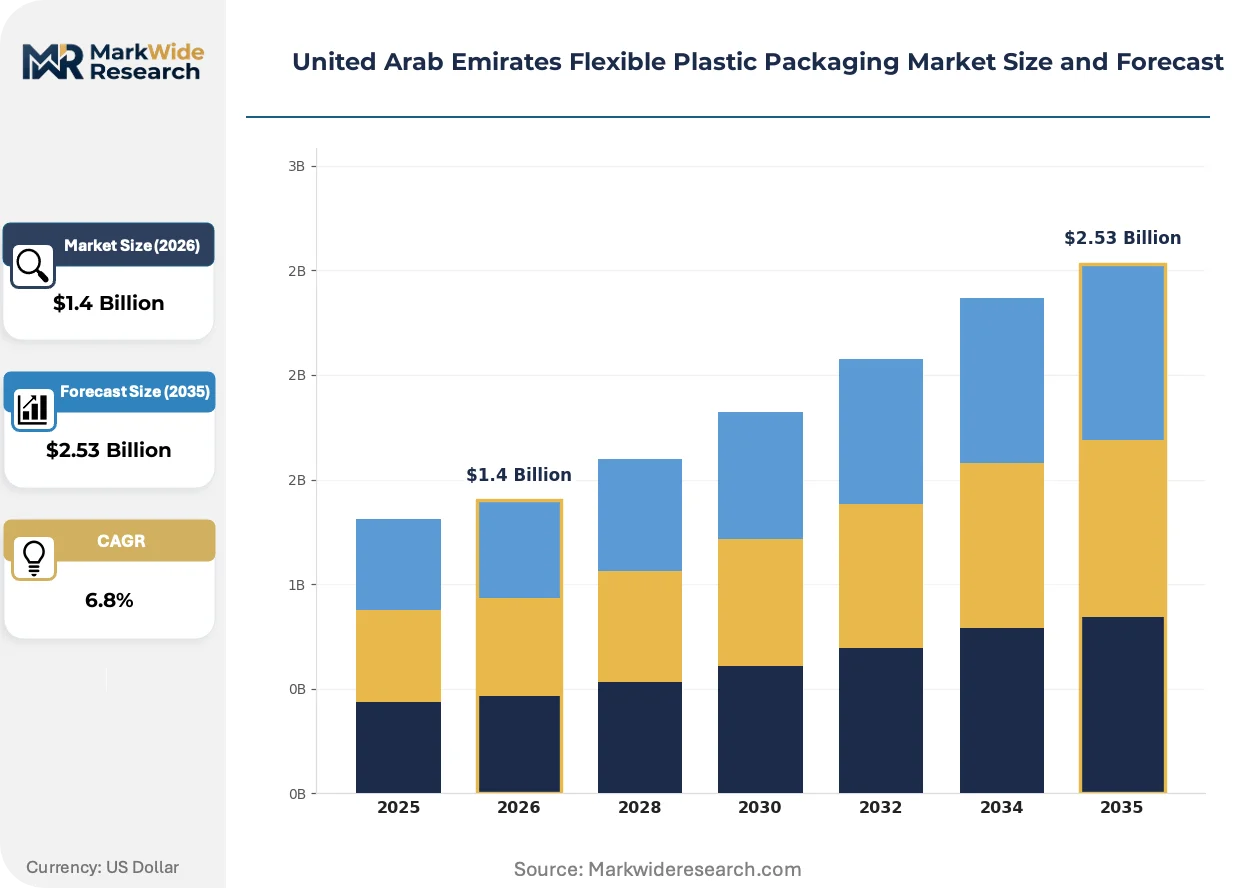
Market Dynamics
MOHAP pharmaceutical packaging standards and ESMA food-contact material regulations are forcing converters to redesign substrate portfolios around compliance-ready mono-material structures, while Dubai's industrial packaging cluster concentrates investment in high-barrier pouch extrusion capabilities.
Growth Catalysts
- Extended Producer Responsibility Frameworks:The UAE Ministry of Climate Change and Environment guidelines redirect capital toward recyclable multilayer structures, creating procurement pull from brand owners seeking verified post-consumer recycled content pathways.
- Food Export Shelf-Life Extension:Emirates-based meat and dairy processors are specifying oxygen transmission rates below 1 cc/m²/day, driving demand for ethylene vinyl alcohol coextruded films in vacuum pouch formats.
- Hot-Fill Pouch Adoption:Beverage and condiment lines across Abu Dhabi's food processing corridor are replacing rigid glass and metal containers with retort-capable stand-up pouches, compressing logistics costs and retail shelf footprint.
Market Restraints
- Polymer Feedstock Volatility:Linear low-density polyethylene and polypropylene resin prices fluctuate with naphtha-cracker margins in the Gulf Cooperation Council, squeezing converter margins on fixed-price annual supply contracts.
- Multilayer Recycling Infrastructure Gap:The absence of industrial-scale delamination capacity for aluminum-oxide-coated polyester-polyethylene laminates limits circular economy claims and exposes producers to greenwashing liability.
- Import Substitution Pressures:Domestic converters face price competition from Saudi Arabian and Indian film exporters benefiting from lower energy input costs and scale economies in blown extrusion.
Strategic Opportunities
- Pharmaceutical Blister Foil Localization:Cleanroom-grade cold-form aluminum and polyvinyl chloride laminates for tablet packaging remain import-dependent, creating white space for domestic investment with MOHAP certification capabilities.
- Digital Printing Convergence:Integration of electron beam curing with flexographic lines enables economic short-run customization for regional FMCG brands, collapsing minimum order quantities and inventory risk.
- Ajman and Ras Al Khaimah Industrial Zones:Underdeveloped converter presence in these emirates offers land and utility cost advantages versus Dubai and Abu Dhabi for mid-cap entrants targeting Gulf distribution.
Industry Challenges
- Barrier Film Formulation Expertise Scarcity:Local polymer science and coextrusion die design talent pools remain shallow, forcing reliance on European and Asian technical service partnerships for high-performance multilayer development.
- ESMA Certification Timelines:Migration testing and food-contact notification approvals average 14-18 months, delaying product launches and freezing working capital in pre-certified inventory positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Flexible Plastic Packaging Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester End User: Food, Beverage, Healthcare, Consumer Goods Packaging Type: Bags, Pouches, Films, Wraps Thickness: Thin, Medium, Heavy, Extra Heavy |
| Companies Covered | ENPI Group, Huhtamaki Oyj, Amber Packaging Industries LLC, Hotpack Packaging LLC, Radiant Packaging Industry LLC, Integrated Plastics Packaging, Arabian Flexible Packaging LLC, Falcon Pack, Swiss Pac UAE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Flexible Plastic Packaging Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape competitive positioning around circularity credentials and barrier performance, with digital workflow integration compressing new product development cycles.
Mono-material polyethylene pouches with plasma-enhanced chemical vapor deposition barrier coatings are supplanting conventional metallized polyester laminates in snack and dry goods applications. Regional dairy brands are specifying these structures for 12-month shelf-life requirements. The shift collapses delamination complexity and aligns with Emirates Authority for Standardization and Metrology recyclability labeling protocols.
MOHAP's 2023 update to pharmaceutical packaging guidelines mandates child-resistant and senior-friendly closure systems for over-the-counter blister packs. Converters are retrofitting thermoforming lines with push-through-foil and peel-push lidding configurations. The compliance burden falls heaviest on imported generic drug distributors lacking local technical adaptation partnerships.
Brand owners in the UAE's food processing corridor are consolidating supplier relationships around full-service converters offering in-house gravure printing and pouch-making. Single-source accountability replaces fragmented film-print-convert procurement chains. The concentration is most pronounced among export-oriented condiment and sauce producers seeking synchronized color management across Middle East and African markets.
United Arab Emirates Flexible Plastic Packaging Market Segmentation
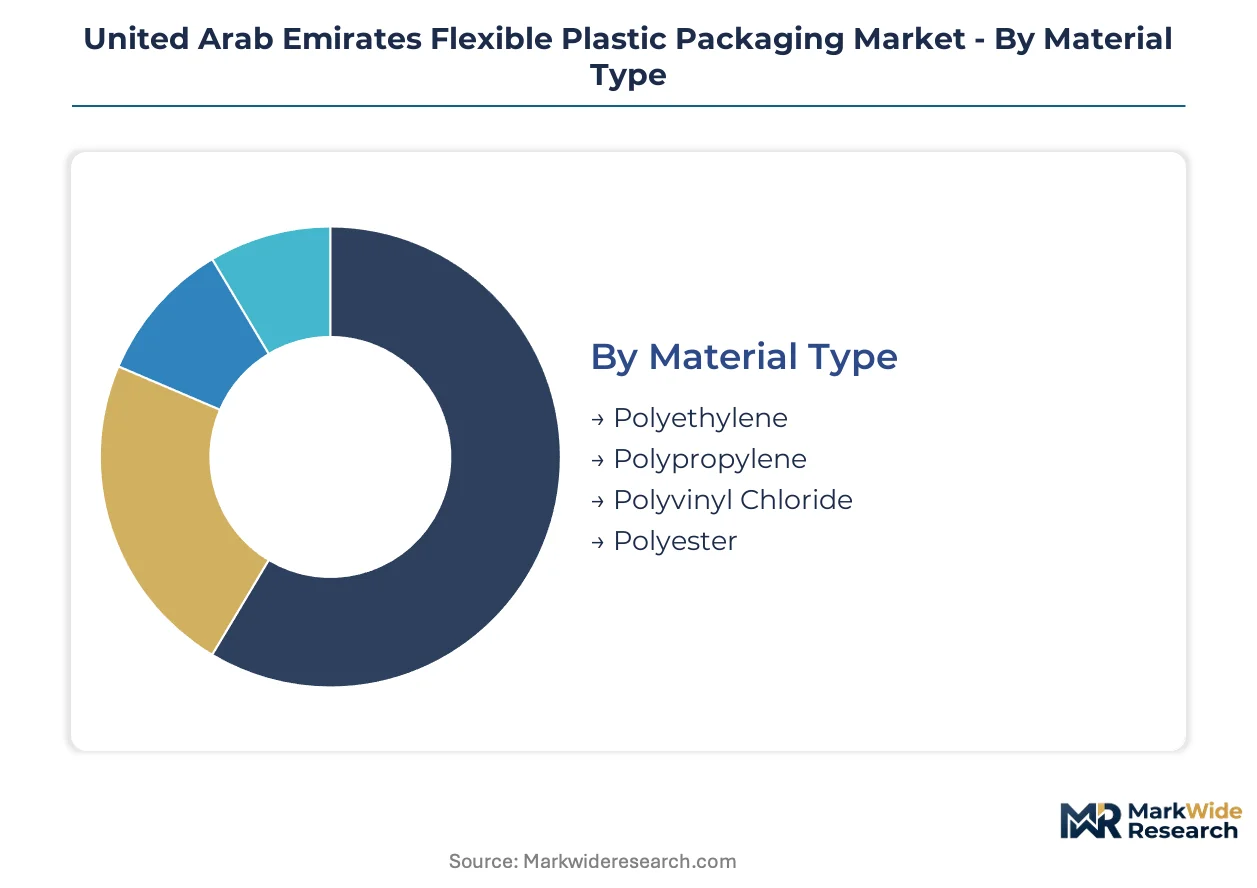
Segmentation in the UAE flexible plastic packaging market reveals distinct procurement patterns across Dubai's industrial cluster and Abu Dhabi's food corridor. Material selection and packaging format preferences diver sharply between export-oriented processors and domestic retail distributors.
Material Type:
Polyethylene formulations dominate commodity bag and wrap applications through Dubai's trading houses, while specialty laminates serve pharmaceutical and high-barrier food channels requiring MOHAP or ESMA certification pathways.
- Polyethylene:Linear low-density and high-density variants constitute the volume backbone for carrier bags, shrink wrap, and industrial liners. Dubai-based converters source these resins through Gulf Cooperation Council naphtha crackers, with procurement concentrated among foodservice disposables suppliers serving the broader GCC retail sector.
- Polypropylene:Cast and oriented films deliver clarity and stiffness for snack laminates and pharmaceutical blister lidding. Abu Dhabi's condiment processors specify biaxially oriented polypropylene for retort pouch applications where dimensional stability under thermal processing is critical.
- Polyvinyl Chloride:Rigid and flexible calendered grades serve pharmaceutical blister packs and medical device overwrap with established migration testing protocols under MOHAP oversight.
- Polyester:Metallized and coated polyethylene terephthalate films provide oxygen barrier layers in multilayer laminates for meat and dairy export applications.
By volume, Polyethylene leads. By growth pace, Polypropylene is ahead.
End User:
Customer procurement sophistication varies across maturity tiers, with export-facing segments demanding technical documentation and compliance verification that domestic retail channels often bypass.
- Food:Meat, dairy, and condiment processors in Abu Dhabi's food corridor specify high-barrier vacuum pouches with oxygen transmission rates below 1 cc/m²/day. Extended shelf-life requirements for African and Asian export markets drive ethylene vinyl alcohol coextrusion demand.
- Beverage:Hot-fill and aseptic pouch adoption is displacing rigid containers across juice and dairy drink lines. Logistics cost compression and retail shelf footprint reduction motivate brand owners to consolidate around stand-up pouch formats.
- Healthcare:Pharmaceutical manufacturers require MOHAP-certified cleanroom production for blister foil, cold-form laminates, and sterile barrier systems. Child-resistant and senior-friendly closure mandates are reshaping lidding specifications.
- Consumer Goods:Personal care and household product brands prioritize print quality and shelf impact over barrier performance, sourcing through Dubai's gravure printing cluster.
Food commands the largest revenue pool. Beverage is climbing the fastest.
Packaging Type:
Format selection tracks handling automation and retail display requirements, with pouch configurations gaining preference where supply chain labor costs favor lightweight alternatives.
- Bags:Side-seal and bottom-gusseted configurations serve bulk industrial and retail commodity applications. Woven polypropylene sacks dominate construction and agricultural supply chains.
- Pouches:Stand-up and flat formats with spout fitments are displacing rigid bottles across condiment, sauce, and beverage categories. Spouted pouch adoption is accelerating in children's nutrition segments.
- Films:Stretch and shrink films secure palletized loads for export logistics. Five-layer coextrusion lines in Dubai's industrial zone produce high-performance collation shrink for beverage multipacks.
- Wraps:Cling film and aluminum foil laminates serve fresh produce and foodservice wrapping with specification divergence between supermarket retail and hospitality procurement channels.
Bags retain volume leadership. Pouches show the steepest expansion trajectory.
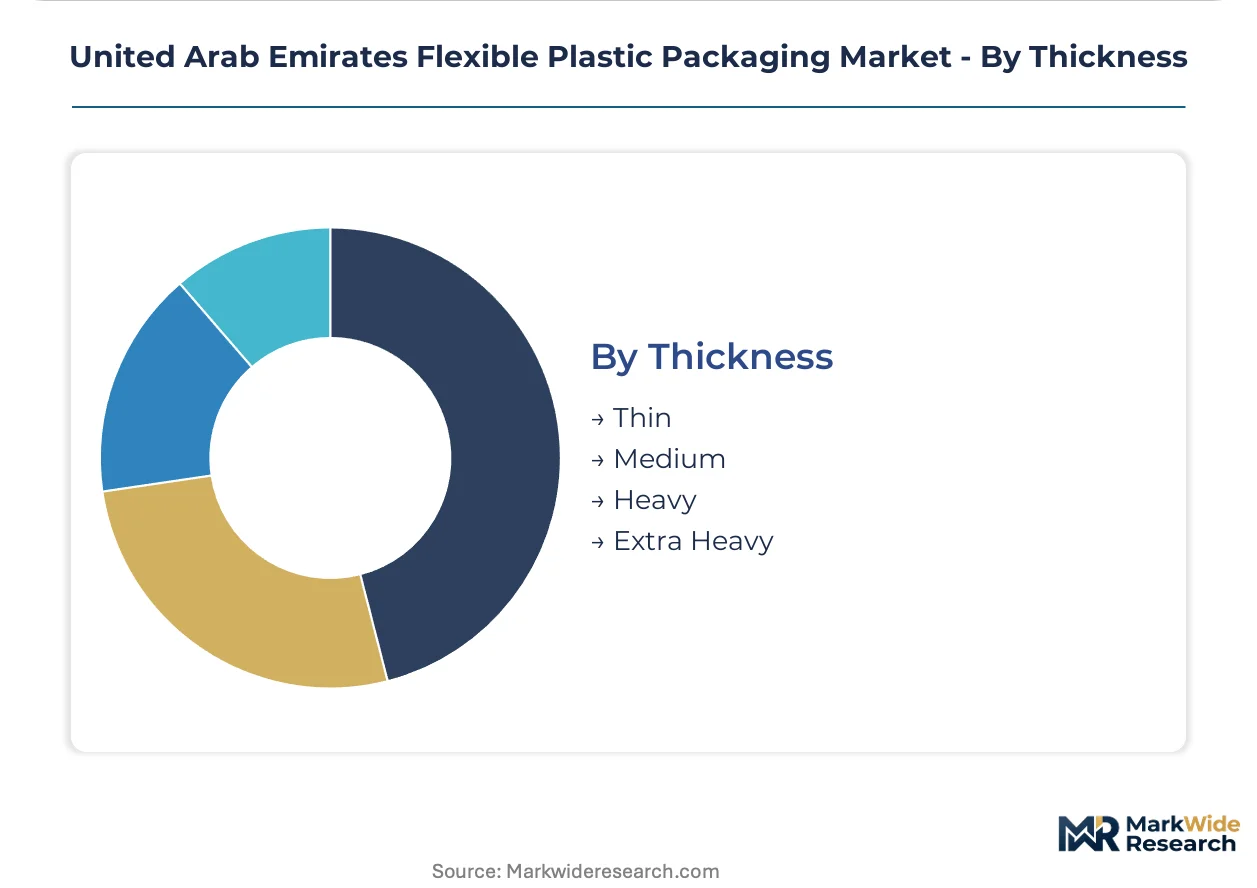
Thickness:
Gauge selection reflects the tension between material cost minimization and mechanical performance requirements, with regulatory pressure on single-use plastics pushing brand owners toward downgauging where barrier permits.
- Thin:Below 25 micron films serve overwrap and lightweight carrier bag applications. Downgauging initiatives face mechanical property constraints in automated handling environments.
- Medium:25-75 micron range balances cost and performance for standard pouch and bag applications across food and consumer goods segments.
- Heavy:75-150 micron structures provide puncture resistance for bone-in meat and industrial chemical packaging. Vacuum pouch specifications cluster in this tier.
- Extra Heavy:Above 150 micron gauges serve bulk flexible intermediate bulk containers and specialized chemical resistance applications with limited domestic production capability.
Medium thickness captures the largest unit volume. Thin gauges are gaining share fastest amid sustainability-driven lightweighting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's flexible plastic packaging trade balance tilts toward import dependency for specialty barrier films, while domestic converters capture commodity segments serving Gulf export markets. Dubai and Abu Dhabi industrial clusters anchor production capacity, with Northern Emirates emerging as cost-competitive expansion zones.
Dubai
Dubai's Jebel Ali industrial corridor concentrates blown film extrusion and gravure printing capacity for foodservice disposables and retail carrier bags. ESMA food-contact certification requirements filter supplier access for European export-oriented brands. The Dubai Industrial City cluster houses integrated converters serving GCC retail distribution networks with polyethylene-based pouch and wrap formats.
Abu Dhabi
Abu Dhabi's food processing corridor drives high-barrier pouch demand from meat and dairy exporters targeting African and Asian markets. MOHAP pharmaceutical packaging standards mandate cleanroom production capabilities for blister foil and cold-form laminates. Khalifa Industrial Zone converters specialize in ethylene vinyl alcohol coextruded films for vacuum packaging applications.
Sharjah
Sharjah's Hamriyah Free Zone offers land and utility cost advantages for mid-cap entrants targeting Gulf distribution networks. The emirate's packaging sector serves construction and agricultural supply chains with woven polypropylene sacks and industrial liners. Local converters benefit from proximity to Dubai's logistics infrastructure without premium real estate costs.
Northern Emirates
Ajman and Ras Al Khaimah industrial zones attract investment from converters seeking lower operational costs than Dubai and Abu Dhabi. These emirates specialize in commodity-grade polyethylene bags and stretch films for regional construction and logistics sectors. Federal sustainability mandates are pushing new entrants toward mono-material recyclable structures from facility inception.
United Arab Emirates Flexible Plastic Packaging Market Competitive Landscape
Listed leaders compete with private specialists across integrated production capabilities, with publicly traded multinationals holding technology advantages in high-barrier pharmaceutical formats while family-owned converters dominate foodservice disposables. The market exhibits tiered concentration: global players anchor premium pharmaceutical and retort pouch segments, mid-cap integrated converters serve regional food brands, and commodity specialists compete on volume in carrier bags and industrial films. Two competitive moves define current dynamics: capacity expansion in Northern Emirates industrial zones to escape Dubai cost premiums, and strategic partnerships with European technical service providers to bridge local polymer science expertise gaps.
Among UAE-based private specialists, ENPI Group and Hotpack Packaging LLC exemplify divergent scale strategies within the domestic converter base. ENPI Group occupies a position in integrated film extrusion and printing for regional dairy and meat clients. Hotpack Packaging LLC anchors the foodservice disposables segment through extensive Gulf distribution infrastructure. Amber Packaging Industries LLC represents the specialized tier, focusing on pharmaceutical-grade cleanroom pouch production under MOHAP oversight. These three players collectively illustrate how domestic converters are repositioning around compliance-ready substrate portfolios and sustainability credentials.
| Leading Market Players |
|---|
| ENPI Group |
| Huhtamaki Oyj |
| Amber Packaging Industries LLC |
| Hotpack Packaging LLC |
| Radiant Packaging Industry LLC |
| Integrated Plastics Packaging |
| Arabian Flexible Packaging LLC |
| Falcon Pack |
| Swiss Pac UAE |
| Others |
Pricing and Supply Chain Analysis
Mono-material polyethylene structures displacing metallized polyester laminates are redrawing raw material procurement geography and compressing premium-mid-economy pricing differentiation across Dubai's converter base. This substitution simultaneously collapses delamination complexity and exposes commodity-grade producers to margin erosion as brand owners consolidate supplier relationships around full-service capabilities.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the UAE flexible packaging market. Price differentiation rests on ESMA certification grade and volume scale, with MOHAP-certified pharmaceutical formats commanding substantial premiums over food-grade commodity films. Pricing pressure stems from Saudi Arabian and Indian import competition benefiting from lower energy input costs. Domestic retail distributors exhibit highest price sensitivity, while export-oriented meat and dairy processors prioritize barrier performance over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites resin supply security for Gulf Cooperation Council naphtha crackers feeding Dubai's extrusion cluster. Raw material sourcing draws from Saudi Arabia, Qatar, and Kuwait for linear low-density polyethylene and polypropylene feedstocks. Single-source vulnerability concentrates in European ethylene vinyl alcohol resin supplies for high-barrier coextrusion. Distribution runs through Jebel Ali port infrastructure and Northern Emirates logistics corridors serving GCC retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE flexible plastic packaging market rewards converters possessing polymer science expertise and regulatory certification capabilities that remain scarce domestically. Formulation chemistry talent gaps and ESMA approval timeline bottlenecks create defensive moats for incumbents while raising entry barriers for aspirants lacking European technical partnerships.
For Market Incumbents: Secure backward integration into film extrusion capabilities to defend margin position against Saudi and Indian import pressure. Acquire MOHAP cleanroom certification capacity to capture pharmaceutical blister foil localization opportunities. Prioritize Ajman and Ras Al Khaimah capacity expansion to escape Dubai real estate premiums while maintaining GCC distribution reach. For New Entrants and Emerging Players: Differentiate on mono-material recyclable structures aligned with Ministry of Climate Change and Environment extended producer responsibility mandates. Target Northern Emirates industrial zones for land and utility cost advantages versus established Dubai-Abu Dhabi clusters. Pursue digital printing convergence partnerships with electron beam curing equipment providers to serve regional FMCG short-run customization demand. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors compliance-ready substrate portfolios over commodity volume plays. Long-term viability hinges on circular economy credential verification and post-consumer recycled content pathway development. Acquisition target archetype: mid-cap integrated converters with gravure printing and pouch-making capabilities serving export-oriented food processors. Signal to watch: ESMA acceleration of food-contact notification approval timelines as indicator of competitive access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captures margin currently lost to GCC resin traders and insulates against naphtha-cracker price volatility. |
| MOHAP Cleanroom Certification Investment | Unlocks pharmaceutical blister foil demand currently satisfied by European and Asian imports. |
| Mono-Material Recyclable Structure Development | Aligns substrate portfolios with Emirates Authority for Standardization and Metrology sustainability labeling protocols. |
| Digital Printing Capability Integration | Enables economic short-run production for regional FMCG brands collapsing minimum order quantities. |
| Northern Emirates Capacity Expansion | Accesses Ajman and Ras Al Khaimah land and utility cost advantages versus Dubai industrial zones. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with film extrusion plant managers, procurement leads at meat and dairy processors, ESMA regulatory affairs specialists, and distribution channel partners across Dubai and Abu Dhabi. Secondary validation drew from Emirates Authority for Standardization and Metrology food-contact guidelines, MOHAP pharmaceutical packaging standards, Gulf Cooperation Council customs trade data, and SEC filings of listed packaging multinationals. Bottom-up volume modeling and top-down value triangulation were cross-referenced against converter capacity announcements and resin import statistics.
Across the analysis window, forecasts were constructed through segmented modeling of material type, end-user industry, packaging format, and thickness gauge dimensions. CAGRs were derived from trend extrapolation of polyethylene and polypropylene resin price trajectories, barrier film adoption curves, and regulatory compliance cost impacts. Industry-specific inputs included ethylene vinyl alcohol coextrusion line deployment schedules and ESMA certification backlog estimates.
The analysis sits within stated boundaries; outcomes outside sustained polymer feedstock price stability and current ESMA approval timeline norms would require recalibration. Forecasts reflect assumptions around Ministry of Climate Change and Environment mandate enforcement intensity and Gulf Cooperation Council naphtha-cracker margin structures. Practitioners should keep alternative scenarios live as import substitution incentive programs and delamination recycling infrastructure investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market