
 Corrugated Box Making Machine Market | 2026-2036
Corrugated Box Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Box Making Machine Market Intelligence
The capital-intensity divergence between players is rotating competitive advantage toward firms with in-house corrugator roll manufacturing. BOBST Group SA leverages its integrated control systems to command premium positioning in flexo folder-gluer segments. Mitsubishi Heavy Industries Ltd. anchors its presence through large-format corrugator lines serving Asian packaging conglomerates. BHS Corrugated sustains technology leadership via proprietary flute-forming innovations that reduce starch consumption.
A corrugated box making machine is industrial equipment that converts linerboard and corrugated medium into finished shipping containers through sequential processes of conditioning, corrugating, gluing, slitting, and folding; operating speeds typically exceed 300 meters per minute on modern corrugators. Its primary purpose is producing protective packaging for goods distribution across supply chains. Rotary die cutter configurations capture substantial margin pools due to precision cutting demands from electronics and pharmaceutical end users. Servo motor technology is displacing pneumatic systems in high-volume plants where registration accuracy and changeover speed determine throughput economics. The folder slotter category maintains stable replacement demand across mature North American and European installed bases.
EPA emissions standards and OSHA machine guarding regulations shape equipment design requirements for US-based installations, while REACH chemical restrictions influence adhesive formulations used in European corrugator operations. CE marking and MDR conformity pressures extend to ancillary components such as automated bundle handling systems. Stakeholders must monitor how packaging EPR legislation in multiple jurisdictions alters box specification requirements and machine flexibility demands.
Market Dynamics
Corrugated box making machine demand pivots on the tension between e-commerce fulfillment velocity requirements and EU Green Deal packaging circularity mandates, forcing converters to balance throughput maximization against material traceability compliance.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics operators in Germany and the Netherlands are retrofitting distribution centers with servo-driven flexo folder-gluers to compress order-to-ship windows for same-day delivery promises.
- REACH chemical traceability:European adhesive formulation rules are compelling corrugator investments with integrated starch-monitoring systems that document supply chain compliance across linerboard and medium inputs.
- Food contact packaging migration:Bakery and fresh produce exporters in Italy and Spain are specifying barrier-coated board configurations that require precision rotary die cutting for moisture-resistant shelf-ready formats.
Market Restraints
- Steel and aluminum input volatility:Corrugator roll manufacturing consumes specialty alloy grades whose price swings compress margin predictability for machine builders without captive metallurgy operations.
- Skilled technician scarcity:Maintenance of high-speed flute-forming sections requires electro-mechanical specialists concentrated in southern Germany and northern Italy, creating regional service bottlenecks.
- Legacy pneumatic system entrenchment:North American installed bases running pre-2015 folder-gluer configurations face prohibitive retrofit costs that delay servo motor adoption despite registration accuracy advantages.
Strategic Opportunities
- India packaging infrastructure buildout:The country's PLI scheme for paperboard manufacturing is attracting corrugator line investments near Mumbai and Chennai industrial corridors serving FMCG distribution expansion.
- Pharmaceutical serialization integration:Track-and-trace mandates from FDA and EMA are creating demand for die-cutting stations with embedded vision systems that verify barcoded secondary packaging integrity.
- Starch-to-hot-melt adhesive convergence:Hybrid gluing systems combining traditional starch with reactive hot-melt technologies are opening specification opportunities for temperature-sensitive agricultural export packaging.
Industry Challenges
- CE marking and MDR conformity complexity:Automated bundle handling systems must undergo expanded safety assessments under updated machinery directives, extending commissioning timelines for European installations.
- Retrofit integration with legacy DCS architectures:Brownfield corrugator upgrades face protocol incompatibility between modern servo drives and existing distributed control systems running proprietary communication stacks.
- Flute geometry standardization delays:Regional variations in F-flute and N-flute dimensional tolerances between DIN and JIS specifications complicate pan-regional equipment standardization for multinational converters.
Report Scope
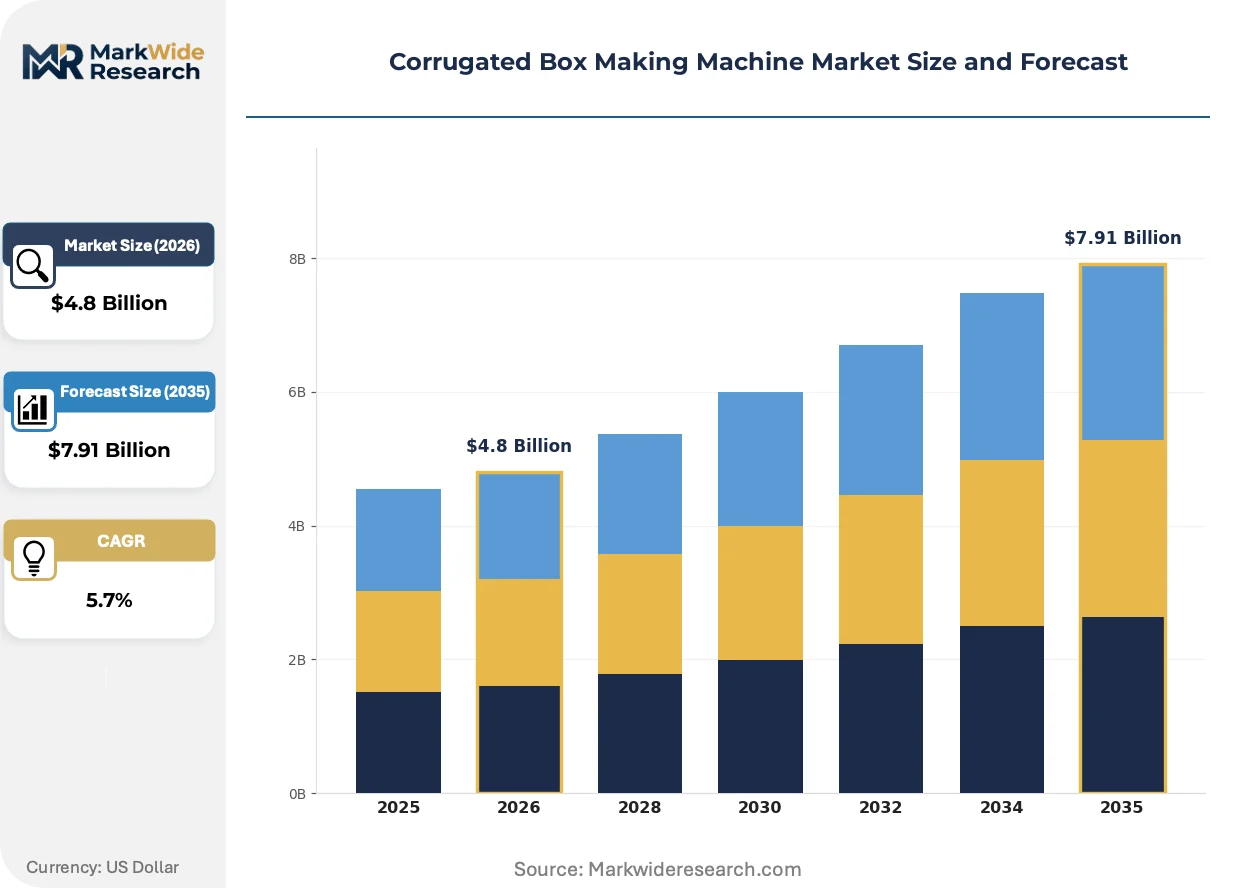
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Box Making Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Single Facer, Double Facer, Rotary Die Cutter, Gluer, Folder Slotter Technology: Hydraulic, Pneumatic, Servo Motor, Electro-Mechanical, Automatic Control End Use Industry: Food & Beverage, Electronics, Pharmaceuticals, Consumer Goods, Chemicals Distribution Channel: Direct Sales, Distributors, Online Platforms, Dealers |
| Companies Covered | BOBST Group SA, Mitsubishi Heavy Industries Ltd., BHS Corrugated, Fosber Spa, Packsize International LLC, BCS Corrugated, EMBA Machinery AB, ISOWA Corporation, SUN Automation Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Box Making Machine Market Strategic Shifts & Innovations
Digital print integration and closed-loop moisture control are redefining corrugator line economics, while regulatory pressure on packaging recyclability accelerates equipment specification changes across converter procurement cycles.
AI-driven predictive maintenance systems are fragmenting traditional service contract structures by enabling real-time vibration analysis of corrugator roll bearings and automated starch viscosity adjustment. Mid-sized converters in Poland and the Czech Republic are piloting these platforms to reduce unplanned downtime without maintaining full in-house mechanical departments. The technology is fragmenting incumbent OEM aftermarket revenue streams as third-party software vendors capture diagnostic value previously monopolized by original equipment service divisions.
EPA emissions standards for volatile organic compounds from adhesive curing operations are compelling US-based corrugator installations to specify thermal oxidizer integration or UV-curable coating alternatives. The industrial consequence is elevated capital intensity for greenfield plants in Ohio and Pennsylvania packaging corridors. Food-contact board producers serving Walmart and Kroger supply chains are most affected, responding with accelerated procurement of low-VOC hot-melt systems that meet both OSHA workplace exposure limits and California Air Resources Board district rules.
Outcome-based service contracts linking equipment availability guarantees to per-box throughput fees are displacing traditional time-and-materials maintenance arrangements among North American e-commerce fulfillment operators. Amazon and Target distribution center engineering teams are negotiating performance-linked agreements that transfer operational risk to OEM service organizations. This procurement evolution is most visible in the southeastern United States, where corrugated consumption concentration near Atlanta and Charlotte logistics hubs creates scale sufficient to support dedicated technician deployment models.
Corrugated Box Making Machine Market Segmentation
Machine configuration choices in the corrugated box making machine market reflect divergent capital intensity, throughput requirements, and compliance burdens across converter operations. Understanding these segment boundaries clarifies where procurement budgets concentrate and how technology roadmaps align with end-use specifications.
Machine Type:
CE marking and MDR conformity pressures vary substantially across corrugator line components, with automated sections facing expanded safety assessments under updated machinery directives.
- Single Facer:The single facer heats and corrugates the medium before bonding it to a single liner, forming the fundamental fluted structure. Demand clusters in brownfield European plants where REACH chemical traceability rules require integrated starch-monitoring systems that document supply chain compliance. EPA emissions standards for adhesive curing operations also shape replacement cycles in Ohio and Pennsylvania packaging corridors.
- Rotary Die Cutter:Precision cutting configurations capture substantial margin pools due to dimensional accuracy demands from electronics and pharmaceutical end users. Servo motor technology is displacing pneumatic systems here where registration accuracy and changeover speed determine throughput economics for same-day e-commerce fulfillment.
- Double Facer:Completes the board sandwich by attaching the second liner to the single-faced web, operating at speeds exceeding 300 meters per minute on modern corrugator lines.
- Gluer:Applies adhesive to flute tips or liner edges, with formulation choices constrained by REACH restrictions in European operations and OSHA workplace exposure limits in US installations.
- Folder Slotter:Maintains stable replacement demand across mature North American and European installed bases running pre-2015 pneumatic configurations.
Rotary die cutter handles the majority of throughput in high-margin precision applications; single facer is the fastest mover on share as converters prioritize upstream process control for compliance documentation.
Technology:
Cost tier differentiation separates premium servo configurations from legacy pneumatic installations, with electro-mechanical hybrids occupying a transitional middle band.
- Servo Motor:Digital drive systems deliver sub-millimeter registration accuracy and programmable changeover sequences. Third-party logistics operators in Germany and the Netherlands are retrofitting distribution centers with these drives to compress order-to-ship windows for same-day delivery promises.
- Pneumatic:Compressed-air actuation dominates legacy installed bases but faces prohibitive retrofit costs that delay replacement despite throughput disadvantages.
- Hydraulic:High-force actuation for heavy-board formats and specialty flute profiles requiring sustained pressure during forming operations.
- Electro-Mechanical:Hybrid architectures combining electric servos with mechanical linkages for mid-volume plants balancing capital constraints against accuracy requirements.
- Automatic Control:Integrated PLC and HMI systems enabling AI-driven predictive maintenance through real-time vibration analysis of corrugator roll bearings.
Servo motor technology commands the premium tier on performance metrics; automatic control systems are expanding most quickly as converters seek to reduce unplanned downtime without maintaining full in-house mechanical departments.
End Use Industry:
Application-specific requirements dictate machine flexibility demands, with food contact and pharmaceutical segments imposing the most stringent specification constraints.
- Food & Beverage:Bakery and fresh produce exporters in Italy and Spain specify barrier-coated board configurations requiring precision rotary die cutting for moisture-resistant shelf-ready formats. FDA and EMA track-and-trace mandates are creating demand for die-cutting stations with embedded vision systems.
- Pharmaceuticals:Serialization integration requirements from FDA and EMA drive specification of stations with embedded vision systems that verify barcoded secondary packaging integrity.
- Electronics:Anti-static and precision-fit packaging for high-value components demands tight dimensional tolerances and cleanroom-compatible materials handling.
- Consumer Goods:High-volume, low-mix production of standard RSC cases for retail distribution through Walmart and Kroger supply chains.
- Chemicals:UN-certified dangerous goods packaging requiring burst strength verification and hazardous materials labeling compliance.
Food & beverage absorbs the largest equipment procurement volumes; pharmaceuticals is climbing the fastest on specification intensity as serialization mandates proliferate.
Distribution Channel:
Customer type and geography determine channel selection, with large-format corrugator lines favoring direct OEM relationships while aftermarket parts flow through intermediaries.
- Direct Sales:OEM field organizations handle specification, installation, and commissioning for greenfield corrugator lines, particularly in India where PLI scheme incentives are attracting investments near Mumbai and Chennai industrial corridors.
- Distributors:Regional inventory and technical support for spare parts, consumables, and retrofit components across fragmented converter bases.
- Dealers:Local representation for mid-sized equipment and used machinery transactions in markets with established packaging infrastructure.
- Online Platforms:Emerging procurement channel for standardized consumables and documentation, though capital equipment transactions remain relationship-intensive.
Direct sales captures the majority of line revenue; distributors are gaining share fastest in aftermarket service and parts procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converter consolidation commands pricing premiums for high-throughput corrugator lines, while Indian packaging infrastructure buildout operates on compressed capital cycles under PLI scheme incentives.
United States
Third-party logistics operators in Ohio and Pennsylvania are retrofitting distribution centers with servo-driven flexo folder-gluers to compress order-to-ship windows. EPA emissions standards for volatile organic compounds from adhesive curing operations shape equipment procurement specifications. Atlanta and Charlotte logistics hubs concentrate corrugated consumption sufficient to support dedicated technician deployment models for outcome-based service contracts.
Germany
Converter consolidation favors high-throughput corrugator lines with integrated starch-monitoring systems for REACH chemical traceability documentation. KBA and EU Green Deal packaging rules tighten material traceability requirements across linerboard and medium inputs. Southern Germany industrial corridors concentrate electro-mechanical specialists for high-speed flute-forming section maintenance, creating regional service bottlenecks.
India
The country's PLI scheme for paperboard manufacturing attracts corrugator line investments serving FMCG distribution expansion. BIS standards and central bank financing protocols shape equipment import and commissioning timelines. Mumbai and Chennai industrial corridors anchor greenfield corrugator installations for domestic packaging demand growth.
China
Dual carbon goals and GB standards for industrial emissions accelerate specification of low-VOC hot-melt systems in packaging manufacturing clusters. SAMR equipment certification requirements extend commissioning timelines for automated bundle handling systems. Yangtze River Delta manufacturing bases concentrate large-format corrugator line demand from Asian packaging conglomerates.
Italy
Bakery and fresh produce exporters specify barrier-coated board configurations requiring precision rotary die cutting for moisture-resistant shelf-ready formats. EMA track-and-trace mandates and national pharmaceutical regulations drive serialization-integrated die-cutting station demand. Northern Italy industrial zones concentrate legacy pneumatic system installed bases facing prohibitive servo retrofit costs.
Corrugated Box Making Machine Market Key Industry Players
Concentration sits with integrated control system specialists and large-format corrugator line fabricators. The vendor base spans Swiss precision engineering groups, Japanese industrial conglomerates, and German mechanical specialists. Strategic archetypes include captive roll manufacturers with metallurgy operations, servo drive integrators, and starch-formulation technology licensors. Competitive moves center on backward integration into corrugator roll manufacturing and AI-driven predictive maintenance platform deployment.
Within the integrated control systems tier, BOBST Group SA exemplifies premium positioning in flexo folder-gluer segments. Mitsubishi Heavy Industries Ltd. anchors large-format corrugator line supply to Asian packaging conglomerates. BHS Corrugated occupies a position defined by proprietary flute-forming innovations that reduce starch consumption in high-speed operations.
| Leading Market Players |
|---|
| BOBST Group SA |
| Mitsubishi Heavy Industries Ltd. |
| BHS Corrugated |
| Fosber Spa |
| Packsize International LLC |
| BCS Corrugated |
| EMBA Machinery AB |
| ISOWA Corporation |
| SUN Automation Group |
| Others |
Cost & Logistics Intelligence
Corrugator line capacity utilization above 85 percent in southern Germany and northern Italy creates natural price floors that shield integrated roll manufacturers from spot-market volatility. This scale concentration rewards OEMs with captive metallurgy operations while forcing smaller fabricators toward configured-to-order positioning.
Pricing Analysis
The customization-premium spread between standard folder-gluer configurations and precision rotary die cutters exceeds three-to-one on per-meter throughput metrics. Three-tier pricing structure across premium servo-driven systems, standard electro-mechanical hybrids, and economy pneumatic legacy tiers reflects certification-grade differentiation and after-sales bundling intensity. Pricing pressure stems from Indian PLI scheme incentives compressing capital recovery timelines for greenfield installations. Third-party logistics operators in Germany and the Netherlands show lowest price sensitivity due to same-day fulfillment service-level agreements, while mid-sized Polish converters face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Hamburg spiked following Red Sea routing disruptions, elevating landed costs for Asian-sourced servo drive components and PLC systems. Manufacturing concentration clusters in Germany, Japan, and China for corrugator roll fabrication, with specialty alloy feedstock drawing from Austrian and Swedish metallurgy centers. Single-source vulnerability sits with precision flute-forming tooling sourced exclusively from BHS Corrugated and select Japanese suppliers. Distribution runs through direct OEM field organizations for greenfield lines, with regional distributors capturing aftermarket parts and retrofit component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated box making machine demand sits in early-cycle expansion as e-commerce fulfillment automation penetrates third-party logistics networks. Servo motor retrofit mandates and REACH chemical traceability rules accelerate replacement cycles beyond traditional depreciation schedules.
For Market Incumbents: Shield installed base revenue streams by embedding AI-driven predictive maintenance platforms that fragment third-party diagnostic competition. Deepen backward integration into corrugator roll manufacturing to offset specialty alloy price volatility from Austrian and Swedish suppliers. Prioritize CE marking and MDR conformity certification for automated bundle handling systems ahead of European commissioning timeline extensions. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors near Mumbai and Chennai where domestic paperboard manufacturing incentives attract greenfield corrugator investments without entrenched incumbent relationships. Target pharmaceutical serialization integration as the most penetrable specification tier, embedding vision systems for FDA and EMA track-and-trace mandates. Pursue outcome-based service contract pilots with southeastern US e-commerce fulfillment operators to bypass capital-intensive direct equipment sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servo drive integrators with predictive maintenance platform deployment, locking in per-box throughput fee structures with Amazon and Target distribution centers. Five-to-ten year viability favors captive roll manufacturers with metallurgy operations over pure-play assembly fabricators. Monitor starch-to-hot-melt adhesive convergence adoption rates in Italian and Spanish agricultural export packaging as inflection signal for hybrid gluing system specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corrugator Roll Manufacturing | Captive metallurgy operations insulate margin predictability against specialty alloy price swings from Austrian suppliers. |
| AI-Driven Predictive Maintenance Platform Deployment | Real-time vibration analysis fragments incumbent OEM aftermarket revenue previously monopolized by original equipment service divisions. |
| Pharmaceutical Serialization Integration | Embedded vision systems for FDA and EMA track-and-trace mandates capture premium specification tiers in die-cutting stations. |
| Servo Motor Retrofit Program Acceleration | Registration accuracy advantages displace pneumatic systems in high-volume plants where changeover speed determines throughput economics. |
| Outcome-Based Service Contract Structuring | Per-box throughput fees transfer operational risk to OEM service organizations at Amazon and Target distribution centers. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers at corrugated converters, procurement leads at third-party logistics operators, aftermarket service heads at OEM field organizations, and regulatory compliance officers at packaging conglomerates, and refined through secondary validation across SEC filings, EU machinery directive documentation, customs and trade data, and BIS standards publications. Bottom-up equipment shipment tallies triangulated against top-down corrugated board consumption forecasts.
Variance decomposition across machine type, technology tier, end-use industry, and distribution channel dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from logistic diffusion curves for servo motor adoption and replacement cycle compression under REACH and EU Green Deal compliance pressures. Industry-specific inputs included starch viscosity monitoring system penetration rates and pharmaceutical serialization mandate implementation timelines.
Material uncertainties — steel and aluminum input volatility, skilled technician scarcity bottlenecks in southern Germany, and legacy pneumatic system retrofit cost thresholds — sit outside the modeled envelope. Forecasts reflect assumptions regarding e-commerce fulfillment velocity maintenance and regulatory compliance timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Aerosol Filling Machines Market