
 Lithographic Printing for Packaging Market | 2026-2036
Lithographic Printing for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Lithographic Printing for Packaging Market Foresight
ISO 12647 color management certification is reorganizing supplier eligibility for high-velocity consumer goods contracts. WestRock leverages integrated pulp-to-printboard operations to control substrate quality and lead times for North American beverage cartons. Graphic Packaging International anchors its position through dedicated food-contact compliant coating lines that serve quick-service restaurant chains. Stora Enso competes from Nordic renewable fiber bases, supplying brownboard and white-top kraftliner grades to European lithographic converters.
Lithographic printing for packaging employs planographic aluminum plates with hydrophilic non-image areas and oleophilic image areas, transferring ink via rubber blanket cylinders onto paper, cardboard, or metallized substrates at resolutions exceeding 175 lines per inch for fine halftone reproduction. Its primary purpose is high-volume, visually consistent decoration of folding cartons, labels, and rigid boxes where brand color fidelity and graphic complexity justify platemaking investment. Cartons and labels represent the most established volume pools, with flexible packaging representing a faster-growing but technically contested frontier as converters adapt web-offset and UV curing systems to thinner film structures. Water-based lithography and UV lithography technologies are diverging in adoption patterns, with water-based systems capturing cost-sensitive food applications and UV systems commanding premium cosmetics and electronics assignments where instant cure and rub resistance justify higher ink expenditure.
EPA regulates volatile organic compound emissions from printing operations through Maximum Achievable Control Technology standards, while FDA maintains 21 CFR 175.300 and related indirect food additive limits for coatings and inks contacting packaged edibles. REACH restricts specific photoinitiators and heavy metal pigments in UV lithographic inks entering European consumer goods supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that are beginning to assign end-of-life accountability to printed packaging formats.
Market Dynamics
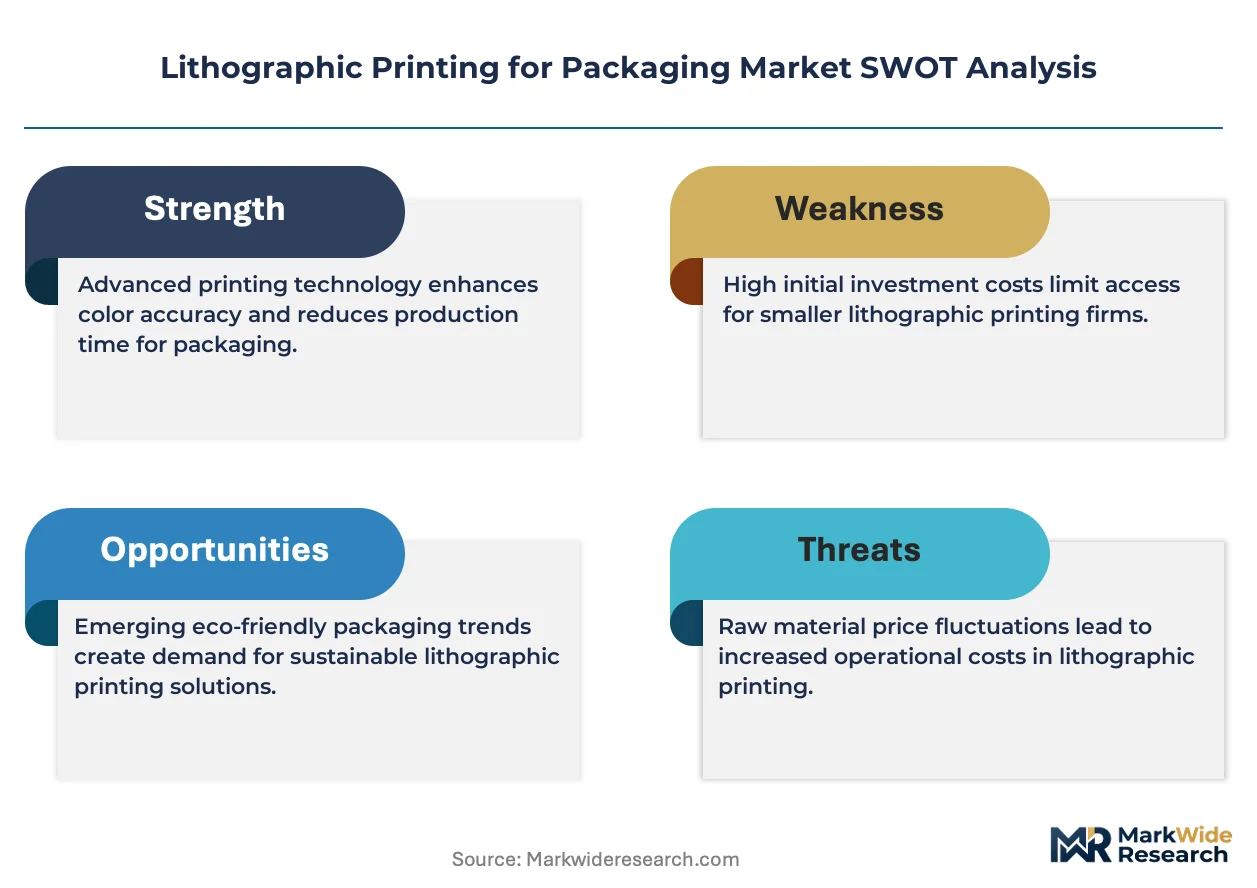
Water-based and UV lithographic ink systems are diverging into parallel supply chains, with EU REACH mandates and FDA indirect food additive rules forcing converters to maintain dual formulation portfolios and separate production lines.
Growth Catalysts
- EU Green Deal packaging mandates:Folding carton converters in Germany and France are accelerating lithographic line investments to meet recycled content thresholds and lower-VOC process requirements for export eligibility.
- Quick-service restaurant chains:Food-contact compliant coating technologies are unlocking high-volume lithographic contracts for beverage carriers and sandwich cartons with extended shelf-life graphics.
- ISO 12647 color certification:Consumer goods manufacturers are restricting supplier pools to certified converters, concentrating lithographic volume among qualified print houses with spectrophotometric quality control systems.
Market Restraints
- Aluminum plate cost volatility:Planographic plate substrate prices fluctuate with bauxite supply chains concentrated in Guinea and Australia, compressing converter margins on short-run jobs.
- Photoinitiator restrictions:REACH Annex XVII limits on specific benzophenone derivatives are forcing UV lithographic ink reformulations, extending qualification timelines for European pharmaceutical packaging contracts.
- Digital print substitution:Electrophotographic and inkjet systems are capturing folding carton jobs below five thousand units, eroding lithography's traditional stronghold in mid-volume promotional packaging.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO compliance requirements and FSSAI labeling rules are creating demand for high-fidelity lithographic cartons among generic drug manufacturers supplying regulated markets.
- UV-LED curing convergence:Instant-dry lithographic systems paired with low-energy LED arrays are opening flexible film applications previously reserved for gravure and flexographic processes.
- California extended producer responsibility:State-level printed packaging accountability laws are incentivizing domestic lithographic capacity investment to reduce carbon-intensive import logistics from Asian converters.
Industry Challenges
- Color management specialist scarcity:Qualified prepress technicians capable of G7 calibration and ICC profile generation for food-contact substrates command premium wages, constraining converter expansion timelines.
- Legacy press integration:Retrofitting sheet-fed offset equipment with automated register control and inline coating stations requires extended downtime, disrupting just-in-time delivery commitments to beverage brand customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithographic Printing for Packaging Market |
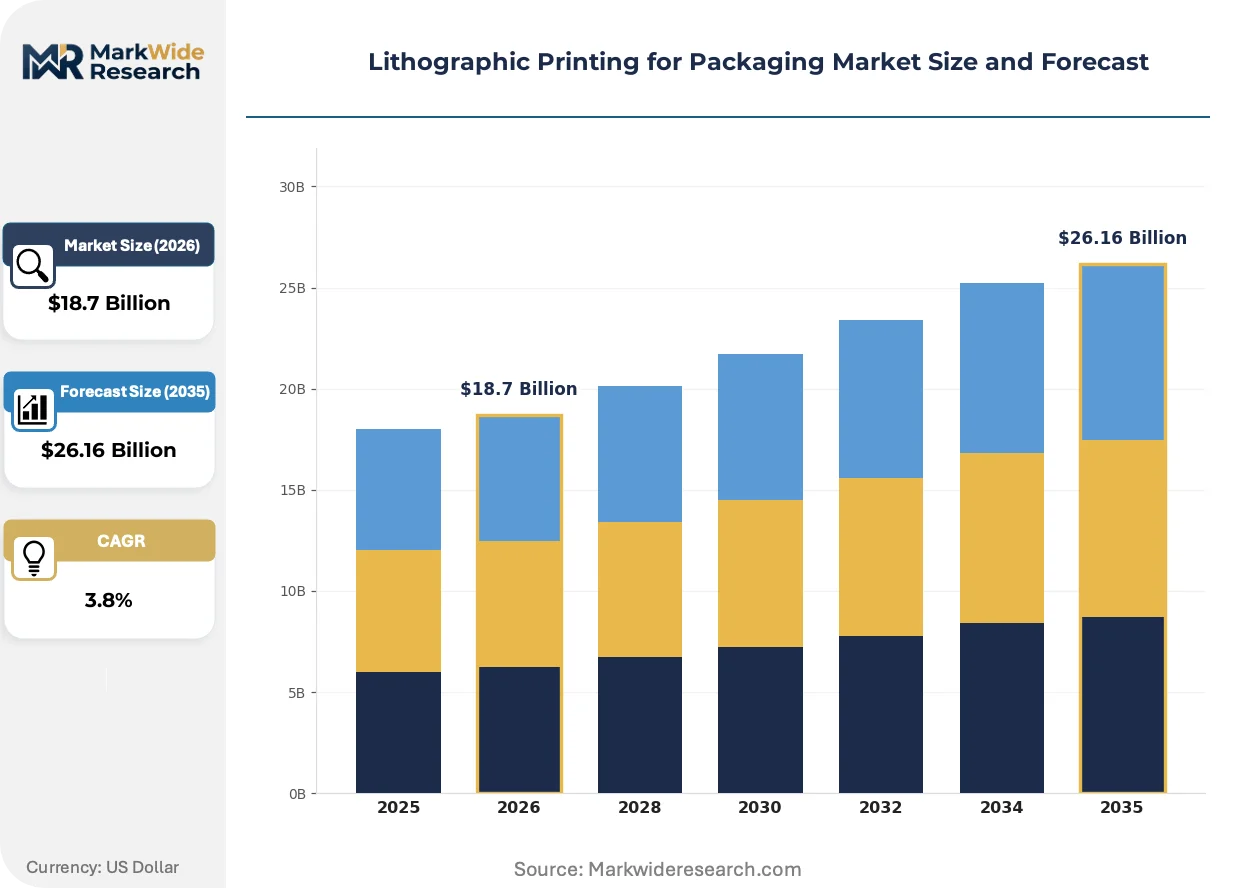
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Cartons, Flexible Packaging, Books Substrate: Paper, Plastic, Metal, Cardboard End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: UV Lithography, Water-Based Lithography, Digital Lithography, Traditional Lithography |
| Companies Covered | WestRock, Graphic Packaging International, Quad/Graphics, Stora Enso, Crown Holdings, RR Donnelley, Smurfit Kappa, Sappi, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithographic Printing for Packaging Market Shifts & Advancements
Process chemistry innovations and substrate diversification are compressing lithography's traditional application boundaries, forcing equipment manufacturers and ink suppliers to coordinate platform development across previously siloed packaging categories.
Electron beam lithographic curing is fragmenting the premium cosmetics and electronics packaging segment by eliminating photoinitiator migration risks entirely. Luxury skincare brands in France and Switzerland are specifying e-beam cured cartons for antioxidant-sensitive formulations. This technology is compressing the addressable market for conventional UV systems in high-value applications where regulatory scrutiny is most intense.
REACH restrictions on specific heavy metal pigments and photoinitiators are reorganizing European ink supply chains. Converters serving pharmaceutical and infant food markets must maintain segregated ink inventories and dedicated press cleaning protocols. German folding carton exporters are investing in water-based lithographic lines to preserve access to EU single market contracts while maintaining FDA-compliant UV capacity for North American pharmaceutical shipments.
Brand owner color specification protocols are tightening tolerance windows for shelf-ready packaging, with major beverage and confectionery companies mandating Delta E thresholds below two for primary brand colors. This behavioral shift is disqualifying smaller lithographic converters lacking closed-loop spectrophotometric control systems. The phenomenon is most visible in North American quick-service restaurant supply chains, where national rollout consistency requirements favor large-scale certified print houses over regional competitors.
Lithographic Printing for Packaging Market Segmentation
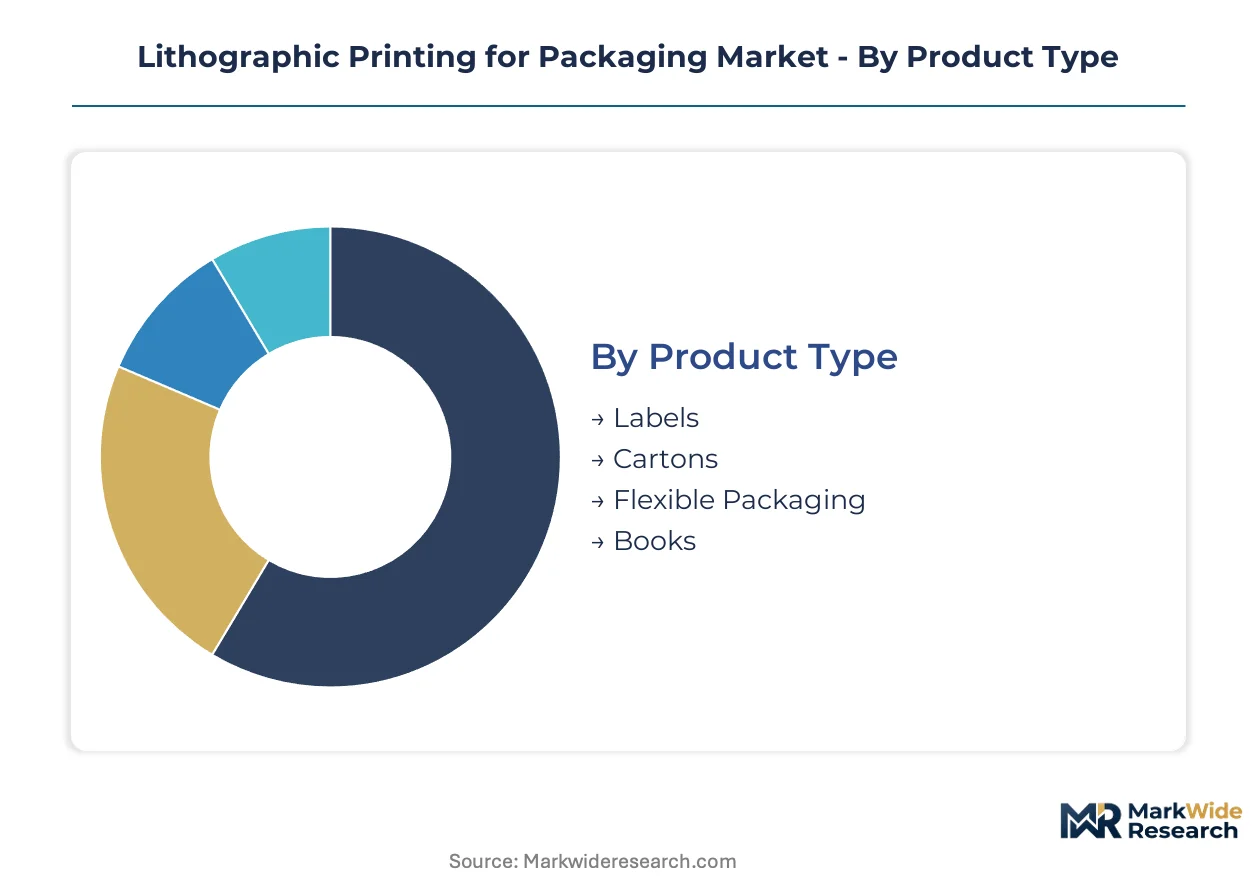
Lithographic printing for packaging serves heterogeneous demand pools with divergent substrate, regulatory, and finishing requirements. Segmentation reveals where technology investments concentrate and where formulation portfolios must bifurcate to serve parallel supply chains.
Product Type:
REACH and FDA indirect food additive rules force converters to maintain segregated production lines for food-contact versus non-food applications.
- Labels:Pressure-sensitive and wet-glue label stocks require oleophilic plate chemistry optimized for smooth coated papers. Pharmaceutical serialization mandates in Germany and France are driving demand for high-resolution lithographic labels with variable data integration.
- Cartons:Folding carton structures dominate lithographic volume, with quick-service restaurant chains in North America specifying food-contact compliant coating systems for beverage carriers and sandwich packaging. Extended shelf-life graphics requirements favor UV-cured surfaces.
- Flexible Packaging:Web-offset adaptations to thinner film structures represent a technically contested frontier, with UV-LED curing systems opening applications previously reserved for gravure.
- Books:Educational and trade book covers utilize lithographic decoration for dust jackets and case bindings, though digital print substitution erodes share in short-run academic titles.
Established volume favors Cartons; emerging adoption favors Flexible Packaging.
Substrate:
Substrate selection determines ink system compatibility, curing architecture, and regulatory compliance pathways.
- Paper:Uncoated and coated paper grades serve label and book applications where absorbency controls ink holdout. Brownboard and white-top kraftliner from Nordic renewable fiber bases supply European lithographic converters serving export markets.
- Cardboard:Folding carton board demands precise caliper control for automated erecting and filling lines. WestRock's integrated pulp-to-printboard operations anchor North American beverage carton supply chains through captive substrate quality management.
- Plastic:Polyester and polypropylene films require surface treatment and specialized ink adhesion for lithographic compatibility, limiting adoption to premium cosmetic and electronics segments.
- Metal:Tinplate and aluminum substrates for rigid containers and decorative tins utilize offset lithography with specialized blanket compounds to manage substrate hardness and thermal conductivity.
Cardboard commands the largest installed press base; Plastic substrates are climbing the fastest as UV-LED curing expands film addressability.
End User:
End-use concentration determines color fidelity requirements, regulatory scrutiny intensity, and contract qualification timelines.
- Food & Beverage:Folding carton demand from quick-service restaurant chains and premium shelf-ready packaging mandates ISO 12647 certification. FDA 21 CFR 175.300 compliance for indirect food contact restricts coating and ink formulation options.
- Pharmaceuticals:CDSCO compliance requirements and FSSAI labeling rules in India are creating demand for high-fidelity lithographic cartons among generic drug manufacturers supplying regulated markets. REACH photoinitiator restrictions extend European qualification timelines.
- Cosmetics:Luxury skincare brands in France and Switzerland specify electron beam cured cartons for antioxidant-sensitive formulations, eliminating photoinitiator migration risks entirely.
- Electronics:Consumer electronics packaging requires rub-resistant UV-cured surfaces for retail handling durability, with Delta E color tolerances below two for brand consistency across regional rollouts.
Food & Beverage anchors lithographic volume; Cosmetics shows the steepest expansion trajectory as e-beam curing penetrates premium segments.
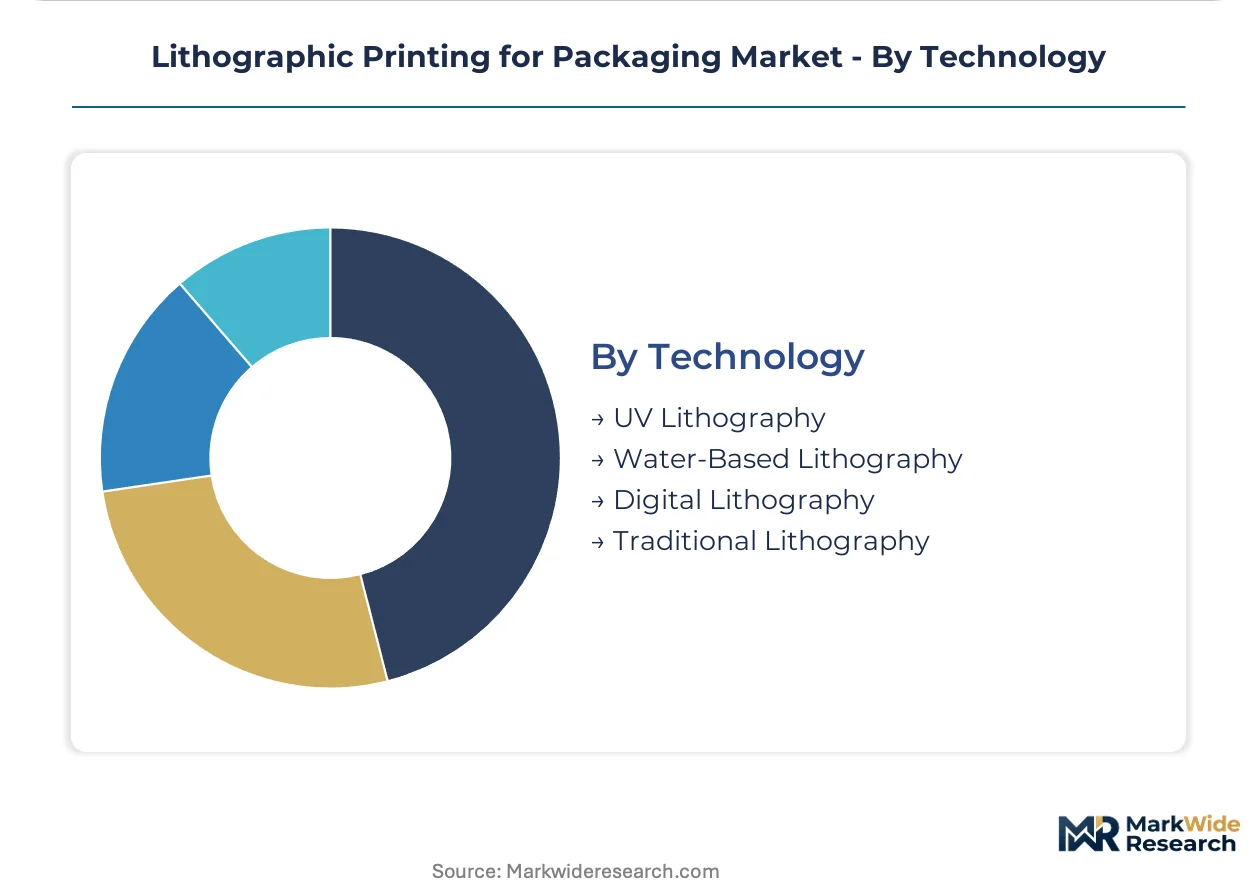
Technology:
Technology selection bifurcates around curing chemistry, energy consumption, and regulatory compliance geography.
- UV Lithography:Instant cure and rub resistance justify higher ink expenditure in premium cosmetics and electronics assignments. REACH Annex XVII limits on benzophenone derivatives are forcing reformulations in European pharmaceutical packaging.
- Water-Based Lithography:Lower-VOC processes capture cost-sensitive food applications and preserve EU single market access under Green Deal mandates. German folding carton exporters maintain water-based capacity alongside FDA-compliant UV lines for North American shipments.
- Digital Lithography:Electrophotographic and inkjet systems capture folding carton jobs below five thousand units, eroding lithography's traditional stronghold in mid-volume promotional packaging.
- Traditional Lithography:Conventional oil-based ink systems persist in non-food applications where regulatory constraints are less stringent, though environmental compliance pressures narrow the addressable market.
Water-Based Lithography dominates food-contact volume; UV Lithography gains share fastest as LED curing reduces energy costs and expands substrate range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and pharmaceutical exporters drive lithographic printing demand across distinct national markets. Buyer concentration in food-contact packaging and regulated healthcare segments shapes regional investment patterns. Regulatory divergence between EU Green Deal mandates and FDA compliance requirements forces converters to maintain dual-capability production networks.
United States
Beverage carton demand from quick-service restaurant chains and extended producer responsibility laws in California and New York concentrate lithographic investment. EPA Maximum Achievable Control Technology standards govern VOC emissions from printing operations. The Southeast manufacturing corridor hosts folding carton converters serving national quick-service restaurant supply chains with food-contact compliant coating systems.
Germany
Folding carton exports and pharmaceutical packaging investments reinforce lithographic capacity expansion. REACH Annex XVII restrictions on benzophenone photoinitiators force UV ink reformulations for European pharmaceutical contracts. The Rhine-Ruhr industrial cluster anchors water-based lithographic line investments preserving EU single market access under Green Deal recycled content thresholds.
India
Generic drug manufacturers supplying regulated markets drive demand for high-fidelity lithographic cartons. CDSCO compliance requirements and FSSAI labeling rules create qualification barriers for export-oriented packaging. Gujarat and Maharashtra host converter investments targeting pharmaceutical serialization mandates and food-contact substrate certifications.
China
Consumer electronics packaging and domestic quick-service restaurant expansion sustain lithographic press utilization. GB standards for food-contact materials and dual carbon goals influence curing technology selection. The Yangtze River Delta concentration serves electronics brands requiring Delta E color tolerances below two for retail handling durability.
Switzerland
Luxury skincare brands specify electron beam cured cartons for antioxidant-sensitive formulations. Swissmedic pharmaceutical regulations and EU REACH alignment create stringent substrate and ink qualification protocols. The Basel-Zurich corridor hosts premium cosmetics packaging specialists eliminating photoinitiator migration risks entirely.
Lithographic Printing for Packaging Market Competitive Landscape
Player mix skews toward integrated forest products groups and specialized folding carton converters with captive substrate operations. Consolidation pressure concentrates volume among scale-capable print houses holding ISO 12647 certification and spectrophotometric quality control systems. Two strategic archetypes dominate: pulp-to-printboard integrated producers controlling substrate quality and lead times, and coating technology specialists maintaining segregated food-contact production lines. Competitive moves center on capacity expansion in water-based lithographic systems and strategic partnerships securing renewable fiber supply agreements.
Among North American integrated producers, WestRock exemplifies the pulp-to-printboard archetype through captive substrate quality management for beverage carton supply chains. Graphic Packaging International occupies a position within the food-contact coating specialist tier, serving quick-service restaurant chains with dedicated compliant production lines. Stora Enso represents the Nordic renewable fiber anchor, supplying brownboard and white-top kraftliner grades to European lithographic converters from integrated forest operations.
| Leading Market Players |
|---|
| WestRock |
| Graphic Packaging International |
| Quad/Graphics |
| Stora Enso |
| Crown Holdings |
| RR Donnelley |
| Smurfit Kappa |
| Sappi |
| Mondi Group |
| Others |
Supply & Pricing Matrix
ISO 12647 certification gates both supplier qualification and price differentiation simultaneously, as consumer goods manufacturers restrict contracts to certified converters while commanding premium rates for spectrophotometric color control. This regulatory-quality nexus concentrates pricing power among scale-capable print houses holding G7 calibration capabilities, while squeezing regional competitors into commodity tiers.
Pricing Analysis
Cost-plus contracts with aluminum LME indexation dominate long-term folding carton agreements, insulating converters from bauxite volatility while passing substrate swings to beverage brand customers. Price differentiation stratifies across certification grade and volume scale, with ISO 12647-certified houses commanding 15-20% premiums over uncertified competitors. Cost compression in short-run promotional packaging is intensifying because electrophotographic systems capture jobs below five thousand units. Quick-service restaurant chains show highest price sensitivity due to national rollout volume scale, while luxury cosmetics brands demonstrate lowest sensitivity given photoinitiator-free e-beam requirements.
Supply Chain Analysis
Bauxite concentrate from Guinea and Australia transit through Rotterdam and Singapore hubs to underwrite global planographic plate supply chains. Raw material dependencies draw from aluminum smelting, rubber blanket compounds, and photoinitiator chemicals for UV systems. Single-source vulnerability concentrates in bauxite-rich West African corridors facing geopolitical disruption. Distribution runs through integrated pulp-to-printboard producers controlling captive substrate quality for North American beverage carton supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU Green Deal and FDA compliance regimes creates white-space opportunities for specialized converters maintaining dual-capability production networks. This demand-side shift toward parallel certification requirements fragments volume among qualified specialists rather than consolidating around generalists.
For Market Incumbents: Secure water-based lithographic capacity in Germany and France to preserve EU single market access under recycled content mandates, while maintaining FDA-compliant UV lines for North American pharmaceutical exports. Backward integration into renewable fiber supply agreements with Nordic producers anchors substrate cost control against pulp volatility. Digital print substitution in sub-five-thousand-unit folding cartons threatens mid-volume promotional margins, requiring automation investment to defend throughput economics.
For New Entrants and Emerging Players: Lead with UV-LED curing specialization targeting flexible film applications previously reserved for gravure, where technical differentiation commands premium positioning. Indian pharmaceutical export packaging offers the most penetrable geography, as CDSCO compliance requirements and FSSAI labeling rules create qualification barriers that favor dedicated entrants over diversified converters. Partner with generic drug manufacturers supplying regulated markets to establish reference accounts before scaling to multinational pharmaceutical contracts.
For Investors and Strategic Acquirers: EU REACH Annex XVII photoinitiator restrictions reshape the acquisition landscape toward converters with segregated ink inventories and dedicated food-contact production lines. Long-term viability centers on water-based and UV-LED technology portfolios capable of serving parallel regulatory geographies without cross-contamination risk. Target mid-cap folding carton specialists holding ISO 12647 certification and spectrophotometric quality control systems. Watch California extended producer responsibility implementation as the signal indicating domestic capacity investment acceleration versus continued Asian import reliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Lithography Capacity Expansion | Preserves EU Green Deal compliance access for German folding carton exporters serving regulated markets. |
| UV-LED Curing Technology Deployment | Opens flexible film applications for cosmetics converters previously excluded from gravure-dominated segments. |
| ISO 12647 Certification Investment | Qualifies converters for quick-service restaurant national rollout contracts requiring Delta E thresholds below two. |
| Renewable Fiber Supply Agreement | Secures brownboard and white-top kraftliner from Nordic integrated forest operations for European lithographic demand. |
| Electron Beam Curing Pilot Line | Eliminates photoinitiator migration risks for Swiss luxury skincare brands specifying antioxidant-sensitive packaging. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with folding carton procurement managers at quick-service restaurant chains, prepress technical directors at certified lithographic converters, regulatory affairs leads at ink formulation suppliers, and pharmaceutical packaging quality heads at generic drug manufacturers. Secondary validation drew from EPA Maximum Achievable Control Technology filings, REACH Annex XVII substance restriction updates, FDA 21 CFR indirect food additive guidance, and EU Green Deal packaging mandate progress reports. Bottom-up press utilization data and top-down folding carton production estimates were triangulated to anchor volume assumptions.
Across the analysis window, the forecast framework models lithographic printing demand through segmentation dimensions spanning substrate type, curing technology, end-use concentration, and regional regulatory cluster. CAGRs were derived from installed press base evolution, technology substitution curves, and export packaging growth trajectories. Industry-specific inputs include pharmaceutical serialization mandate timelines in India and Germany, quick-service restaurant chain expansion plans in North America and China, and UV-LED curing adoption rates in flexible packaging applications.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable bauxite supply corridors, or continued quick-service restaurant volume growth would require recalibration. Forecasts reflect assumptions regarding certification adoption curves and technology substitution thresholds. Practitioners should keep alternative scenarios live as REACH photoinitiator restriction scope and California extended producer responsibility implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Label Printers Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
North America Print Label Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Laser Coders Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Soft Signage Market
Packaging Printing
Stack Flexo Printing Press Market