
 Global Digital Printing Packaging Market | 2026-2036
Global Digital Printing Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Printing Packaging Market Intelligence
Expanded production capacity in China is fragmenting the supply base for digital printing equipment and consumables. HP Inc. leverages its deep technology portfolio in inkjet and electrophotography to capture share among high-volume brand owners. Concurrently, packaging specialists like Amcor plc and WestRock Company embed digital presses within their converting operations to support demand for personalization.
Digital printing for packaging involves transferring a digital file directly to a substrate without requiring printing plates. This process uses technologies like inkjet, which applies controlled micro-droplets of ink to create high-resolution graphics for cost-effective short runs and customization. Inkjet technology leads growth due to its versatility on diverse substrates from flexible packaging to folding cartons. The food and beverages application remains the largest segment, demanding rapid design changes for seasonal and promotional packaging.
Regulations governing food contact materials, such as those from the US FDA and the European Food Safety Authority (EFSA), dictate permissible ink formulations. EU directives on packaging waste and recyclability under the Green Deal framework influence substrate selection and the push for more sustainable solutions. Stakeholders must therefore navigate the trade-off between investing in high-speed, versatile presses and managing the rising cost of compliant, eco-friendly consumables.
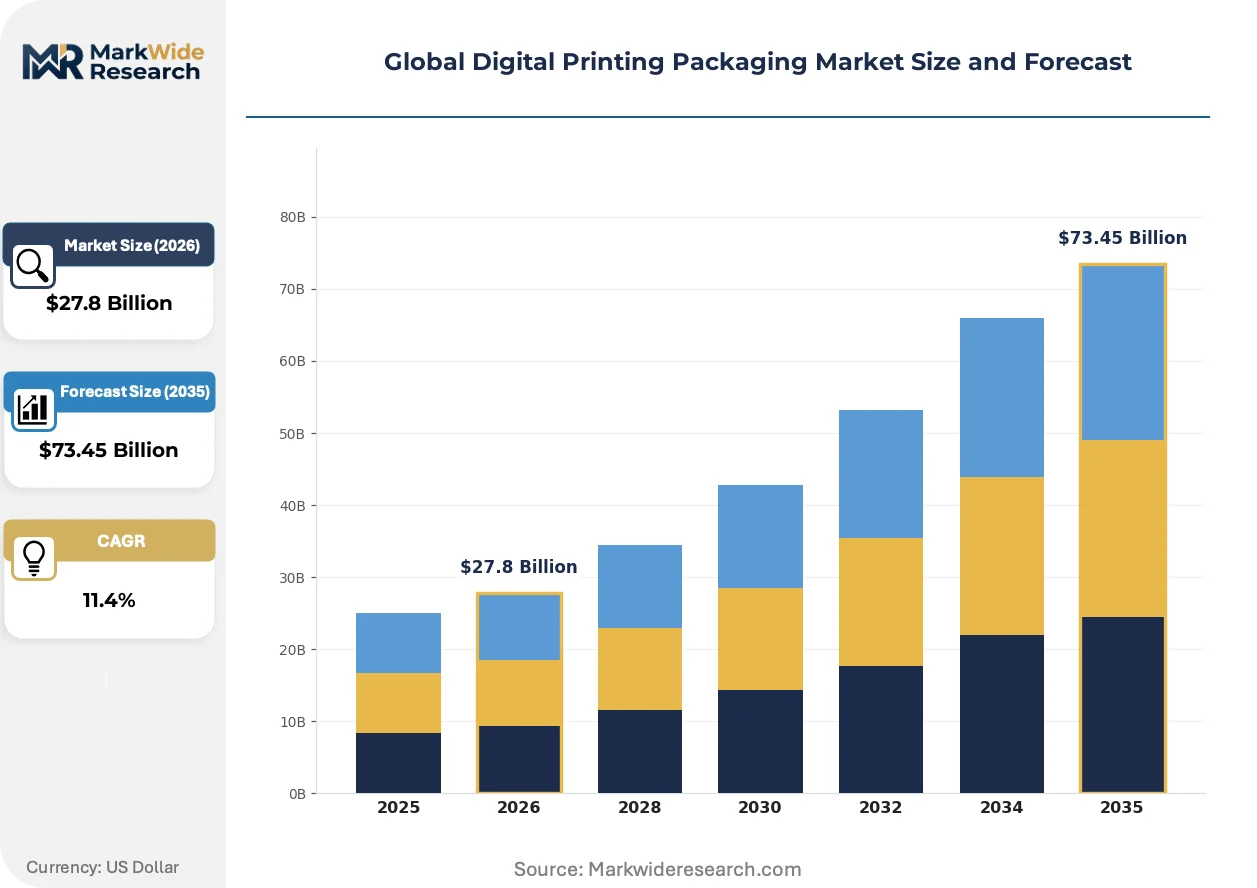
Market Dynamics
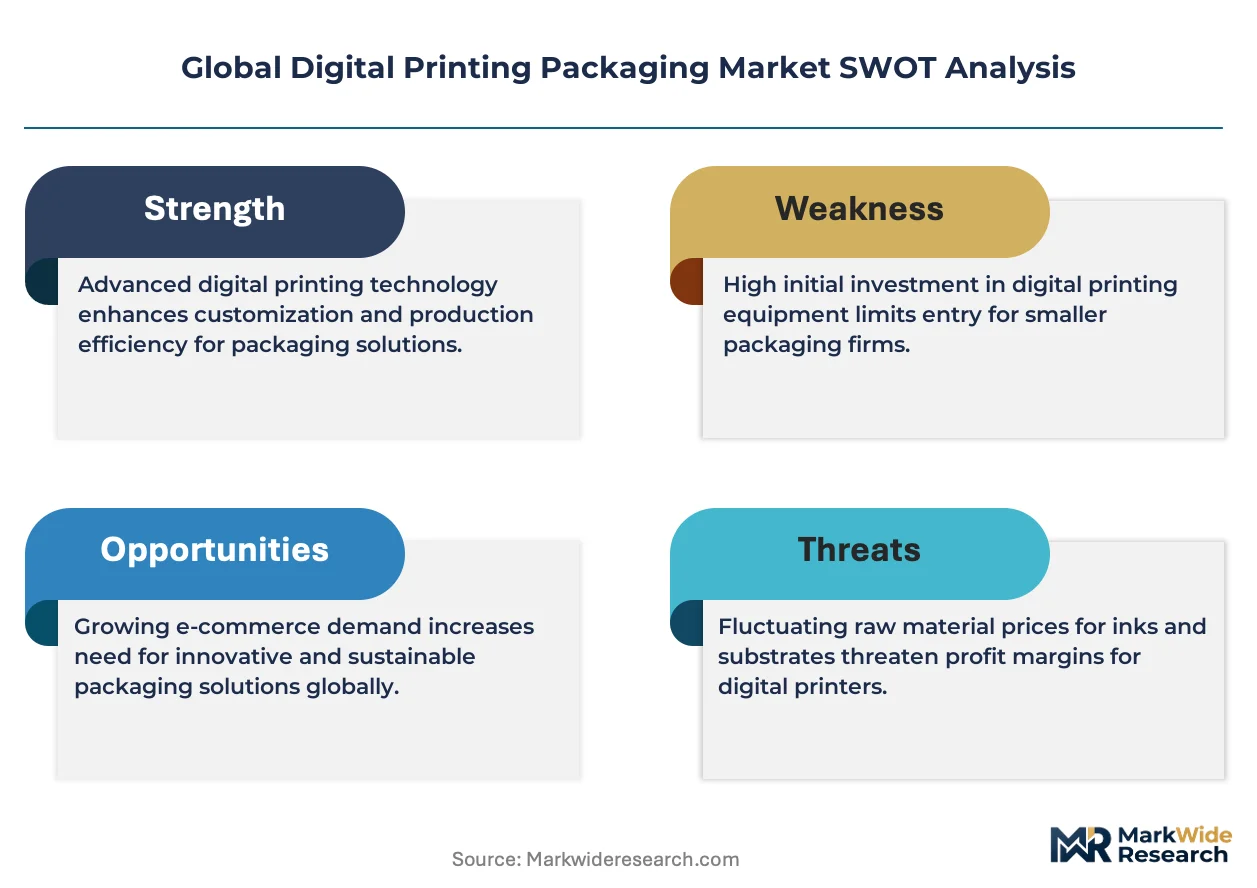
The market's central tension lies in balancing the push for mass personalization and rapid design cycles against the stringent regulatory frameworks governing materials and the rising costs of compliant consumables.
Growth Catalysts
- Inkjet Versatility:Inkjet technology's compatibility with diverse substrates like flexible films and folding cartons enables cost-effective customization for short production runs.
- Pharmaceutical Serialization:The need for scannable track-and-trace coding in the pharmaceuticals industry drives digital printing adoption for regulatory compliance.
- On-Demand Customization:The food and beverage sector uses short-run digital printing for rapid promotional campaigns, reducing waste from obsolete packaging.
Market Restraints
- High Consumable Costs:The price premium on specialized, compliant inks for digital presses, particularly for food-safe applications, constrains profitability for converters.
- Regulatory Friction:Food contact material regulations from the US FDA and EFSA create long, costly validation cycles for new ink formulations.
- Throughput Gaps:Digital press speeds often lag behind conventional methods like flexography, limiting cost-effectiveness for very high-volume, standardized production runs.
Strategic Opportunities
- Smart Packaging Integration:Digitally printing QR codes or NFC tags transforms packaging into a platform for supply chain tracking and consumer engagement.
- Sustainable Solutions:The EU Green Deal's push for recyclability creates demand for digitally printed solutions on mono-materials using eco-friendly inks.
- Adjacent Market Expansion:Inkjet versatility allows for expansion into industrial markets like direct-to-shape printing on rigid containers and durable goods labeling.
Industry Challenges
- High Capital Expenditure:The investment for industrial-scale digital presses is a major capital hurdle for converters accustomed to depreciated analog assets.
- Workflow Integration Complexity:Integrating digital front-ends and color management software with legacy production systems presents a significant operational challenge for converters.
- Supply Chain Fragmentation:A growing base of equipment suppliers from China complicates procurement and ensuring consistent quality of consumables across global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Printing Packaging Market |
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $73.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Folding Cartons, Labels, Rigid Boxes, Blister Packs Printing Technology: Inkjet, Electrophotography, Thermal, Digital UV, Dye Sublimation Application: Food & Beverages, Personal Care, Pharmaceuticals, Consumer Electronics, Automotive Components End User: Brand Owners, Packaging Manufacturers, Custom Printers, Advertising Agencies, Retailers |
| Companies Covered | HP Inc., Canon Inc., Xeikon N.V., Amcor plc, CCL Industries Inc., Mondi PLC, Huhtamaki Oyj, DS Smith plc, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Printing Packaging Market Strategic Shifts & Innovations
The convergence of sustainability mandates with mass customization capabilities is reshaping production economics. This shift forces a re-evaluation of the entire packaging value chain, from substrate selection to end-of-life management.
Hybrid printing systems combine digital technologies like inkjet with conventional methods such as flexography in a single line. Large-scale packaging converters are adopting these systems for folding cartons and flexible packaging applications. This technology is hybridizing production workflows, allowing companies to blend the cost-effectiveness of analog for static elements with digital's variability for codes and personalization.
European Union regulations under the Green Deal, particularly the Packaging and Packaging Waste Regulation (PPWR), are setting stringent targets for recyclability. This policy directly influences material choices, favoring mono-material structures and discouraging complex multi-layer packaging. Ink and substrate suppliers are now forced to validate their products for compatibility with established recycling streams, especially within the food and beverage segment.
A fundamental shift from forecast-driven bulk production to on-demand manufacturing is altering procurement dynamics between brands and converters. This change disrupts the traditional model reliant on long lead times for printing plates, favoring agile printers with robust digital workflows. This trend is most prominent in Germany's consumer goods sector, where frequent promotional cycles demand rapid packaging redesigns.
Global Digital Printing Packaging Market Segmentation
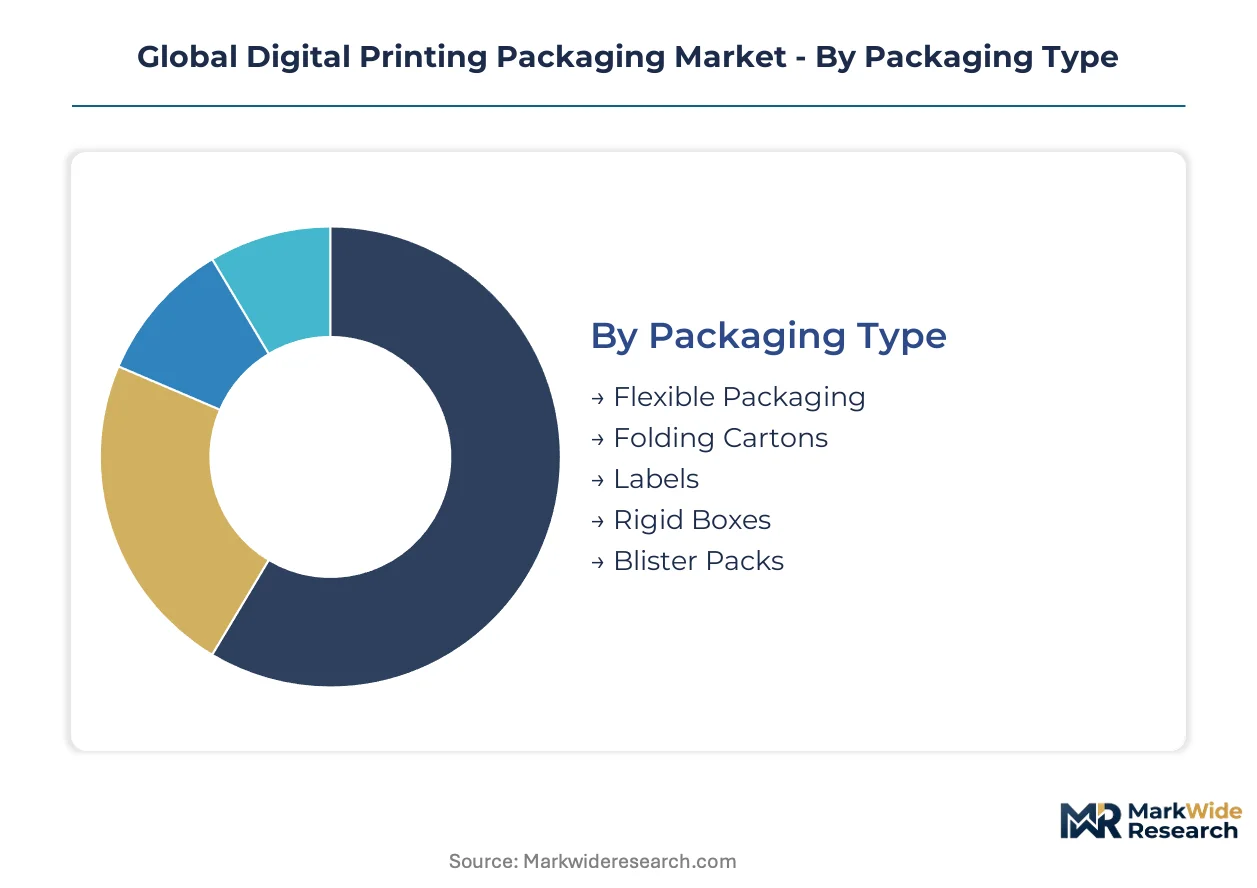
Segmentation provides a granular understanding of the Global Digital Printing Packaging Market, illuminating specific demand drivers and technological preferences. Analyzing different packaging types, printing technologies, applications, and end-users reveals distinct value propositions. This detailed breakdown helps stakeholders tailor strategies for market entry and product development.
Packaging Type:
After-sales service intensity for digital printing packaging often correlates with the complexity and regulatory demands associated with each packaging type.
- Flexible Packaging:This type includes pouches, bags, and wraps, often made from films or foils. Demand concentrates in the food and beverages sector for customized, short-run promotional packaging, driven by rapid design changes.
- Labels:Labels encompass self-adhesive, shrink sleeve, and in-mold varieties, providing critical product information and branding. The pharmaceuticals industry drives demand for scannable track-and-trace coding on labels to meet serialization regulations globally.
- Folding Cartons:These provide structural integrity and visual branding for products like cosmetics and electronics.
- Rigid Boxes:Used for premium products, rigid boxes offer enhanced protection and a luxury unboxing experience.
- Blister Packs:Blister packs secure individual items, primarily for pharmaceutical tablets and small consumer goods.
Flexible Packaging holds the largest share; momentum sits with Labels.
Printing Technology:
Application versatility significantly differentiates digital printing technologies, influencing their suitability for diverse substrates and production scales.
- Inkjet:Inkjet technology applies controlled micro-droplets of ink directly to substrates, enabling high-resolution graphics and variable data printing. Its compatibility with flexible films and folding cartons drives its expansion across food and beverage applications.
- Electrophotography:This technology uses electrically charged toner particles to create images, known for its high-quality color reproduction and speed. High-volume brand owners in consumer goods leverage electrophotography for consistent branding across diverse product lines.
- Thermal:Thermal printing uses heat to transfer ink, often for barcodes and simple text on labels and receipts.
- Digital UV:Digital UV curing technology hardens inks instantly with ultraviolet light, suitable for durable outdoor labels and direct-to-shape printing.
- Dye Sublimation:Dye sublimation creates vibrant, full-color images by heating dyes onto specialized transfer paper or direct to substrate.
Inkjet technology leads growth due to its versatility, while Electrophotography maintains a strong position in high-quality graphic applications.
Application:
Volume concentration across different applications dictates the scale and specific technological requirements for digital printing packaging solutions.
- Food & Beverages:This segment includes packaging for perishable goods, snacks, and drinks, requiring rapid design changes for promotions. The demand for seasonal and promotional packaging drives digital printing adoption to reduce waste from obsolete stock.
- Pharmaceuticals:Packaging for medicines and medical devices necessitates stringent regulatory compliance for serialization and tamper evidence. Regulatory mandates from the US FDA and European Medicines Agency (EMA) compel the use of digital printing for track-and-trace coding.
- Personal Care:This segment covers cosmetics, toiletries, and hygiene products, often requiring premium aesthetics and frequent design updates.
- Consumer Electronics:Packaging for devices like smartphones and laptops benefits from digital printing for quick-turnaround marketing campaigns and product differentiation.
- Automotive Components:This application involves packaging for spare parts, where durability and clear identification are paramount for supply chain management.
Food & Beverages consistently generates the highest demand, with Pharmaceuticals demonstrating significant expansion due to regulatory pressures.
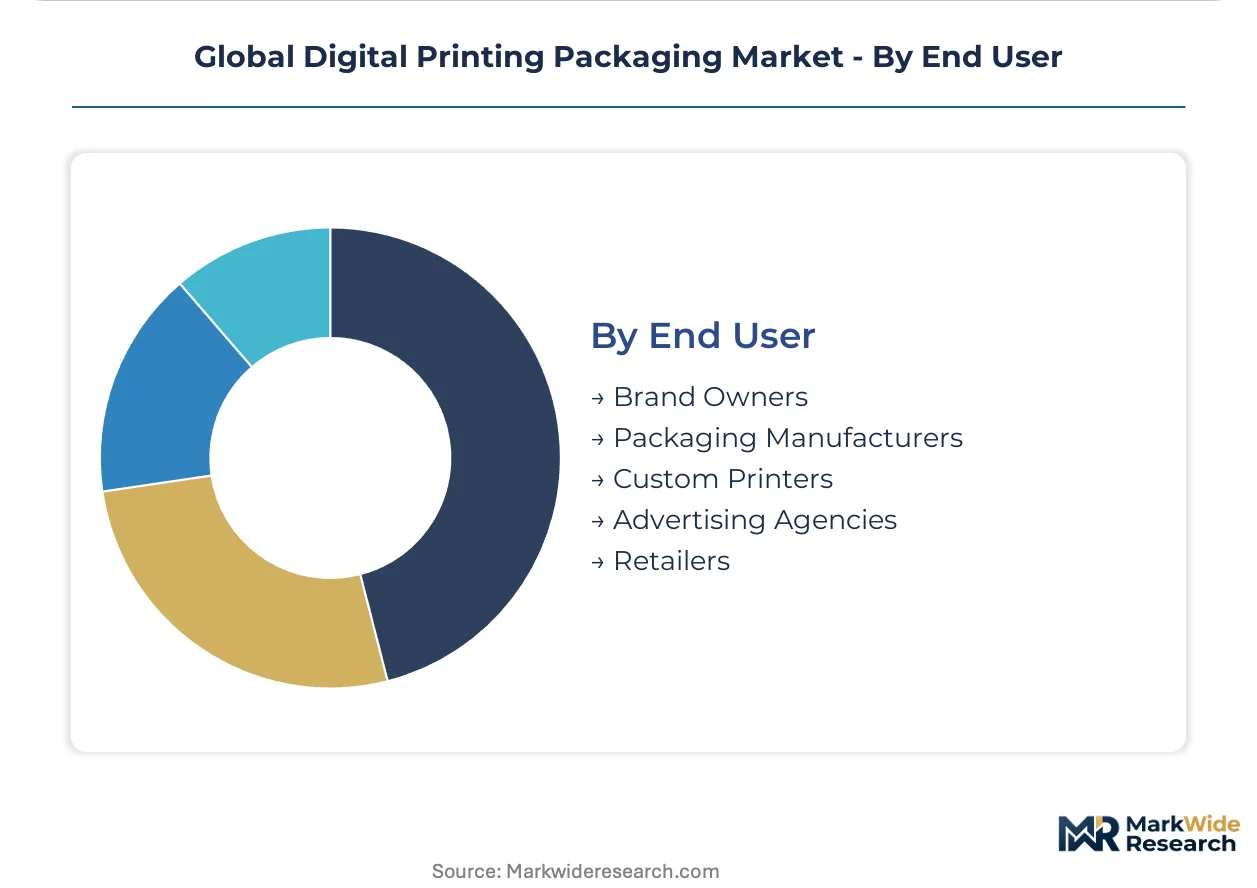
End User:
Procurement dynamics vary significantly among end-users, reflecting diverse needs for customization, speed, and regulatory adherence in digital printing.
- Brand Owners:These entities own the product and brand identity, driving demand for packaging that enhances consumer engagement and brand storytelling. They increasingly seek personalized and sustainable packaging solutions to differentiate products in competitive markets like Germany's consumer goods sector.
- Packaging Manufacturers:Converters and producers of packaging materials integrate digital presses into their operations to offer agile, short-run capabilities. They address the rising demand from brand owners for on-demand customization and rapid prototyping, often embedding digital presses within existing flexography lines.
- Custom Printers:These specialized print shops cater to niche markets requiring highly personalized or very short-run packaging orders.
- Advertising Agencies:Agencies utilize digital printing for packaging prototypes and promotional campaigns, valuing speed and design flexibility.
- Retailers:Retailers use digital printing for private label brands and in-store promotional packaging, focusing on cost-effectiveness and quick market response.
Brand Owners initiate most digital printing packaging projects, while Packaging Manufacturers execute the bulk of production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Union directives, particularly the Green Deal framework, significantly influence digital printing packaging adoption across the continent. These regulations drive demand for sustainable packaging materials and compliant ink formulations. This focus reshapes material selection and production processes for converters.
Germany
Germany's advanced manufacturing and consumer goods sectors prioritize packaging innovation and rapid design cycles. The EU's PPWR influences material choices and recyclability. The Rhine-Ruhr region, a major consumer goods hub, drives demand for agile digital printing solutions.
United States
The United States pharmaceuticals sector requires scannable track-and-trace coding for regulatory compliance. US FDA regulations govern ink formulations and material safety. The Northeast corridor, with its strong pharmaceutical presence, sees investment in digital printing for serialization.
Japan
Japan's demand for premium aesthetics in consumer electronics and frequent food promotions fuels digital printing. METI promotes advanced manufacturing and waste reduction initiatives. The Kanto region, including Tokyo, exhibits strong demand for high-resolution, on-demand packaging solutions.
China
China's expanded production capacity and vast e-commerce market drive significant digital printing adoption. GB standards for food safety and dual carbon goals influence material and ink choices. The Yangtze River Delta region, a manufacturing powerhouse, leads in integrating digital presses.
India
India's rapidly expanding consumer goods market and pharmaceutical sector boost digital printing demand. FSSAI sets guidelines for packaging materials, while CDSCO mandates serialization. Maharashtra, with its large industrial base, shows strong adoption for customized and compliant packaging.
Global Digital Printing Packaging Market Key Industry Players
Technology providers and packaging specialists split the market for digital printing solutions, forming distinct competitive tiers. The supply base fragments due to expanded production capacity, particularly from China, impacting equipment and consumables. High-volume brand owners seek integrated solutions, while converters focus on agile, short-run capabilities for diverse end-users. Competitive moves include technology licensing, strategic partnerships, capacity expansion, and portfolio diversification to meet evolving demand.
Among technology providers, HP Inc. and Xeikon N.V. represent global leaders in digital press manufacturing, offering diverse inkjet and electrophotography solutions for various substrates. Amcor plc, a prominent packaging specialist, exemplifies converters embedding digital presses within their operations to support personalized, on-demand packaging for brand owners. These entities occupy positions across the value chain, from equipment and software provision to integrated packaging production, catering to both high-volume and niche requirements. Their strategies often involve expanding digital capabilities to address rising demand for customization and sustainability.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Xeikon N.V. |
| Amcor plc |
| CCL Industries Inc. |
| Mondi PLC |
| Huhtamaki Oyj |
| DS Smith plc |
| WestRock Company |
Cost & Logistics Intelligence
Expanded production capacity in China creates overcapacity for digital printing equipment, driving down equipment prices and influencing converter investment decisions and their pricing posture for packaged goods.
Pricing Analysis
Regional price disparities exist, with premium pricing in Western Europe for compliant food-grade inks compared to Asian markets. Per-unit transactional pricing dominates for short-run, customized packaging orders. Price differentiation stems from customization complexity and the level of regulatory compliance required for food contact materials. Pricing softness in standardized digital printing segments reflects increased competition among converters. Brand owners in consumer goods exhibit high price sensitivity for promotional packaging, while pharmaceutical clients prioritize compliance over cost.
Supply Chain Analysis
Extended payment terms for digital press equipment shape supplier-converter relationships, influencing capital expenditure cycles. Geographic supply concentration for digital printing equipment centers on China, Germany, and Japan. Raw material dependencies include specialized polymers for flexible substrates and pigments for compliant ink formulations. Single-source vulnerability for key ink components represents a structural risk. Distribution runs through a network of equipment manufacturers and their regional distributors, alongside direct sales channels for major consumables suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital printing packaging market is experiencing a shift in buyer power, driven by the consolidation of large brand owners and packaging manufacturers demanding integrated solutions.
For Market Incumbents:Insulate existing client relationships by investing in hybrid printing systems that blend analog efficiency with digital flexibility. Develop advanced color management software to ensure brand consistency across diverse substrates and digital presses. This strategy counters the threat from specialized digital-only entrants and addresses evolving brand owner demands for rapid design cycles. Certification investment in sustainable ink formulations strengthens market position against regulatory shifts.
For New Entrants and Emerging Players:Pursue niche applications requiring high customization or rapid prototyping, such as limited-edition consumer electronics packaging. The most penetrable segment remains short-run promotional packaging for small and medium-sized food and beverage brands. A go-to-market angle focused on speed-to-market and design agility offers a strong competitive advantage. Offer subscription-based design and print services to reduce upfront costs for smaller clients.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among software providers offering digital front-end solutions and specialized ink suppliers with proprietary compliant formulations. Long-term viability rests on companies that can integrate digital printing capabilities with sustainable material science and smart packaging features. An acquisition target archetype includes mid-sized converters specializing in flexible packaging with established digital press infrastructure. The signal to watch is the increasing adoption rate of mono-material substrates in food packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Printing Systems | Combines analog efficiency with digital flexibility to meet diverse production needs for packaging manufacturers. |
| Develop Sustainable Ink Formulations | Addresses EU Green Deal regulations and brand owner demand for eco-friendly packaging solutions. |
| Expand Direct-to-Shape Printing | Opens new market segments in industrial and rigid container applications for technology providers. |
| Acquire Niche Digital Converters | Provides access to specialized expertise and customer bases for larger packaging manufacturers. |
| Integrate Smart Packaging Features | Enhances consumer engagement and supply chain traceability for brand owners. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This study incorporates insights from packaging manufacturers, brand owners, digital press engineers, and regulatory affairs specialists. Secondary data sources include company annual reports, industry association publications, government regulatory filings, and trade statistics. Bottom-up and top-down triangulation ensures data consistency across the analysis.
The calibration approach involves modeling market growth based on technology adoption curves and application-specific demand drivers across the analysis window. Segmentation dimensions modeled include packaging type, printing technology, application, and end-user, with an additional focus on regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data analysis and projected market shifts. Key forecast inputs include pharmaceutical serialization mandates and food and beverage promotional cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology providers or large brand owners would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and material cost trends. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Label Printers Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Label Printing Software Market
Packaging Printing
Flex Banner Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
North America Print Label Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Laser Coders Market
Packaging Printing
Soft Signage Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Stack Flexo Printing Press Market