
 Pre-Press for Packaging Market | 2026-2036
Pre-Press for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Press for Packaging Market Analysis
Pre-press file preparation and color separation revenue is narrowing as packaging converters internalize basic trapping and imposition workflows. Esko-Graphics leverages its integrated suite of structural design and pre-press automation tools to dominate brand-owner direct engagements. Heidelberger Druckmaschinen anchors European equipment-centric pre-press service networks through its Prinect workflow architecture. AGFA-Gevaert differentiates via inkjet proofing systems and advanced flexo plate chemistry for narrow-web label converters.
Pre-press for packaging encompasses the technical processes of file optimization, color separation, plate or cylinder preparation, and proofing that transform brand artwork into production-ready formats for printing presses. These operations require precise dot gain compensation curves, minimum 175 lpi screening thresholds for high-end cosmetic work, and substrate-specific ink prediction models to ensure press-side color fidelity. Flexography pre-press leads volume throughput across corrugated and flexible film applications due to its cost efficiency on long runs, while digital printing pre-press represents the fastest-expanding segment as converters adopt variable-data workflows for personalized packaging campaigns. Color management technology commands premium margins because brand owners mandate delta-E tolerances below 2.0 across multi-site production networks.
The US FDA enforces strict label accuracy requirements for food and pharmaceutical packaging that elevate pre-press proofing rigor and traceability documentation. The EU F-Gas Regulation and REACH chemical restrictions are reshaping plate-washout solvent choices and proofing substrate specifications across European pre-press operations. ISO 12647 color standards govern cross-border print consistency, creating compliance-driven demand for certified color management systems. Stakeholders must evaluate whether to build captive pre-press capabilities or outsource to specialized providers as run lengths fragment and brand-owner quality specifications tighten.
Market Dynamics
Run-length fragmentation across corrugated and flexible packaging is compressing pre-press service economics, forcing converters to choose between captive digitization and specialized outsourcing partnerships.
Growth Catalysts
- EU Green Deal packaging mandates:Waste reduction targets and chemical intensity caps are accelerating migration from solvent-based plate-washout systems to water-washable flexo plate technologies across European converter networks.
- Food packaging converters:North American and European food brands are mandating delta-E tolerances below 2.0 across multi-site production, creating compliance-driven demand for certified color management systems and proofing rigor.
- Digital workflow adoption:Variable-data capabilities for personalized packaging campaigns are expanding pre-press service scope beyond static file preparation into data-driven imposition and version control automation.
Market Restraints
- Photopolymer plate material costs:Raw material volatility in photopolymer resins and plate substrates creates margin pressure for narrow-web label converters operating on fixed-fee pre-press contracts.
- Specialized talent concentration:Skilled flexo pre-press technicians and color scientists cluster in Germany, creating supply bottlenecks for converters in peripheral European markets and North American regions.
- REACH chemical restrictions:ECHA substance evaluations are limiting traditional plate-washout solvent options, forcing costly formulation changes and extended qualification timelines for proofing substrate suppliers.
Strategic Opportunities
- India packaging growth:FSSAI-mandated label accuracy requirements and expanding domestic food processing capacity are creating demand for pre-press digitization among corrugated converters in Maharashtra and Gujarat.
- Extended color gamut (ECG) workflows:Convergence of fixed palette printing with spectral color prediction models enables brand owners to reduce spot color inventories while maintaining shelf impact across flexible film applications.
- Brand-owner direct engagement:Packaging converters are bypassing traditional trade shops to establish captive pre-press capabilities, creating white space for workflow software providers to sell direct-to-converter licensing models.
Industry Challenges
- ISO 12647-6 certification timelines:Flexographic converters face 12-18 month qualification periods for narrow-web and wide-web process standard compliance, delaying contract awards from multinational brand owners.
- Legacy MIS integration:Pre-press automation platforms require costly middleware development to connect with existing converter ERP systems, extending payback periods for digitization investments.
- Dot gain compensation expertise:Shortage of technicians capable of calibrating substrate-specific ink prediction models creates quality variability across high-end cosmetic and pharmaceutical packaging work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Press for Packaging Market |
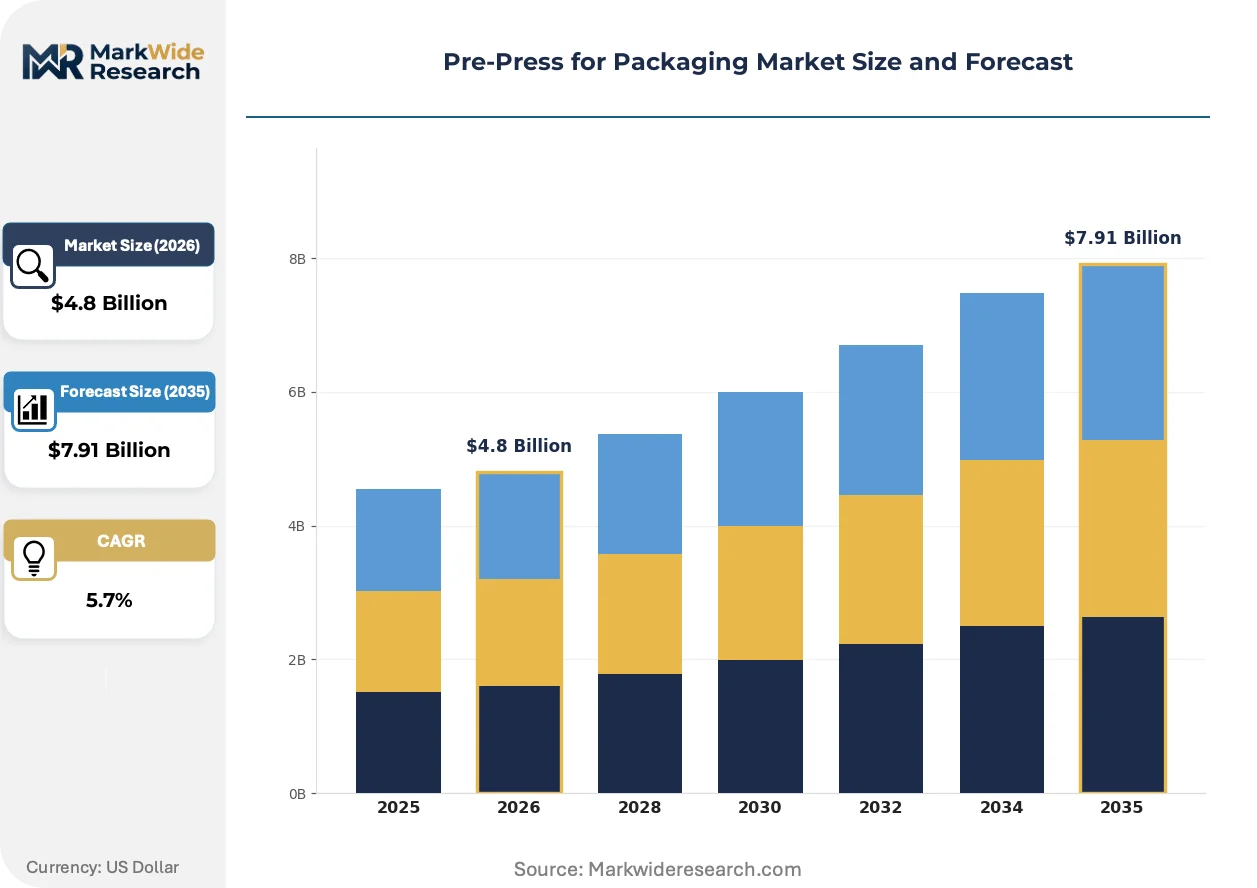
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printing, Flexography, Offset Printing, Gravure Application: Food Packaging, Beverage Packaging, Cosmetic Packaging, Pharmaceutical Packaging Technology: Pre-Press Software, Workflow Management, Color Management, Proofing Systems End User: Packaging Manufacturers, Brand Owners, Printing Services, Design Agencies |
| Companies Covered | Sonoco-Trident, Propelis Group, AGFA-Gevaert, Reproflex3 Ltd, Miller Graphics AB, Esko-Graphics, Janoschka AG, SPGPrints Group, Heidelberger Druckmaschinen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Press for Packaging Market Emerging Trajectories
Pre-press operations are pivoting from file preparation services toward integrated color science and automation platforms that compress cycle times and reduce press-side makeready waste.
Extended gamut screening technology is migrating from conventional CMYK plus spot color workflows toward fixed seven-color palette systems. Mid-market corrugated converters in the United States are adopting ECG at accelerating pace to eliminate spot color changeovers. This migration from spot-dependent pre-press is reducing plate inventory costs and enabling shorter run economics across food and beverage packaging.
REACH F-Gas Regulation restrictions on solvent-based plate processing are reshaping equipment investment patterns across European pre-press operations. Thermal plate imaging and water-washable chemistry are displacing traditional UV solvent workflows in Germany and Benelux converter networks. Narrow-web label specialists face the steepest compliance costs, driving consolidation toward service providers with captive thermal imaging capacity.
Brand-owner quality audits are compressing pre-press proofing cycles from weekly batch reviews to same-day digital approvals. Cosmetic and pharmaceutical packaging converters in France and Switzerland are unbundling physical proofing from file preparation services, adopting remote soft-proofing workflows with calibrated display certification. This behavioral shift is reducing logistics costs and accelerating time-to-market for seasonal packaging campaigns.
Pre-Press for Packaging Market Segmentation
Pre-press service providers configure their technology portfolios around distinct print process economics and brand-owner compliance requirements. Each segmentation dimension reflects different margin structures, equipment investment cycles, and customer relationship intensities.
Product Type:
After-sales service intensity varies sharply across print processes, with plate-based technologies demanding ongoing calibration support and digital workflows requiring software subscription maintenance.
- Flexography:Photopolymer plate imaging and dot gain compensation dominate corrugated and flexible film applications. German converter networks in Baden-Württemberg and Bavaria anchor European flexo pre-press capacity, driven by food packaging brands mandating delta-E tolerances below 2.0 across multi-site production.
- Digital Printing:Variable-data imposition and version control automation enable personalized packaging campaigns. Demand concentrates among North American beverage and cosmetic converters seeking shorter run economics without plate changeover costs.
- Offset Printing:High-resolution screening and substrate-specific ink prediction models serve premium cosmetic and pharmaceutical folding carton work.
- Gravure:Cylinder engraving and electro-mechanical calibration support long-run flexible packaging for snack foods and confectionery.
Flexography holds the largest share; momentum sits with digital printing.
Application:
Cost tier stratification separates commodity food work from premium cosmetic and pharmaceutical segments requiring extended proofing cycles and regulatory documentation.
- Food Packaging:FSSAI-mandated label accuracy requirements in India and FDA traceability rules in the US elevate proofing rigor and file versioning discipline. Maharashtra and Gujarat corrugated converters are digitizing pre-press workflows to meet domestic food processing expansion.
- Pharmaceutical Packaging:FDA serialization mandates and EU Falsified Medicines Directive compliance demand tamper-evident artwork verification and audit trail documentation. Swiss and French converters face compressed approval cycles for same-day digital proofing.
- Beverage Packaging:Shrink sleeve and label converters manage high SKU counts with automated imposition and color standardization across multiple production sites.
- Cosmetic Packaging:Minimum 175 lpi screening thresholds and metallic ink prediction models support shelf-impact requirements for luxury brands.
Food packaging commands the highest volume; pharmaceutical packaging climbs the fastest on compliance-driven premiumization.
Technology:
Volume concentration favors integrated workflow platforms over point solutions, as converters seek to compress cycle times from file receipt to press-ready output.
- Color Management:Spectral color prediction models and ISO 12647-6 certification systems enable brand owners to reduce spot color inventories while maintaining consistency. REACH chemical restrictions and F-Gas Regulation limits are reshaping proofing substrate specifications across European operations.
- Pre-Press Software:Structural design integration and automated trapping reduce manual intervention for corrugated converters facing shorter run requirements.
- Workflow Management:ERP middleware connects pre-press automation to converter planning systems, though legacy MIS integration extends payback periods.
- Proofing Systems:Inkjet proofing and remote soft-proofing with calibrated display certification displace physical proof logistics for seasonal campaigns.
Color management captures premium margins; pre-press software is expanding most quickly through direct-to-converter licensing models.
End User:
Customer type determines contract structure, with packaging manufacturers seeking captive capabilities and brand owners demanding direct quality audit access.
- Packaging Manufacturers:Corrugated and flexible film converters in Germany and the US are internalizing basic trapping and imposition to reduce per-job costs. Thermal plate imaging investments displace outsourced solvent-based plate processing.
- Brand Owners:Multinational food and cosmetic companies mandate certified color management systems and conduct direct quality audits, bypassing traditional trade shop relationships.
- Printing Services:Narrow-web label specialists face steepest REACH compliance costs, driving consolidation toward providers with captive thermal imaging capacity.
- Design Agencies:Structural design and artwork origination services require integration with converter pre-press platforms for production feasibility validation.
Packaging manufacturers represent the deepest installed base; brand owner direct engagement shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany pay premium rates for certified color management while Indian corrugated specialists in Maharashtra and Gujarat absorb digitization costs to capture FSSAI-compliant food packaging contracts. Price elasticity varies sharply by regulatory exposure and brand-owner audit intensity.
Germany
Baden-Württemberg and Bavaria host dense clusters of flexo pre-press specialists serving food brands mandating delta-E tolerances below 2.0. The EU F-Gas Regulation and REACH chemical restrictions are accelerating thermal plate imaging adoption across converter networks. Heidelberg anchors equipment-centric service networks through its Prinect workflow architecture.
United States
FDA label accuracy requirements for food and pharmaceutical packaging elevate proofing rigor and traceability documentation demands. Mid-market corrugated converters adopt extended color gamut workflows to eliminate spot color changeovers. The Pacific Northwest and Southeast regions concentrate beverage packaging pre-press digitization for shorter run economics.
India
FSSAI-mandated label accuracy requirements and expanding domestic food processing capacity drive pre-press digitization among corrugated converters. Maharashtra and Gujarat industrial clusters absorb workflow automation costs to qualify for multinational brand owner contracts. The PLI scheme for food processing indirectly supports packaging quality infrastructure investment.
Switzerland
Swissmedic pharmaceutical serialization mandates and EU Falsified Medicines Directive compliance compress proofing cycles toward same-day digital approvals. Cosmetic and pharmaceutical converters in Basel and Zurich unbundle physical proofing from file preparation services. Remote soft-proofing with calibrated display certification reduces logistics costs for seasonal campaigns.
France
ANSM pharmaceutical packaging regulations and luxury cosmetic brand audits demand minimum 175 lpi screening thresholds and metallic ink prediction models. The Île-de-France region concentrates high-end pre-press capacity serving LVMH and L'Oréal supply chains. ECHA substance evaluations are reshaping proofing substrate specifications across converter operations.
Pre-Press for Packaging Market Vendor Landscape
Capability concentration sits with specialized pre-press software and color science providers; scale advantage sits with diversified printing equipment manufacturers extending into workflow automation. The market structures around three archetypes: integrated workflow platform vendors, niche flexo plate chemistry specialists, and equipment-centric service network operators. Consolidation pressures concentrate among narrow-web label specialists facing REACH compliance costs. Dominant competitive moves include direct-to-converter licensing bypassing traditional trade shops and thermal imaging capacity investments displacing solvent-based plate processing.
Among European-anchored specialists, Esko-Graphics and Heidelberger Druckmaschinen occupy positions reflecting divergent strategic bets on software-centric versus equipment-centric pre-press service models. AGFA-Gevaert represents the chemistry and proofing systems archetype navigating regulatory constraints on traditional plate-washout solvents. These three companies exemplify how geographic clustering in Germany and Benelux shapes competitive positioning around EU Green Deal compliance trajectories and brand-owner quality audit proximity.
| Leading Market Players |
|---|
| Sonoco-Trident |
| Propelis Group |
| AGFA-Gevaert |
| Reproflex3 Ltd |
| Miller Graphics AB |
| Esko-Graphics |
| Janoschka AG |
| SPGPrints Group |
| Heidelberger Druckmaschinen |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's volatile container rates compress margin structures for photopolymer plate suppliers serving German converter networks, amplifying price differentiation between thermal imaging specialists and solvent-dependent operators facing REACH compliance penalties.
Pricing Analysis
After-sales service contracts for plate calibration and color profile maintenance generate recurring revenue streams that exceed initial equipment margins for workflow platform vendors. Three-tier pricing structure across premium certification, standard compliance, and economy transactional tiers separates ISO 12647-6 certified providers from uncertified trade shops. Cost compression in narrow-web label pre-press is intensifying because photopolymer resin volatility forces fixed-fee contract renegotiations. Small corrugated converters in peripheral European markets exhibit highest price sensitivity; multinational brand owners in cosmetics and pharmaceuticals demonstrate lowest sensitivity due to delta-E tolerance mandates.
Supply Chain Analysis
Tariff exposure between Germany and China for thermal imaging equipment dominates supply chain risk planning for converter networks migrating from solvent-based workflows. Manufacturing concentration centers on Germany, the United States, and Japan for pre-press automation platforms and color management systems. Raw material dependencies include photopolymer resins from Belgium, proofing substrates from the Netherlands, and thermal plate substrates from Japan. Single-source vulnerability in flexo plate chemistry creates qualification bottlenecks when REACH substance evaluations force formulation changes. Distribution runs through converter-direct licensing models that displace traditional trade shop intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical talent scarcity for dot gain compensation and substrate-specific ink prediction models constrains quality consistency across high-end cosmetic and pharmaceutical packaging segments, creating asymmetric returns for capability holders.
For Market Incumbents: Entrench market position by acquiring captive thermal imaging capacity in Baden-Württemberg to preempt REACH-driven solvent workflow obsolescence. Deepen software subscription attach rates among corrugated converters through ERP middleware integration that extends switching costs. Defend against emerging cloud-native workflow entrants by embedding structural design tools into pre-press automation suites.
For New Entrants and Emerging Players: Maharashtra and Gujarat's corrugated converter clusters present underpenetrated demand for FSSAI-compliant digitization services as domestic food processing capacity expands. Target mid-tier flexible film converters in India with remote soft-proofing offerings that bypass physical logistics infrastructure. Establish go-to-market partnerships with regional equipment distributors lacking captive color science capabilities.
For Investors and Strategic Acquirers: Niche flexo plate chemistry specialists with water-washable formulations and thermal imaging assets represent priority acquisition targets given regulatory tailwinds. Long-term viability hinges on EU Green Deal compliance trajectory and brand-owner direct engagement models displacing trade shop relationships. Monitor ECHA substance evaluation timelines as inflection indicators for accelerated thermal imaging adoption across European converter networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Imaging Capacity Buildout | REACH and F-Gas Regulation restrictions are accelerating displacement of solvent-based plate processing across German converter networks. |
| Direct-to-Converter Software Licensing | Brand-owner quality audits are bypassing traditional trade shops, creating white space for workflow platform vendors. |
| Extended Color Gamut Workflow Deployment | Fixed seven-color palette systems enable corrugated converters to eliminate spot color changeover costs and capture shorter run economics. |
| Remote Soft-Proofing Infrastructure | Swiss and French cosmetic converters are unbundling physical proofing to compress seasonal campaign approval cycles. |
| ERP Middleware Integration | Legacy MIS connectivity requirements extend digitization payback periods, creating defensive moats for integrated platform providers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, equipment manufacturer disclosures, and converter association datasets. Interviews with flexo pre-press technicians, color scientists, packaging converter operations directors, brand owner quality auditors, and workflow software product managers informed demand-side dynamics. Secondary validation drew from ECHA substance evaluations, FDA label accuracy guidance, ISO 12647 certification records, and EU Green Deal implementation documents. Bottom-up triangulation across converter capacity investments and top-down reconciliation against equipment shipment data anchored market sizing.
Forecast inputs span print process technology migration curves, regulatory compliance timelines, and brand-owner quality specification trajectories across the analysis window. Segmentation modeling incorporates print process economics, application-specific compliance requirements, technology platform adoption patterns, and end-user relationship structures. CAGRs derive from equipment replacement cycles, software subscription renewal rates, and service contract expansion patterns. Industry-specific inputs include photopolymer plate volume trends and thermal imaging capacity installation data.
Practitioners should monitor ECHA substance evaluation announcements, FSSAI enforcement intensity in Maharashtra and Gujarat, and brand-owner direct engagement announcements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Laser Coders Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Label Printers Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
North America Print Label Market