
 Stamping Foils Market | 2026-2036
Stamping Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Stamping Foils Market Analytics
Polyester film substrates is recalibrating cost structures across the stamping foils value chain as converters seek thinner gauges with equivalent barrier performance. LEONHARD KURZ leverages its captive coating technology to sustain margin control across holographic and metallized product lines. API anchors European supply through specialized security foil production for tax stamp and authentication programs. Henan Foils dominates volume manufacturing in Asia with integrated aluminum metallization and lacquering capabilities.
Stamping foils are multilayer thin-film products comprising a carrier substrate, release layer, lacquer or image layer, and metallized or pigmented decorative coating, typically applied at 12-25 microns total thickness through heated die pressure or UV-activated transfer. Their primary purpose is to impart metallic, holographic, or pigment effects onto paper, plastic, or composite surfaces in high-speed converting operations. Hot stamping foils retains the largest value share due to entrenched infrastructure in tobacco and cosmetics packaging, while security foils generates the fastest expansion as pharmaceutical serialization mandates spread across regulated supply chains. Cold foiling captures growing interest among label converters seeking to eliminate tooling costs for short-run variable data jobs.
EMA pharmaceutical packaging guidelines, EU Packaging and Packaging Waste Directive recyclability targets, and FDA 21 CFR indirect food additive regulations collectively shape substrate selection, adhesive chemistry, and migration testing protocols for suppliers serving regulated end uses. REACH compliance in Europe and evolving state-level extended producer responsibility frameworks in the United States are forcing reformulation investments that favor suppliers with in-house analytical and regulatory affairs capabilities. Stakeholders must monitor accelerating consolidation among European masterbatch and coating resin suppliers, as captive raw material access increasingly separates profitable participants from price-takers in security and pharmaceutical-grade foil segments.
Market Dynamics
Pharmaceutical serialization mandates across regulated supply chains are compressing qualification timelines for security-grade foil substrates while forcing converters to maintain dual inventory lanes for compliant and non-compliant formulations.
Growth Catalysts
- EMA pharmaceutical packaging guidelines:Tamper-evident requirements for prescription drug packaging are expanding foil adoption across European serialization programs.
- Cold foiling technology:Label converters are eliminating heated die tooling costs for short-run variable data applications in cosmetics and premium spirits.
- Germany:Dense clusters of specialty printing houses and captive R&D operations sustain demand concentration for holographic and metallized product lines.
Market Restraints
- Aluminum price volatility:Metallized layer input costs fluctuate with LME pricing, compressing converter margins on fixed-price contracts.
- European coating resin consolidation:Captive raw material access among consolidated masterbatch suppliers limits negotiating leverage for independent foil manufacturers.
- REACH compliance friction:Reformulation investments for lower-VOC release layers extend product development cycles by 8-14 months.
Strategic Opportunities
- India:Pharmaceutical packaging localization under PLI scheme incentives creates demand for tax stamp and authentication foil production.
- Recyclable carrier substrates:EU Packaging and Packaging Waste Directive recyclability targets favor suppliers with in-house substrate development capabilities.
- UV-activated transfer systems:Convergence of digital printing and cold foiling enables on-demand metallization without tooling for personalized packaging runs.
Industry Challenges
- Migration testing protocols:FDA 21 CFR indirect food additive regulations and EFSA compliance requirements demand specialized analytical capabilities that smaller converters lack.
- Legacy hot stamping infrastructure:Tobacco and cosmetics packaging lines require capital-intensive retooling to accommodate thinner gauge polyester substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stamping Foils Market |
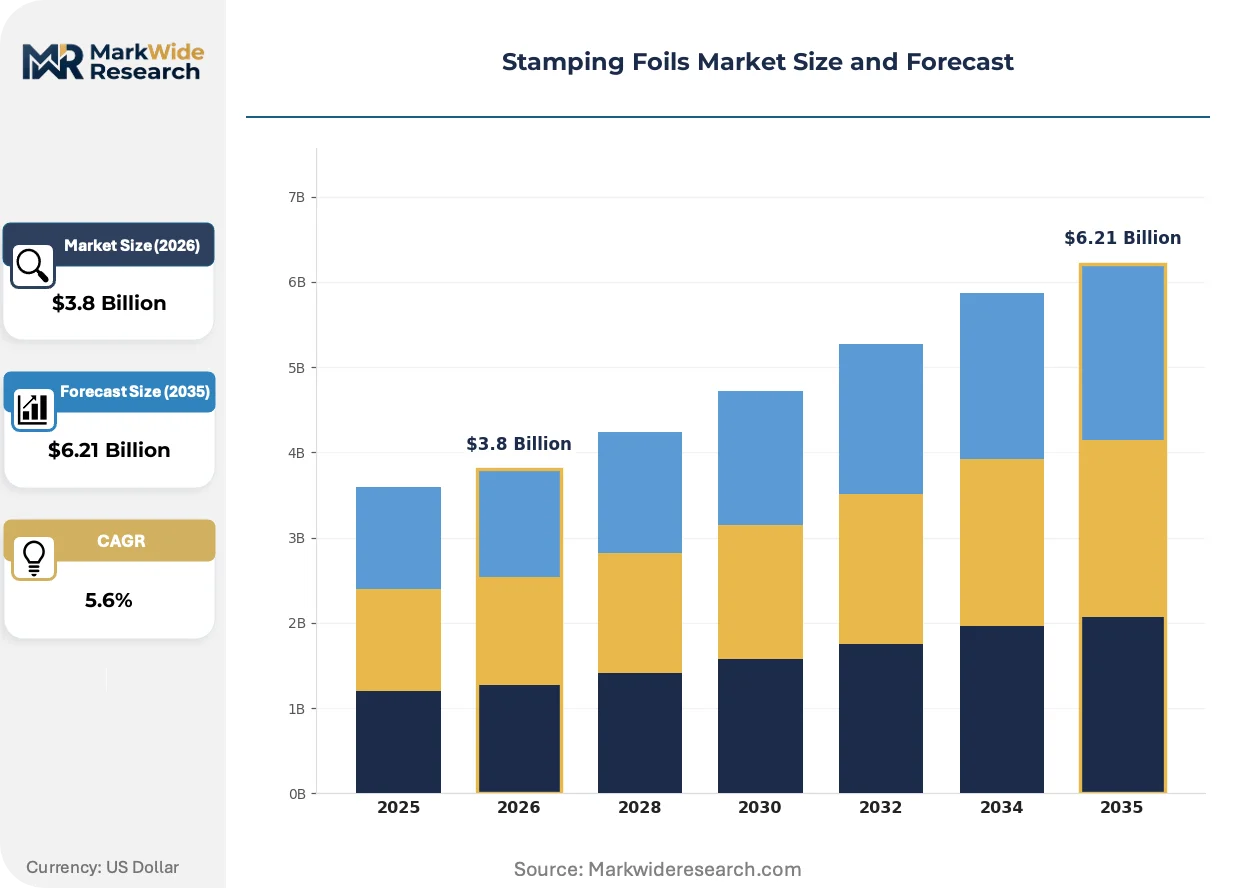
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamping Foils, Cold Foiling, Transfer Foils, Security Foils Application: Packaging, Labeling, Advertising, Decorative Printing End User: Consumer Goods, Automotive Parts, Electronics, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | LEONHARD KURZ, API, CFC International, Crown Roll Leaf, UNIVACCO Foils Corporation, ITW Foils, Foilco Limited, Henan Foils, Nakai Industrial Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stamping Foils Market Evolving Landscape
Material science advances and regulatory chemistry constraints are simultaneously enabling thinner functional layers while complicating qualification pathways for next-generation stamping foil architectures.
Nano-structured release coatings are absorbing solvent-based formulation share as converters face VOC emission thresholds under REACH and state-level air quality regulations. Pharmaceutical label printers in Germany and Switzerland are qualifying these water-based systems for high-speed serialization lines. The technology is absorbing margin pressure from environmental compliance costs while extending product development timelines.
EU F-Gas Regulation phase-down schedules are accelerating investment in non-fluorinated barrier technologies for carrier substrates. Metallized layer protection now relies on hybrid organic-inorganic coatings rather than perfluorinated chemistries. Security foil segments serving tax stamp applications are absorbing the steepest cost increases as barrier performance specifications tighten.
Brand owners are consolidating approved supplier lists to reduce qualification overhead across multi-site packaging operations. Converters serving multinational cosmetics and spirits accounts face compressed switching cycles as procurement centralizes specifications. This concentration is most visible in North American and Western European markets where three-tier supplier accreditation now governs foil sourcing decisions.
Stamping Foils Market Segmentation
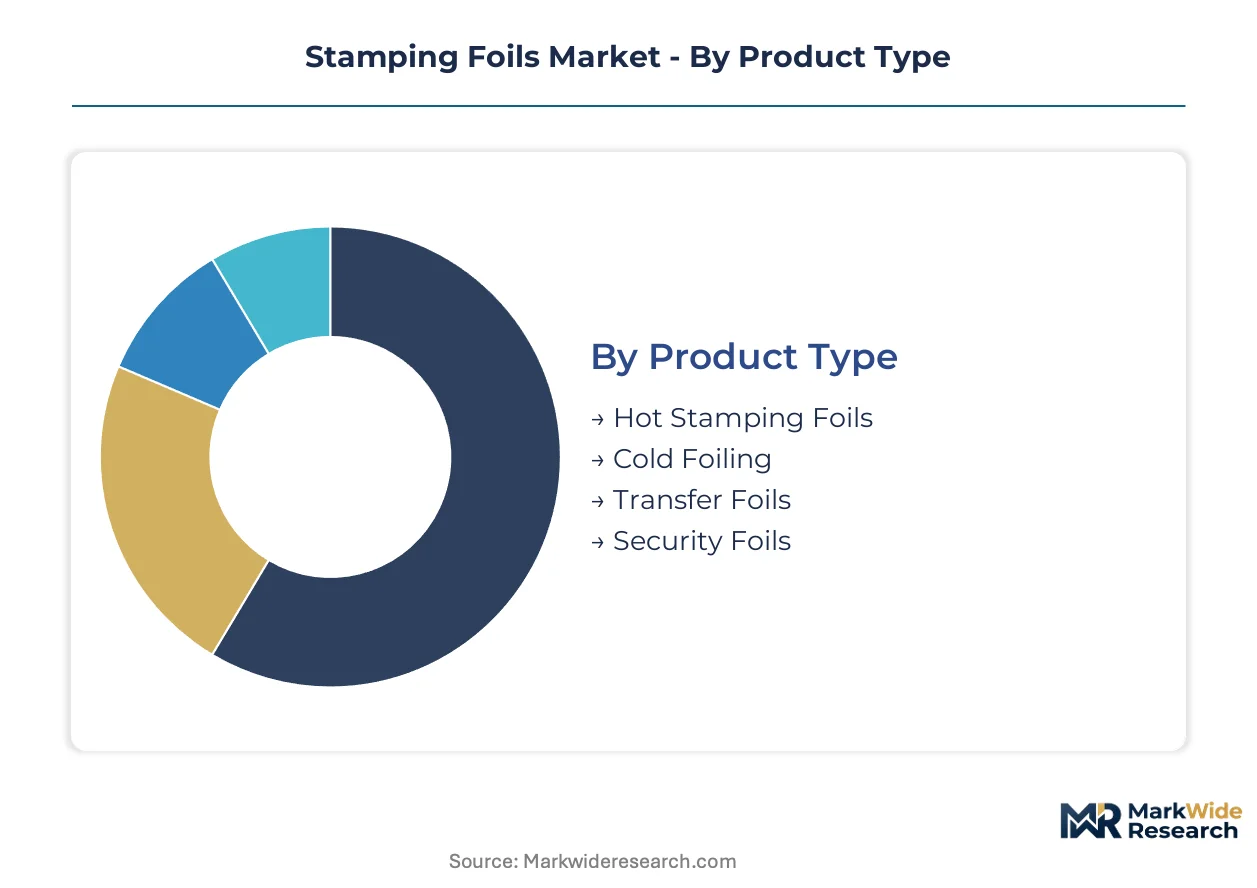
Stamping foil buyers segment procurement decisions across four distinct axes: process technology, surface application, downstream industry, and supply chain access. Each dimension carries different qualification burdens, volume thresholds, and margin profiles that reshape competitive positioning among suppliers.
Product Type:
Cost tier separates buyers in this category, with capital intensity and tooling requirements determining converter preferences.
- Hot Stamping Foils:Multi-layer constructions with heat-activated release layers dominate tobacco and cosmetics packaging through established heated die infrastructure. German specialty printing houses sustain demand concentration for metallized and holographic variants amid entrenched production lines.
- Security Foils:Serialized authentication layers with tamper-evident features serve pharmaceutical tax stamp programs under EMA serialization mandates. Demand concentrates in European serialization lanes where qualification timelines compress supplier selection.
- Cold Foiling:UV-activated adhesive systems eliminate heated tooling for short-run label converters serving premium spirits and cosmetics.
- Transfer Foils:Carrier-stripped decorative layers enable complex three-dimensional surface applications in automotive interior trim.
Volume sits with hot stamping foils; growth tilts toward security foils.
Application:
Application maturity determines whether buyers prioritize barrier performance or aesthetic differentiation.
- Packaging:Primary and secondary container decoration absorbs the majority of metallized and pigmented foil throughput. Pharmaceutical blister packs and folding cartons drive specification tightening under FDA 21 CFR and EFSA migration protocols.
- Labeling:Pressure-sensitive and wet-glue label stocks require thinner gauge polyester substrates with equivalent barrier performance. Converters in Switzerland and Germany qualify nano-structured release coatings for high-speed serialization lines.
- Advertising:Point-of-sale displays and promotional materials favor cold foiling for variable data personalization without tooling investment.
- Decorative Printing:Book covers, greeting cards, and specialty publications sustain demand for premium holographic effects.
Revenue concentrates in packaging; labeling expands most quickly under pharmaceutical serialization pressure.
End User:
Regulatory exposure separates buyers, with migration testing requirements and authentication mandates reshaping supplier relationships.
- Pharmaceuticals:Blister lidding and folding carton applications demand specialized barrier properties and tamper-evident features under EMA guidelines. Serialization mandates across European supply chains compress qualification timelines for compliant substrate formulations.
- Consumer Goods:Cosmetics and premium spirits packaging sustains demand for holographic differentiation through established hot stamping infrastructure.
- Automotive Parts:Interior trim and badging applications require weather-resistant lacquer systems with extended durability specifications.
- Electronics:Device housing decoration favors cold foiling for short-run customization without heated die retooling.
Procurement volume centers on consumer goods; pharmaceuticals climbs the fastest under regulatory serialization expansion.
Distribution Channel:
Customer scale and technical support requirements determine channel selection, with large converters favoring direct relationships.
- Direct Sales:Multinational packaging groups and dedicated security printers negotiate specifications directly with foil manufacturers. Brand owner consolidation into three-tier supplier accreditation compresses switching cycles for direct accounts.
- Distributors:Regional converters access inventory pooling and technical service through specialized industrial distribution networks serving mid-tier label and packaging operations.
- Online Retail:Small-format converters and prototyping shops source standard metallized products through digital procurement platforms.
- Wholesalers:General industrial supply houses serve occasional-use decorative printing customers with limited technical specification requirements.
Transaction volume flows through direct sales; distributor relationships gain share among mid-tier converters seeking inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, India, and the United States concentrate stamping foil manufacturing through tax incentives and bonded warehouse facilities serving pharmaceutical and cosmetics packaging corridors.
Germany
Pharmaceutical serialization mandates under EMA guidelines drive security foil qualification timelines. REACH compliance requirements for lower-VOC release layers extend product development cycles. LEONHARD KURZ maintains headquarters and captive R&D operations near Fürth, anchoring a dense cluster of specialty printing houses in Bavaria.
United States
FDA 21 CFR indirect food additive regulations shape substrate selection for blister lidding applications. State-level extended producer responsibility frameworks in California and New York force reformulation investments. Chicago and Milwaukee host established converting infrastructure serving tobacco and spirits packaging accounts.
India
Pharmaceutical packaging localization under the PLI scheme creates demand for tax stamp and authentication foil production. CDSCO serialization requirements align with global track-and-trace standards. Gujarat and Maharashtra house expanding converting capacity serving domestic and export pharmaceutical markets.
China
Dual carbon goals under MIIT guidance accelerate investment in recyclable carrier substrate development. GB standards for packaging migration testing tighten qualification protocols for food-contact applications. Zhejiang and Jiangsu provinces concentrate metallized film manufacturing with integrated lacquering capabilities.
Switzerland
Swissmedic pharmaceutical packaging guidelines exceed EU baseline requirements for tamper-evident features. EFTA alignment ensures seamless market access for security foil suppliers. Basel and Zurich anchor high-value label converting serving multinational pharmaceutical headquarters.
Stamping Foils Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated European players dominating security-grade formulations while Asian fabricators capture volume in standard metallized products. The vendor base organizes into three strategic archetypes: integrated substrate-to-foil producers with captive coating technology, regional converters leveraging toll metallization partnerships, and specialty security printers with in-house foil slitting operations. M&A activity concentrates among European coating resin suppliers, while capacity expansion dominates Asian manufacturing corridors.
Within the integrated technology tier, LEONHARD KURZ and API exemplify European specialists with end-to-end substrate development and holographic security capabilities. Henan Foils occupies a position among Chinese volume manufacturers with integrated aluminum metallization operations. These three anchors represent divergent competitive positions: technology leadership through captive R&D, security-focused qualification depth, and scale-driven cost optimization respectively.
| Leading Market Players |
|---|
| LEONHARD KURZ |
| API |
| CFC International |
| Crown Roll Leaf |
| UNIVACCO Foils Corporation |
| ITW Foils |
| Foilco Limited |
| Henan Foils |
| Nakai Industrial Co. |
| Others |
Value Network & Pricing Analysis
Cold foiling technology adoption is simultaneously compressing tooling-dependent hot stamping margins and concentrating supply relationships among UV-adhesive specialists with captive coating capabilities. This production-method transition rewards converters who can eliminate heated die inventory while squeezing price-takers lacking in-house lacquer formulation expertise.
Pricing Analysis
Volume concentrates in standard metallized hot stamping foils where Asian manufacturers compete on scale; margins accrue to security-grade and holographic tiers where REACH-compliant release layer chemistry creates qualification barriers. Three-tier pricing structure across premium holographic, standard metallized, and economy pigmented levels separates LEONHARD KURZ and API from toll-metallization competitors. Cost compression in economy tiers is intensifying because aluminum LME volatility transfers directly to converter input costs. Small-format label converters exhibit highest price sensitivity; multinational pharmaceutical security printers prioritize compliance certification over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle multinational packaging group demand while specialized distributors serve mid-tier label operations with inventory pooling. Raw material dependencies draw from German and Chinese PET substrate suppliers, consolidated European coating resin producers, and LME-tethered aluminum metallization feedstock. Geographic supply concentration centers on Germany for security foil R&D, China for integrated metallization-lacquering volume, and India for pharmaceutical localization under PLI incentives. Single-source vulnerability pervades European release layer chemistry where masterbatch supplier consolidation has eliminated alternative qualified sources. Distribution runs through direct specification negotiation for accredited security printers and regional distributor networks for standard decorative applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stamping foils sector is navigating a technology-transition phase as UV-activated cold foiling displaces heated die infrastructure across short-run label converting. Incumbents and entrants face divergent imperatives shaped by regulatory chemistry constraints and serialization mandate expansion.
For Market Incumbents: Anchor qualification depth in pharmaceutical security foils where EMA serialization mandates compress supplier switching timelines. Prioritize captive coating resin development to offset European masterbatch consolidation leverage. Defend margin position through backward integration into nano-structured release layer chemistry rather than competing on metallized volume against Asian scale manufacturers. For New Entrants and Emerging Players: Regional pharmaceutical label converters in India and Southeast Asia represent the most penetrable buyer archetype underserved by established European security foil suppliers. Target CDSCO-aligned serialization programs where domestic qualification timelines lag global mandate expansion. Pursue toll-metallization partnerships with existing PET substrate producers to bypass capital-intensive lacquering infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging material conglomerates seeking security foil capabilities. Long-term viability favors specialists with in-house REACH-compliant formulation laboratories and established pharmaceutical printer accreditation. Watch for inflection when EU F-Gas Regulation phase-down accelerates non-fluorinated barrier technology substitution costs beyond independent converter absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Resin Production | Captive supply of REACH-compliant release layers insulates margin from European masterbatch consolidation. |
| Pharmaceutical Security Foil Qualification | EMA serialization mandates compress supplier switching cycles for accredited tax stamp producers. |
| Cold Foiling UV-Adhesive Capacity Expansion | Elimination of heated die tooling captures short-run variable data demand from premium spirits label converters. |
| Recyclable Carrier Substrate Development | EU Packaging and Packaging Waste Directive alignment secures access to multinational brand owner approved supplier lists. |
| India Pharmaceutical Localization Partnership | PLI scheme incentives under CDSCO serialization requirements create tax stamp foil demand outside European supply concentration. |
Research Methodology
Trade association filings, customs metallized film export records, and EMA regulatory guidance documents formed the secondary backbone for demand sizing and supply mapping. Primary fieldwork encompassed structured interviews with specialty printing house technical directors, pharmaceutical packaging procurement managers, coating resin supplier regulatory affairs leads, and label converter operations heads. Bottom-up and top-down triangulation reconciled converter throughput estimates against substrate supplier shipment data.
Bottom-up modeling anchored volume projections in pharmaceutical serialization lane expansion, cosmetics packaging retooling cycles, and cold foiling adoption curves across label converting segments. Segmentation dimensions spanned process technology, surface application, downstream regulatory exposure, and supply chain access tier. CAGRs derived from weighted scenario analysis across aluminum price volatility assumptions and REACH reformulation compliance timelines. Migration testing protocol evolution and EU F-Gas Regulation phase-down schedules served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum LME volatility, European coating resin supplier consolidation trajectories, and pharmaceutical serialization mandate enforcement variance across regulatory jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Laser Coders Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Printed Boxes Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Global Digital Printing Packaging Market