
 Europe Printed Packaging Market | 2026-2036
Europe Printed Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Printed Packaging Market Foresight
Germany's Rhineland packaging belt is rewriting regional supply dynamics for printed corrugated and folding carton capacity. Mondi plc leverages integrated pulp-to-pack operations across Central European mills to sustain margin control. Huhtamaki Oyj anchors specialty flexible packaging demand through its Nordic dairy and ready-meal customer base. Constantia Flexibles Group GmbH dominates pharmaceutical blister lidding and cold-form foil segments across Alpine and Benelux markets.
Europe printed packaging encompasses decorated substrates—paper, plastic films, metal foils, and glass surfaces—produced via flexography, gravure, offset, and digital printing methods to deliver brand communication, regulatory labeling, and shelf differentiation. Flexible packaging leads volume throughput due to lightweight material efficiency and extended food preservation properties, while labels capture concentrated margin pools from pharmaceutical serialization and premium cosmetics authentication requirements. Rigid packaging maintains structural importance in spirits, fragrances, and high-value electronics where tactile unboxing experience commands price premiums.
REACH chemical safety standards and the EU Packaging and Packaging Waste Regulation reshape material selection and recyclability thresholds for converters across the continent. EMA pharmaceutical labeling requirements and F-Gas Regulation compliance for barrier films create technical entry barriers that favor accredited mid-cap specialists. Stakeholders must monitor pending EU Green Deal packaging reuse targets and digital product passport mandates that will redefine capital allocation between substrate innovation and circular infrastructure.
Market Dynamics
EU pharmaceutical serialization mandates under the Falsified Medicines Directive are forcing converters to retool label production lines for track-and-trace compliance, compressing margins for non-accredited suppliers while creating certification premiums for qualified specialists.
Growth Catalysts
- REACH chemical safety standards:Material substitution toward bio-based inks and adhesives is opening new supplier relationships for compliant converters across German automotive packaging corridors.
- Pharmaceutical serialization infrastructure:Alpine and Benelux markets are expanding cold-form foil and blister lidding capacity to serve EMA-mandated authentication requirements.
- Digital printing adoption:Short-run personalization for Nordic dairy and ready-meal segments is reducing minimum order quantities and enabling SKU proliferation without plate costs.
Market Restraints
- Pulp and polymer input volatility:Integrated pulp-to-pack operators maintain margin buffers that standalone converters cannot replicate, concentrating volume with Mondi plc and similar vertically structured players.
- F-Gas Regulation compliance costs:Barrier film producers face capital-intensive retooling for reduced-GWP formulations, favoring mid-cap specialists with accredited testing capabilities.
- Rigid packaging substitution pressure:Lightweight flexible formats are displacing folding cartons in ambient food categories, constraining corrugated demand growth in Southern European markets.
Strategic Opportunities
- Polish and Romanian manufacturing expansion:Lower conversion costs and proximity to German distribution networks are attracting flexible packaging investment from Western European brand owners.
- EU Green Deal reuse targets:Pending mandates for reusable transport packaging will require printed RFID-embedded tracking labels, creating new specification demand.
- Digital product passport integration:Convergence of printed QR codes with blockchain verification systems is enabling premium authentication services for cosmetics and spirits exporters.
Industry Challenges
- Gravure cylinder engraving skill scarcity:Retiring master engravers in Italian and Spanish converter bases are constraining high-volume publication and decorative packaging output.
- Multi-substrate certification timelines:EFSA food-contact approvals for novel bio-barrier coatings extend development cycles beyond typical customer contract windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Printed Packaging Market |
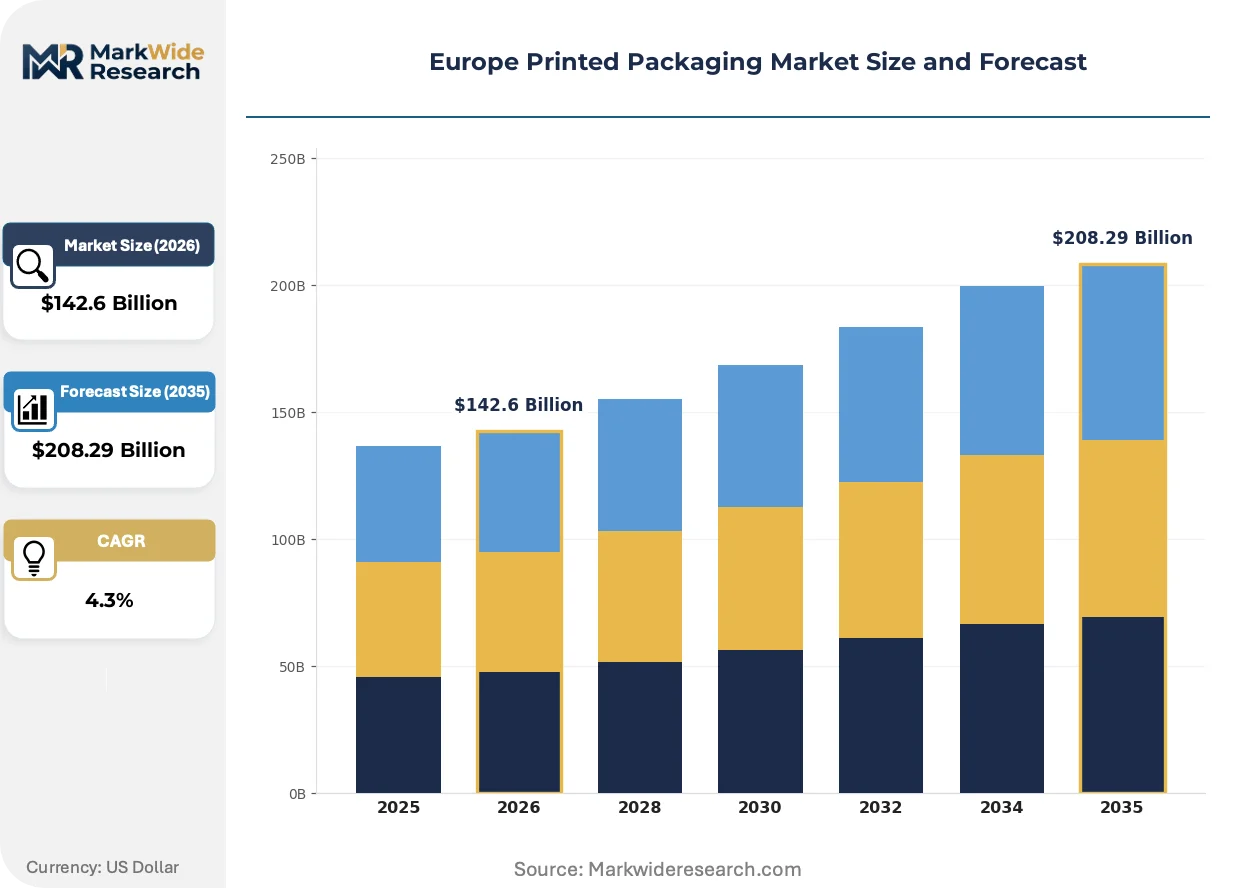
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $208.29 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Rigid Packaging, Cartons Material: Paper, Plastic, Metal, Glass Application: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics End User: Retail, Wholesale, E-commerce, Industrial |
| Companies Covered | Mondi plc, Ahlstrom Oyj, Autajon Group, Huhtamaki Oyj, CCL Industries Inc., Amcor Group, Smurfit Westrock plc, DS Smith PLC, Constantia Flexibles Group GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Printed Packaging Market Shifts & Advancements
Flexography is hybridizing with digital printheads to bridge the gap between long-run efficiency and short-run customization, reshaping capital allocation across Central European converter floors.
Water-based flexo ink systems are hybridizing with UV-LED curing modules to eliminate solvent recovery infrastructure while maintaining print speed on coated paper and film substrates. German automotive parts suppliers are piloting these lines for just-in-time label production with lot-specific barcoding. The technology is hybridizing prepress and production workflows, compressing job changeover times from hours to minutes and enabling same-day turnaround for export documentation.
The EU Packaging and Packaging Waste Regulation is mandating extended producer responsibility fee modulation based on recyclability performance, forcing brand owners to redesign multilayer structures. High-barrier food pouches with incompatible polymer combinations face cost penalties that favor monomaterial alternatives. Premium chocolate and coffee exporters in Switzerland and Belgium are accelerating adoption of paper-based barrier solutions to maintain shelf-life claims while avoiding modulation surcharges.
Brand owner specification teams are consolidating supplier panels to reduce audit burden, compressing the viable vendor base for pharmaceutical and infant nutrition contracts. This concentration is displacing transactional spot-buying relationships with multi-year framework agreements that bundle design, regulatory filing support, and inventory management. The shift is most visible in French and German markets where EMA and national health authority documentation requirements create high switching costs.
Europe Printed Packaging Market Segmentation
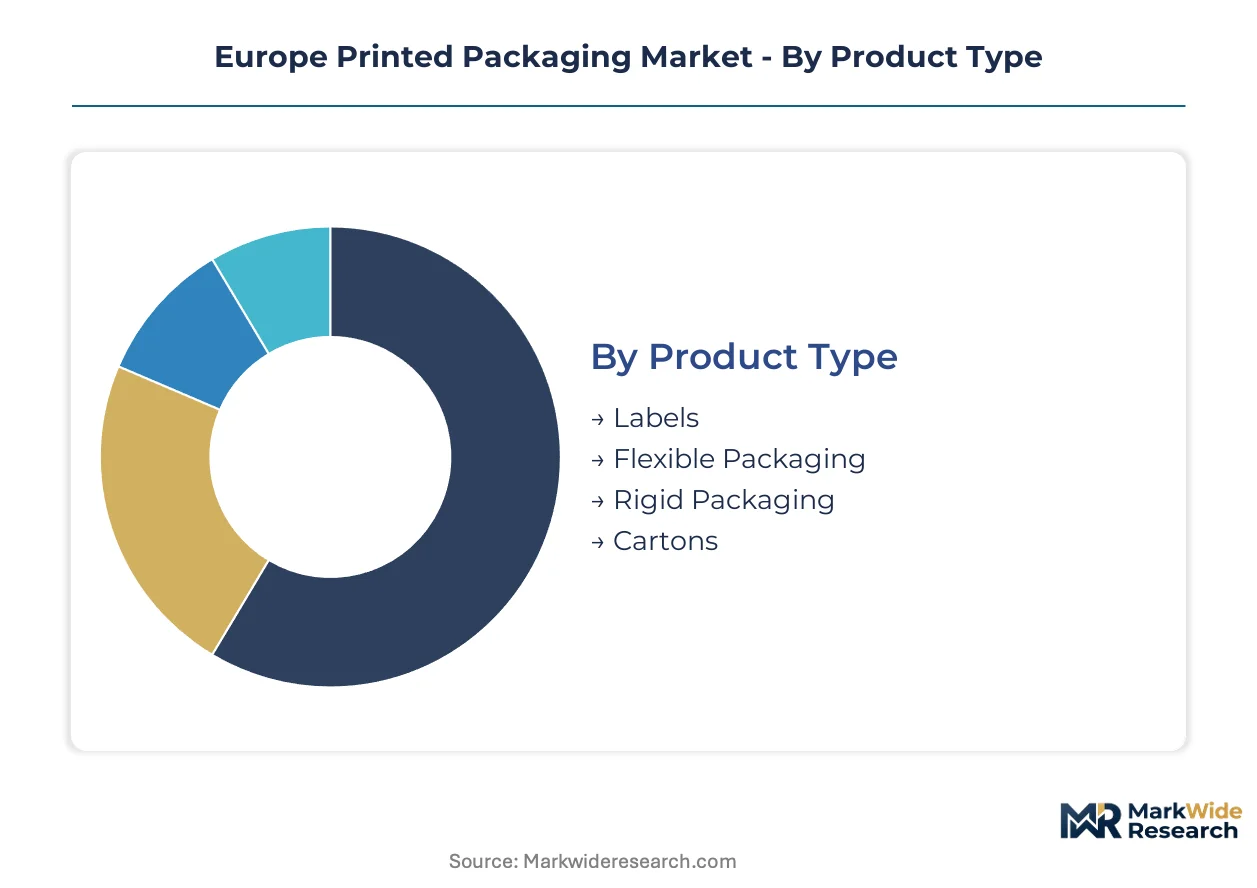
Segmentation in Europe printed packaging reveals how substrate choices, regulatory compliance tiers, and channel-specific shelf-life requirements fragment converter capabilities. Understanding these divisions exposes where capital equipment investments concentrate and where margin premiums accrue from certification barriers.
Product Type:
Mature gravure and offset platforms dominate long-run formats while emerging digital workflows reshape short-run economics across the Rhineland and Alpine corridors.
- Labels:Pressure-sensitive and shrink-sleeve formats incorporate serialized QR codes and tamper-evident features mandated by EMA pharmaceutical track-and-trace rules. German automotive exporters in Baden-Württemberg drive just-in-time demand for lot-specific barcoding on chemical and parts shipments.
- Flexible Packaging:Multilayer pouches and films combine barrier polymers with high-definition flexographic decoration for extended shelf-life foods. Nordic dairy processors and Belgian chocolate exporters specify these formats to meet EU Packaging and Packaging Waste Regulation recyclability thresholds while preserving oxygen and moisture barriers.
- Rigid Packaging:Decorated cans, bottles, and containers serve spirits, fragrances, and premium cosmetics where tactile unboxing commands price premiums. French perfume houses and Scottish whisky distillers specify embossed metal and specialty glass finishes.
- Cartons:Folding carton and corrugated formats carry structural loads for retail-ready shelf presentation. Southern European ambient food producers face displacement pressure from lightweight flexible alternatives in pasta and dry goods categories.
Flexible packaging retains volume leadership; labels hold the steepest expansion curve from pharmaceutical serialization mandates.
Material:
Cost tiers separate commodity substrates from certified barrier and decorative grades that command specification premiums in regulated end-uses.
- Paper:Uncoated kraft and coated folding boxboard serve corrugated shipping cases and retail cartons. REACH-compliant bio-based barrier coatings are displacing polymer laminates in Swiss and Belgian premium food exports facing extended producer responsibility fee modulation.
- Plastic:PE, PP, PET, and multilayer barrier films dominate flexible food and pharmaceutical formats. F-Gas Regulation compliance costs for high-barrier coextrusions favor mid-cap specialists with accredited testing capabilities in Germany and the Netherlands.
- Metal:Aluminum and steel substrates provide structural integrity and light protection for beverages, aerosols, and high-value industrial chemicals. Italian and Spanish converters face gravure cylinder engraving skill scarcity that constrains decorative output.
- Glass:Screen-printed and labeled glass containers serve premium spirits, cosmetics, and pharmaceuticals requiring inert contact surfaces. French and German brand owners consolidate supplier panels to reduce audit burden for EMA documentation.
Plastic substrates capture the widest application footprint; paper-based barrier innovations are climbing the fastest as brands redesign for recyclability penalties.
Application:
Customer type determines whether procurement prioritizes total landed cost or compliance certification depth.
- Food & Beverage:The largest volume sink spans ambient, chilled, and frozen categories with divergent barrier requirements. Polish and Romanian manufacturing expansion attracts Western European brand owners seeking lower conversion costs with German distribution proximity.
- Cosmetics:Premium skincare and fragrance packaging demands tactile substrates and authentication features against counterfeiting. Digital product passport integration via printed QR codes and blockchain verification enables premium services for exporters.
- Pharmaceuticals:Blister lidding, cold-form foil, and serialized labels face EMA-mandated authentication infrastructure. Alpine and Benelux markets are expanding accredited capacity to serve these requirements.
- Electronics:Anti-static films and precision-cut foam inserts protect high-value components through distribution. German industrial packaging corridors concentrate demand from automotive and chemical exporters.
Food and beverage retains volume leadership; pharmaceuticals holds the steepest expansion curve from serialization infrastructure buildout.
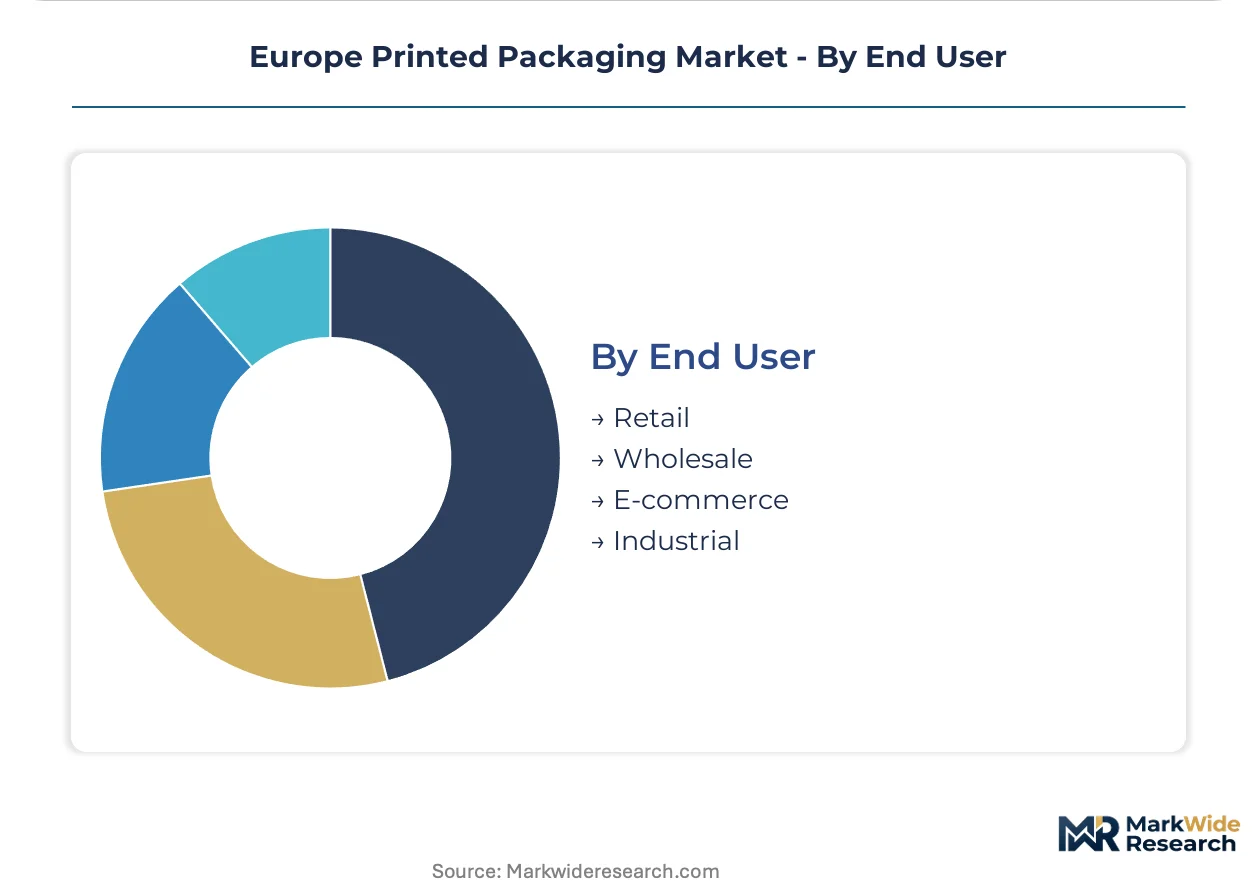
End User:
Channel-specific fulfillment speeds and batch size economics reshape converter equipment configuration across the continent.
- Retail:High-volume, standardized formats with shelf-ready display requirements dominate hypermarket and supermarket supply chains. Mondi plc's integrated pulp-to-pack operations across Central European mills sustain margin control for these accounts.
- Wholesale:Bulk industrial packaging emphasizes pallet efficiency and shipping durability over decoration depth. German automotive parts suppliers pilot hybrid flexo-digital lines for just-in-time export documentation.
- E-commerce:Ship-ready formats with printed return instructions and damage-resistant construction face SKU proliferation pressures. Digital printing adoption reduces minimum order quantities for Nordic ready-meal segments.
- Industrial:Chemical, automotive, and machinery exporters specify hazard-compliant labels and corrosion-resistant barriers. REACH chemical safety standards are opening new supplier relationships for compliant converters.
Retail retains volume leadership; e-commerce holds the steepest expansion curve from personalization and ship-ready format demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in printed packaging logistics, connecting Bavarian industrial zones to Rotterdam's container terminals and Black Sea outlets.
Germany
EMA pharmaceutical serialization mandates and REACH chemical safety standards drive demand for high-traceability labels and bio-based barrier coatings. The Rhineland packaging belt concentrates flexible packaging capacity serving automotive exporters in Baden-Württemberg and chemical producers along the Rhine-Neckar triangle.
France
Premium cosmetics authentication requirements and spirits export packaging sustain rigid format demand from Paris-based luxury houses. ANSM pharmaceutical labeling rules and extended producer responsibility fee modulation under the EU Packaging and Packaging Waste Regulation favor monomaterial carton redesigns in the Île-de-France cluster.
Netherlands
Rotterdam-Europoort container throughput anchors distribution logistics for Western European brand owners sourcing flexible formats. F-Gas Regulation compliance costs for barrier films concentrate accredited testing capabilities among mid-cap specialists in the Eindhoven-Brabant corridor serving dairy and ready-meal processors.
Switzerland
Swissmedic pharmaceutical packaging standards and premium chocolate export requirements sustain cold-form foil and blister lidding demand. Basel's pharmaceutical corridor hosts specialized converters accredited for EMA-mandated authentication infrastructure serving Alpine and Benelux markets.
Poland
Lower conversion costs and rail connectivity to German distribution networks attract flexible packaging investment from Western European brand owners. Polish manufacturing expansion serves Nordic dairy segments and ambient food exporters redesigning for EU Green Deal recyclability thresholds.
Europe Printed Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing specification premiums from certification barriers. The vendor base separates between vertically structured pulp-to-pack operators sustaining margin buffers and standalone converters exposed to input volatility. Three archetypes dominate: integrated resource-backed platforms, mid-cap accredited specialists, and regional scale players. Competitive moves concentrate on backward integration into raw material supply and geographic expansion into lower-cost manufacturing zones.
Among Nordic-based operators, Huhtamaki Oyj occupies a position exemplifying specialty flexible packaging concentration around dairy and ready-meal customer segments. Mondi plc represents the integrated platform archetype with captive pulp supply across Central European mill networks. Constantia Flexibles Group GmbH anchors the mid-cap specialist tier within pharmaceutical blister lidding and cold-form foil segments.
| Leading Market Players |
|---|
| Mondi plc |
| Ahlstrom Oyj |
| Autajon Group |
| Huhtamaki Oyj |
| CCL Industries Inc. |
| Amcor Group |
| Smurfit Westrock plc |
| DS Smith PLC |
| Constantia Flexibles Group GmbH |
| Others |
Supply & Pricing Matrix
German pulp-to-pack integration anchors margin pools downstream, with captive Kraftliner supply from Rhineland mills converting into corrugated formats at cost structures standalone converters cannot match. REACH compliance costs and EMA serialization premiums concentrate pricing power with accredited specialists serving pharmaceutical and automotive corridors.
Pricing Analysis
EMA pharmaceutical serialization mandates dictate the pricing tier structure across European printed packaging, separating premium-accredited specialists from commodity label converters. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EMA-tracked blister lidding commanding specification premiums above generic food-grade flexibles. Price differentiation stems from regulatory compliance tier and volume scale, with long-run gravure contracts from French spirits exporters showing lower sensitivity than short-run digital jobs for Nordic ready-meal SKUs. Cost compression in standard-tier folding cartons is intensifying because lightweight flexible formats displace rigid formats in Southern European ambient food categories.
Supply Chain Analysis
Tariff exposure between EU member states and third-country pulp suppliers dominates supply chain risk assessment for European printed packaging converters. Raw material sourcing draws from Swedish and Finnish Kraftliner producers, German mechanical pulp mills, and Benelux polymer resin distributors, with barrier film formulations resting on specialty chemical inputs from Basel and Rotterdam chemical clusters. Single-source vulnerability concentrates in gravure cylinder engraving capacity, where retiring master engravers in Italian and Spanish converter bases constrain decorative output. Distribution runs through Rotterdam-Europoort container terminals for Atlantic export routes and Rhine-Main-Danube waterway corridors for Central European inland distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European printed packaging presents a service-attach opportunity where regulatory filing support and inventory management contracts expand faster than substrate production, with EMA documentation services and digital product passport integration capturing recurring revenue layers.
For Market Incumbents: Entrench EMA-accredited capacity through certification maintenance and cold-form foil line expansion in Alpine corridors, defending against mid-cap specialists capturing pharmaceutical serialization premiums. Backward integration into bio-based barrier coating R&D secures margin buffers as EU Green Deal fee modulation penalizes multilayer structures. Channel control through multi-year framework agreements with French and German brand owners raises switching costs for transactional competitors. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian flexible packaging manufacturing, where lower conversion costs and German distribution proximity attract Western European brand owner investment. The most penetrable segment sits with Nordic dairy processors seeking short-run digital personalization without plate costs. A go-to-market angle combining just-in-time export documentation with hybrid flexo-digital lines addresses German automotive parts supplier demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap flexible packaging specialists holding F-Gas Regulation accredited testing capabilities but lacking pulp integration. Long-term viability over a 5-10 year window favors converters with circular infrastructure investments aligned to pending EU packaging reuse targets. The acquisition target archetype combines pharmaceutical certification depth with digital printhead integration. The signal to watch is EU Green Deal packaging reuse target finalization triggering capital reallocation toward RFID-embedded tracking label capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Barrier Coatings | REACH-compliant coatings displace polymer laminates for Swiss chocolate exporters facing extended producer responsibility modulation. |
| Digital Product Passport Integration | Blockchain-verified printed QR codes enable premium authentication services for French cosmetics and Scottish spirits exporters. |
| Polish Manufacturing Footprint Expansion | Rail connectivity to German distribution networks captures Nordic dairy and ambient food brand owner volume migration. |
| Hybrid Flexo-Digital Line Deployment | UV-LED curing modules eliminate solvent recovery infrastructure while maintaining speed for Baden-Württemberg automotive label demand. |
| EMA Serialization Infrastructure Buildout | Alpine and Benelux cold-form foil capacity expansion serves pharmaceutical track-and-trace mandates under Falsified Medicines Directive. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with converter operations directors, brand owner specification managers, pharmaceutical packaging engineers, and EMA regulatory affairs consultants. Secondary validation drew from EMA submission databases, EU Packaging and Packaging Waste Regulation impact assessments, F-Gas Regulation compliance filings, and Cefic chemical industry trade data. Bottom-up capacity modeling across German, French, and Benelux converter installations was triangulated against top-down demand estimates from Nordic dairy processor procurement disclosures and automotive exporter shipping documentation requirements.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include substrate type, printing technology, regulatory compliance tier, and end-use application intensity. CAGRs were derived from slope analysis of normalized adoption curves and elasticity-adjusted price-volume relationships. Industry-specific forecast inputs incorporated EMA serialization mandate compliance deadlines and EU Green Deal packaging reuse target progression scenarios.
Stress conditions across pulp and polymer input volatility, F-Gas Regulation compliance cost trajectories, and gravure cylinder engraving labor scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around regulatory timeline adherence and brand owner redesign cycles for recyclability thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Mexico Print Label Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Pad Printing Machine Market