
 Flexible Alternating Current Transmission Systems Market | 2026-2036
Flexible Alternating Current Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Alternating Current Transmission Systems Market Foresight
Project finance and long-term equipment leasing is reshaping competitive entry in flexible AC transmission systems, lowering capital barriers for regional grid operators and independent power producers. Siemens Energy leverages integrated engineering capabilities to anchor large-scale utility contracts across Europe and North America. ABB sustains technology leadership in thyristor-based series compensation through continuous R&D investment in semiconductor control systems. NR Electric competes aggressively on cost-engineered static VAR solutions for emerging market transmission upgrades.
Flexible alternating current transmission systems encompass power-electronic and mechanically switched devices that dynamically control voltage, impedance, and phase angle across high-voltage grids, typically operating at transmission levels above 100 kV to stabilize alternating current networks against fluctuating load and generation patterns. Static synchronous compensators deliver instantaneous reactive power injection through voltage-source converters, making them essential for wind and solar integration where conventional capacitor banks respond too slowly. Thyristor-controlled series capacitors occupy mature, high-volume positions in long-distance transmission corridors, while unified power flow controllers remain niche due to complexity but command premium margins where multi-parameter control justifies investment. Deployment through renewable energy integration represents the fastest-expanding channel as offshore wind farms in the North Sea and onshore clusters in Texas require dynamic voltage support that fixed compensation cannot provide.
The Federal Energy Regulatory Commission enforces mandatory reliability standards under NERC that directly specify reactive power margins and voltage recovery timelines, compelling US transmission operators to install FACTS devices or face substantial penalties. In Europe, the EU Green Deal and F-Gas Regulation constrain sulfur hexafluoride-insulated switchgear alternatives, pushing manufacturers toward dry-air or vacuum-insulated FACTS designs that align with decarbonization pathways. China's National Energy Administration and Ministry of Ecology and Environment jointly enforce dual carbon goals that accelerate ultra-high voltage corridor builds requiring advanced power flow controllers. Stakeholders must monitor how evolving grid codes in multiple jurisdictions redefine technical specifications before committing to platform architectures with twenty-year operational lifecycles.
Market Dynamics
Grid operators face mounting pressure to stabilize networks against renewable intermittency, forcing accelerated deployment of power-electronic compensation devices that respond faster than mechanical switching systems.
Growth Catalysts
- EU Green Deal mandates:European transmission operators must modernize aging corridors to meet decarbonization timelines, creating procurement pull for advanced power flow controllers.
- Offshore wind clusters:North Sea developments and Texas onshore arrays require dynamic voltage support that fixed capacitor banks cannot deliver.
- India's CEA technical standards:Tightened grid code requirements compel state transmission utilities to install static compensators for reactive power management.
Market Restraints
- Semiconductor supply concentration:Thyristor and IGBT sourcing depends on limited East Asian foundry capacity, exposing lead time volatility.
- SF6 insulation restrictions:Europe's F-Gas Regulation constrains sulfur hexafluoride-insulated switchgear, forcing costly redesign toward dry-air alternatives.
- High upfront capital intensity:Unified power flow controllers require substation-grade investment that regional utilities struggle to finance without multilateral support.
Strategic Opportunities
- Project finance structures:Long-term equipment leasing lowers capital barriers for independent power producers and regional grid operators.
- Ultra-high voltage corridors:China's dual carbon goals accelerate 800 kV+ builds requiring multi-parameter power flow controllers.
- Modular static VAR designs:Scalable compensation units address emerging market transmission upgrades without full substation reconstruction.
Industry Challenges
- Power electronics expertise scarcity:Voltage-source converter design and commissioning skills concentrate among a narrow specialist workforce.
- Legacy system integration complexity:Retrofitting thyristor-controlled series capacitors into existing protection schemes demands extensive relay coordination.
- Twenty-year platform commitment risk:Evolving grid codes across multiple jurisdictions may obsolete specifications before equipment end-of-life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Alternating Current Transmission Systems Market |
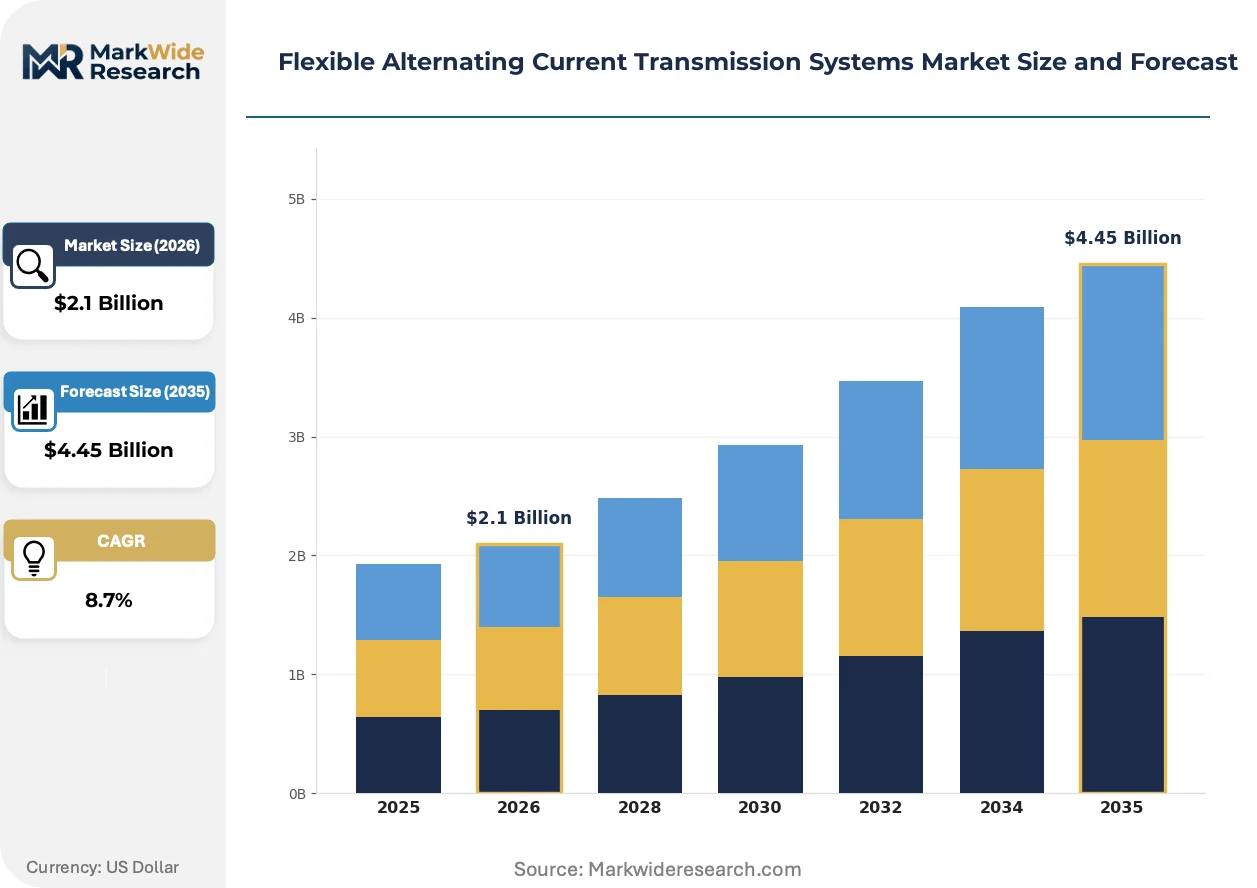
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thyristor-Controlled Series Capacitor, Static Synchronous Compensator, Static VAR Compensator, Unified Power Flow Controller Application: Power Flow Control, Voltage Stability, Transmission Capacity Enhancement, System Reliability End User: Transmission Operators, Distribution Network Owners, Independent Power Producers, Grid Service Providers Deployment: Utility-Scale Projects, Renewable Energy Integration, Smart Grid Implementation, Microgrid Systems |
| Companies Covered | Siemens Energy, ABB, Hitachi Energy, GE Vernova, Mitsubishi Electric, NR Electric, Hyosung Heavy Industries, Eaton Corporation, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Alternating Current Transmission Systems Market Shifts & Advancements
Digital control architectures and semiconductor advances are compressing response times for grid stabilization equipment while policy frameworks reshape equipment specifications across major transmission markets.
Wide-bandgap silicon carbide semiconductors are replacing conventional silicon IGBTs in voltage-source converters, enabling higher switching frequencies with reduced thermal losses. European and North American utilities are piloting these modules in next-generation static synchronous compensators. This transition is digitizing protection and control architectures, embedding real-time analytics that compress fault response intervals from cycles to milliseconds.
The EU F-Gas Regulation and parallel EPA scrutiny in the United States are phasing down sulfur hexafluoride use in high-voltage insulation. Manufacturers must redesign gas-insulated switchgear for dry-air or vacuum alternatives. European transmission operators face the tightest compliance timelines, accelerating procurement of SF6-free FACTS platforms despite cost premiums.
Asset ownership models are fragmenting as independent power producers and renewable developers assume direct responsibility for grid connection compliance. Traditional utility procurement of turnkey substations is giving way to developer-led sourcing of modular compensation units. This pattern is most visible in Texas and the North Sea, where offshore wind leaseholders specify point-of-interconnection reactive power support independently of incumbent transmission planning.
Flexible Alternating Current Transmission Systems Market Segmentation
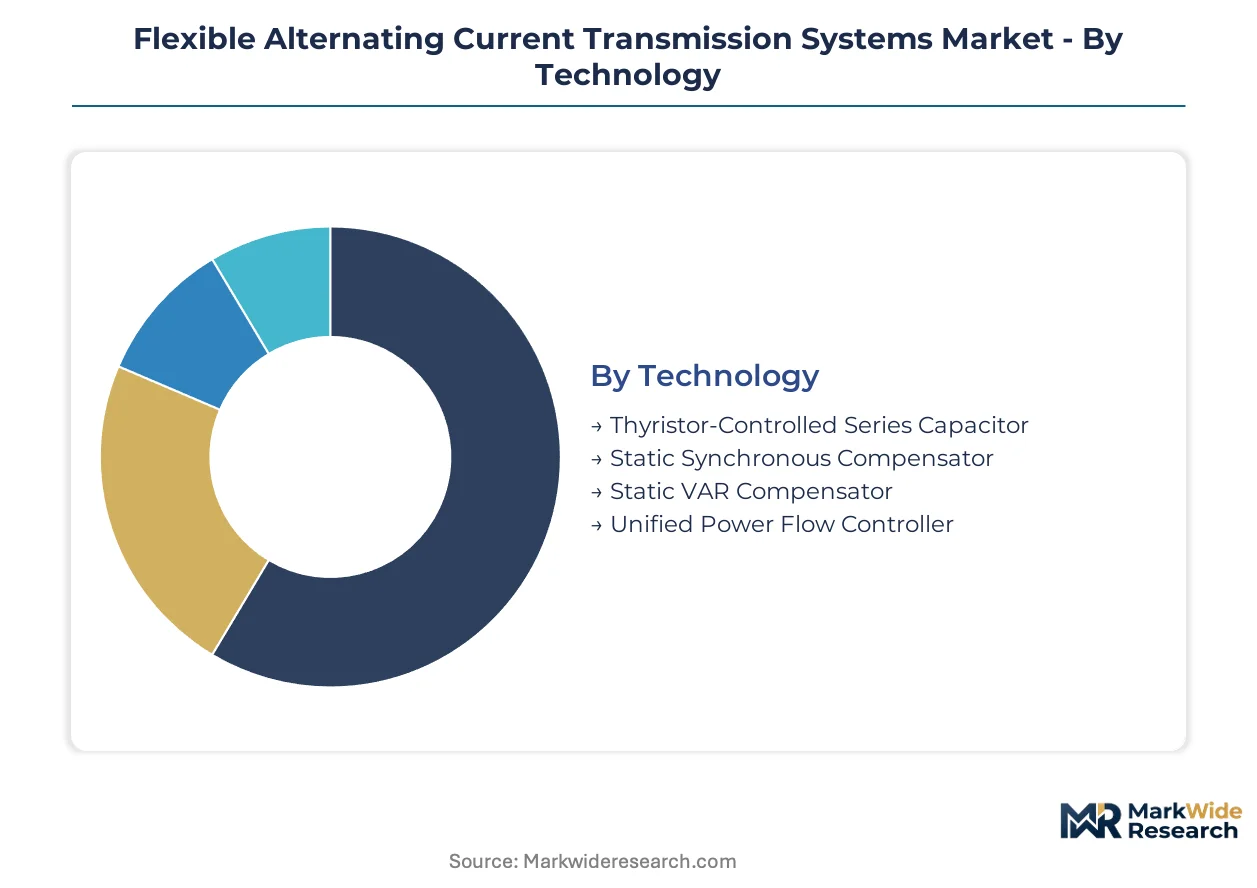
Technology selection in FACTS equipment determines commissioning complexity, spare parts inventory, and field service requirements across multi-decade operational lifecycles. Procurement patterns diverge sharply between utilities prioritizing proven reliability and developers seeking rapid deployment for renewable interconnection deadlines.
Technology:
After-sales service intensity varies dramatically across power electronic architectures, with voltage-source converters demanding specialized commissioning expertise that thyristor-based systems rarely require.
- Static Synchronous Compensator:Voltage-source converters using IGBT or silicon carbide modules deliver instantaneous reactive power injection. Offshore wind clusters in the North Sea specify these units for dynamic voltage support where response latency determines grid code compliance. Siemens Energy and ABB anchor European utility contracts through integrated engineering capabilities that bundle long-term service agreements.
- Thyristor-Controlled Series Capacitor:Mature phase-controlled thyristor banks modulate series capacitance for impedance compensation across long-distance transmission corridors. China's ultra-high voltage corridor builds consume the largest volumes, though procurement concentrates among state-grid procurement consortia with standardized maintenance protocols. NR Electric competes aggressively on cost-engineered variants for emerging market transmission upgrades.
- Static VAR Compensator:Thyristor-switched capacitor and reactor banks provide stepped reactive compensation for voltage regulation at lower cost than synchronous compensators.
- Unified Power Flow Controller:Multi-parameter controllers combining series and shunt compensation enable simultaneous voltage, impedance, and phase-angle control.
Thyristor-Controlled Series Capacitor holds the largest share; momentum sits with Static Synchronous Compensator.
Application:
Margin structures compress where standardized specifications enable vendor substitution, while bespoke performance requirements sustain premium pricing.
- Voltage Stability:Dynamic reactive compensation prevents voltage collapse during fault conditions or sudden generation loss. Texas ERCOT operators deploy static compensators at renewable-rich nodes where solar ramping exceeds conventional capacitor response capabilities. FERC NERC reliability standards mandate specific voltage recovery timelines that only power-electronic devices satisfy.
- Power Flow Control:Active management of transmission line loading prevents thermal limit violations and loop flows. Germany's SuedLink corridor and comparable meshed networks require continuous impedance adjustment that mechanically switched equipment cannot provide. EU Green Deal timelines accelerate procurement for corridor modernization.
- Transmission Capacity Enhancement:Series compensation increases effective line length capability without conductor replacement.
- System Reliability:FACTS devices contribute to n-1 security criteria and post-contingency recovery performance.
Voltage Stability commands the highest service attach rates; Transmission Capacity Enhancement delivers the steepest expansion trajectory.
End User:
Customer procurement sophistication shapes contract structures, with independent developers accepting equipment leasing terms that traditional utilities reject.
- Transmission Operators:Vertically integrated grid owners specify turnkey substations with twenty-year service agreements and penalty clauses for availability shortfalls. State Grid Corporation of China and comparable national utilities dominate procurement volumes through centralized procurement frameworks.
- Independent Power Producers:Renewable developers assume direct grid connection compliance responsibility, sourcing modular compensation units through project finance structures that lower capital barriers. North Sea offshore wind leaseholders and Texas solar developers drive this pattern.
- Distribution Network Owners:Lower-voltage operators deploy scaled-down FACTS for feeder voltage regulation.
- Grid Service Providers:Merchant operators offer ancillary services using strategically located compensation assets.
Transmission Operators account for the largest contract values; Independent Power Producers are climbing the fastest.
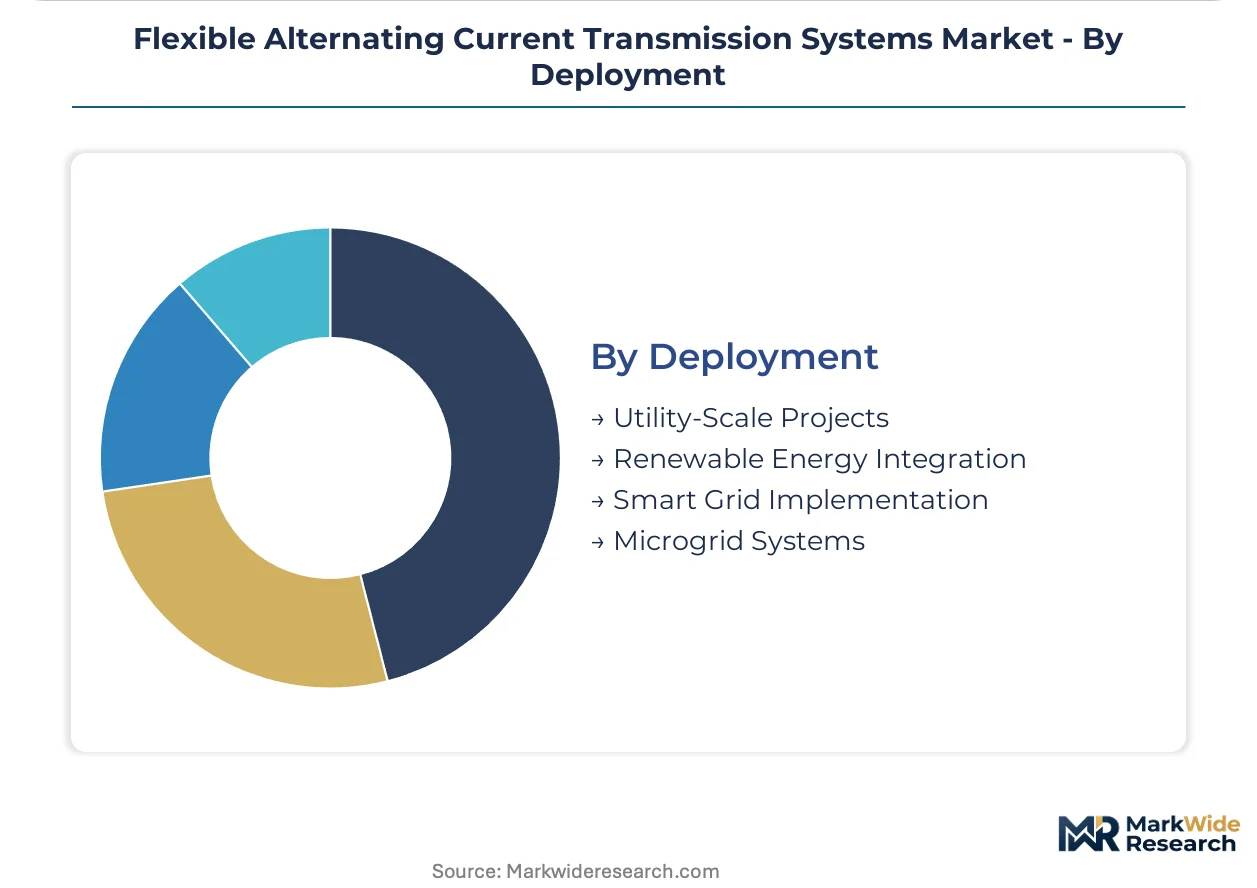
Deployment:
Volume concentration follows renewable interconnection queues, with queue position determining developer urgency for equipment delivery.
- Renewable Energy Integration:Offshore wind farms and utility-scale solar clusters require dynamic compensation at point of interconnection. Germany's North Sea buildout and Texas CREZ transmission expansion create concentrated demand for static synchronous compensators with sub-cycle response. India's CEA technical standards now mandate similar capabilities for state transmission utilities.
- Utility-Scale Projects:Greenfield substation construction for bulk power transfer enables optimized FACTS integration without retrofit constraints. China's 800 kV+ ultra-high voltage corridors represent the largest individual project scale.
- Smart Grid Implementation:Digital substation architectures embed FACTS within wider automation and monitoring systems.
- Microgrid Systems:Islanded or weak-grid applications use smaller-scale compensation for local voltage and frequency stabilization.
Utility-Scale Projects dominate absolute capacity additions; Renewable Energy Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid modernization mandates and renewable integration deadlines are concentrating FACTS procurement across transmission markets with the most aggressive decarbonization timelines. National regulators are tightening technical specifications faster than equipment replacement cycles, forcing operators toward power-electronic solutions with multi-decade operational horizons.
China
State Grid Corporation's ultra-high voltage corridor builds drive the largest absolute demand for thyristor-controlled series compensation. The National Energy Administration and Ministry of Ecology and Environment jointly enforce dual carbon goals that accelerate 800 kV+ transmission investments. Sichuan-Chongqing and the Yangtze River Delta host the densest clusters of substation construction requiring advanced power flow controllers.
Germany
The SuedLink corridor and North Sea offshore wind buildouts require dynamic voltage support that fixed compensation cannot deliver. EU Green Deal mandates and the F-Gas Regulation constrain sulfur hexafluoride-insulated alternatives, pushing procurement toward dry-air designs. Northern coastal regions from Schleswig-Holstein to Lower Saxony concentrate developer-led sourcing of static synchronous compensators.
United States
Texas ERCOT operators deploy static compensators at renewable-rich nodes where solar ramping exceeds conventional response capabilities. FERC enforces NERC reliability standards that specify reactive power margins and voltage recovery timelines. The Texas CREZ transmission expansion and California's interconnection queue create concentrated demand in the Southwest and Pacific regions.
India
State transmission utilities face tightened CEA technical standards compelling installation of static compensators for reactive power management. Central Electricity Authority mandates now require dynamic compensation capabilities that conventional capacitor banks cannot satisfy. Gujarat and Maharashtra host the most active procurement for emerging market transmission upgrades.
United Kingdom
Offshore wind leaseholders in the North Sea specify point-of-interconnection reactive power support independently of incumbent transmission planning. OFGEM's regulatory framework accommodates developer-led sourcing of modular compensation units. Scotland's offshore clusters and the Eastern England transmission reinforcement drive the fastest-growing procurement channel.
Flexible Alternating Current Transmission Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates large-scale utility contracts among integrated engineering groups while fragmenting emerging market procurement among cost-optimized suppliers. The competitive terrain separates into three archetypes: full-service system integrators bundling long-term service agreements, component-focused semiconductor suppliers capturing value from power-electronic cores, and regional specialists engineering localized solutions for standardized technical specifications. Dominant competitive moves include strategic partnerships between equipment manufacturers and project finance providers, plus technology licensing arrangements that accelerate voltage-source converter deployment without captive semiconductor fabrication.
Among integrated engineering groups, Siemens Energy and ABB exemplify the full-service archetype anchoring European and North American utility contracts through bundled capabilities. NR Electric occupies a position within the cost-engineered tier, representing regional specialists competing aggressively on static VAR solutions for emerging market transmission upgrades. These three companies illustrate how competitive positioning stratifies across procurement sophistication: premium-tier integrated players capture turnkey substation contracts, while mid-tier specialists penetrate modular compensation markets through project finance structures that lower capital barriers for independent power producers.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB |
| Hitachi Energy |
| GE Vernova |
| Mitsubishi Electric |
| NR Electric |
| Hyosung Heavy Industries |
| Eaton Corporation |
| Infineon Technologies |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for thyristor and IGBT modules concentrates margin capture among semiconductor suppliers, while downstream equipment vendors compete through bundled service contracts that offset hardware price erosion. The pricing-power asymmetry between captive power-electronic cores and commoditized mechanical assemblies defines competitive positioning across the value chain.
Pricing Analysis
Certification level against F-Gas Regulation and NERC reliability standards creates the primary spread between premium and standard tiers. Project-based contracting dominates, with price differentiation driven by after-sales service bundling and silicon carbide versus silicon IGBT module selection. Cost compression in thyristor-controlled series capacitors is intensifying because standardized specifications enable vendor substitution. Independent power producers exhibit highest price sensitivity due to project finance constraints, while transmission operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Silicon carbide wafer feedstock draws from Japan, Germany, and the United States, with device fabrication concentrating in Taiwan and South Korea. Raw material dependencies include high-purity silicon, rare-earth magnetic materials, and specialty capacitor films. Single-source vulnerability in wide-bandgap semiconductor substrates exposes lead time volatility for voltage-source converter manufacturers. Distribution runs through EPC contractors and direct utility procurement channels, with developer-led sourcing fragmenting traditional turnkey structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service agreements and digital monitoring subscriptions are expanding faster than hardware shipments, transforming capital-equipment vendors into recurring-revenue platforms. The service-attach opportunity exceeds equipment margins across multi-decade operational lifecycles.
For Market Incumbents: Harden semiconductor supply security through captive sourcing agreements or equity positions in silicon carbide substrate suppliers. Deepen commissioning expertise pools to defend against specialist engineering firms capturing high-margin service contracts. The scarcity of voltage-source converter design talent represents the most acute threat to margin retention.
For New Entrants and Emerging Players: Modular static VAR designs for India's state transmission utilities represent the most penetrable entry point, given CEA-mandated procurement timelines and cost-engineering requirements. Project finance partnerships with regional grid operators lower capital barriers and accelerate contract acquisition without competing for turnkey utility awards.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular compensation units as standardized designs reduce engineering overhead. Acquisition targets should exhibit established commissioning capabilities in offshore wind or ultra-high voltage corridors. Watch silicon carbide module pricing as the inflection indicator for voltage-source converter cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Captive silicon carbide sourcing insulates against East Asian foundry lead time volatility. |
| Long-term Service Contract | Twenty-year availability guarantees lock in recurring revenue above hardware depreciation cycles. |
| Project Finance Partnership | Equipment leasing structures open independent power producer procurement channels. |
| SF6-free Platform Certification | F-Gas Regulation compliance enables European utility market access with premium positioning. |
| Voltage-Source Converter Licensing | Technology transfer accelerates emerging market penetration without captive fabrication investment. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads; and secondary validation against FERC filings, IEA grid integration reports, CEA technical standards documentation, and project development databases. Bottom-up equipment shipment tallies and top-down transmission investment forecasts were triangulated to establish market sizing boundaries.
Forecast inputs include renewable interconnection queue volumes, ultra-high voltage corridor build schedules, and evolving grid code specifications across the projection horizon. Segmentation dimensions modeled encompass technology architecture, application function, end-user procurement sophistication, and deployment channel. CAGRs were derived from equipment replacement cycles and policy-mandated procurement deadlines rather than extrapolated historical trends.
Stress conditions across semiconductor supply disruption, F-Gas Regulation acceleration, and renewable curtailment risk were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about grid code harmonization and carbon policy continuity. Cross-checking against national transmission investment plans and interconnection queue data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
United States LNG Infrastructure Market