
 South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market Analytics
Brazilian converter station manufacturing capacity is hardening as domestic energy infrastructure investment accelerates. Siemens AG leverages its European engineering base to anchor large-scale bipole projects across the continent. ABB Ltd competes through specialized submarine cable integration for offshore wind interconnections. Prysmian Group dominates high-voltage cable supply, extending its Mediterranean production expertise into Argentinian and Chilean waters.
High-Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding conventional alternating current limits, typically operating at voltages above 100 kV with thyristor or insulated-gate bipolar transistor switching. These systems primarily serve to interconnect asynchronous grids, stabilize renewable-heavy networks, and deliver power across submarine routes where capacitive losses render AC impractical. Voltage Source Converter technology leads new installations across South and Central America due to superior grid-forming capabilities and black-start resilience. Bi-pole configurations sustain premium pricing as utilities prioritize redundancy for cross-border links between Brazil, Argentina, and Paraguay. Undersea transmission applications concentrate fastest growth, driven by offshore wind development off Brazil's northeastern coast and inter-island connections in the Caribbean basin.
ANEEL, Brazil's national electric energy regulator, mandates grid code compliance for HVDC interconnections exceeding 230 kV, while Argentina's ENRE enforces similar technical standards for cross-border capacity allocation. Chile's SEC certification requirements for imported converter equipment create selective market access barriers favoring established European and Japanese suppliers. Stakeholders must monitor evolving local content rules and submarine cable environmental licensing timelines as project development cycles lengthen across the region's diverse regulatory jurisdictions.
Market Dynamics
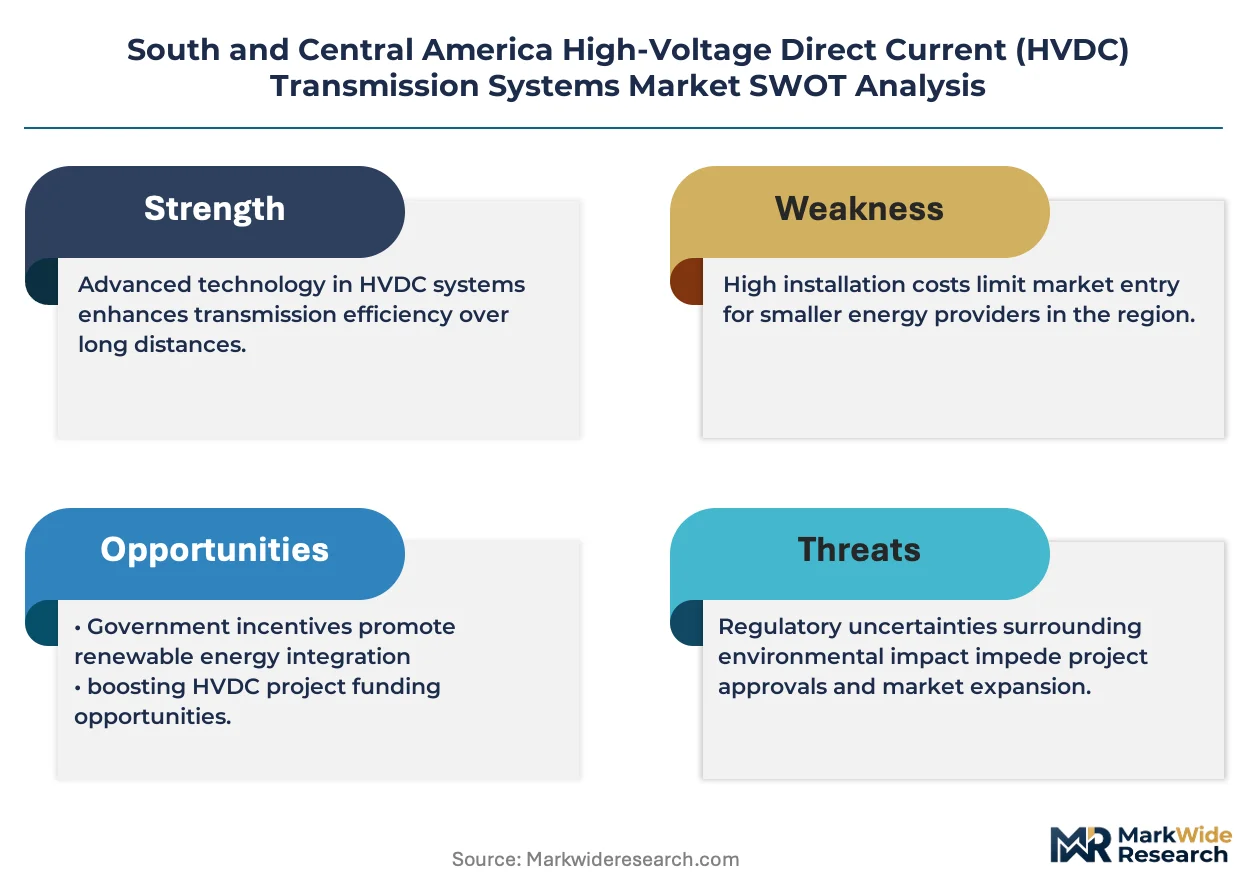
Voltage Source Converter technology is modularizing converter station architectures across Brazil and Argentina, compressing project timelines while ANEEL's grid code mandates force synchronous upgrades to legacy thyristor corridors.
Growth Catalysts
- ANEEL grid code mandates:Brazil's national electric energy regulator requires HVDC interconnections exceeding 230 kV to meet stringent stability standards, forcing synchronous investment in converter station modernization.
- Offshore wind interconnection:Brazilian waters host accelerating submarine cable demand as northeast coastal wind farms seek grid integration through subsea bipole links.
- Cross-border renewable integration:Remote hydroelectric and solar generation in Paraguay and Chile requires long-distance transmission corridors that only HVDC technology can economically serve.
Market Restraints
- Converter equipment import dependence:Chile's SEC certification requirements create selective barriers favoring established European and Japanese suppliers, limiting domestic manufacturing scale.
- Submarine cable supply concentration:Mediterranean-based cable producers dominate high-voltage subsea capacity, creating geographic concentration risk for Brazilian offshore projects.
- Environmental licensing timelines:Brazilian coastal and Argentinian Patagonian cable routes face extended seabed impact assessments that stretch project development cycles.
Strategic Opportunities
- Caribbean inter-island connections:Underpenetrated island grids in the Lesser Antilles present white space for submarine HVDC links currently served by inefficient diesel generation.
- Black-start resilience services:Voltage Source Converter stations enable grid-forming capabilities that Argentine utilities can monetize as ancillary services during system restoration events.
- Local content rule evolution:Shifting domestic manufacturing incentives across Brazil and Argentina may reward converter station assembly investments with preferential procurement access.
Industry Challenges
- Specialized power electronics engineering:Thyristor-era technicians require retraining for insulated-gate bipolar transistor maintenance, creating workforce transition friction in Brazilian utilities.
- Asynchronous grid synchronization:Integration complexity rises as Paraguayan and Uruguayan frequency standards diverge from Brazilian-Argentine norms, demanding sophisticated control system adaptation.
- Extended commissioning cycles:Bipole redundancy requirements and submarine cable soak-testing protocols compress operational revenue timelines for project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market |
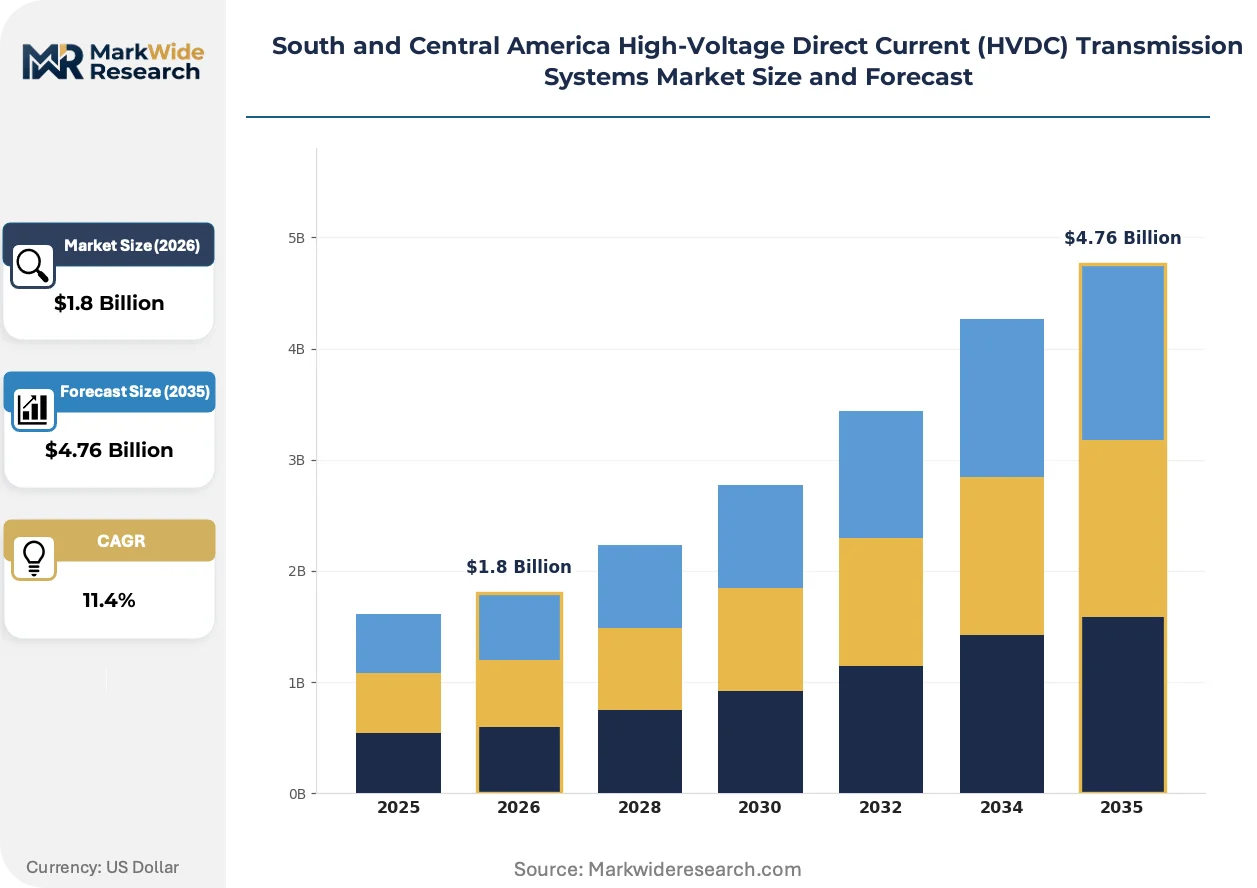
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
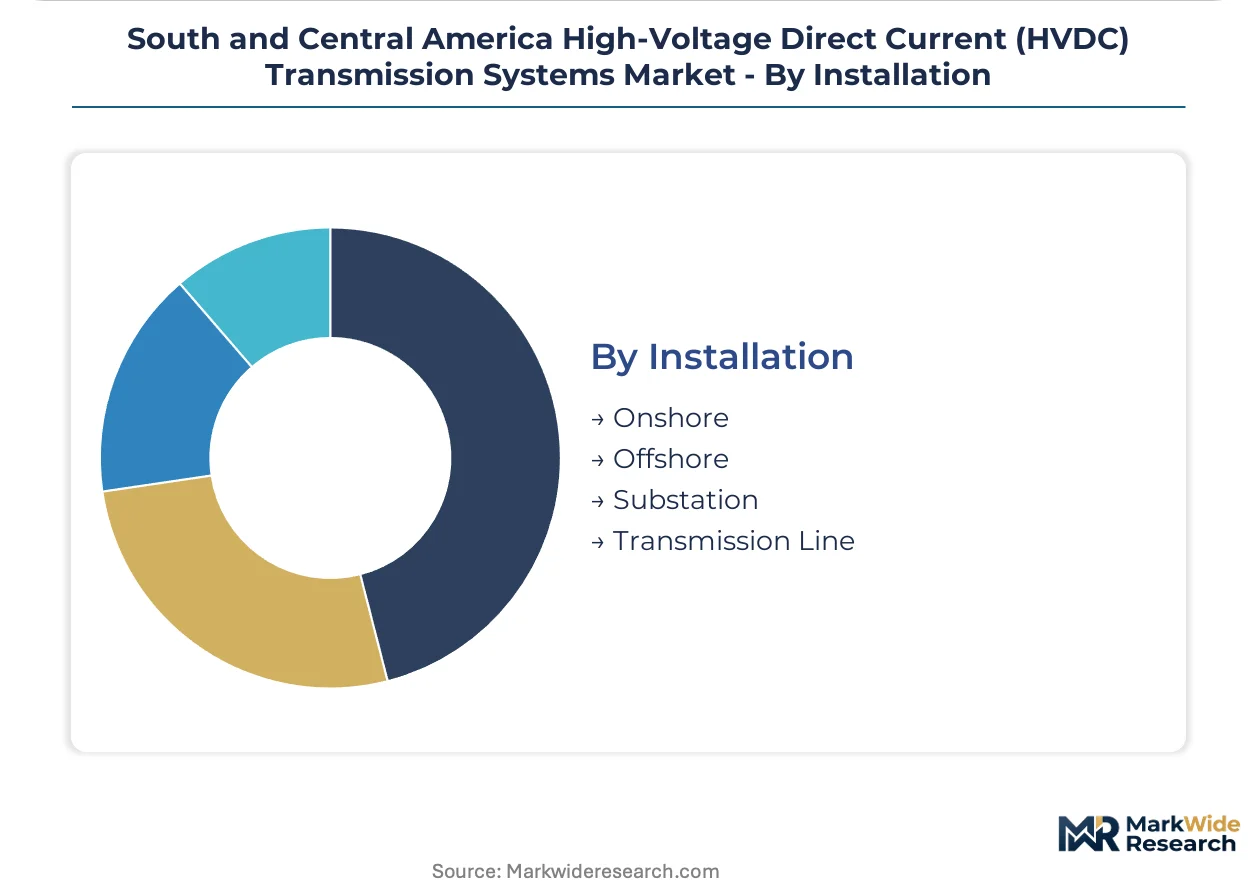
| Segmentation | Technology: Mono-pole, Bi-pole, Voltage Source Converter, Line Commutated Converter End User: Utilities, Industrial, Renewable Energy, Data Centers Application: Undersea Transmission, Grid Interconnection, Power Supply, Voltage Regulation Installation: Onshore, Offshore, Substation, Transmission Line |
| Companies Covered | Siemens AG, Toshiba Corporation, General Electric Company, ABB Ltd, Prysmian Group, Mitsubishi Electric Corporation, Schneider Electric SE, Alstom SA, NKT A/S, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market Evolving Landscape
Modular converter architectures are compressing station footprints while regulatory mandates accelerate thyristor-to-VSC transitions across the continent's transmission backbone.
Voltage Source Converter technology is modularizing station design by replacing monolithic thyristor halls with standardized power module cabinets. Brazilian utilities including state-grid operators are adopting these configurations for greenfield bipole projects. This modularity is compressing construction schedules and enabling phased capacity expansion without full station shutdowns.
ANEEL's evolving grid code framework now mandates dynamic reactive power support from all HVDC interconnections above 230 kV, effectively prohibiting pure thyristor solutions for new projects. Industrial consequence includes forced retirement planning for legacy mercury-arc and early semiconductor stations. Cross-border links between Brazil and Argentina face the steepest compliance timelines given their system-critical status.
Procurement patterns among South American transmission operators are rotating from equipment purchase toward availability-based service contracts covering converter station lifecycle performance. Brazilian federal utility consortia now unbundle hardware acquisition from 15-year maintenance commitments, displacing traditional EPC lump-sum structures. This shift concentrates most visibly in northeast Brazil where offshore wind integration projects demand guaranteed uptime clauses.
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
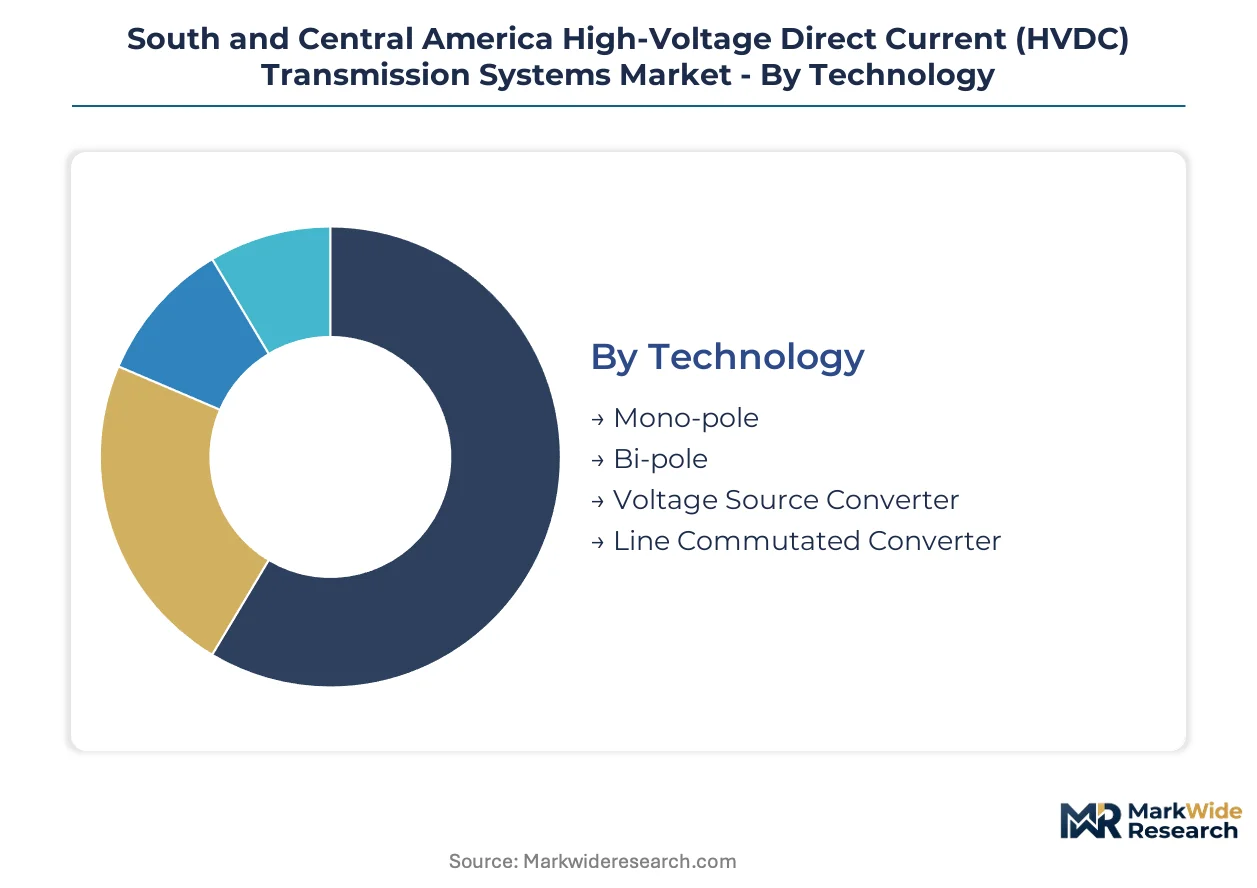
HVDC transmission systems segment across multiple dimensions that determine project economics and technical specifications. Technology choice dictates converter station architecture and grid-forming capabilities. End-user concentration and application context shape procurement patterns across South and Central American markets.
Technology:
Capital intensity varies sharply across converter technologies, with station costs scaling from modular VSC units to legacy thyristor halls requiring extensive civil works.
- Voltage Source Converter:Insulated-gate bipolar transistor switching enables black-start capability and reactive power support without synchronous compensation. Brazilian utilities prioritize VSC for northeast offshore wind integration where grid-forming resilience commands premium pricing.
- Bi-pole:Dual-conductor configurations with metallic return paths sustain transmission continuity during single-pole outages. Cross-border corridors between Brazil and Argentina mandate bipole redundancy for system-critical links under ANEEL grid code requirements.
- Mono-pole:Single-pole designs with ground or sea return reduce upfront capital for shorter transmission distances. Suitable for island interconnections in the Caribbean basin where load density cannot justify bipole investment.
- Line Commutated Converter:Thyristor-based technology dominates legacy installations requiring synchronous voltage support. Existing corridors face phased replacement as ANEEL mandates dynamic reactive capability above 230 kV.
Bi-pole configurations absorb the bulk of installed capacity; Voltage Source Converter technology is expanding most quickly across greenfield projects.
End User:
Procurement scale and technical sophistication diverge sharply between state-grid operators and private offtakers.
- Utilities:State and federal transmission operators in Brazil and Argentina drive bipole corridor development with 15-year availability-based contracts. Northeast Brazilian federal consortia unbundle hardware from lifecycle performance guarantees.
- Renewable Energy:Offshore wind developers in Brazilian waters demand submarine cable integration with guaranteed uptime clauses. Project finance requirements force developers toward service-contract procurement structures.
- Industrial:Mining and smelting operations in Chile and Peru seek dedicated HVDC links for remote renewable offtake. Load centers concentrate in Atacama solar zones and Patagonian wind corridors.
- Data Centers:Hyperscale facilities in São Paulo and Santiago metro areas require stable power quality for compute-intensive workloads. Grid interconnection via HVDC isolates sensitive loads from transmission disturbances.
Utilities command the dominant share of transmission capex; renewable energy developers are gaining procurement volume fastest.
Application:
Functional requirements determine cable specifications and converter control systems.
- Undersea Transmission:Submarine cable systems with polyethylene insulation and armored sheathing serve Brazilian offshore wind and Caribbean inter-island links. Extended seabed impact assessments in Patagonian waters stretch development timelines.
- Grid Interconnection:Asynchronous frequency coupling between Paraguayan, Uruguayan, and Brazilian-Argentine standards demands sophisticated control adaptation. System restoration services monetize black-start capabilities.
- Power Supply:Bulk electricity delivery from remote generation to load centers concentrates in Brazil's north-south transmission backbone. Distance economics favor HVDC above 600 kilometers.
- Voltage Regulation:Dynamic reactive support stabilizes renewable-heavy networks with fluctuating inverter-based generation. ANEEL mandates govern performance specifications.
Grid interconnection claims the largest installed base; undersea transmission is climbing the fastest on offshore wind development.
Installation:
Site constraints and environmental licensing differentiate project risk profiles.
- Offshore:Converter platforms and cable lay vessels operate in Brazilian northeastern waters with seasonal weather windows. Mediterranean cable producers dominate high-voltage subsea supply.
- Onshore:Converter station civil works and transmission tower corridors face land acquisition challenges in densely settled southeast Brazil. Modular VSC architectures compress station footprints.
- Substation:AC-DC conversion facilities house power electronics, harmonic filters, and cooling systems. Chile's SEC certification creates selective access barriers for imported equipment.
- Transmission Line:Overhead bipole conductors traverse Amazon basin terrain with specialized tower designs for span distances. Maintenance access determines operational cost structures.
Onshore installations retain the greatest cumulative investment; offshore deployment is gaining share fastest on submarine cable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining corridors in Chile's Atacama Desert and northeastern Brazil's offshore wind zones anchor HVDC infrastructure deployment across the continent.
Brazil
Offshore wind developers in Rio Grande do Norte and Ceará states drive submarine cable demand for subsea bipole links. ANEEL grid code mandates above 230 kV force synchronous converter station upgrades. São Paulo-based federal utility consortia unbundle hardware procurement from 15-year availability contracts.
Argentina
Cross-border hydroelectric integration with Paraguay requires asynchronous grid coupling through Yacyretá corridor expansions. ENRE technical standards govern capacity allocation for bi-national transmission links. Patagonian wind zones in Chubut and Santa Cruz provinces face extended seabed impact assessments for coastal cable routes.
Chile
Atacama Desert solar concentration and mining load centers in Antofagasta demand dedicated HVDC links from remote renewable generation. SEC certification requirements for imported converter equipment create selective market access barriers. Santiago metro hyperscale data centers require stable power quality through grid-isolating interconnections.
Paraguay
Itaipú hydroelectric surplus export capacity depends on bi-pole redundancy upgrades to Brazilian interconnections. The national electricity regulator mandates frequency standard harmonization with Mercosur grid codes. Alto Paraná industrial clusters near Ciudad del Este concentrate converter station maintenance demand.
Caribbean Basin
Lesser Antilles inter-island diesel replacement creates white space for submarine HVDC links between underpenetrated grids. Environmental licensing for seabed cable routes stretches development timelines across multiple national jurisdictions. Puerto Rican utility restructuring accelerates interest in grid-forming converter capabilities for resilience services.
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Global majors compete with regional champions across converter technology and cable integration, producing a tiered structure where European engineering houses anchor large-scale bipole projects while specialized fabricators capture submarine niche demand. Market concentration centers on power electronics and high-voltage cable supply, with procurement patterns shifting toward availability-based service contracts. Three archetypes dominate: integrated technology providers, cable specialists with subsea expertise, and regional engineering contractors. Competitive moves concentrate on strategic partnerships for offshore platform integration and backward integration into converter module manufacturing.
Within the integrated technology tier, Siemens AG and ABB Ltd represent European engineering anchors for continent-scale bipole corridors. Prysmian Group exemplifies cable specialists extending Mediterranean production expertise into South American waters. Among diversified industrial conglomerates, General Electric Company and Toshiba Corporation occupy positions spanning converter stations through grid automation portfolios.
| Leading Market Players |
|---|
| Siemens AG |
| Toshiba Corporation |
| General Electric Company |
| ABB Ltd |
| Prysmian Group |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Alstom SA |
| NKT A/S |
| Others |
Value Network & Pricing Analysis
Voltage Source Converter modularization is compressing converter station footprints while simultaneously redistributing cost economics from civil works toward power electronics procurement. Brazilian federal utility consortia now unbundle hardware acquisition from 15-year availability commitments, reshaping how suppliers capture value across the project lifecycle.
Pricing Analysis
Warranty and lifecycle service bundling now dominates procurement structures for Brazilian offshore wind integration projects. Three-tier pricing stratification separates premium VSC stations with black-start guarantees from standard thyristor replacements and economy mono-pole configurations for island links. Cost compression in the standard tier intensifies as Mediterranean cable producers extend capacity into South American waters. Renewable energy developers exhibit highest price sensitivity due to project finance constraints, while state-grid operators prioritize availability guarantees over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for critical converter modules now mandate multi-supplier qualification across European and Japanese engineering houses. Manufacturing concentration centers on Germany, Italy, and Japan for insulated-gate bipolar transistor switching components and high-voltage cable insulation. Raw material dependencies include refined copper for conductors, rare earth elements for magnetic components, and cross-linked polyethylene for submarine sheathing. Single-source vulnerability persists for specialized cable lay vessels serving Brazilian northeastern waters. Distribution runs through EPC contractors with integrated offshore platform capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as converter station suppliers pursue captive control over power module manufacturing to secure margins against availability-based contracting pressure.
For Market Incumbents: Anticipate margin compression from unbundled procurement structures by deepening backward integration into IGBT module fabrication and securing long-term service contracts with ANEEL-mandated uptime clauses. Defensive consolidation through submarine cable fleet partnerships will counter Mediterranean supply concentration. Threat substitution from Chinese converter entrants demands accelerated VSC platform standardization. For New Entrants and Emerging Players: Digital-channel routes through remote monitoring and predictive maintenance platforms offer lower-friction entry than hardware manufacturing. White space concentrates in Caribbean inter-island submarine links currently served by diesel generation, and in black-start resilience services for Argentine grid restoration. Target Paraguayan bi-pole redundancy upgrades through technology licensing rather than turnkey delivery. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated European engineering houses seeking South American platform capabilities. Long-term viability hinges on positioning ahead of ANEEL grid code enforcement waves. Acquisition target archetypes include regional cable integration specialists with Brazilian environmental licensing track records. Watch for inflection when Brazilian offshore wind capacity auctions accelerate seabed lease allocations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Module Manufacturing | Captive IGBT supply secures margins against 15-year availability contracting terms. |
| Submarine Cable Fleet Partnership | Joint vessel access mitigates Mediterranean supply concentration for Brazilian offshore projects. |
| VSC Platform Standardization | Modular architectures compress ANEEL compliance timelines across greenfield bipole corridors. |
| Black-Start Resilience Service Contracting | Grid-forming capabilities monetize ancillary services during Argentine system restoration events. |
| Environmental Licensing Acceleration | Pre-approved seabed impact assessments shorten development cycles for Patagonian cable routes. |
Research Methodology
Multi-period observation of converter station procurement patterns and ANEEL regulatory filings anchored the trend analysis, supplemented by interviews with utility planning officers, EPC project directors, submarine cable procurement leads, and offshore wind developers. Secondary validation drew from ANEEL grid code documentation, ENRE technical standards, FERC interconnection filings, IEA electricity transmission databases, and customs records of high-voltage cable imports. Bottom-up project pipeline aggregation triangulated against top-down transmission investment forecasts.
Input-output matrices mapped converter technology adoption across voltage classes, installation contexts, and end-user procurement structures throughout the forecast period. Segmentation dimensions modeled include technology type, application function, and regulatory jurisdiction cluster. CAGRs were derived from installed capacity buildout trajectories and unit cost evolution curves. Industry-specific forecast inputs incorporated offshore wind lease auction schedules and cross-border interconnection treaty ratification timelines.
Inputs from primary utility stakeholder interviews were available through the study window; gaps in proprietary project development timelines introduce uncertainty bands around near-term capacity commissioning dates. Deviation in Brazilian environmental licensing velocity or Mercosur frequency harmonization negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
DC Distribution Network Market