
 Digital Substation Market | 2026-2036
Digital Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Substation Market Analysis
Utility end-user demand is broadening as renewable energy providers and heavy industrial facilities accelerate digital substation procurement alongside traditional grid operators. Siemens Energy leverages its IEC 61850 protocol leadership to anchor European utility modernization programs. ABB competes through integrated protection-control platforms that dominate Scandinavian and German transmission upgrades. Hitachi Energy sustains its position in Asia-Pacific markets with gas-insulated switchgear paired with digital monitoring layers.
A digital substation replaces conventional copper-wired control and protection systems with fiber-optic networked intelligent electronic devices, process buses, and merged unit architectures sampling at 4 kHz for synchronized phasor measurement. Protection systems command the largest product type segment due to mandatory redundancy requirements and SIL-rated hardware costs. Communication equipment represents the fastest-expanding category as utilities deploy time-sensitive networking over Ethernet to replace legacy serial protocols. New installations currently absorb the majority of capital expenditure, though retrofitting of existing air-insulated substations is gaining traction where land constraints prevent greenfield construction.
IEC 61850 standards from the International Electrotechnical Commission, IEEE 2030 smart grid interoperability guidelines, and NERC CIP cybersecurity mandates collectively shape product certification requirements and procurement specifications across major markets. The EU Green Deal's transmission reinforcement targets are accelerating digital substation deployment timelines in member states. Stakeholders must monitor evolving cybersecurity disclosure rules from national regulators and weigh capital allocation between new digital-native installations versus staged retrofit architectures.
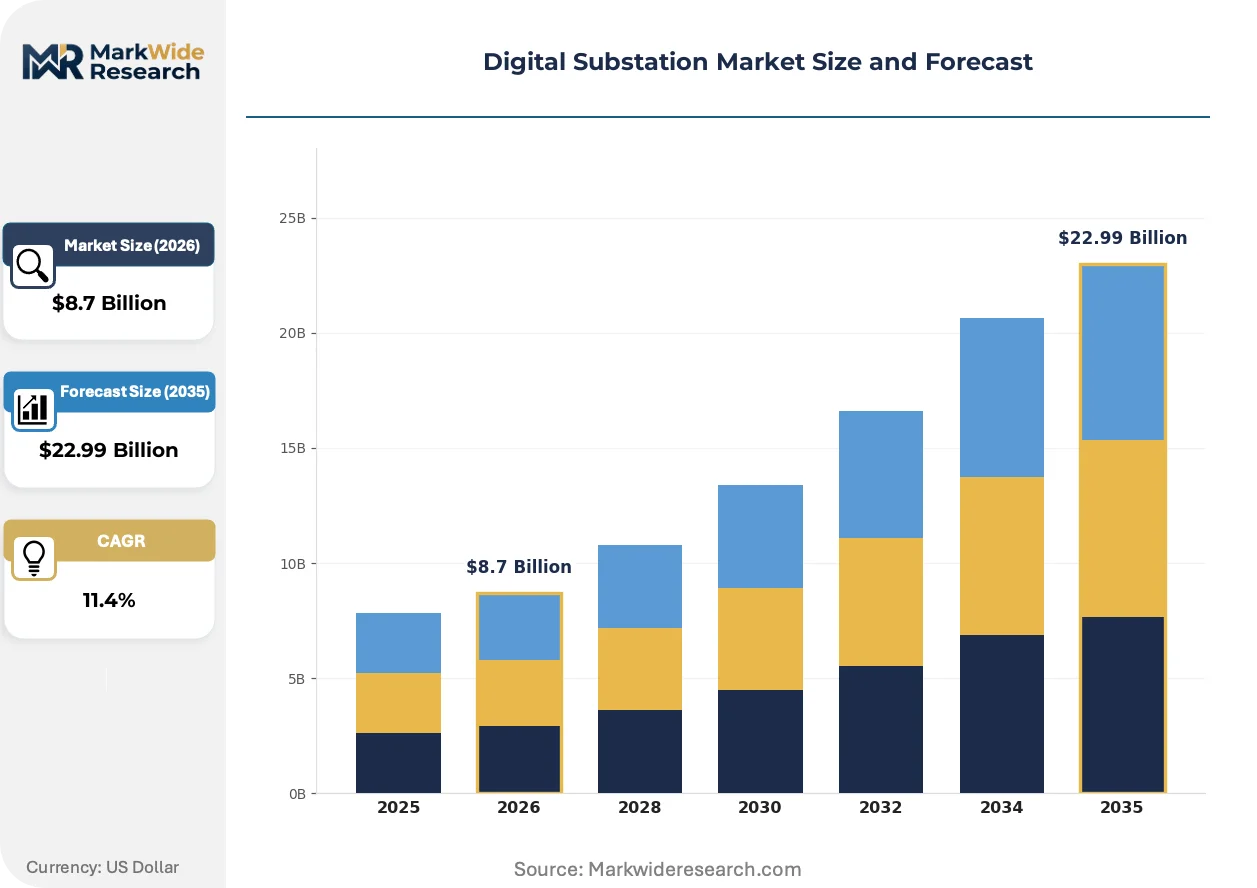
Market Dynamics
Utility-scale grid operators face mounting pressure to modernize aging electromechanical protection systems as renewable penetration forces faster fault detection and bidirectional power flow management across transmission networks.
Growth Catalysts
- IEC 61850 Protocol Mandates:European and Asian regulators have hardened interoperability requirements for substation automation, compressing deployment timelines for multi-vendor architectures.
- State Grid Retrofit Programs:China's central utility has committed capital to convert legacy air-insulated substations to digital process bus configurations.
- Time-Sensitive Networking:IEEE 802.1 Ethernet extensions are displacing serial fieldbus protocols in protection and control loops.
Market Restraints
- Copper-Fiber Transition Costs:Full digital substation builds require complete replacement of conventional instrument transformer wiring with merging units and optical CT/VT sensors.
- Cybersecurity Certification Burden:NERC CIP baseline standards impose multi-year compliance timelines on North American transmission operators.
- Specialized Engineering Talent Scarcity:Protection relay commissioning and SIL-rated system design depend on a shrinking pool of certified substation automation engineers.
Strategic Opportunities
- Offshore Wind Integration:North Sea and East Asian offshore clusters require compact gas-insulated digital substations with integrated monitoring layers.
- Brownfield Retrofit Architectures:Staged conversion of existing air-insulated substations allows utilities to preserve land assets while incrementally deploying process buses.
- EU Green Deal Transmission Targets:Member state reinforcement programs are accelerating procurement of digital-native substation designs.
Industry Challenges
- Legacy Electromechanical System Interoperability:Hybrid architectures combining analog inputs with digital process buses introduce synchronization and latency management complexity.
- Multi-Vendor Integration Risk:IEC 61850 edition mismatches between protection IEDs from different suppliers create commissioning delays and functional constraint violations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Substation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Protection Systems, Communication Equipment, Monitoring Solutions Installation Type: New Installation, Upgrades, Modernization, Retrofitting End User: Utilities, Renewable Energy Providers, Industrial Sector, Commercial Establishments Technology: Automation, Cybersecurity, IoT, Cloud Computing |
| Companies Covered | Hitachi Energy, Eaton Corporation, Siemens Energy, Cisco Systems, Toshiba Energy Systems & Solutions, GE Vernova, Schneider Electric, Honeywell International, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Substation Market Emerging Trajectories
Digital substation architectures are converging around software-defined protection functions and edge-computing platforms that compress decision latency from milliseconds to microseconds.
Sampled value process buses operating at 4 kHz with IEEE 1588 precision time protocol are integrating protection, measurement, and monitoring functions onto unified Ethernet backbones. Transmission utilities in Germany and South Korea are deploying these architectures for synchronized phasor measurement. The technology is integrating conventional hard-wired trip circuits with networked GOOSE messaging, enabling centralized protection logic while reducing copper cabling mass by over seventy percent.
The EU Green Deal's network reinforcement mandates are forcing accelerated procurement cycles for digital substation equipment across member states. Grid operators must demonstrate compliance with F-Gas Regulation phase-down schedules when specifying gas-insulated switchgear. Scandinavian transmission system operators are responding by prioritizing digital-native designs with reduced SF6 volumes and integrated condition monitoring.
Asset ownership models are fragmenting as renewable developers and industrial offtakers build private substations rather than contracting utility interconnection. European offshore wind consortia now procure complete digital substation packages directly from equipment manufacturers. This pattern is most visible in the North Sea cluster, where developer-led procurement bypasses traditional transmission system operator specification channels.
Digital Substation Market Segmentation
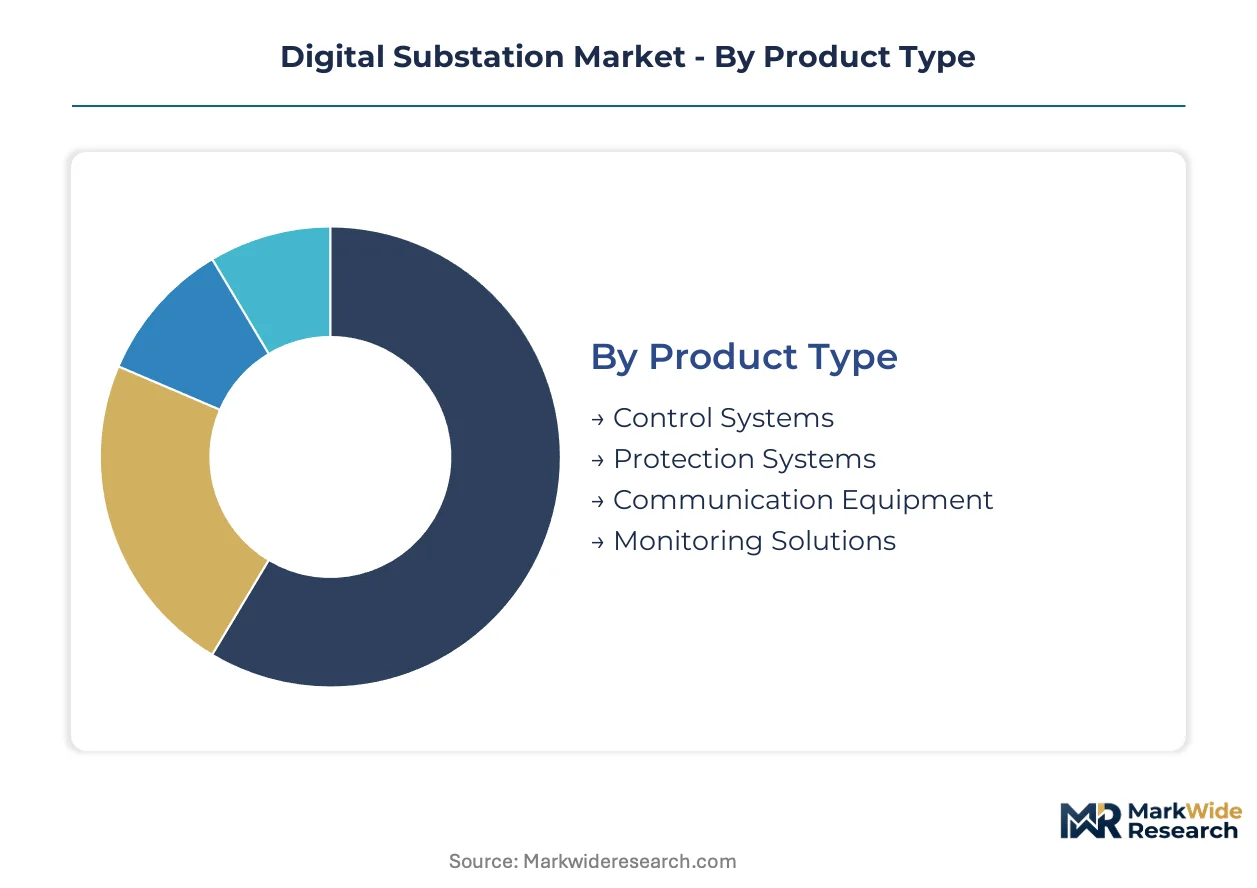
Digital substation procurement patterns diverge sharply across product architectures, installation contexts, and operational technologies. Understanding these fault lines reveals where capital concentrates and which specifications command premium positioning.
Product Type:
Hardware specifications and functional safety ratings define competitive positioning across the four product categories.
- Protection Systems:SIL-rated intelligent electronic devices with redundant tripping logic and 4 kHz sampling rates form the core of fault isolation architectures. State Grid Corporation and German transmission operators drive procurement of these systems as renewable penetration forces sub-cycle fault detection requirements.
- Communication Equipment:Time-sensitive networking switches and IEEE 1588 precision time protocol infrastructure are displacing legacy serial fieldbus protocols. Scandinavian and South Korean utilities are deploying these Ethernet-based process buses to synchronize phasor measurements across wide-area networks.
- Control Systems:Bay controllers and station-level SCADA interfaces manage circuit breaker operations and interlocking logic.
- Monitoring Solutions:Condition monitoring platforms track gas-insulated switchgear health and transformer thermal performance.
Protection Systems lead on scale; Communication Equipment leads on momentum.
Installation Type:
Capital deployment strategies split between greenfield digital-native builds and staged conversion of legacy infrastructure.
- New Installation:Greenfield digital substations with full process bus architectures and optical instrument transformers eliminate copper wiring entirely. China's coastal provinces and North Sea offshore wind clusters absorb the majority of these capital-intensive deployments.
- Retrofitting:Staged conversion of air-insulated substations preserves land assets while incrementally merging analog inputs with digital process buses. European utilities facing urban land constraints favor this approach for transmission reinforcement under EU Green Deal timelines.
- Upgrades:Partial digitalization of protection and control layers within existing substation footprints.
- Modernization:Comprehensive refurbishment of electromechanical relay systems with IEC 61850-compliant IEDs.
New Installation commands the largest capital allocation; Retrofitting gains share fastest as land scarcity bites.
End User:
Demand fragmentation intensifies as non-traditional buyers enter with distinct procurement specifications.
- Utilities:Transmission system operators and distribution utilities remain the volume anchor, mandating IEC 61850 interoperability and NERC CIP cybersecurity compliance in procurement specifications.
- Renewable Energy Providers:Offshore wind developers and solar IPPs now procure complete digital substation packages directly, bypassing traditional utility specification channels in the North Sea and East Asian clusters.
- Industrial Sector:Heavy manufacturing and petrochemical facilities deploy private substations for power quality and reliability.
- Commercial Establishments:Data centers and large commercial complexes install compact digital substations for critical load protection.
Utilities anchor volume; Renewable Energy Providers are expanding most quickly.
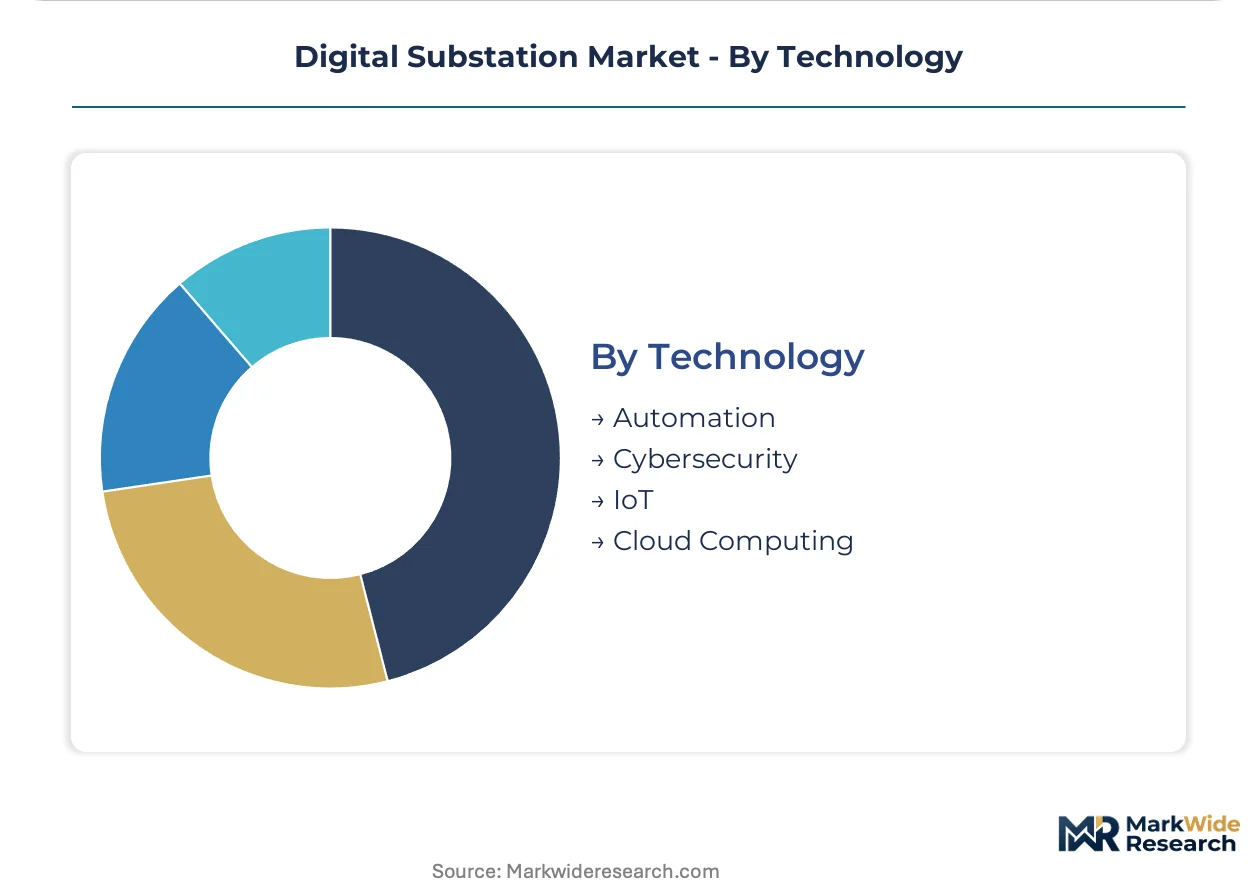
Technology:
Underlying technology stacks determine cybersecurity surface area and operational latency profiles.
- Automation:IEC 61850-based substation automation systems with GOOSE messaging and sampled value process buses enable centralized protection logic while reducing copper mass.
- Cybersecurity:NERC CIP-compliant network segmentation, encryption, and access control layers add compliance cost and engineering complexity to every deployment.
- IoT:Sensor networks for asset health monitoring and predictive maintenance.
- Cloud Computing:Edge-to-cloud data pipelines for fleet-wide analytics and remote diagnostics.
Automation leads on installed base; Cybersecurity is climbing the fastest as regulatory mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing deployment timelines where IEC 61850 mandates create compliance cost gaps between jurisdictions. Equipment manufacturers are relocating engineering resources toward markets with hardened interoperability requirements and accelerated procurement cycles.
China
State Grid Corporation drives the world's largest retrofit program, converting legacy air-insulated substations to digital process bus configurations. The country's dual carbon goals under MEE guidance mandate transmission reinforcement to accommodate renewable penetration. Jiangsu and Zhejiang provinces absorb concentrated capital expenditure for coastal digital-native substations serving offshore wind clusters.
Germany
Transmission system operators face EU Green Deal deadlines for network reinforcement with reduced SF6 volumes. The F-Gas Regulation phase-down schedule forces specification of gas-insulated switchgear with integrated condition monitoring. Industrial demand concentrates in Bavaria and Baden-Württemberg, where automotive and chemical facilities deploy private digital substations for power quality assurance.
United States
NERC CIP cybersecurity mandates impose multi-year compliance timelines on transmission operators, creating engineering capacity bottlenecks. FERC Order 2222 aggregation rules accelerate procurement of bidirectional power flow management systems. Texas and California utilities lead capital deployment, with ERCOT grid operators modernizing protection architectures to manage intermittent renewable output.
South Korea
KEPCO's smart grid investment program prioritizes sampled value process buses with IEEE 1588 precision time protocol for synchronized phasor measurement. METI-aligned standards harmonization enables multi-vendor IEC 61850 architectures. The Seoul Capital Area and Busan-Ulsan corridor concentrate deployment of compact gas-insulated digital substations for urban transmission densification.
United Kingdom
Ofgem's RIIO-2 price control framework incentivizes transmission asset replacement with digital-native designs. Offshore wind consortia in the North Sea cluster now procure complete substation packages directly, bypassing traditional National Grid specification channels. Scotland and Northeast England host the densest concentration of developer-led digital substation deployment for renewable integration.
Digital Substation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in utility-scale procurement while component suppliers capture volume in retrofit applications. The vendor base organizes around three strategic archetypes: full-stack automation integrators, protection-specialist relay manufacturers, and networking infrastructure providers. Consolidation pressure intensifies as utilities demand single-source accountability for multi-vendor IEC 61850 architectures. Dominant competitive moves include vertical integration into optical sensor manufacturing and strategic partnerships between switchgear OEMs and cybersecurity software vendors.
Within the full-stack automation tier, Siemens Energy and ABB occupy positions anchored by European utility modernization programs, while Hitachi Energy exemplifies the Asia-Pacific gas-insulated switchgear specialist model. These three companies represent distinct geographic anchoring strategies—German engineering-centric, Swiss-Swedish integrated platform, and Japanese-Korean compact design leadership—that shape how procurement specifications propagate across regional markets.
| Leading Market Players |
|---|
| Hitachi Energy |
| Eaton Corporation |
| Siemens Energy |
| Cisco Systems |
| Toshiba Energy Systems & Solutions |
| GE Vernova |
| Schneider Electric |
| Honeywell International |
| ABB |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation phase-down schedule gates qualified supply for gas-insulated switchgear and compresses premium-tier pricing access to manufacturers with integrated condition monitoring and reduced SF6 architectures. State Grid Corporation procurement specifications in China simultaneously enforce multi-vendor IEC 61850 interoperability, fragmenting pricing power across protection system suppliers.
Pricing Analysis
Distributor margins in utility-scale procurement compress to single digits as direct manufacturer-to-utility contracting dominates transmission system operator relationships. Project-based pricing stratifies across premium, standard, and economy tiers based on SIL certification level and after-sales service bundling. Pricing pressure stems from copper-fiber transition costs in retrofit architectures, squeezing margins on brownfield deployments. Renewable energy providers demonstrate highest price sensitivity due to developer-led procurement bypassing traditional utility specification channels, while transmission system operators absorb premium pricing for NERC CIP-compliant cybersecurity layers.
Supply Chain Analysis
Dual-sourcing requirements from German and South Korean utilities mandate multi-supplier qualification for intelligent electronic devices and time-sensitive networking switches, fragmenting procurement across Hitachi Energy, Siemens Energy, and ABB. Manufacturing concentrates in Germany, Japan, and China for gas-insulated switchgear and protection relay assembly. Supply chains draw from optical fiber cable, precision time protocol chipsets, and rare-earth magnet dependencies for merging units. Single-source vulnerability in IEEE 1588 clock synchronization hardware creates chokepoint exposure. Distribution runs through EPC contractors and direct OEM relationships for offshore wind clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European IEC 61850 mandate acceleration and North American NERC CIP compliance timeline delays, with the latter imposing multi-year engineering capacity constraints that inflate qualified supplier pricing power.
For Market Incumbents: Deploy IEC 61850 edition 2.1 certification investment to lock out competitors facing interoperability commissioning delays from multi-vendor integration risk. Anchor backward integration into optical current transformer manufacturing to capture margin from copper-fiber transition demand. Consolidate engineering talent pools in protection relay commissioning to defend against specialized substation automation engineer scarcity threatening project delivery timelines. For New Entrants and Emerging Players: Edge-computing platforms with sub-millisecond decision latency represent the most penetrable technology-first wedge into protection system architectures dominated by legacy relay manufacturers. Target brownfield retrofit architectures in European urban transmission reinforcement where land constraints prevent greenfield construction and incumbent switchgear OEMs lack staged conversion expertise. Pursue direct procurement relationships with North Sea offshore wind consortia bypassing traditional transmission system operator specification channels. For Investors and Strategic Acquirers: Roll-up economics work for cybersecurity software vendors with NERC CIP compliance tooling because utility procurement specifications now mandate network segmentation and encryption layers as non-negotiable contract terms. Acquire mid-cap protection relay specialists with SIL-rated hardware certification and established German or South Korean utility relationships. Watch IEC 61850 edition mismatch resolution between protection IED suppliers as the inflection signal for multi-vendor architecture commissioning timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sensor Manufacturing Integration | Captures margin from copper-fiber transition costs in State Grid retrofit programs. |
| Cybersecurity Software Partnership | Addresses NERC CIP multi-year compliance timelines constraining North American deployment. |
| Offshore Wind Direct Procurement Channel | Bypasses traditional utility specification channels in North Sea and East Asian clusters. |
| Precision Time Protocol Hardware Sourcing | Mitigates single-source vulnerability in IEEE 1588 clock synchronization chipsets. |
| IEC 61850 Edition 2.1 Certification Investment | Locks out competitors facing multi-vendor integration commissioning delays. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, grid operators, and substation automation engineers with secondary validation from IEC standards documentation, FERC filings, EIA transmission asset databases, and project development registries. Bottom-up equipment procurement tracking and top-down transmission reinforcement budget analysis triangulated market sizing across protection systems, communication equipment, control systems, and monitoring solutions.
Segment-weighting approaches applied differential growth assumptions across new installation, retrofitting, upgrade, and modernization deployment contexts, with additional weighting for utility, renewable energy provider, industrial, and commercial end-user demand fragmentation. CAGRs derived from equipment shipment trajectories and capital expenditure pipeline analysis across the projection horizon, incorporating renewable penetration rates, F-Gas Regulation compliance deadlines, and smart grid investment program allocations as industry-specific forecast inputs.
The model holds under stable IEC 61850 standards harmonization and sustained utility capital expenditure commitment; deviation in cybersecurity disclosure rule acceleration or copper-fiber transition cost inflation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Power Transmission Cables Market