
 United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market Analytics
Modular multilevel converter topology is reconfiguring how HVDC stations are engineered and commissioned across British waters. Prysmian Group leverages its submarine cable manufacturing footprint to anchor supply security for North Sea link projects. Siemens AG sustains technology leadership through proprietary converter valve platforms purpose-built for offshore collector platforms. Hitachi Ltd competes on integrated control system architectures that unify AC-DC conversion with grid-forming inverters.
High-Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity over long distances with lower resistive losses than alternating current, typically operating at voltage levels exceeding 100 kV and serving primarily to interconnect asynchronous grids or deliver remote renewable generation to demand centers. Voltage Source Converter technology dominates new UK project awards due to its black-start capability and compact footprint suitable for offshore platforms. Offshore Wind Integration application demand is outpacing interconnection builds as lease round four and five developments commit to HVDC export rather than radial AC strings. Underground installation type is gaining share in England's densely populated corridors where planning consent for overhead lines faces sustained local opposition.
Ofgem's electricity transmission price control reviews shape network operator capex allowances and thereby gate HVDC project timelines. National Grid ESO's clean power 2030 framework and the UK government's offshore transmission network review are tightening technical standards for multi-terminal DC configurations. BEIS and the Planning Inspectorate jointly determine consenting pathways for cross-border links and subsea corridors. Stakeholders must monitor how regulatory asset base treatment evolves for anticipatory transmission investments ahead of generation commitment.
Market Dynamics
Scotland's offshore wind lease rounds are forcing converter station investments ahead of grid reinforcement completion, compressing project timelines and concentrating engineering resources around the North Sea.
Growth Catalysts
- Contracts for Difference scheme:The UK government's CfD mechanism redirects developer capital toward HVDC export cables rather than radial AC strings, accelerating procurement for Round 4 and 5 wind farms.
- Voltage Source Converter topology:Black-start capability and compact platform footprints are displacing Line-Commutated Converter technology in new North Sea interconnectors.
- Clean Power 2030 framework:National Grid ESO's target timeline tightens technical standards and accelerates consenting for multi-terminal DC configurations connecting Scottish generation to England.
Market Restraints
- Copper and rare earth input volatility:Converter valve manufacturing depends on dysprosium and terbium supply concentrated in Chinese processing facilities, creating price uncertainty for station components.
- Planning consent friction:England's densely populated eastern corridors face sustained local opposition to overhead lines, forcing expensive underground cable routes through the Planning Inspectorate.
- Specialized vessel scarcity:Cable-laying fleet capacity for subsea HVDC installation concentrates among Northern European operators, creating installation bottlenecks during peak construction windows.
Strategic Opportunities
- Wales and Southwest England interconnectors:Underpenetrated western seaboard routes offer white space for cross-border links to Irish and French grids, diversifying beyond North Sea concentration.
- Grid-forming inverter convergence:Integration of HVDC converters with synchronous condenser functionality creates new revenue streams from ancillary services markets.
- Anticipatory transmission treatment:Ofgem's evolving regulatory asset base rules may permit network operators to recover costs for capacity built ahead of generation commitment.
Industry Challenges
- Power electronics engineering talent gap:Converter station design and commissioning require specialized skills in modular multilevel control systems that outpace UK university output.
- Multi-vendor integration complexity:Projects combining submarine cables from one supplier with converter platforms from another face interface risk during offshore commissioning.
- Subsea cable repair response time:Fault location and recovery operations in North Sea conditions demand specialized assets with limited availability, extending outage duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market |
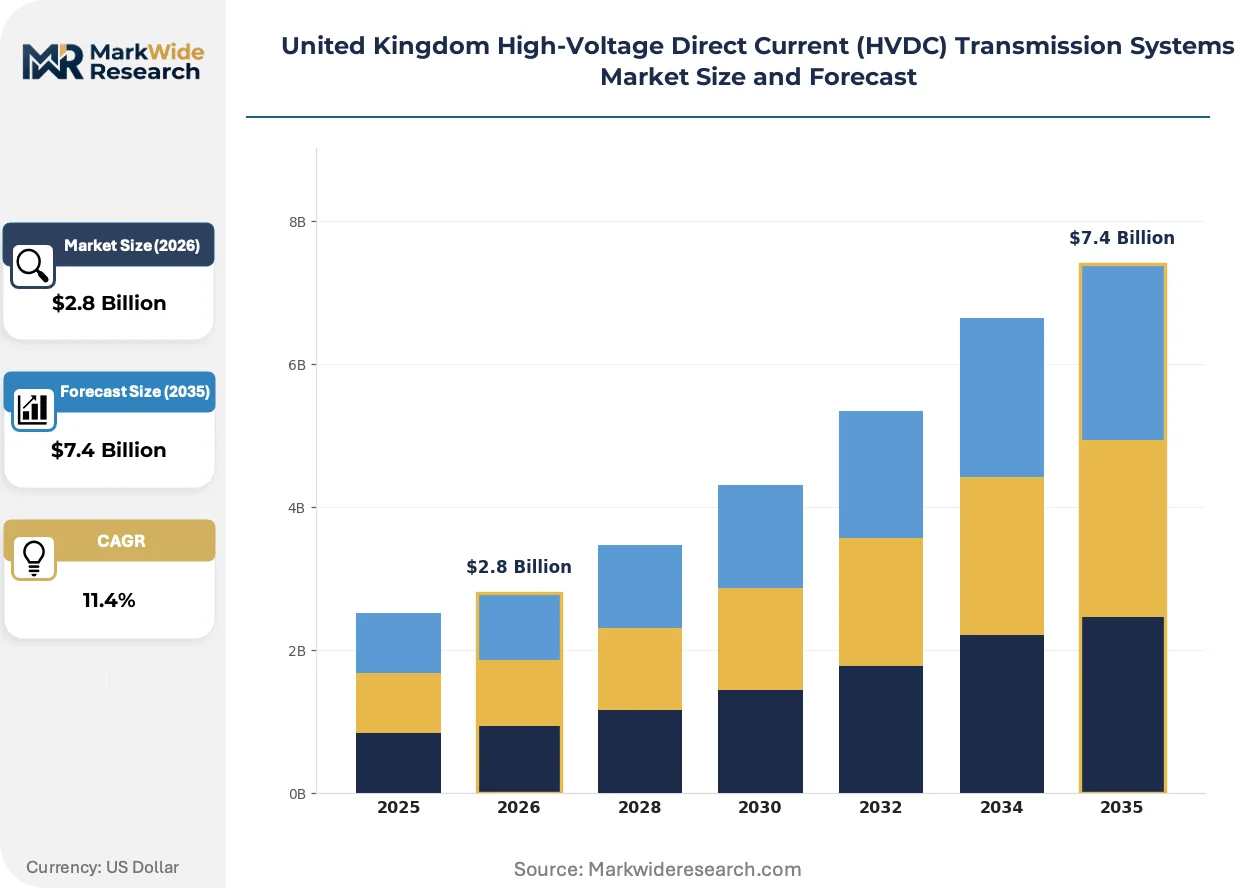
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voltage Source Converter, Line Commutated Converter, Control System, Transmission Circuit Application: Offshore Wind Integration, Interconnection, Energy Trading, Grid Stability End User: Utilities, Independent Power Producers, Industrial Users, Government Agencies Installation Type: Onshore, Offshore, Hybrid, Underground |
| Companies Covered | Prysmian Group, Mitsubishi Electric Corporation, Siemens AG, Hitachi Ltd, Schneider Electric SE, ABB Ltd, Toshiba Corporation, Alstom SA, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market Evolving Landscape
Modular construction methods and digital twin commissioning are compressing project delivery schedules while tightening performance guarantees for offshore HVDC infrastructure.
Hybrid AC-DC collector platforms are rendering obsolete traditional radial AC string architectures for wind farms exceeding 1.5 GW capacity. Developers of Dogger Bank and Hornsea zones are specifying integrated HVDC export from the planning stage, eliminating intermediate AC substations and reducing offshore electrical infrastructure mass by approximately forty percent.
Ofgem's RIIO-T2 price control review tightened allowed returns and introduced output-based incentive mechanisms for transmission network operators. The regulatory shift forces National Grid and Scottish Power Transmission to prioritize asset availability metrics over capital expenditure maximization, reshaping procurement evaluation criteria toward lifecycle performance rather than upfront cost.
Long-term service agreements now bundle cable monitoring, converter maintenance, and availability guarantees into single-contract structures spanning twenty-five years. Offshore wind farm operators are displacing traditional break-fix maintenance models with integrated performance contracts, transferring operational risk to original equipment manufacturers and concentrating vendor selection on service capability rather than component pricing alone.
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
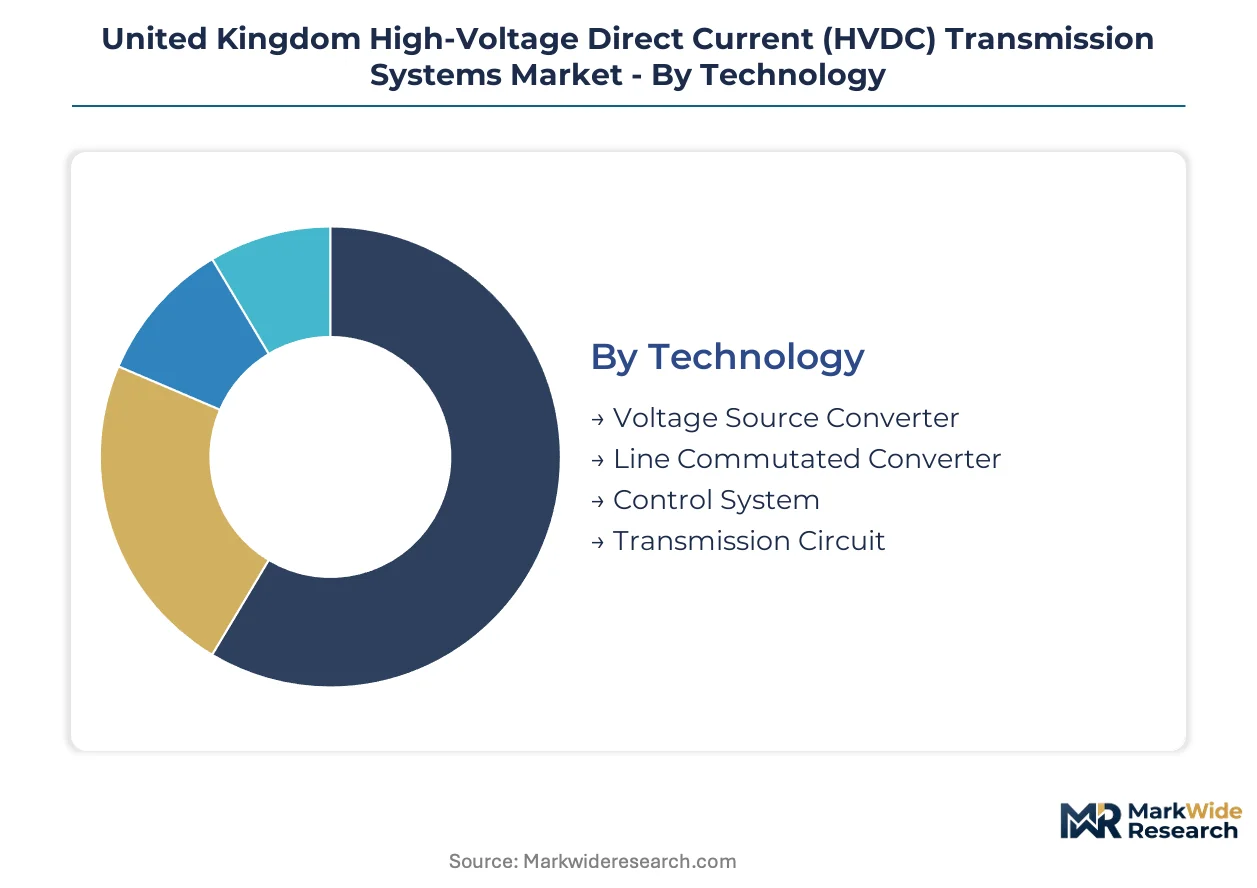
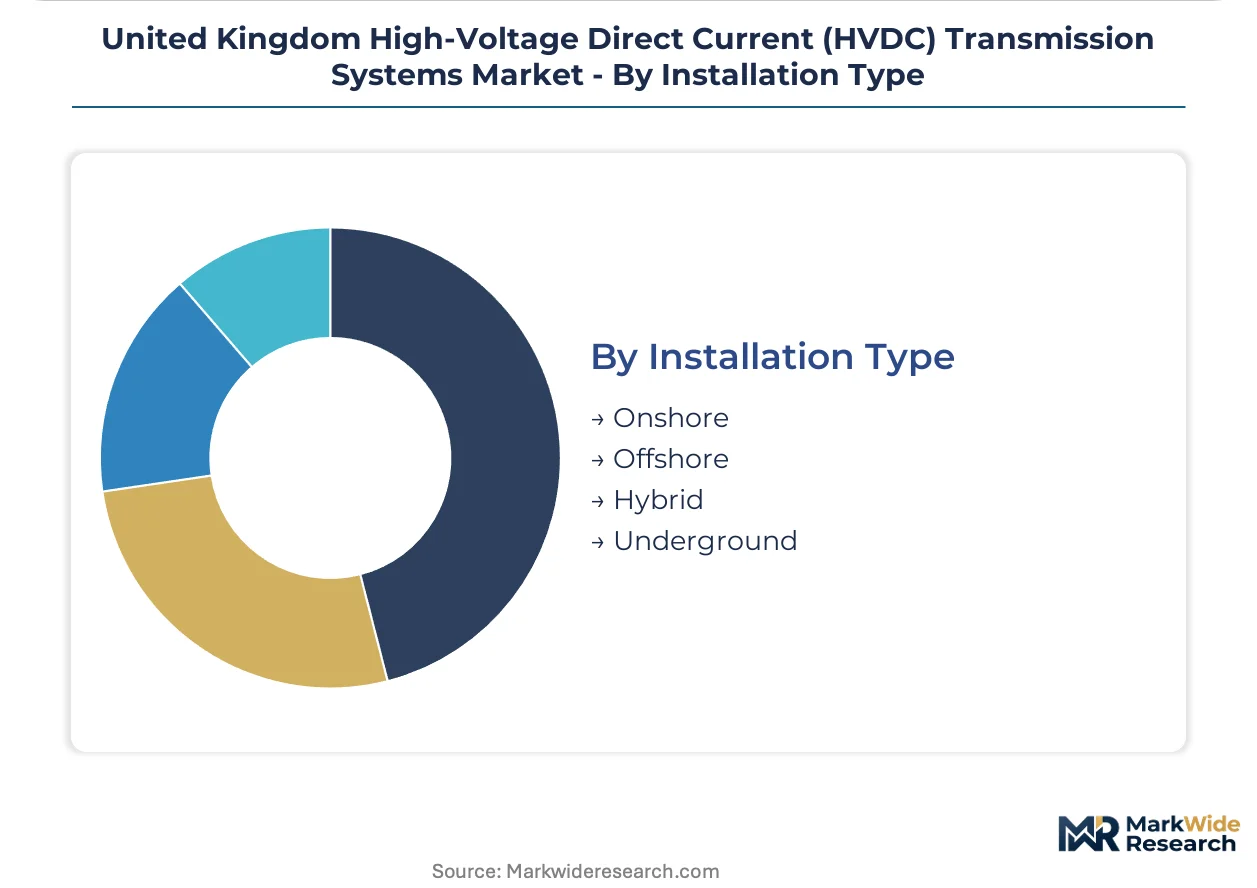
Segmentation of United Kingdom HVDC transmission systems reveals how procurement patterns concentrate around converter technology choices and installation constraints. Each dimension carries distinct service intensity profiles that reshape vendor relationships and contract structures across North Sea developments.
Technology:
After-sales service intensity varies sharply across converter architectures, with modular multilevel designs demanding specialized control system expertise throughout operational life.
- Voltage Source Converter:Employs insulated-gate bipolar transistors arranged in modular cascades to enable bidirectional power flow and black-start capability. Scottish offshore wind developers specify this topology for Dogger Bank and Hornsea zones where compact platform footprints outweigh capital cost premiums. Converter station vendors bundle twenty-five-year availability guarantees with predictive maintenance algorithms to capture recurring revenue streams.
- Line Commutated Converter:Relies on thyristor-based switching with synchronous condenser support for commutation, suited to high-capacity bulk transmission with lower semiconductor counts. England's eastern seaboard interconnection projects retain this mature technology where converter stations sit onshore with space for harmonic filter compounds. National Grid ESO's clean power framework is accelerating displacement by voltage source alternatives.
- Control System:Integrates modular multilevel converter gate drives with grid-forming inverter algorithms and real-time digital simulators for hardware-in-the-loop commissioning.
- Transmission Circuit:Encompasses DC smoothing reactors, surge arresters, and metallic return conductors configured for bipolar or monopolar operation.
By volume, Voltage Source Converter leads. By growth pace, Control System is expanding most quickly.
Application:
Project economics diverge based on whether HVDC infrastructure serves generation collection or cross-border arbitrage functions.
- Offshore Wind Integration:Connects remote North Sea generation clusters to onshore load centers through dedicated export cables and offshore converter platforms. Round four and five lease commitments in Scottish waters are compressing procurement timelines as developers pre-commit to HVDC export before grid reinforcement completion. Hybrid AC-DC collector designs eliminate intermediate substations for wind farms exceeding 1.5 GW capacity.
- Interconnection:Links asynchronous AC grids across national boundaries to enable capacity sharing and security of supply. Western seaboard routes to Irish and French grids remain underpenetrated relative to North Sea concentration, creating white space for new project development. BEIS and the Planning Inspectorate jointly determine consenting pathways for these cross-border corridors.
- Energy Trading:Facilitates wholesale market arbitrage across price zones through controllable DC power flow.
- Grid Stability:Provides synthetic inertia and frequency response services through grid-forming converter control.
Offshore Wind Integration commands the largest capital deployment. Interconnection offers the steepest expansion trajectory for merchant revenue models.
End User:
Risk allocation structures differ fundamentally between regulated network operators and competitive generation developers.
- Utilities:Regulated transmission owners recover HVDC investments through Ofgem's price control mechanisms with output-based availability incentives. National Grid and Scottish Power Transmission prioritize lifecycle performance metrics over upfront capital minimization under RIIO-T2 frameworks.
- Independent Power Producers:Offshore wind farm developers bear full construction risk and negotiate long-term service agreements transferring operational liability to equipment vendors. Contracts for Difference scheme redirect capital toward HVDC export cables rather than radial AC strings.
- Industrial Users:Large electricity consumers invest in private interconnection links to secure direct renewable supply.
- Government Agencies:Coordinate strategic network planning through National Grid ESO and BEIS policy frameworks.
Utilities dominate installed base. Independent Power Producers are driving capacity additions.
Installation Type:
Physical deployment constraints dictate cable technology selection and marine licensing complexity.
- Offshore:Submarine cable corridors across North Sea waters require specialized laying vessels and burial protection systems. Cable-laying fleet capacity concentrates among Northern European operators, creating installation bottlenecks during peak construction windows. Prysmian Group anchors supply security through dedicated manufacturing footprint for British waters.
- Underground:Land cable routes through England's densely populated eastern corridors avoid planning consent friction for overhead lines. Forced undergrounding through the Planning Inspectorate adds thirty to fifty percent capital cost premiums versus overhead equivalents.
- Onshore:Converter stations and cable terminations occupy substation compounds with standard civil works.
- Hybrid:Combines offshore submarine sections with onshore underground or overhead transitions.
Offshore claims the highest unit values. Underground is gaining share fastest where planning constraints bite hardest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HVDC equipment flows from continental European manufacturers into British North Sea developments, with converter stations and submarine cables crossing the Channel to serve Scottish offshore wind zones and England's eastern seaboard reinforcement corridors.
Scotland
Dogger Bank and Hornsea lease rounds are compressing converter station procurement timelines ahead of grid reinforcement completion. Ofgem's RIIO-T2 price control shapes transmission operator investment allowances for North Sea link projects. Aberdeen and Peterhead anchor the offshore engineering cluster where cable-laying vessels stage for subsea corridor construction.
North England
Grid reinforcement demand concentrates around the eastern seaboard where HVDC terminals connect Scottish generation to southern load centers. BEIS and the Planning Inspectorate jointly determine consenting pathways for cross-border link corridors. Teesside and Humberside host converter station compounds and marine logistics bases for cable installation fleets.
East England
Planning consent friction for overhead lines is forcing underground cable routes through densely populated corridors. National Grid ESO's clean power 2030 framework tightens technical standards for multi-terminal DC configurations. Great Yarmouth and Lowestoft serve as marine coordination hubs for North Sea submarine cable laying operations.
Wales
Western seaboard interconnection routes to Irish and French grids remain underpenetrated relative to North Sea concentration. BEIS coordinates strategic network planning for Celtic Sea and Irish Sea link developments. Milford Haven and Holyhead position for converter station investment if cross-border projects advance through regulatory approval.
South England
Underground installation type is gaining share fastest where local opposition blocks overhead line consent through the Planning Inspectorate. National Grid ESO's output-based incentive mechanisms prioritize asset availability over capital expenditure maximization. Southampton and Portsmouth anchor southern cable landing points for cross-Channel interconnection feasibility studies.
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across converter station and submarine cable procurement. The vendor base concentrates around integrated platform providers and component specialists serving North Sea offshore wind integration. Three archetypes dominate: full-system integrators bundling converter and cable solutions, converter technology specialists licensing valve platforms, and cable manufacturers anchoring supply security through dedicated production footprints. Capacity expansion and long-term service agreement bundling represent the dominant competitive moves reshaping contract structures.
Among European-integrated industrial groups, Prysmian Group, Siemens AG, and Hitachi Ltd occupy distinct positions within the HVDC value chain. Prysmian Group anchors submarine cable supply security for British waters through dedicated manufacturing infrastructure. Siemens AG exemplifies the converter platform specialist archetype with proprietary valve technology deployment. Hitachi Ltd sits within the control system integration tier, unifying AC-DC conversion architectures with grid-forming functionality. These three entities represent how vendor selection criteria have shifted toward lifecycle service capability rather than component pricing alone.
| Leading Market Players |
|---|
| Prysmian Group |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Hitachi Ltd |
| Schneider Electric SE |
| ABB Ltd |
| Toshiba Corporation |
| Alstom SA |
| General Electric Company |
| Others |
Value Network & Pricing Analysis
North Sea cable-laying corridor cost dynamics concentrate pricing power among Northern European vessel operators while forcing project developers to absorb premium logistics charges through differentiated contract structures for converter stations and submarine cable bundles.
Pricing Analysis
Voltage Source Converter platform pricing stratifies across Line-Commutated Converter legacy systems, current-generation modular multilevel installations, and next-generation grid-forming hybrid architectures. Project-based long-term offtake contracts dominate, with price differentiation hinging on after-sales service bundling and converter valve semiconductor grade. Cost compression in standard LCC configurations is intensifying because Chinese rare earth processing concentration feeds input volatility. Independent Power Producers exhibit highest price sensitivity due to CfD scheme margin constraints, while Utilities accept lifecycle cost premiums under RIIO-T2 output-based incentives.
Supply Chain Analysis
Export control regimes restricting power semiconductor and high-voltage cable technology flows limit converter valve sourcing to Germany, Japan, and Switzerland, while submarine cable manufacturing concentrates in Italy, Norway, and Japan. Converter station assembly draws from dysprosium and terbium rare earth feedstock anchored in Chinese processing facilities, plus epoxy resin compounds and copper conductor stock. Single-source vulnerability in specialized cable-laying vessel availability creates installation bottleneck risk. Distribution runs through EPC contractor-led turnkey procurement with original equipment manufacturers embedding twenty-five-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent scarcity constrains converter station commissioning velocity, creating acquisition premiums for firms with proven modular multilevel control system expertise.
For Market Incumbents: Entrench technology leadership by backward integration into semiconductor valve manufacturing and captive supply of rare earth processing partnerships. Prysmian Group's dedicated UK cable manufacturing footprint demonstrates how geographic production anchoring defends against vessel logistics chokepoints. Prioritize long-term service agreement bundling to capture recurring revenue streams and lock out specialist maintenance entrants. For New Entrants and Emerging Players: Wales and Southwest England interconnection routes offer white space with lower incumbent saturation than North Sea corridors. Celtic Sea and Irish Sea link developments present penetrable entry points where BEIS consenting pathways remain underexploited. Target grid-forming inverter convergence opportunities as merchant ancillary services revenue streams detach from pure infrastructure plays. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with stranded HVDC technology divisions lacking integrated service capabilities. Five-to-ten-year viability hinges on converter platform vendors capturing anticipatory transmission treatment under evolving Ofgem regulatory asset base rules. Monitor Ofgem RIIO price control review timelines as inflection signals for network operator capex release schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Converter Platform Capacity Expansion | Siemens AG and Hitachi Ltd are scaling UK engineering centers to match Scottish offshore wind lease round procurement velocity. |
| Submarine Cable Manufacturing Footprint | Prysmian Group anchors supply security through dedicated British waters production infrastructure reducing vessel logistics exposure. |
| Long-Term Service Agreement Bundling | Twenty-five-year availability guarantees transfer operational risk from Independent Power Producers to original equipment manufacturers. |
| Grid-Forming Inverter Convergence | Integration with synchronous condenser functionality creates merchant revenue streams from National Grid ESO ancillary services markets. |
| Anticipatory Transmission Investment | Ofgem regulatory asset base evolution may permit cost recovery for capacity built ahead of generation commitment. |
Research Methodology
The analysis maps converter technology sub-sectors, installation type configurations, and end-user risk allocation structures, each validated through transmission network planners, offshore wind farm developers, EPC contractors, and power electronics engineering specialists. Primary interview data triangulates against Ofgem RIIO-T2 documentation, BEIS offshore transmission network review filings, National Grid ESO clean power framework disclosures, and submarine cable project development databases. Bottom-up project pipeline aggregation reconciles with top-down regulatory capex allowance modeling.
Assumptions held fixed include Ofgem price control mechanisms and Contracts for Difference scheme continuity, while technology substitution rates and vessel fleet availability were varied across sensitivity scenarios. Segmentation dimensions span converter topology, application function, end-user regulatory status, and installation environment. CAGRs derive from installed capacity buildout trajectories matched against supply-side engineering resource constraints. Forecast inputs incorporate offshore wind lease round commitment schedules and cross-border interconnection consenting pathway timelines.
Practitioners should monitor Ofgem regulatory asset base treatment evolution and cable-laying vessel fleet expansion announcements for early signals of project timeline compression or extension. Forecasts reflect these documented assumptions. Material shifts in rare earth export control regimes or Contracts for Difference scheme redesign would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market