
 High Voltage Transmission Substation Market | 2026-2036
High Voltage Transmission Substation Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Transmission Substation Market Insights
Long-term service contracts for asset performance management is hardening into a core revenue stream for substation vendors. Hitachi Energy leverages its Lumada platform to anchor predictive maintenance revenue across European transmission grids. Siemens Energy sustains competitive differentiation through in-house production of high-voltage direct current converter valves. ABB dominates digital substation software integration, positioning its Ability platform as the control layer for utility automation.
High voltage transmission substations are facilities that switch, transform, and regulate electrical power at voltages typically exceeding 72.5 kV, using gas-insulated or air-insulated architectures to manage load flows across regional and national grids. Their primary purpose is to step up generation output for efficient long-distance transport and step down voltage for distribution networks while maintaining grid stability through protection and control systems. Gas insulated substations command premium pricing due to footprint constraints in dense urban corridors, while air insulated configurations retain cost advantages for greenfield rural installations. Circuit breaker technology within the equipment layer absorbs significant capital allocation as utilities replace aging sulfur hexafluoride-dependent units with vacuum or hybrid interruption mechanisms.
The Federal Energy Regulatory Commission in the United States mandates transmission planning standards that directly shape substation investment timelines, while the EU F-Gas Regulation accelerates replacement cycles for gas-insulated equipment across member states. China's National Energy Administration enforces grid reliability benchmarks that require automated substation controls in new transmission corridors. Stakeholders must monitor how digital twin integration and synthetic insulating medium maturation alter equipment procurement specifications and vendor qualification criteria.
Market Dynamics
The EU F-Gas Regulation is forcing accelerated retirement of sulfur hexafluoride-insulated equipment across European transmission networks, compressing replacement cycles and rewiring vendor qualification criteria toward vacuum interruption and synthetic gas alternatives.
Growth Catalysts
- Interstate renewable corridors:India's Green Energy Corridors program mandates new 765 kV substations to evacuate solar and wind generation from Rajasthan and Gujarat to demand centers.
- SF6 phase-down mandates:The EU F-Gas Regulation imposes strict quotas on fluorinated gas use, compelling utilities to specify SF6-free switchgear in procurement tenders.
- IEC 61850 standardization:Digital substation protocols enable centralized protection and control architectures that reduce copper wiring and commissioning time.
Market Restraints
- Copper and aluminum price volatility:Raw material swings compress margins for busbar and transformer manufacturers, forcing price escalation clauses into long-lead contracts.
- GIS equipment supply concentration:Gas-insulated switchgear production clusters in Germany, Japan, and South Korea, exposing buyers to extended lead times during capacity constraints.
- Vacuum interruption voltage ceilings:Current vacuum breaker technology faces dielectric limitations above 145 kV in certain configurations, slowing full SF6 displacement.
Strategic Opportunities
- Sub-Saharan Africa grid extension:Power transmission infrastructure in Nigeria, Kenya, and Ethiopia remains underdeveloped, creating first-mover positioning for modular air-insulated substations.
- Digital twin integration:Convergence of physics-based simulation with real-time sensor data enables predictive asset management contracts that extend vendor revenue streams.
- US Inflation Reduction Act transmission incentives:Federal cost-sharing mechanisms for interregional transmission projects expand addressable substation capacity in the Mountain West and Southwest.
Industry Challenges
- Protection engineer scarcity:Specialized expertise in relay coordination and cybersecurity for IEC 61850 architectures commands premium compensation, constraining project execution capacity.
- Legacy electromechanical system integration:Digital control retrofits into 1970s-era air-insulated substations require custom protocol gateways and extended outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Transmission Substation Market |
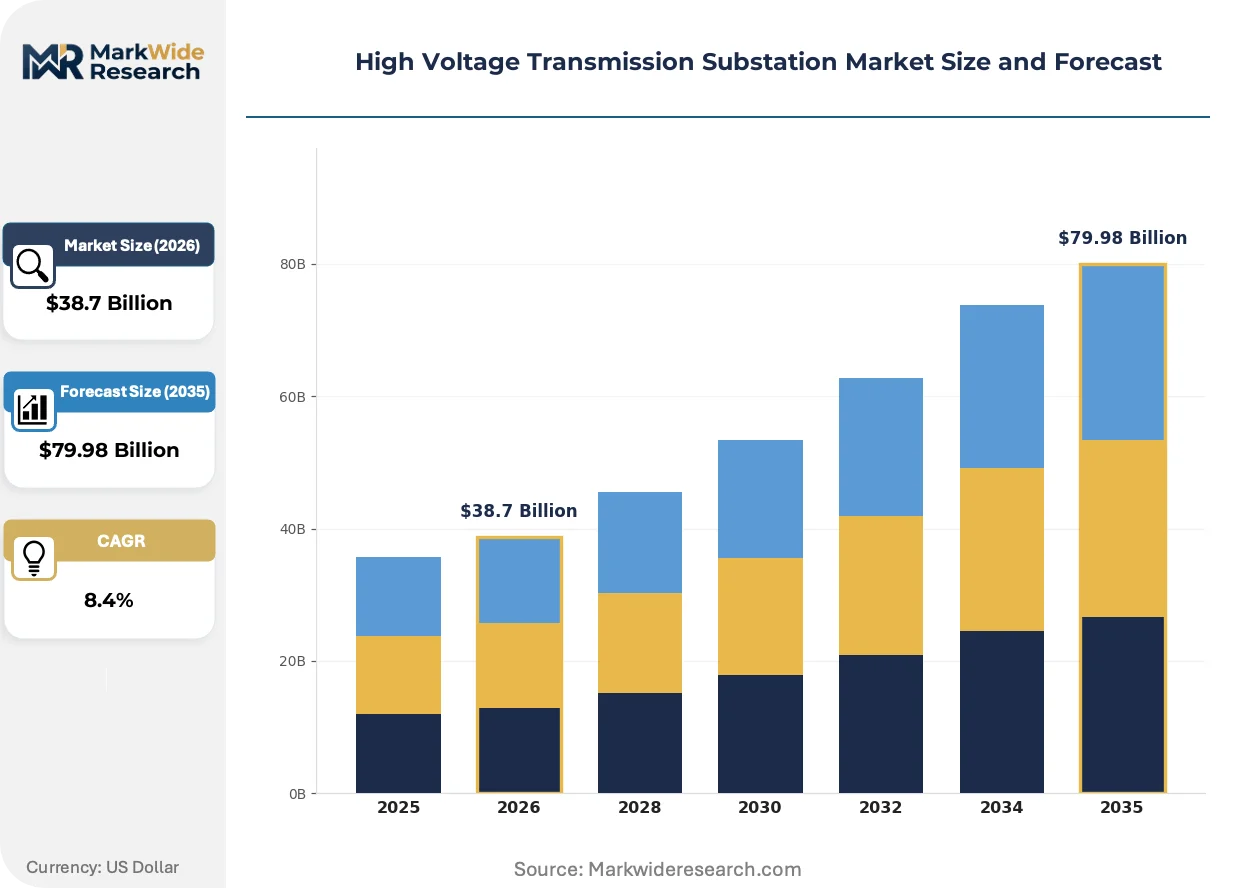
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas Insulated, Air Insulated, Hybrid, AIS-GIS Combination Equipment Technology: Circuit Breakers, Disconnectors, Current Transformers, Voltage Transformers, Surge Arresters Application: Electric Utilities, Independent Power Producers, Industrial Facilities, Renewable Power Integration End User: Transmission Operators, Distribution Companies, Grid Operators, Energy Regulators |
| Companies Covered | Hitachi Energy, Siemens Energy, ABB, General Electric, Schneider Electric, Eaton, Mitsubishi Electric, Toshiba, Hyundai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Transmission Substation Market Trends and Innovations
Synthetic insulating media and solid-state protection systems are displacing conventional gas and electromechanical architectures across high-voltage transmission infrastructure. These shifts compress equipment lifecycles while opening new service revenue models.
Fluoronitrile-based insulating gas mixtures are electrifying the switchgear segment by delivering comparable dielectric performance to SF6 at materially reduced global warming potential. European utilities led by German and French transmission system operators are piloting 145 kV GIS bays with this medium. The technology is compressing the addressable market for conventional SF6 equipment and accelerating patent positioning around gas handling and reclamation processes.
The EU F-Gas Regulation tightens annual quotas on fluorinated greenhouse gases through 2030, with step-down provisions that directly constrain SF6 availability for new equipment. Manufacturers must certify leak rates below 0.1 percent annually and fund end-of-life reclamation. This regulatory pressure is concentrating procurement specification revisions in Germany, Italy, and the Nordic markets, where transmission operators face the earliest compliance deadlines.
Asset performance management contracts are unbundling from equipment supply agreements, with utilities separating capital procurement from long-term service obligations. European transmission operators now tender predictive maintenance and condition monitoring as standalone lots, displacing traditional time-based maintenance schedules. This bifurcation is most advanced in the United Kingdom and Netherlands, where regulatory frameworks permit opex treatment of digital monitoring expenditures.
High Voltage Transmission Substation Market Segmentation
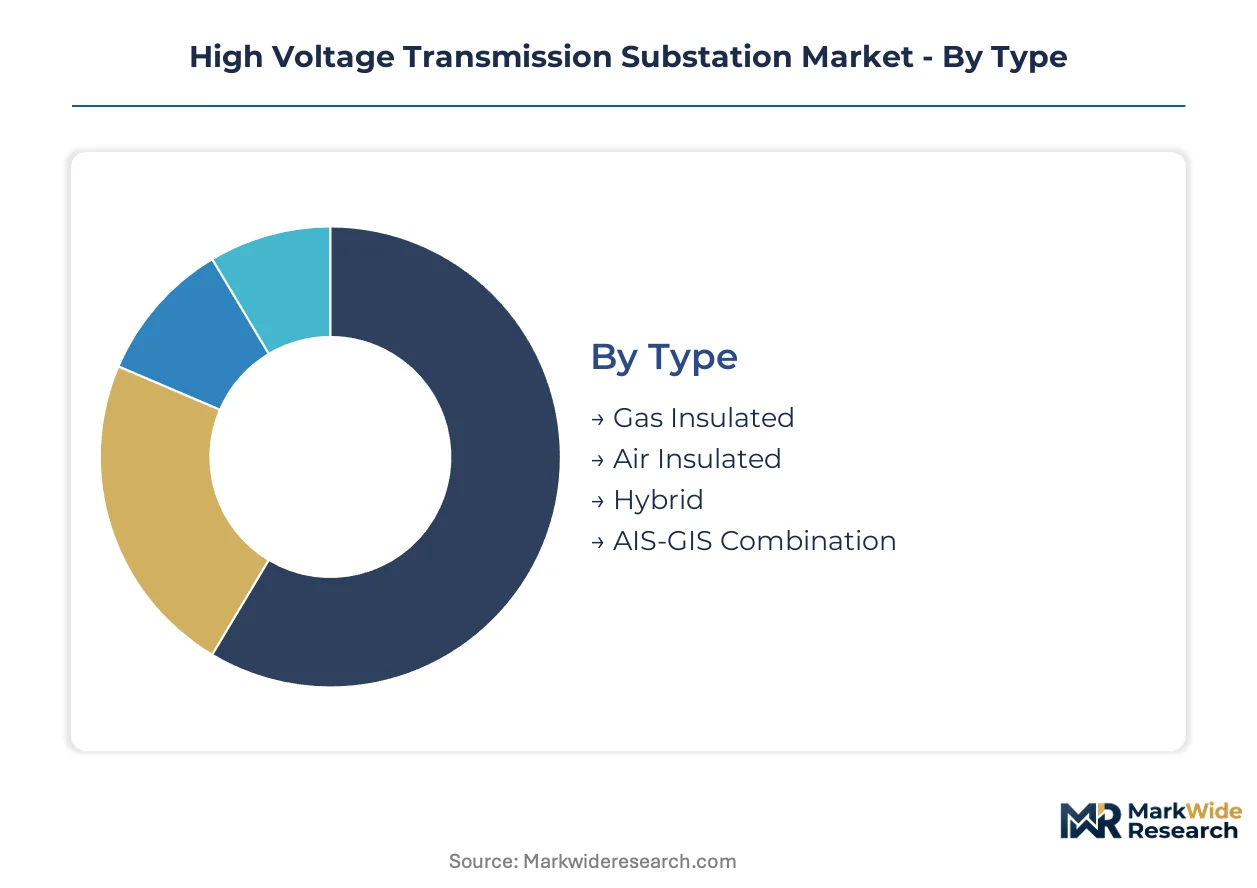
Substation procurement decisions pivot on footprint constraints, environmental compliance timelines, and voltage rating requirements. Each segmentation dimension captures a distinct layer of buyer prioritization—from architectural topology to regulatory stakeholder influence.
Type:
Site footprint availability and urban density dictate architectural selection, with environmental regulations now exerting equal weight in European tenders.
- Gas Insulated:SF6 or synthetic gas-filled enclosures enable 70% smaller footprints than air-insulated equivalents, critical for dense urban corridors in Germany and Japan. Japanese utilities specify these for Tokyo-Osaka corridor upgrades where land scarcity commands premium construction costs.
- Air Insulated:Open-air busbar arrangements dominate rural greenfield installations across India and the United States, offering lower capital outlay where land is abundant. India's Green Energy Corridors program deploys these extensively across Rajasthan desert solar zones.
- Hybrid:Mixed configurations combine GIS bays for high-density zones with AIS extensions for peripheral connections, optimizing capital deployment across heterogeneous terrain.
- AIS-GIS Combination:Retrofit-friendly architectures allow phased modernization of legacy substations, preserving existing AIS infrastructure while adding compact GIS modules for capacity expansion.
Air Insulated leads on scale; Gas Insulated leads on momentum.
Equipment Technology:
Interruption medium selection now carries regulatory compliance implications that reshape equipment replacement cycles.
- Circuit Breakers:Vacuum interruption mechanisms below 145 kV and hybrid designs above this threshold are displacing SF6-dependent units under EU F-Gas Regulation quotas. German transmission operators now mandate SF6-free specifications in all new 420 kV procurement.
- Disconnectors:Motorized disconnectors with integrated position monitoring enable remote operation sequences required by IEC 61850 digital substation architectures.
- Current Transformers:Optical and Rogowski coil designs eliminate magnetic saturation risks in high-fault-current corridors, gaining traction in Chinese ultra-high voltage projects.
- Voltage Transformers:Capacitive voltage transformers with digital output interfaces reduce wiring complexity in digital substation retrofits across United Kingdom transmission networks.
- Surge Arresters:Metal-oxide varistor technology with polymer housings replaces porcelain in seismically active zones, particularly across Japan and California installations.
Circuit Breakers command the largest capital allocation; optical instrument transformers are expanding most quickly.
Application:
Revenue model differentiation separates capital-intensive utility builds from service-oriented industrial deployments.
- Electric Utilities:Vertically integrated transmission owners in the United States and state-owned operators in China drive volume procurement through decade-long capital programs. FERC Order 1000 compliance mandates drive interregional transmission investments.
- Independent Power Producers:Merchant renewable developers require modular substation solutions for rapid grid connection, prioritizing standardized designs over custom engineering.
- Industrial Facilities:Mining and petrochemical complexes in Australia and Chile specify captive substations with enhanced reliability tiers for continuous process operations.
- Renewable Power Integration:Offshore wind connection points in the North Sea and North American Great Lakes demand specialized GIS platforms rated for saline environments.
Electric Utilities lead on scale; Renewable Power Integration leads on momentum.
End User:
Regulatory and operational roles determine procurement authority and technical specification control.
- Transmission Operators:National and regional TSOs in Germany, France, and the United States define equipment standards through framework agreements that cascade to distribution counterparts.
- Distribution Companies:Local utilities concentrate demand for medium-voltage transformation and urban distribution substations, particularly across Indian state electricity boards.
- Grid Operators:Independent system operators in Texas and Australia coordinate interconnection standards without direct asset ownership, influencing technical requirements through connection codes.
- Energy Regulators:Rate-setting authorities in the United Kingdom and Netherlands approve cost recovery for digital monitoring investments, enabling opex treatment of asset performance management contracts.
Transmission Operators lead on scale; Energy Regulators lead on momentum through incentive design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces India in absolute transmission corridor investment, though India's Green Energy Corridors program deploys substations at faster normalized growth rates per installed renewable gigawatt.
United States
FERC Order 1000 mandates interregional transmission planning that compresses substation procurement timelines across the Mountain West and Southwest. The Inflation Reduction Act provisions cost-sharing mechanisms for interregional projects. Texas ERCOT interconnection queues concentrate demand in the Permian Basin wind zones.
Germany
Grid expansion for offshore wind evacuation drives 420 kV substation procurement along the North-South DC corridor. The EU F-Gas Regulation imposes the continent's strictest SF6 phase-down quotas. TenneT and 50Hertz framework agreements cascade technical specifications across Central European supply chains.
China
Ultra-high voltage DC corridors spanning 2,000+ kilometers require automated substation controls at each converter station. The National Energy Administration enforces reliability benchmarks above 99.99% for new transmission infrastructure. State Grid Corporation concentrates procurement authority in Beijing with regional execution across Xinjiang and Inner Mongolia renewable bases.
India
Green Energy Corridors mandate 765 kV substations to evacuate Rajasthan and Gujarat solar generation to Maharashtra and Tamil Nadu demand centers. Central Electricity Authority technical standards accelerate digital substation adoption. Power Grid Corporation deploys air-insulated configurations across desert solar zones while specifying gas-insulated units for Mumbai and Delhi urban corridors.
Japan
Tokyo-Osaka corridor upgrades prioritize footprint-constrained gas-insulated substations where land scarcity commands premium construction costs. METI grid resilience standards require seismic-resistant architectures. Chubu Electric and Kansai Electric concentrate procurement in the Nagoya-Osaka industrial belt.
High Voltage Transmission Substation Market Competitive Landscape
Top-tier vendors anchor premium-tier digital substation integration, while mid-tier specialists occupy modular air-insulated configurations and regional service contracts. The vendor base stratifies across three archetypes: integrated energy technology conglomerates, electrical equipment pure-plays, and regional infrastructure specialists. Consolidation pressure concentrates among European and Japanese players facing synchronous SF6 regulatory deadlines. Dominant competitive moves include predictive maintenance service unbundling and synthetic gas patent positioning.
Within the integrated technology tier, Hitachi Energy, Siemens Energy, and ABB exemplify divergent platform strategies. Hitachi Energy anchors predictive maintenance revenue through its Lumada platform across European transmission grids. Siemens Energy occupies a position defined by in-house production of high-voltage direct current converter valves. ABB exemplifies digital substation software integration, positioning its Ability platform as the control layer for utility automation architectures.
| Leading Market Players |
|---|
| Hitachi Energy |
| Siemens Energy |
| ABB |
| General Electric |
| Schneider Electric |
| Eaton |
| Mitsubishi Electric |
| Toshiba |
| Hyundai Electric |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation mandates for SF6-free switchgear are compressing procurement timelines and forcing utilities to absorb premium pricing for vacuum interruption and synthetic gas alternatives while vendors scramble to qualify new equipment platforms.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for gas-insulated switchgear as these production hubs expand to meet European demand surges. Three-tier pricing structure across premium digital substations, standard IEC 61850-compliant units, and economy air-insulated configurations stratifies the market. Cost compression in the economy tier is intensifying because Indian and Chinese state utilities negotiate volume frameworks that squeeze margins. Merchant renewable developers exhibit the highest price sensitivity, while German transmission operators prioritize specification compliance over unit cost.
Supply Chain Analysis
SF6 gas supply rests on Chinese and German chemical producers who dominate global production of this insulating medium now facing regulatory phase-down. Sulfur hexafluoride, vacuum interrupter ceramics, and copper busbar stock feed into switchgear assembly across Germany, Japan, and South Korea. Single-source vulnerability concentrates in Japanese ceramic suppliers for high-voltage vacuum bottles. Distribution runs through transmission system operator framework agreements that cascade specifications to regional EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high voltage transmission substation market compounds steadily as grid modernization cycles extend replacement demand across decades-long asset bases.
For Market Incumbents: Anchor predictive maintenance revenue through digital twin platforms to offset equipment margin compression from SF6 phase-down investments. Defend against modular AIS specialists by accelerating synthetic gas patent positioning in European markets. Prioritize vertical integration into converter valve production for HVDC corridor dominance. For New Entrants and Emerging Players: Direct-to-utility digital channel routes enable bypass of established EPC relationships in Sub-Saharan Africa's underdeveloped grid extension markets. Target modular air-insulated substations for Nigerian and Kenyan rural electrification programs where first-mover positioning remains open. Lead with rapid deployment capabilities and standardized designs over custom engineering. For Investors and Strategic Acquirers: Asymmetric upside sits with digital substation software specialists who capture recurring revenue from asset performance management contracts. Five-to-ten year viability favors vendors with IEC 61850 protocol expertise and synthetic gas handling capabilities. Watch for EU F-Gas quota tightening as the inflection signal accelerating replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Technology Transition | European F-Gas Regulation deadlines force vacuum and synthetic gas qualification investments by German and French TSOs. |
| Digital Substation Platform Integration | IEC 61850 protocol adoption reduces copper wiring and enables centralized protection architectures across United Kingdom networks. |
| Predictive Maintenance Service Unbundling | Asset performance management contracts separate from equipment supply, extending vendor revenue streams in Dutch and British markets. |
| HVDC Converter Valve Capacity Buildout | Ultra-high voltage DC corridors in China and India demand in-house production capabilities for long-distance renewable evacuation. |
| Sub-Saharan Africa Geographic Expansion | Modular AIS deployments in Nigeria, Kenya, and Ethiopia capture first-mover positioning in underdeveloped transmission infrastructure. |
Research Methodology
Direct dialogue with transmission system operator planning officers, utility procurement managers, EPC contractor project directors, and substation equipment R&D heads grounded the qualitative assessment. Secondary validation drew from FERC filings, EIA transmission project databases, IEA grid investment reports, and EU regulatory impact assessments. Bottom-up equipment shipment tallies and top-down grid investment forecasts were triangulated to anchor volume estimates.
Bottom-up modeling of substation deployments by voltage class, architectural type, and interruption technology converged with top-down transmission capital expenditure flows across the projection horizon. Segmentation dimensions included gas-insulated versus air-insulated topology, equipment technology tier, and end-user regulatory framework. CAGRs were derived from regression analysis against historical grid investment cycles and renewable interconnection queue growth. Forecast inputs incorporated copper and aluminum price trajectories alongside SF6 phase-down compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for synthetic insulating gas maturation would alter the outlook for equipment replacement cycles. Forecasts reflect documented assumptions about regulatory enforcement intensity and raw material supply elasticity. A small set of triggers—EU quota acceleration, vacuum interruption voltage ceiling breakthroughs, and protection engineer labor shortages—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market