
 Pantograph Disconnector Market | 2026-2036
Pantograph Disconnector Market Size, Share, and Industry Trends Forecast 2026-2036
Pantograph Disconnector Market Insights
Direct procurement from national rail infrastructure authorities is rewriting how pantograph disconnector contracts flow to manufacturers. Siemens AG leverages long-term framework agreements with European railway operators to sustain recurring revenue streams. ABB Ltd. anchors its position through backward integration into high-voltage switchgear manufacturing. Schneider Electric SE competes by specializing in electronic control systems for automatic disconnector units.
A pantograph disconnector is a high-voltage switching device that mechanically isolates overhead catenary sections using a hinged arm assembly, typically rated for 15-25 kV railway electrification systems with operating currents exceeding 1000A. Its primary purpose is to enable safe maintenance access and sectional fault isolation on electrified rail corridors. The automatic product type commands the dominant share as rail operators phase out manual switching for remote-controlled operations, while hydraulic technology leads installations where extreme weather reliability determines procurement decisions. Rail electrification applications absorb the majority of volume, though energy distribution substation connections represent the fastest-growing segment as utility-scale battery storage projects integrate with rail microgrids.
The EU Green Deal and F-Gas Regulation shape product material choices across European installations, while China's GB standards and NMPA-aligned rail safety protocols govern domestic procurement specifications. India's CEA and BIS certification requirements for high-voltage equipment create compliance barriers for non-local suppliers. Stakeholders must monitor how IEC 62271-102 revisions affect arc-quenching performance benchmarks and whether national content rules in emerging rail markets redirect supply chain sourcing.
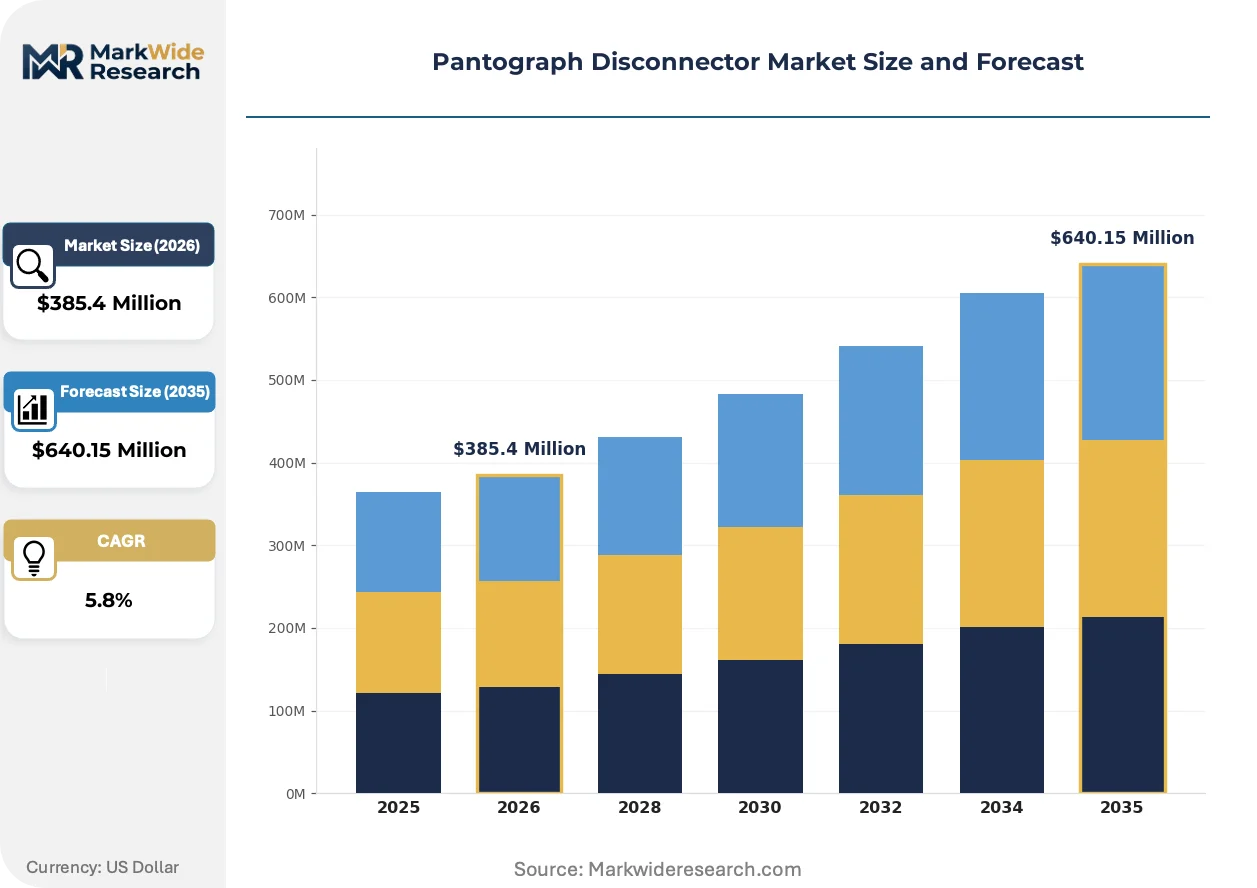
Market Dynamics
The EU Green Deal's electrification mandates are forcing railway operators to replace aging manual disconnectors with automatic units capable of remote fault isolation, compressing replacement cycles from decades to single-digit years.
Growth Catalysts
- EU Green Deal rail electrification quotas:Member states must double electrified track kilometers by 2035, mandating pantograph disconnector installations on every new corridor segment.
- High-speed rail buildouts in China and India:China's NMPA rail safety protocols and India's CEA certification requirements are accelerating procurement volumes for 25 kV-rated automatic disconnectors.
- IEC 62271-102 arc-quenching revisions:Tighter performance benchmarks for fault-current interruption are rendering legacy pneumatic designs obsolete and triggering wholesale fleet replacements.
Market Restraints
- Copper and silver contact material volatility:Spot price swings for these critical conductor materials compress manufacturer margins and destabilize long-term framework pricing.
- Supply concentration in German and Swiss switchgear foundries:Three specialized casting facilities produce the majority of high-voltage porcelain housings, creating single-point vulnerability.
- SF6 gas phase-out under F-Gas Regulation:Arc-quenching alternatives remain immature for railway-specific duty cycles, delaying product certifications and freezing procurement decisions.
Strategic Opportunities
- Utility-scale battery storage integration:Rail microgrid projects in Germany and Austria require disconnectors at distribution substations, opening a non-rail application channel.
- India's PLI scheme for electrical equipment:Local manufacturing incentives are attracting joint ventures that can bypass BIS import barriers and capture domestic procurement.
- Convergence of IoT condition monitoring with hydraulic actuators:Predictive maintenance algorithms layered onto existing disconnector fleets create aftermarket software revenue streams.
Industry Challenges
- Specialized high-voltage field technician scarcity:Railway electrification engineering programs in European technical universities graduate fewer candidates than replacement demand requires.
- CEA and BIS certification timeline compression:India's concurrent safety reviews for mechanical endurance and electromagnetic compatibility extend approval cycles by 8-14 months.
- Legacy catenary system interoperability:Pre-1990 overhead line geometries in Eastern European networks resist standard automatic disconnector mounting configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pantograph Disconnector Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Automatic, Manual End User: Railway Operators, Municipalities, Power Companies, Transportation Agencies Application: Rail Electrification, Energy Distribution, Overhead Lines, Substation Connections Technology: Hydraulic, Pneumatic, Mechanical, Electronic |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric SE, Alstom, General Electric Company, Eaton, WEG, Fuji Electric Co., Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pantograph Disconnector Market Trends and Innovations
Actuator technology and control system architectures are converging to eliminate mechanical complexity, while regulatory pressure on insulating gases forces material science pivots that reshape product roadmaps.
Hybrid electromechanical-hydraulic actuator designs are hybridizing the pantograph disconnector category. These systems combine the speed of electromechanical drives with the weather resilience of hydraulic seals. Deutsche Bahn and ÖBB are piloting units for Alpine corridor deployments where temperature swings exceed 60°C annually. The technology is hybridizing procurement specifications, forcing manufacturers to dual-source actuator subsystems rather than optimize around single-technology platforms.
The EU F-Gas Regulation's 2030 phase-down targets for sulfur hexafluoride are pressuring arc-quenching innovation. Vacuum interrupter modules originally developed for utility switchgear are being adapted for railway duty cycles with higher mechanical operation frequencies. French and Italian operators are requiring SF6-free declarations in tender documents, compressing development timelines for alternative insulation media including fluoronitrile mixtures and dry air systems.
Framework contracting is consolidating buyer power among European infrastructure managers. Deutsche Bahn, SNCF Réseau, and Trenitalia are bundling disconnector procurement into multi-year catenary maintenance agreements that specify availability guarantees rather than unit prices. German and Austrian corridors show the most advanced adoption, with penalty clauses for unplanned downtime displacing traditional capital expenditure models.
Pantograph Disconnector Market Segmentation
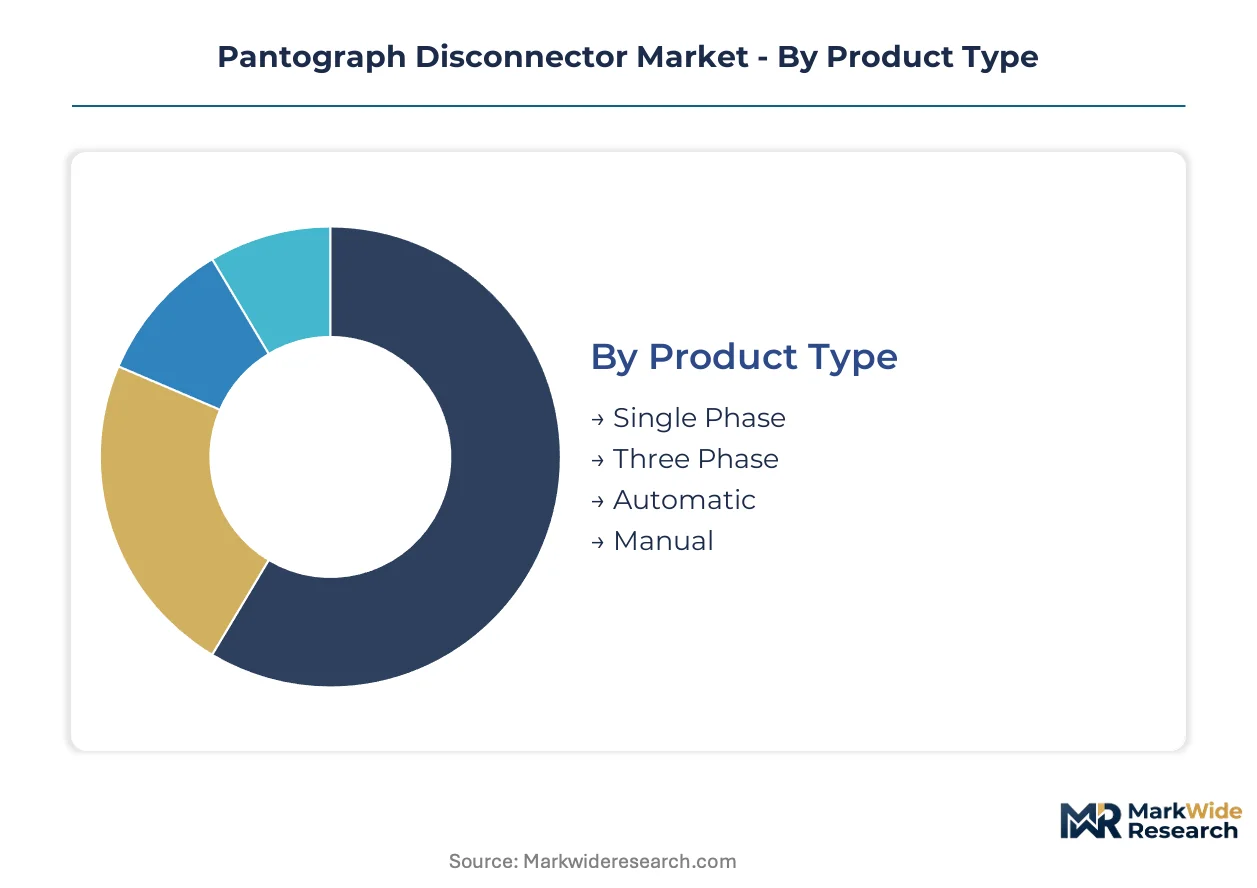
Pantograph disconnector procurement diverges sharply across operating environments, from high-frequency railway corridors to intermittent utility substations. Segment boundaries determine actuator specifications, control architectures, and maintenance protocols that manufacturers must harmonize.
Product Type:
Mature manual designs coexist with emerging automatic platforms as electrification mandates accelerate replacement cycles.
- Automatic:Remote-controlled units with motorized actuators and SCADA integration enable fault isolation from centralized control centers. Deutsche Bahn and SNCF Réseau specify these exclusively for new corridor installations under EU Green Deal electrification quotas. IEC 62271-102 arc-quenching revisions are rendering legacy pneumatic designs obsolete and triggering fleet-wide replacements.
- Manual:Hand-cranked hinged arm assemblies persist in pre-1990 Eastern European networks where legacy catenary geometries resist standard automatic mounting configurations. Operators in Poland and Romania maintain these for low-traffic branch lines with minimal maintenance budgets.
- Single Phase:15-25 kV rated units dominate standard railway electrification systems across Germany and Austria.
- Three Phase:Industrial railway applications and heavy-haul mining corridors in Australia and Brazil deploy these for higher current capacity.
Automatic handles the majority of throughput; Manual is the fastest mover on share as operators phase out hand-cranked switching.
End User:
Customer concentration varies by procurement authority structure and infrastructure ownership models.
- Railway Operators:Deutsche Bahn, ÖBB, and Trenitalia bundle disconnector procurement into multi-year catenary maintenance agreements with availability guarantees rather than unit pricing. These infrastructure managers command consolidated buyer power across Alpine and Central European corridors.
- Power Companies:Utility-scale battery storage projects in Germany and Austria require disconnectors at distribution substations connecting rail microgrids to national grids. RWE and E.ON are piloting SF6-free vacuum interrupter modules for these installations.
- Municipalities:Urban metro buildouts in India and China drive volume for 25 kV-rated automatic disconnectors with compact footprints.
- Transportation Agencies:Regional transit authorities in France and Italy procure through framework contracts specifying penalty clauses for unplanned downtime.
Railway Operators absorb the dominant procurement volume; Power Companies are expanding most quickly as rail microgrid integration accelerates.
Application:
Duty cycle intensity shapes material specifications and maintenance intervals across installation environments.
- Rail Electrification:Overhead catenary sectionalization for high-speed and conventional lines requires mechanical endurance ratings exceeding 100,000 operations. China's NMPA rail safety protocols and India's CEA certification requirements are accelerating procurement volumes for 25 kV-rated automatic disconnectors on new corridor segments.
- Substation Connections:Utility-scale battery storage integration with rail microgrids in Germany and Austria creates non-rail demand for disconnectors rated at distribution voltage levels. These installations prioritize SF6-free declarations under EU F-Gas Regulation phase-down targets.
- Energy Distribution:Grid interconnection points for electrified railway feeders require higher fault-current interruption capacity.
- Overhead Lines:Legacy corridor maintenance and sectional fault isolation in Eastern European networks with pre-1990 geometries.
Rail Electrification commands the established application base; Substation Connections are gaining share fastest as energy storage projects multiply.
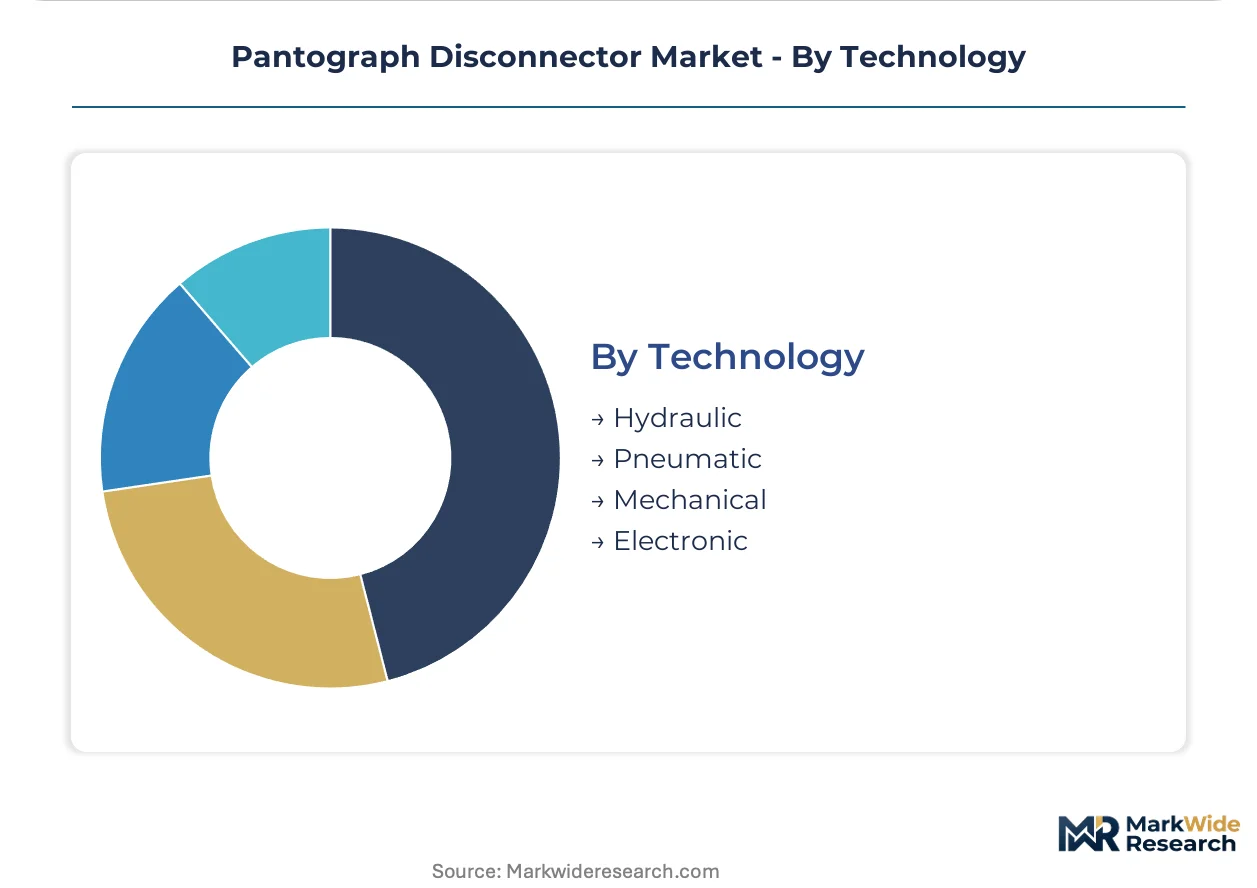
Technology:
Actuator selection hinges on climate exposure, operating frequency, and remote control requirements.
- Hydraulic:Sealed fluid systems withstand temperature swings exceeding 60°C annually in Alpine corridors where Deutsche Bahn and ÖBB are piloting hybrid electromechanical-hydraulic designs. Weather resilience determines procurement decisions for exposed outdoor installations.
- Electronic:Solid-state control systems with IoT condition monitoring enable predictive maintenance algorithms layered onto existing fleets. Schneider Electric SE specializes in these architectures for automatic disconnector units with SCADA integration.
- Pneumatic:Compressed air actuators face obsolescence as IEC 62271-102 revisions tighten arc-quenching performance benchmarks.
- Mechanical:Direct linkage systems persist in manual units for cost-constrained branch line applications.
Hydraulic maintains the largest installed base; Electronic is climbing the fastest as condition monitoring converges with actuator control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor underwrites Germany's centrality to pantograph disconnector demand, with Deutsche Bahn's electrification program driving procurement volumes across Central Europe. China's Beijing-Guangzhou high-speed trunk anchors Asia-Pacific installation activity, while India's Delhi-Mumbai Industrial Corridor accelerates domestic certification requirements.
Germany
Deutsche Bahn's framework agreements for catenary maintenance specify availability guarantees rather than unit pricing, compressing supplier margins. The EU F-Gas Regulation's 2030 phase-down targets force SF6-free vacuum interrupter adoption across Bavarian and North Rhine-Westphalian installations. Siemens AG anchors supply relationships through long-term electrification contracts along the Rhine-Alpine freight corridor.
China
China Railway's 25 kV-rated automatic disconnector procurement accelerates under NMPA rail safety protocols for new high-speed segments. GB standards governing high-voltage switchgear create compliance barriers for non-domestic suppliers. The Yangtze River Delta cluster around Shanghai concentrates manufacturing capacity for porcelain housings and hydraulic actuator subsystems.
India
Indian Railways' electrification targets under the CEA's technical standards drive volume for 25 kV automatic units on the Delhi-Mumbai and Chennai-Bengaluru corridors. The PLI scheme for electrical equipment attracts joint ventures seeking BIS certification shortcuts. Maharashtra and Gujarat host emerging fabrication clusters for high-voltage porcelain components.
France
SNCF Réseau bundles disconnector procurement into multi-year catenary agreements with penalty clauses for unplanned downtime. The EU Green Deal mandates double electrified track kilometers by 2035, forcing fleet-wide replacement of legacy pneumatic designs. The Île-de-France region around Paris concentrates pilot deployments of SF6-free vacuum interrupter modules.
Austria
ÖBB pilots hybrid electromechanical-hydraulic designs for Alpine corridors where temperature swings exceed 60°C annually. Utility-scale battery storage integration with rail microgrids creates non-rail demand at distribution substations. The Tyrol-Vorarlberg corridor anchors weather-resilience testing for sealed fluid actuator systems.
Pantograph Disconnector Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified industrial conglomerates with captive switchgear capabilities, specialized high-voltage equipment pure-plays, and electronic control system specialists. The competitive terrain rewards backward integration into porcelain housing foundries and forward integration into SCADA-enabled service contracts. M&A activity concentrates on actuator technology acquisitions, while capacity expansion targets Indian and Chinese certification hubs.
Among European-based industrial conglomerates, Siemens AG and ABB Ltd. exemplify the integrated archetype through captive supply of high-voltage switchgear components. Schneider Electric SE occupies a distinct position as an electronic control specialist. These three anchors demonstrate how procurement consolidation among infrastructure managers favors scale-driven vendors with framework contracting experience.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Alstom |
| General Electric Company |
| Eaton |
| WEG |
| Fuji Electric Co., Ltd. |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's electrification cost dynamics compress supplier margins while amplifying price differentiation between framework-contract incumbents and spot-market challengers. Three German and Swiss porcelain housing foundries anchor upstream supply concentration, enabling tiered pricing power that cascades through catenary maintenance agreements and into regional procurement specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and after-sales bundling intensity. Premium tiers capture IEC 62271-102 arc-quenching compliance and predictive maintenance software integration, while economy tiers serve Eastern European manual-disconnector replacement cycles. Price erosion runs through the economy tier as Indian and Chinese domestic manufacturers achieve BIS and GB certification parity. Railway operators with multi-year framework agreements exhibit lowest price sensitivity; municipal transit authorities in emerging markets show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates at three specialized foundries in Germany and Switzerland producing high-voltage porcelain housings, with hydraulic actuator subsystems sourced from Yangtze River Delta machining clusters. Raw material dependencies center on copper and silver contact alloys, high-alumina ceramic feedstocks, and synthetic hydraulic fluids. Single-source vulnerability at the porcelain housing tier exposes procurement timelines to foundry capacity constraints. Distribution runs through national rail infrastructure authority tender platforms and OEM direct-sales engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
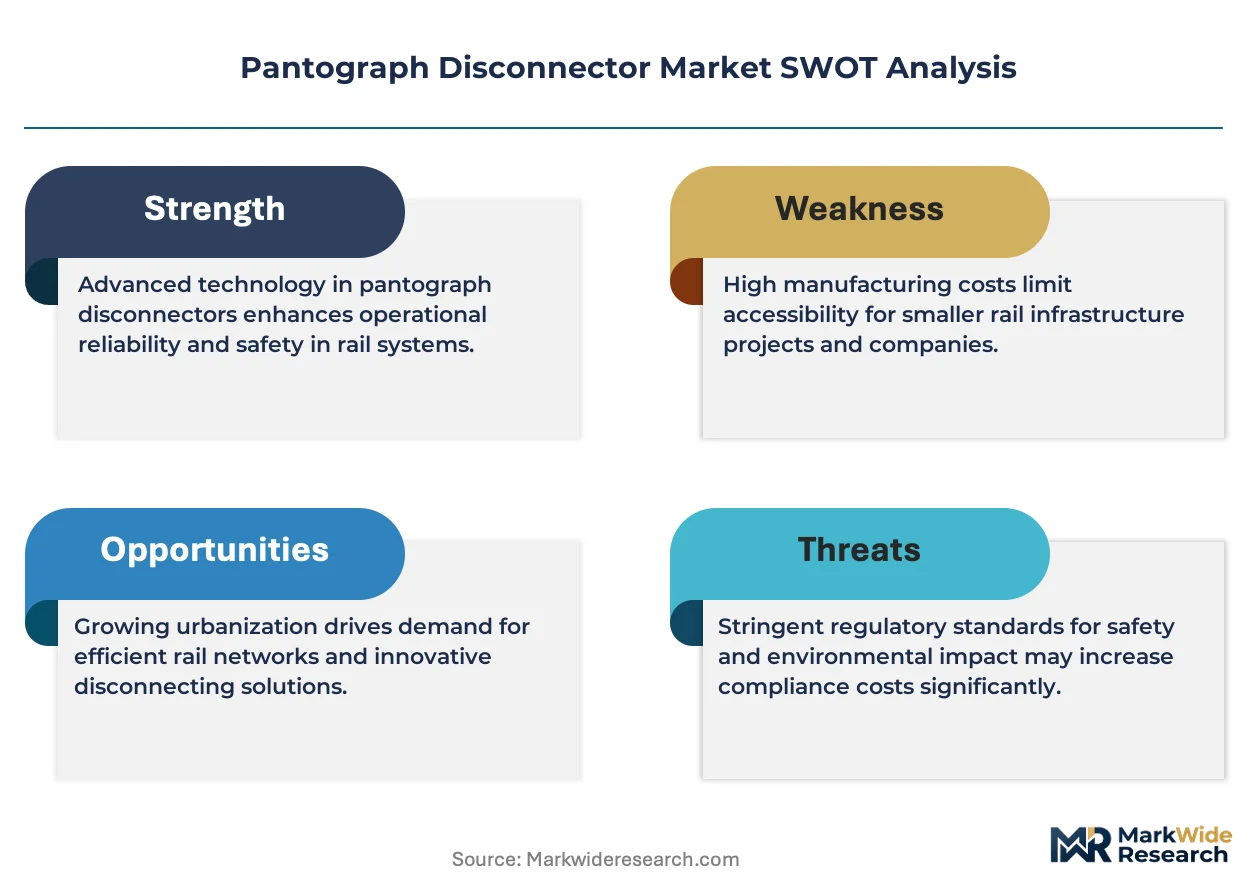
The pantograph disconnector market is approaching a platform-economics inflection as SCADA-integrated automatic units create interoperability lock-in between hardware vendors and railway control system ecosystems. This shift favors vendors who bundle predictive maintenance algorithms with actuator hardware.
For Market Incumbents: Build certification moats around IEC 62271-102 arc-quenching revisions and F-Gas Regulation SF6-free declarations. Deepen backward integration into high-voltage porcelain foundry capacity to secure supply against single-source vulnerability. Capture emerging utility-scale battery storage substation connections through joint development agreements with RWE and E.ON grid planning teams. For New Entrants and Emerging Players: Pursue India's PLI scheme joint ventures to bypass BIS certification barriers and access Delhi-Mumbai Industrial Corridor electrification procurement. Target manual-to-automatic conversion cycles in Poland and Romania where legacy catenary geometries resist standard mounting configurations. Lead with IoT condition monitoring software layers that retrofit existing hydraulic actuator fleets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates' non-core switchgear divisions where electrification mandates outpace internal investment prioritization. Five-to-ten year viability hinges on SF6-free technology maturation and Alpine corridor weather-resilience validation. Monitor Deutsche Bahn and ÖBB hybrid electromechanical-hydraulic pilot deployment outcomes as inflection indicator for actuator technology consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Porcelain Foundry Capacity | Captive supply of high-voltage housings insulates against German-Swiss foundry bottlenecks. |
| SF6-Free Vacuum Interrupter Certification | F-Gas Regulation compliance unlocks SNCF Réseau and Trenitalia framework contract eligibility. |
| IoT Predictive Maintenance Platform Launch | Schneider Electric's electronic control architecture creates aftermarket software revenue from existing fleets. |
| Joint Venture under India's PLI Scheme | BIS certification shortcuts capture Delhi-Mumbai and Chennai-Bengaluru corridor procurement volumes. |
| Rail Microgrid Substation Integration Partnership | Utility-scale battery storage projects in Germany and Austria open non-rail application channels. |
Research Methodology
Desk research of IEC 62271-102 technical standards, EU Green Deal implementation documents, and national rail infrastructure authority tender records preceded structured interviews with catenary maintenance directors, high-voltage switchgear procurement managers, and railway electrification engineering consultants. Secondary validation drew from Deutsche Bahn and SNCF Réseau framework contract disclosures, CEA and BIS certification timelines, and foundry capacity utilization reports. Bottom-up unit installation forecasts triangulated against top-down electrification mileage targets.
Assumptions held fixed include EU member state electrification quotas under the Green Deal and China's NMPA rail safety protocol enforcement intensity; variables tested included SF6 phase-down acceleration timelines and copper spot price volatility bands. Segmentation modeling spanned product type, technology, application, and end-user procurement authority structure across the projection horizon. CAGR derivation weighted historical replacement cycle compression against greenfield high-speed rail construction schedules.
Sensitivities concentrate around IEC standard revision timing, F-Gas Regulation enforcement stringency, and Indian certification timeline compression. Forecasts reflect documented assumptions on framework contract penetration rates and utility-scale storage integration velocity. Quarterly review of Deutsche Bahn pilot deployment outcomes, BIS approval queue lengths, and Yangtze River Delta foundry output indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market