
 Flexible AC Transmission Systems Market | 2026-2036
Flexible AC Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible AC Transmission Systems Market Analysis
China's western ultra-high-voltage corridor build-out is rewriting regional FACTS deployment patterns. Siemens Energy leverages its thyristor valve manufacturing scale to anchor European utility tenders. GE Vernova competes through integrated digital control platforms that span STATCOM and SVC architectures. ABB sustains technology leadership in phase-shifting transformer design for congested interconnections.
Flexible AC Transmission Systems deploy power electronics-based controllers—thyristor-switched capacitors, static synchronous compensators rated up to ±800 Mvar, and unified power flow controllers—to modulate voltage, impedance, and phase angle across alternating-current grids. These systems enable utilities to push existing transmission corridors toward thermal limits without building new lines. Static synchronous compensator technology dominates capital allocation due to its superior dynamic response for renewable integration, while distributed FACTS represents the fastest-expanding segment as grid operators seek modular, lower-investment alternatives for localized voltage support. Power flow control applications command the deepest margin pools because they address congestion pricing arbitrage in restructured electricity markets.
FERC Order 1000 in the United States mandates competitive transmission planning that implicitly rewards FACTS solutions deferring greenfield construction, while the EU Green Deal's network infrastructure targets and CE marking requirements for power electronics shape European procurement standards. China's GB standards and MIIT energy-efficiency directives enforce domestic content thresholds for grid-scale equipment. Stakeholders must monitor how evolving interconnection queue reforms in multiple jurisdictions redefine the economic case for dynamic versus static compensation.
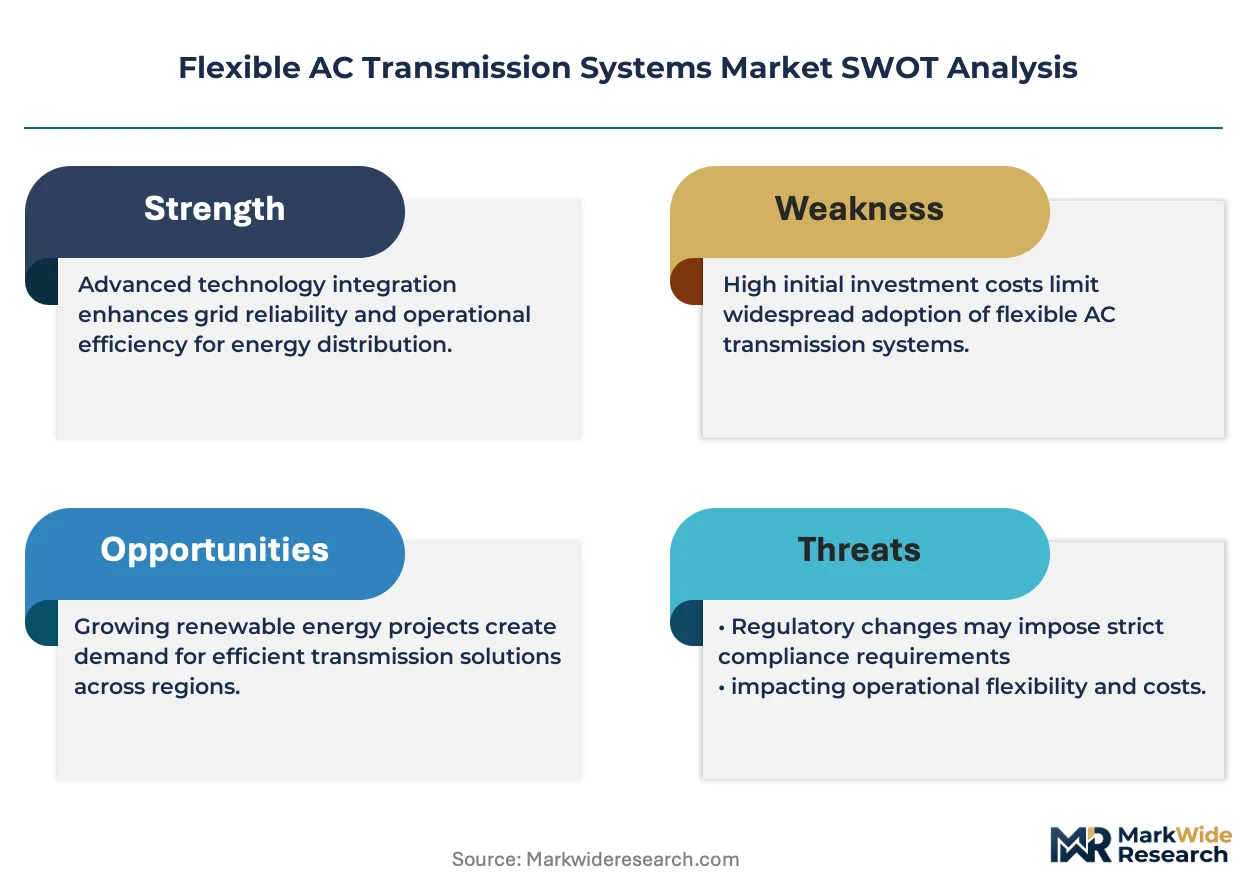
Market Dynamics
Ultra-high-voltage corridor build-outs across western China are compressing FACTS procurement cycles and forcing thyristor valve manufacturers to expand foundry capacity ahead of demand curves.
Growth Catalysts
- EU Green Deal network mandates:Brussels' infrastructure targets accelerate utility procurement timelines for STATCOM installations across congested interconnections.
- India's western renewable zones:Rajasthan and Gujarat solar parks require dynamic reactive compensation to stabilize fluctuating generation injected into weak grid nodes.
- Silicon carbide power modules:Wide-bandgap semiconductors reduce switching losses in next-generation static compensators, enabling higher Mvar density per substation footprint.
Market Restraints
- Copper and rare-earth price volatility:Magnet materials and winding conductors constitute 35-40% of STATCOM bill-of-materials, exposing margins to commodity swings.
- Thyristor valve foundry concentration:High-power semiconductor fabrication clusters in Germany and Japan create single-source vulnerability for 800 Mvar-class equipment.
- GB standards domestic content rules:China's MIIT directives mandate local sourcing thresholds that freeze out non-Chinese vendors from western province tenders.
Strategic Opportunities
- Brazil's Amazon transmission integration:Norte Energia and other concessionaires seek modular SVC alternatives to defer greenfield line construction across rainforest terrain.
- FERC Order 1000 competitive planning:US grid operators now explicitly value FACTS solutions that defer capital-intensive transmission builds in interconnection queues.
- Digital twin convergence with power electronics:Real-time thermal modeling and predictive maintenance algorithms create service revenue streams beyond hardware sales.
Industry Challenges
- Power electronics control firmware integration:Utilities struggle to harmonize proprietary FACTS control languages with existing SCADA architectures and legacy protection relays.
- HV equipment certification timelines:IEC 61954 and IEEE 1031 type-testing protocols extend product validation cycles to 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible AC Transmission Systems Market |
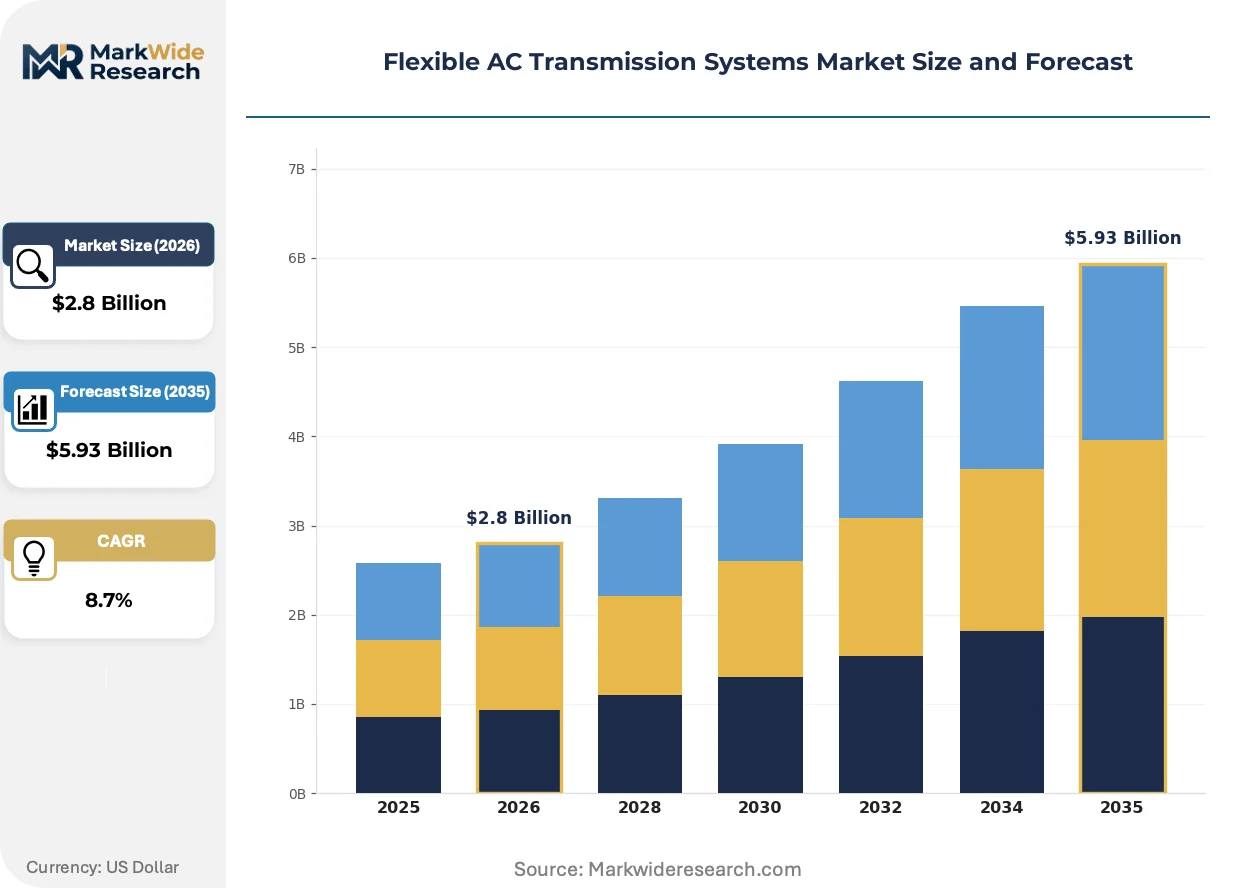
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Static Synchronous Compensator, Phase-Shifting Transformer, Flexible AC Transmission System Controller, Distributed FACTS Application: Power Flow Control, Voltage Regulation, Reactive Power Compensation, Transmission Capacity Enhancement End User: Utilities, Industrial, Renewable Energy, Commercial Component: Power Electronics, Control Systems, Transformers, Capacitors |
| Companies Covered | Siemens Energy, GE Vernova, ABB, Hitachi Energy, Mitsubishi Electric, NR Electric, Hyosung Heavy Industries, Infineon Technologies, American Superconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible AC Transmission Systems Market Emerging Trajectories
Power semiconductor architecture and procurement contracting models are undergoing simultaneous transformation, compressing technology refresh cycles while fragmenting vendor-customer relationships.
Silicon carbide MOSFETs are migrating from niche aerospace applications to grid-scale STATCOM inverters. European TSOs including TenneT and National Grid ESO pilot 300 Mvar-class SiC-based compensators for offshore wind integration. The technology is migrating from laboratory demonstration to serial procurement, collapsing the cost premium against silicon IGBT solutions from roughly 40% to under 15% across the analysis window.
The EU F-Gas Regulation's phasedown of sulfur hexafluoride intensifies pressure on gas-insulated switchgear-dependent FACTS installations. Manufacturers accelerate dry-air and vacuum interrupter development for series compensation schemes. Offshore wind connection projects in the North Sea and Baltic face the steepest compliance curves, driving joint procurement consortia among Orsted, RWE, and Equinor.
Performance-based availability contracts displace traditional EPC lump-sum arrangements for STATCOM deployments. Nordic and British TSOs now tie 30-50% of vendor payments to demonstrated reactive power response latency and annualized availability metrics. This restructuring concentrates risk with equipment suppliers while transferring operational complexity to specialized O&M contractors in Germany and Denmark.
Flexible AC Transmission Systems Market Segmentation
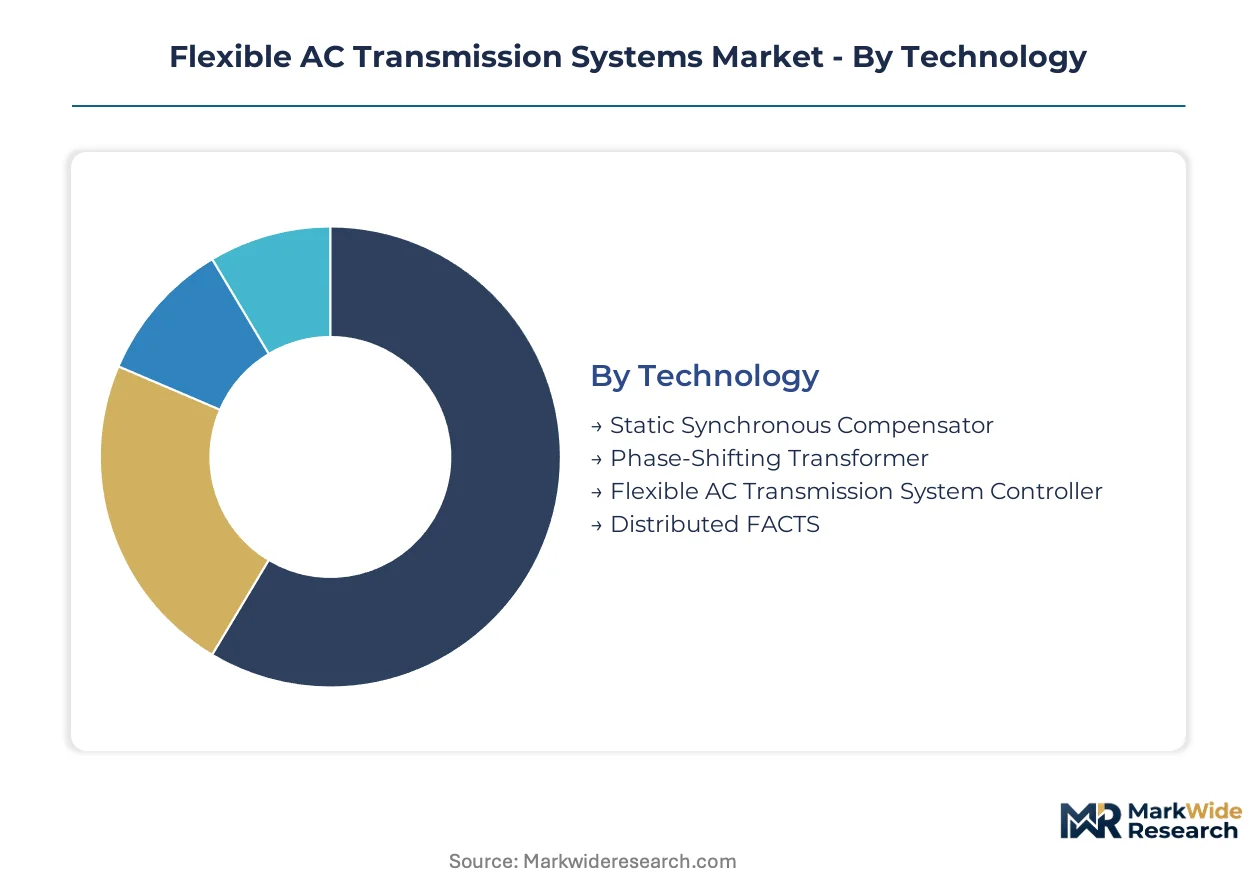
Segmentation in FACTS markets reveals how technology maturity, application urgency, and procurement economics fragment vendor strategies across grid modernization cycles. Each dimension carries distinct margin profiles and competitive entry barriers.
Technology:
Mature thyristor-based architectures coexist with emerging wide-bandgap semiconductor platforms, creating a bifurcated investment landscape for utilities balancing reliability against performance gains.
- Static Synchronous Compensator:Voltage-source converter topology delivers sub-cycle reactive power response for renewable integration. Rajasthan and Gujarat solar parks in India deploy STATCOM clusters to stabilize fluctuating generation at weak grid nodes. STATCOM retains volume leadership; Distributed FACTS holds the steepest expansion curve.
- Phase-Shifting Transformer:Electromechanical phase angle regulation redirects power flows across congested interconnections without new line construction. European TSOs including TenneT prioritize these installations for cross-border capacity optimization under EU Green Deal mandates.
- Flexible AC Transmission System Controller:Unified power flow controllers and thyristor-switched series capacitors manage simultaneous voltage, impedance, and phase parameters.
- Distributed FACTS:Modular, lower-investment alternatives target localized voltage support in distribution networks and industrial microgrids.
STATCOM commands the deepest capital allocation pools; Distributed FACTS is climbing the fastest as grid operators seek scalable, bite-sized investments.
Application:
Application segmentation tracks how electricity market restructuring and renewable penetration reshape compensation priorities across transmission planning horizons.
- Power Flow Control:Congestion pricing arbitrage in restructured markets drives premium valuations for phase-shifting and series compensation schemes. Nordic TSOs tie vendor payments to demonstrated response latency metrics under performance-based contracting models.
- Voltage Regulation:Dynamic voltage support prevents collapse during fault conditions and maintains power quality for sensitive industrial loads.
- Reactive Power Compensation:Absorbs surplus reactive generation from lightly loaded transmission corridors and injects support during peak demand periods.
- Transmission Capacity Enhancement:Pushes existing corridors toward thermal limits, deferring greenfield construction across difficult terrain such as Brazil's Amazon basin.
Power Flow Control captures the highest margin pools; Transmission Capacity Enhancement is expanding most quickly as interconnection queue reforms accelerate deferral economics.
End User:
Customer type segmentation exposes divergent procurement sophistication, from centralized utility tenders to fragmented industrial site requirements.
- Utilities:Grid-scale deployments across ultra-high-voltage corridors in western China and competitive transmission planning under FERC Order 1000 in the United States dominate procurement volumes.
- Industrial:Steel mills, aluminum smelters, and semiconductor fabs require dedicated compensation for voltage flicker mitigation and power factor correction.
- Renewable Energy:Offshore wind developers in the North Sea and Baltic face steep EU F-Gas Regulation compliance curves, driving joint procurement consortia.
- Commercial:Data centers and large retail complexes seek modular solutions for localized power quality management.
Utilities retain absolute volume leadership; Renewable Energy holds the steepest expansion trajectory as interconnection standards tighten.
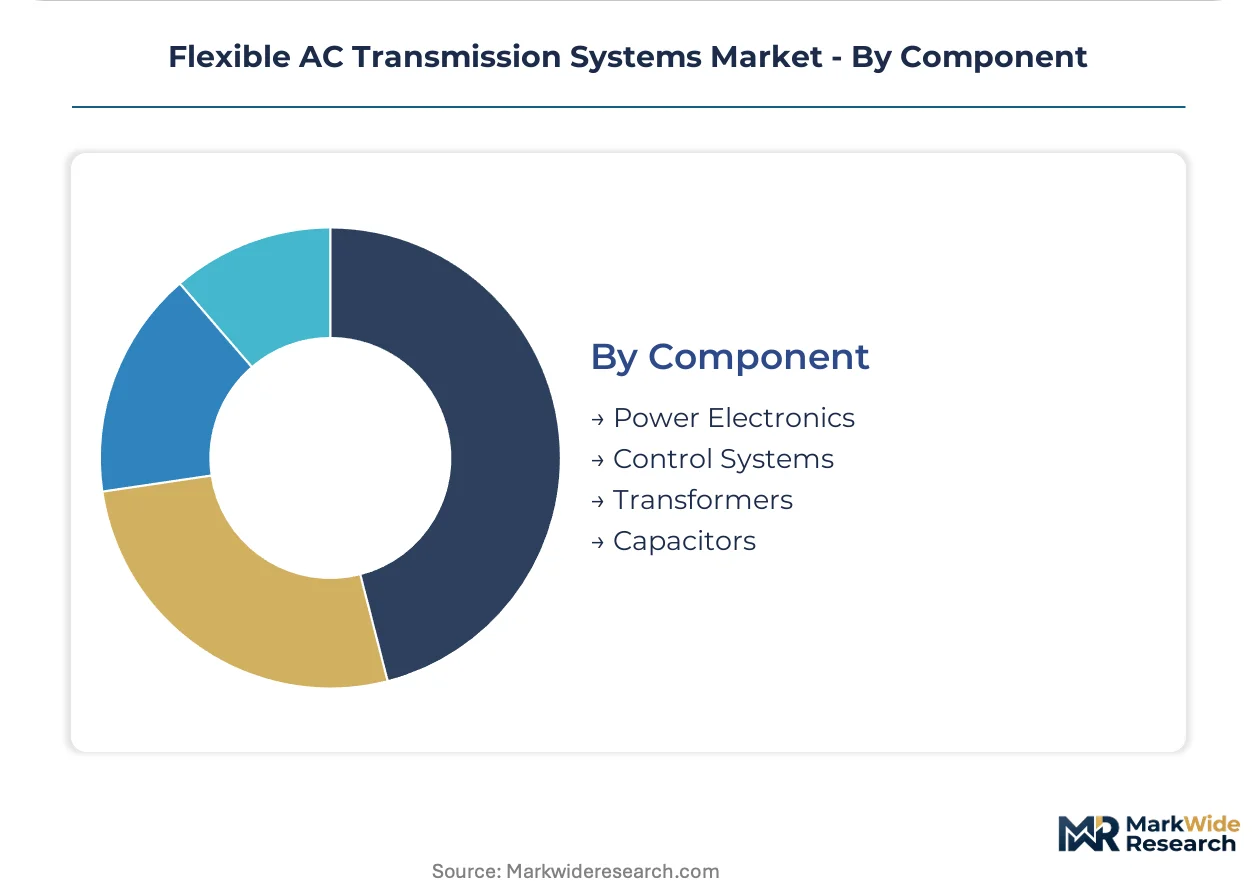
Component:
Component segmentation traces supply chain concentration risks from rare-earth magnet materials to specialized high-power semiconductor fabrication.
- Power Electronics:Thyristor valves and silicon carbide MOSFETs constitute 35-40% of STATCOM bill-of-materials, with foundry concentration in Germany and Japan creating single-source vulnerability for 800 Mvar-class equipment.
- Control Systems:Digital control platforms and predictive maintenance algorithms create service revenue streams beyond hardware sales.
- Transformers:Phase-shifting and converter-grade designs require specialized insulation coordination for harmonic-rich environments.
- Capacitors:Film and ceramic dielectrics provide reactive support in switched and fixed configurations.
Power Electronics commands the largest cost share; Control Systems is gaining share fastest as digital twin convergence restructures vendor-customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives through China's GB standards enforce domestic content thresholds for grid-scale equipment, compressing procurement cycles for ultra-high-voltage corridors in western provinces. FERC Order 1000 mandates competitive transmission planning in the United States. The EU Green Deal's network infrastructure targets accelerate STATCOM installations across congested interconnections.
China
Western province solar and wind build-outs in Xinjiang and Qinghai demand dynamic reactive compensation for weak grid nodes. MIIT energy-efficiency directives mandate local sourcing thresholds that reshape vendor participation in ultra-high-voltage tenders. Siemens Energy and domestic suppliers compete for STATCOM clusters along the ±1100 kV Changji-Guquan corridor.
United States
Interconnection queue reforms in Texas and California redefine the economic case for dynamic versus static compensation solutions. FERC Order 1000 explicitly rewards FACTS deployments that defer greenfield transmission construction. ERCOT operators in the Lone Star State pilot modular SVC alternatives to address renewable integration bottlenecks.
Germany
TenneT and other TSOs prioritize phase-shifting transformer installations for cross-border capacity optimization under EU Green Deal mandates. The EU F-Gas Regulation accelerates dry-air and vacuum interrupter development for series compensation schemes. Foundry concentration in Bavaria and Baden-Württemberg creates single-source vulnerability for high-power semiconductor fabrication.
India
Rajasthan and Gujarat solar parks require STATCOM clusters to stabilize fluctuating generation injected into weak grid nodes. CEA regulations and state-level renewable purchase obligations compress procurement timelines for grid modernization investments. Western regional load dispatch centers in Ahmedabad and Jaipur coordinate dynamic reactive power management across renewable zones.
Brazil
Norte Energia and other concessionaires seek modular SVC alternatives to defer greenfield line construction across Amazon rainforest terrain. ANEEL transmission auction rules implicitly value compensation solutions that minimize environmental licensing delays. Belo Monte corridor operators in Pará state deploy distributed FACTS for localized voltage support in remote substations.
Flexible AC Transmission Systems Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated vendor landscape where specialized power electronics expertise competes against integrated platform breadth. The market structure consolidates around three to five dominant system integrators with captive semiconductor supply relationships, while modular specialists capture niche opportunities in distributed applications. Two strategic archetypes predominate: full-stack platform vendors with digital control integration and component-focused specialists with foundry-scale manufacturing. Competitive moves concentrate on silicon carbide technology licensing partnerships and performance-based availability contracting that transfers operational risk to equipment suppliers.
Within the integrated platform tier, Siemens Energy, GE Vernova, and ABB represent contrasting geographic and technological positioning strategies. Siemens Energy anchors European utility tenders through thyristor valve manufacturing scale. GE Vernova competes through digital control platforms spanning multiple compensation architectures. ABB sustains technology leadership positioning in phase-shifting transformer design for congested interconnections. These three exemplify how vendor differentiation converges on semiconductor supply security and firmware integration capabilities rather than hardware specifications alone.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| ABB |
| Hitachi Energy |
| Mitsubishi Electric |
| NR Electric |
| Hyosung Heavy Industries |
| Infineon Technologies |
| American Superconductor |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on high-power thyristor valve foundries in Germany and Japan compresses pricing tier spreads while forcing buyers into long-term offtake commitments to secure 800 Mvar-class equipment slots. This concentration simultaneously elevates premium pricing for silicon carbide-based alternatives and locks standard-tier buyers into extended lead-time contracts.
Pricing Analysis
European TSOs pay 15-20% premiums over Indian utilities for identical STATCOM ratings due to EU F-Gas Regulation compliance costs and CE marking requirements. Three-tier pricing structure across premium SiC-based systems, standard silicon IGBT platforms, and economy-grade thyristor-switched capacitors reflects semiconductor architecture differentiation. Cost compression in the standard tier intensifies as Chinese domestic suppliers absorb western province demand under MIIT local-content rules. Industrial end-users in steel and aluminum exhibit highest price sensitivity, while offshore wind developers accept premium positioning for availability-guaranteed performance contracts.
Supply Chain Analysis
Tariff exposure between China and Western semiconductor equipment suppliers dominates supply chain risk calculus for grid-scale FACTS deployments. High-power semiconductor fabrication concentrates in Germany, Japan, and China, with magnet materials and copper windings drawing from Chilean mining operations and Chinese rare-earth processing. Single-source vulnerability for 800 Mvar-class thyristor valves creates procurement bottlenecks during ultra-high-voltage corridor build-outs. Distribution runs through EPC contractors and specialized O&M providers in Germany and Denmark rather than direct manufacturer-to-utility channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization cycles tied to renewable integration mandates position this market for sustained equipment procurement expansion. Capital expenditure deferral economics and interconnection queue reforms reinforce multi-year visibility for STATCOM and SVC deployments.
For Market Incumbents: Insulate semiconductor supply security through captive foundry partnerships or equity stakes in Bavarian and Baden-Württemberg fabrication facilities. Accelerate silicon carbide technology licensing to offset pricing pressure from Chinese domestic suppliers under MIIT local-content directives. Prioritize firmware integration capabilities that harmonize proprietary control languages with utility SCADA architectures.
For New Entrants and Emerging Players: Modular SVC alternatives for Brazil's Amazon transmission integration represent the most penetrable entry point given environmental licensing constraints on greenfield construction. Distributed FACTS for industrial microgrids in India's western renewable zones offer second-tier opportunity with lower capital barriers. Pursue joint development agreements with Nordic TSOs piloting performance-based availability contracting models.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors foundry-scale manufacturers with existing thyristor valve production lines. Long-term viability over the next decade hinges on wide-bandgap semiconductor transition readiness rather than legacy silicon IGBT market share. Monitor silicon carbide cost-parity milestones against silicon solutions as the primary inflection signal for technology substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures semiconductor supply for next-generation STATCOM inverters targeting offshore wind integration. |
| Performance-Based Availability Contracting | Transfers operational risk to suppliers while creating recurring service revenue streams with TenneT and National Grid ESO. |
| F-Gas Regulation Compliance Program | Accelerates dry-air and vacuum interrupter development for North Sea and Baltic offshore connection projects. |
| Digital Twin Platform Integration | Enables predictive maintenance algorithms that extend vendor-customer relationships beyond hardware sales cycles. |
| Western China Localization Joint Venture | Navigates MIIT domestic content thresholds for ultra-high-voltage corridor tenders in Xinjiang and Qinghai provinces. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FERC interconnection queue databases, EU Green Deal infrastructure filings, and MIIT equipment procurement notices. Utility planning officers, EPC contractors, and grid operators across Germany, China, India, and the United States provided qualitative inputs on procurement timelines and technology preferences. Semiconductor supply specialists and thyristor valve manufacturers contributed fabrication capacity and cost structure intelligence. Bottom-up project pipelines were triangulated against top-down regulatory mandate trajectories.
Forecast inputs span technology segmentation across STATCOM, SVC, phase-shifting transformer, and distributed FACTS architectures; application dimensions including power flow control, voltage regulation, and transmission capacity enhancement; and end-user categories from utilities through renewable energy developers. CAGRs were derived from regression analysis of historical procurement volumes against renewable capacity addition curves and interconnection queue depths. Silicon carbide cost reduction trajectories and F-Gas Regulation compliance timelines served as technology-specific modifiers.
Practitioners should monitor rare-earth price volatility, foundry capacity expansion announcements, and interconnection queue reform implementations for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market