
 Global Pre Zippered Pouches Market | 2026-2036
Global Pre Zippered Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pre Zippered Pouches Market Intelligence
Integrated sustainability consulting, including lifecycle analysis and recyclability certification, is broadening the scope of supplier engagements. This shift moves contracts beyond simple unit pricing to value-added partnerships. Amcor Limited leverages its global manufacturing footprint to offer consistent material specifications across regions. Mondi Group differentiates through its portfolio of paper-based flexible packaging solutions, appealing to brands with plastic reduction goals.
Pre-zippered pouches are flexible packages created from film where the resealable closure is applied before the pouch forming, filling, and sealing process. This manufacturing method enhances production line efficiency and ensures consistent zipper alignment for consumer convenience. Stand-up pouches command the largest market share due to their excellent shelf visibility. The food industry constitutes the primary end-user, though the pet care segment represents the fastest-growing application area.
Material selection and product claims are governed by a complex web of international standards. In the United States, the FDA sets guidelines for food-contact materials, while the EU's Packaging and Packaging Waste Regulation imposes strict recyclability targets. Concurrently, China’s GB standards dictate packaging safety and material composition. Suppliers must navigate the trade-off between advanced barrier performance and circular economy compliance to secure long-term contracts.
Market Dynamics
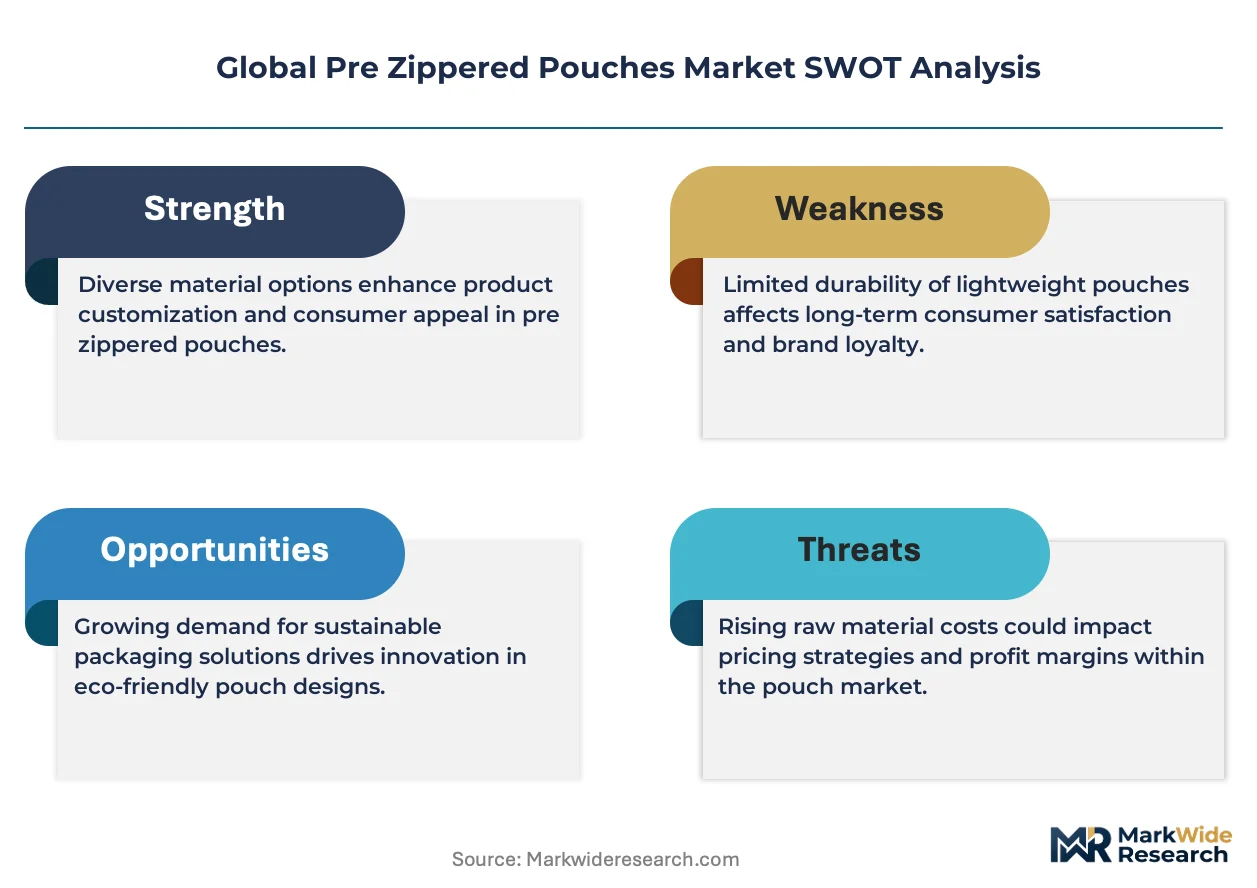
The central tension shaping the pre-zippered pouch market is the conflict between achieving high-barrier product protection and meeting stringent circular economy mandates. This forces material science innovation to reconcile performance requirements, such as oxygen and moisture resistance, with recyclability targets set by regulations like the EU Green Deal.
Growth Catalysts
- Premium Pet Care Expansion:Demand for high-value pet foods with specific nutritional profiles drives adoption of premium, resealable stand-up pouches that preserve freshness and offer consumer convenience.
- E-commerce Packaging Demand:The growth of online retail for packaged goods, particularly in China, favors flexible, lightweight, and durable pouch formats that reduce shipping weight and volume compared to rigid containers.
- Monomaterial Mandates:Regulatory initiatives, including the EU's focus on recyclability, are accelerating the development and adoption of monomaterial PE or PP pouches, creating a clear pathway for compliant packaging solutions.
Market Restraints
- Polymer Price Volatility:Pouch manufacturing costs are directly exposed to fluctuations in the price of polyethylene and polypropylene resins, creating margin pressure for converters and price uncertainty for CPG buyers.
- Barrier vs. Recyclability Trade-off:High-performance multi-layer films that provide the best product protection are often incompatible with standard recycling streams, creating a technical hurdle for circular economy compliance.
- Substitution from Paper-Based Alternatives:Brands pursuing aggressive plastic reduction targets are increasingly exploring paper-based flexible packaging, posing a substitution threat to all-plastic pouch formats for certain dry goods applications.
Strategic Opportunities
- Pharmaceutical and Nutraceutical Applications:Underpenetrated segments like single-dose medications, supplements, and medical devices offer an opportunity for high-margin pouches featuring child-resistant zippers and specialized barrier properties.
- Cold-Chain Logistics:The expansion of refrigerated and frozen food delivery services creates a need for durable, resealable pouches that can withstand low temperatures and maintain product integrity throughout the cold chain.
- Recyclability Certification Services:Suppliers can offer value-added services by guiding clients through complex recyclability certification processes, such as those required under the EU's Packaging and Packaging Waste Regulation.
Industry Challenges
- Navigating Global Regulatory Divergence:Suppliers face significant complexity in managing material compliance across differing standards, including FDA food-contact rules, EU recyclability targets, and China's GB standards for material composition.
- Capital Investment for New Material Lines:Transitioning production to support emerging monomaterials or paper-based structures requires significant capital expenditure in new extrusion, lamination, and converting equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pre Zippered Pouches Market |
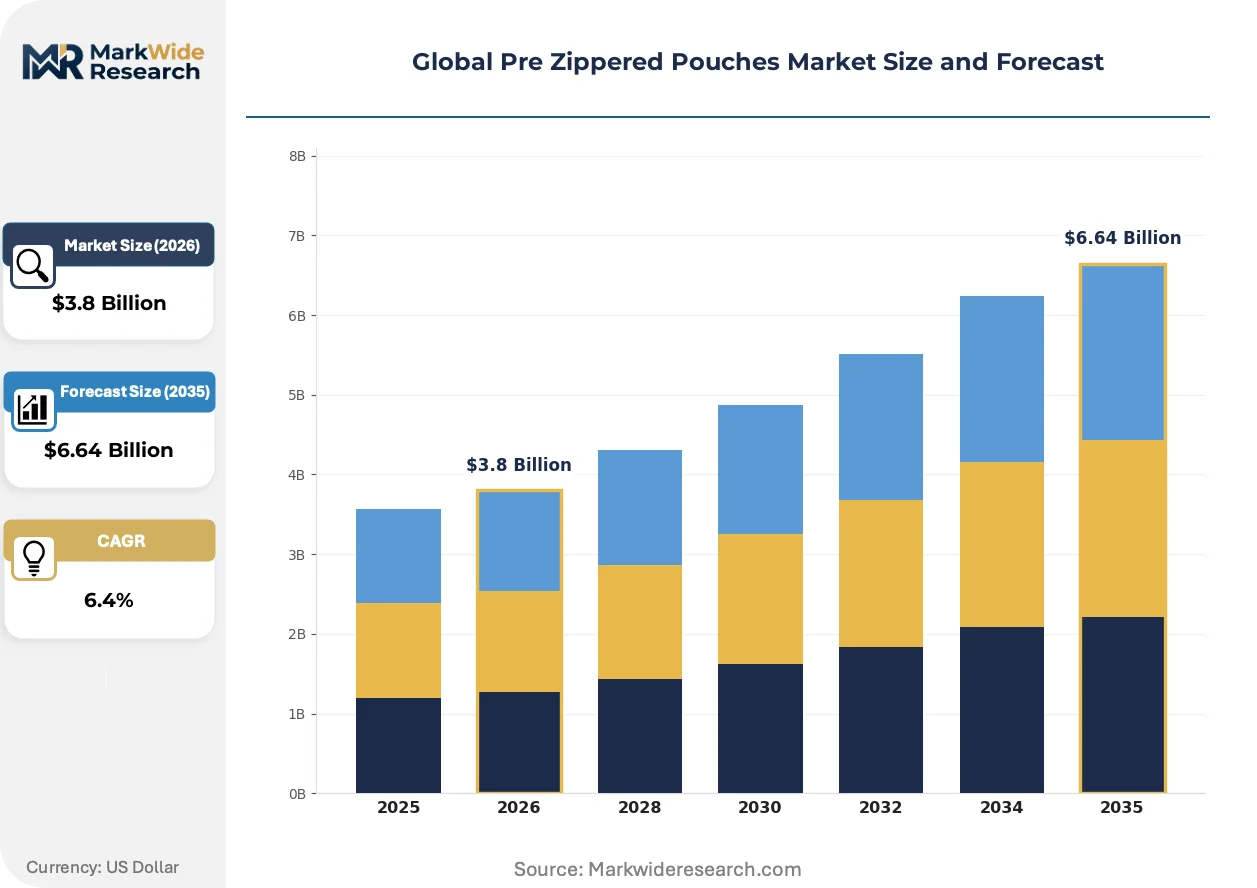
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Side Gusset Pouches, Mini Pouches Material: Plastic, Paper, Aluminum Foil, Compound Materials End User: Food Industry, Healthcare, Personal Care, Pet Care Closure Type: Single Zipper, Double Zipper, Tear Notch, Others |
| Companies Covered | Amcor Limited, Sealed Air Corporation, Mondi Group, Huhtamaki Oyj, Berry Global Group, Sonoco Products Company, ProAmpac Holdings LLC, Coveris Holdings S.A., Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pre Zippered Pouches Market Strategic Shifts & Innovations
Material science and regulatory pressures are fundamentally altering the design and composition of flexible packaging. This evolution moves the basis of competition from simple cost-per-unit to a more complex calculus involving lifecycle impact, regulatory compliance, and consumer perception.
Advanced monomaterial films, predominantly based on polyethylene, provide a pathway to recyclability that multi-laminate structures lack. Food, pet care, and home care brands are adopting these materials to meet sustainability commitments and prepare for stricter regulations. The shift toward these simplified material structures is consolidating the technology choices for brands that require both barrier performance and circular economy alignment.
European Union policy, specifically the Packaging and Packaging Waste Regulation, imposes strict targets for packaging recyclability and recycled content. This regulation directly impacts pouch design, compelling a move away from complex, multi-material laminates that are difficult to process in recycling facilities. Food and beverage manufacturers supplying the EU market are most affected, actively reformulating packaging to ensure compliance.
Buyer behavior is evolving from transactional, price-focused procurement toward integrated partnerships with packaging suppliers. This shift displaces vendors competing solely on cost, favoring those who provide comprehensive support, including lifecycle analysis, material selection consulting, and recyclability certification guidance. This trend is most prominent in the organic food and premium consumer goods segments, where sustainability claims are a core part of brand value.
Global Pre Zippered Pouches Market Segmentation
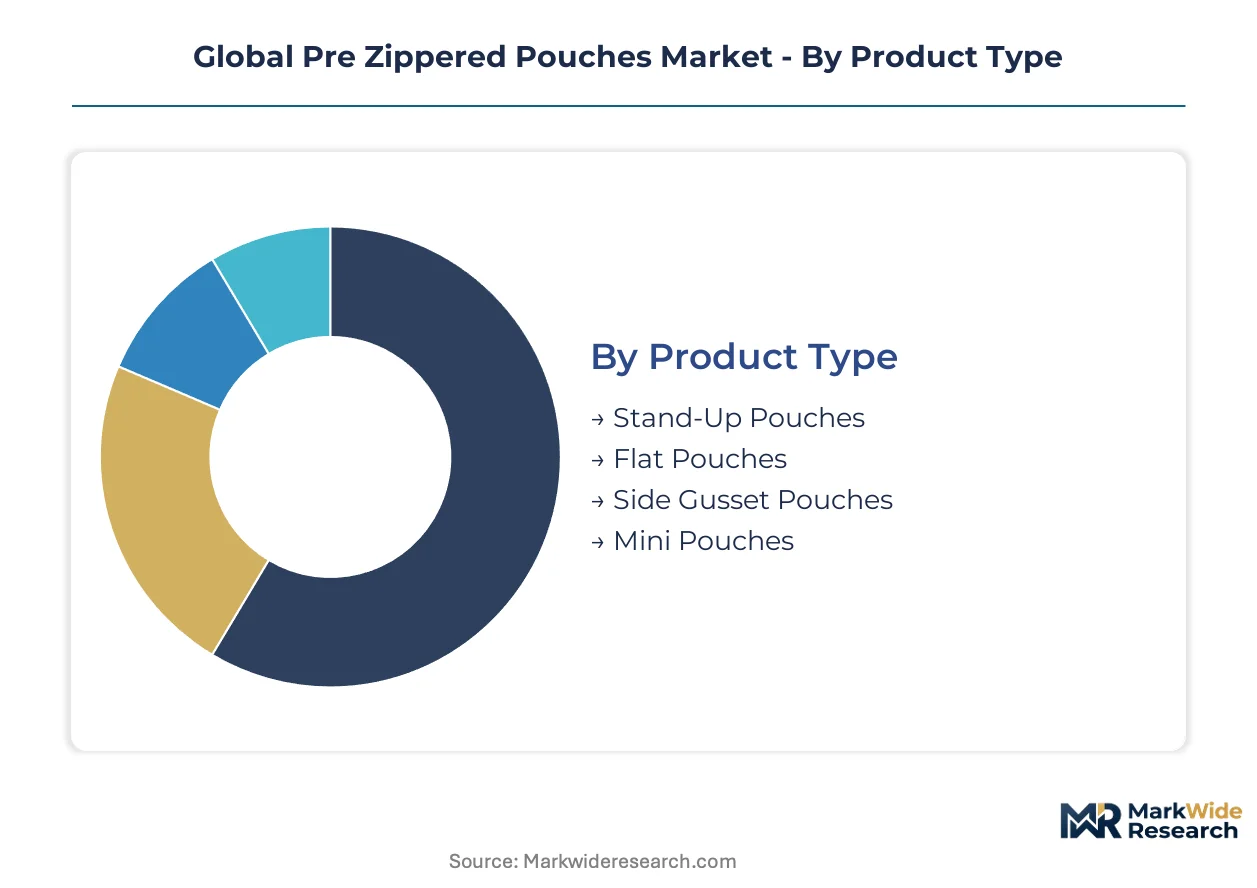
The pre-zippered pouches market segments by distinct product types, material compositions, end-user applications, and closure mechanisms. Understanding these divisions allows packaging suppliers to align their capital investments with specific demand patterns and regulatory compliance needs. Each segment presents unique challenges and opportunities for innovation within the flexible packaging landscape.
Product Type:
The capital intensity of pre-zippered pouch production varies significantly across product types, with stand-up pouches often requiring more specialized forming and sealing equipment. This necessitates higher upfront investment for manufacturers targeting visually prominent formats. Flat pouches, conversely, often leverage more standardized converting lines, reducing initial capital outlay.
- Stand-Up Pouches:These flexible packages feature a bottom gusset, allowing them to stand upright on shelves. They command the largest market share due to superior shelf visibility and consumer convenience, particularly in the food and pet care sectors across Europe and North America.
- Flat Pouches:These pouches are typically sealed on all four sides, offering a simple, cost-effective packaging solution. Demand for flat pouches concentrates in single-serve portions and sample sizes, especially within the snack and personal care industries.
- Side Gusset Pouches:Characterized by gussets on their sides, these pouches provide increased volume capacity while maintaining a compact footprint. Coffee and bulk dry goods manufacturers utilize this format for efficient storage and transport.
- Mini Pouches:Small-format pouches designed for single servings or individual doses, these are prevalent in nutraceuticals and confectionery.
Stand-up pouches absorb the bulk of installed capacity; mini pouches are expanding most quickly.
Material:
Supply concentration for pouch materials heavily favors polymer producers, particularly those specializing in polyethylene and polypropylene resins. The shift towards monomaterial solutions is reshaping the material supply chain, as converters seek fewer, more integrated suppliers for compliant films. Paper-based alternatives, while growing, still represent a smaller, more specialized supply base.
- Plastic:Dominated by polyethylene (PE) and polypropylene (PP), plastic materials offer excellent barrier properties and flexibility. Monomaterial PE pouches are gaining traction across the EU and North America to meet recyclability targets.
- Paper:Paper-based flexible packaging provides an alternative for brands aiming to reduce plastic content, particularly for dry goods. Mondi Group offers a range of paper-based solutions appealing to sustainability-focused brands.
- Aluminum Foil:Aluminum foil provides an exceptional barrier against oxygen, moisture, and light, crucial for sensitive products. Pharmaceutical and high-barrier food applications utilize aluminum foil for extended shelf life.
- Compound Materials:These multi-layer laminates combine different materials to achieve specific barrier and mechanical properties. High-performance compound materials face scrutiny under new EU recycling regulations.
Plastic materials dominate production, while paper-based alternatives are gaining traction.
End User:
Demand concentration for pre-zippered pouches is highest within the food industry, which utilizes these formats for a vast array of products from snacks to frozen meals. The pet care segment exhibits significant growth, driven by premiumization trends and consumer demand for convenient, resealable packaging. Healthcare and personal care sectors also contribute to overall demand, albeit with specific regulatory requirements.
- Food Industry:The primary end-user segment, the food industry leverages pre-zippered pouches for convenience, extended shelf life, and portion control. This includes snacks, dried fruits, cereals, and frozen foods, particularly in China's expanding e-commerce sector.
- Healthcare:This segment requires specialized pouches for pharmaceuticals, medical devices, and supplements, often with child-resistant features. Strict FDA and EMA guidelines govern material selection for medical applications.
- Personal Care:Pouches for cosmetics, toiletries, and cleaning products offer lightweight and travel-friendly options. Brands increasingly adopt flexible packaging for liquid and semi-liquid formulations.
- Pet Care:The fastest-growing application area, pet care utilizes resealable pouches for premium pet food and treats. This segment values packaging that preserves freshness and offers consumer convenience.
The food industry drives the largest volume, but pet care applications exhibit the steepest expansion trajectory.
Closure Type:
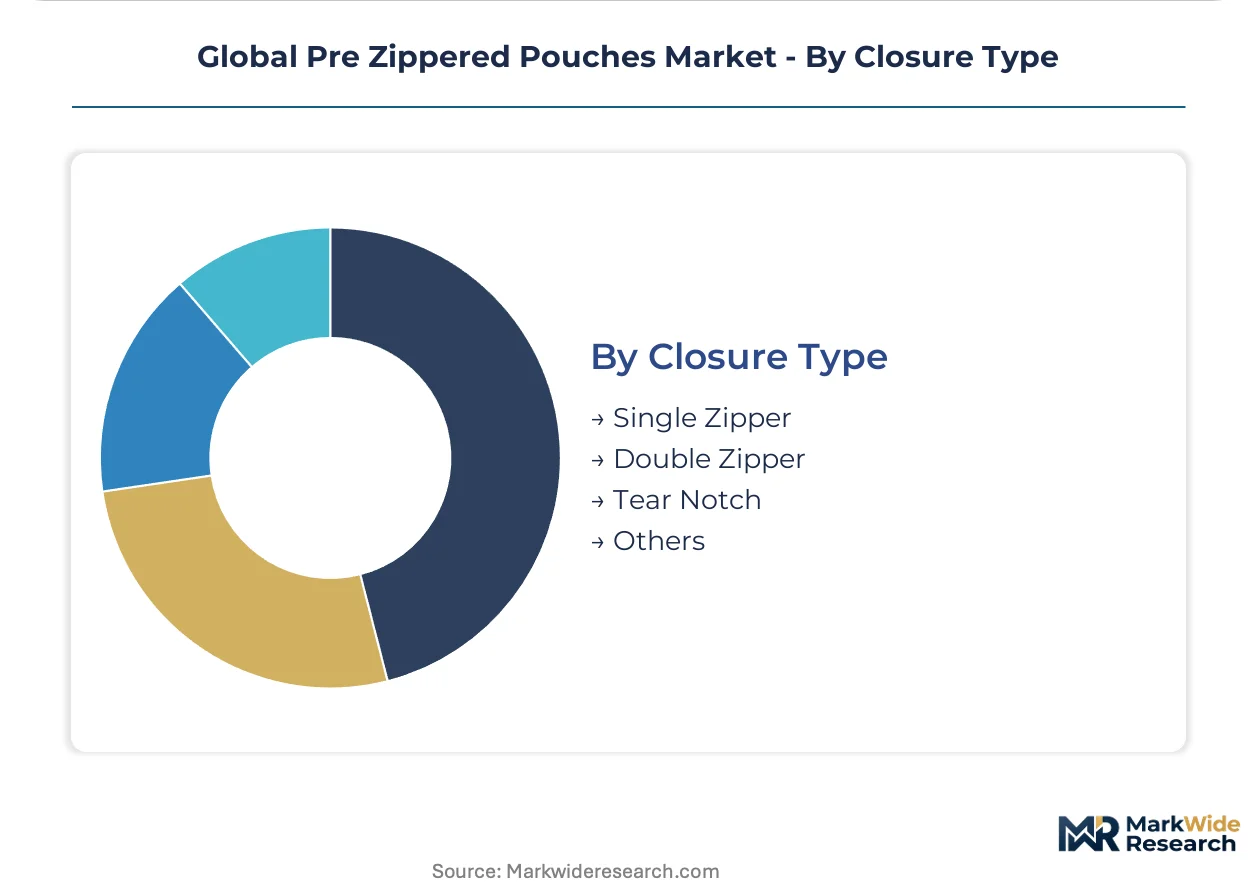
Consumer convenience is a primary driver in the selection of closure types for pre-zippered pouches, with single zippers being the most common and widely accepted. Double zippers offer enhanced product protection and freshness, appealing to premium segments. Tear notches provide initial tamper evidence and easy opening, often combined with a resealable zipper for subsequent use.
- Single Zipper:The standard resealable closure, a single zipper provides convenient opening and reclosing for everyday products. This closure type is ubiquitous across food and pet care packaging.
- Double Zipper:Featuring two interlocking zipper tracks, double zippers offer superior hermetic sealing and enhanced barrier protection. Premium food products and sensitive ingredients often utilize double zipper technology for extended freshness.
- Tear Notch:An integrated cut or perforation on the pouch, the tear notch facilitates easy initial opening. Many pouches combine a tear notch for initial access with a resealable zipper for subsequent use.
- Others:This category includes specialized closures like child-resistant zippers, press-to-close features, and custom designs. Pharmaceutical and high-value consumer goods often integrate these specialized closure mechanisms.
Single zipper formats are ubiquitous, as double zipper designs offer a premium solution for enhanced product preservation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global production of pre-zippered pouches often concentrates in regions with established film extrusion and converting capabilities. However, consumption is driven by large consumer markets with evolving purchasing habits and regulatory landscapes. This creates a dynamic interplay between manufacturing hubs and high-demand areas.
United States
Demand for pre-zippered pouches in the United States is spurred by the expansive food and beverage sector and premium pet care segments. The FDA sets guidelines for food-contact materials, influencing material selection for packaging innovations. Key packaging clusters in states like Illinois and California focus on developing advanced barrier solutions for specialized applications.
Germany
Germany drives European pre-zippered pouch innovation, emphasizing sustainable packaging solutions for its robust consumer goods market. The EU's Packaging and Packaging Waste Regulation imposes strict recyclability targets, accelerating the shift to monomaterials. Packaging machinery manufacturers in Bavaria actively develop equipment for efficient pouch production and sealing.
China
China's pre-zippered pouch market is significantly influenced by the rapid expansion of e-commerce for packaged goods, favoring flexible formats. The country's GB standards dictate packaging safety and material composition, guiding local and international suppliers. Industrial zones near Shanghai and Guangzhou serve as major production and distribution hubs for flexible packaging.
India
India's growing middle class and organized retail sector are fueling the demand for convenient, resealable pre-zippered pouches across food and personal care. The BIS (Bureau of Indian Standards) sets quality and safety standards for packaging materials. Packaging manufacturers in Maharashtra and Gujarat are expanding capacity to meet domestic market needs.
Japan
Japanese consumers prioritize product quality and convenience, driving demand for high-barrier pre-zippered pouches in food and nutraceuticals. METI (Ministry of Economy, Trade and Industry) promotes sustainable packaging initiatives and material recycling. Packaging technology firms in the Kanto region lead research into advanced film structures and functional closures.
Global Pre Zippered Pouches Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the pre-zippered pouches market, creating a tiered competitive landscape. The market structure features large integrated players alongside specialized converters. Strategic archetypes include global material suppliers, regional flexible packaging specialists, and niche solution providers. Dominant competitive moves involve capacity expansion to meet demand and strategic partnerships for material innovation.
Global material suppliers like Amcor Limited and Mondi Group represent broad portfolios spanning diverse packaging solutions. These entities occupy a position leveraging extensive manufacturing footprints and material science expertise, serving a wide range of end-user industries. Huhtamaki Oyj also sits within this tier, exemplifying a focus on flexible packaging solutions across multiple geographies. These players often drive innovation in monomaterial films and sustainable alternatives to meet evolving regulatory and brand requirements. ProAmpac Holdings LLC, another significant player, anchors a strong presence in North America, specializing in custom flexible packaging.
| Leading Market Players |
|---|
| Amcor Limited |
| Sealed Air Corporation |
| Mondi Group |
| Huhtamaki Oyj |
| Berry Global Group |
| Sonoco Products Company |
| ProAmpac Holdings LLC |
| Coveris Holdings S.A. |
| Constantia Flexibles |
Cost & Logistics Intelligence
Captive supply of specialized barrier films anchors the competitive position for large integrated packaging producers, directly influencing their pricing power for pre-zippered pouches. This integration ensures material consistency and mitigates external polymer price volatility.
Pricing Analysis
Cost-down pressure on commodity flexible packaging intensifies due to polymer price volatility and increasing regulatory compliance costs. The dominant pricing model for pre-zippered pouches involves contract-based long-term offtake agreements, often with hybrid elements for specialized films. Price differentiation stems from the customization level required for specific product applications and the recyclability certification level under regulations like the EU's Packaging and Packaging Waste Regulation. Food industry buyers exhibit higher price sensitivity compared to pharmaceutical or nutraceutical clients.
Supply Chain Analysis
Reverse logistics for flexible packaging primarily involves post-consumer collection and sorting for mechanical or chemical recycling, driven by circular economy mandates. Supply concentration for pre-zippered pouch materials anchors in major polymer production hubs like China, Germany, and the United States. The industry relies heavily on polyethylene and polypropylene resins, alongside specialized barrier coatings, making commodity price volatility a significant structural supply chain risk. Direct-to-manufacturer sales and specialized packaging distributors constitute the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pre-zippered pouches market operates as a supply-constrained environment, primarily due to specialized extrusion and lamination capacity for advanced monomaterial films. This bottleneck props up pricing power for converters with established production lines.
For Market Incumbents:To counter the threat of substitution from paper-based alternatives, incumbents should accelerate investment in advanced monomaterial PE and PP film R&D. Capacity addition in key European and North American markets for monomaterial production strengthens supply security and regulatory compliance. Investing in recyclability certification services for clients represents a key lever for value-added partnerships. Consolidating smaller regional converters expands geographic reach and market share.
For New Entrants and Emerging Players:Specialized barrier coating innovations offer a technology-first wedge into high-value applications like pharmaceuticals and nutraceuticals. Underpenetrated segments, such as single-dose medications or medical devices, present white-space targets for bespoke pouch solutions. Focusing on child-resistant zippers and specialized barrier properties for these applications provides a differentiated go-to-market angle. The cold-chain logistics market also offers growth for durable, temperature-resistant pouches.
For Investors and Strategic Acquirers:Exit pathways concentrate in integrated flexible packaging converters possessing advanced monomaterial production capabilities. The market demonstrates long-term viability over the next decade, driven by ongoing demand for convenience and sustainability mandates. Acquisition targets should be mid-sized specialists with strong R&D in barrier films or specialized closure technologies. The rate of new monomaterial film certifications under EU regulations serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Monomaterial Extrusion | Enhances compliance with EU Green Deal mandates for recyclable packaging, securing long-term brand contracts. |
| Expand Recyclability Certification Services | Offers value-added support to brands navigating complex regulations like the EU Packaging and Packaging Waste Regulation. |
| Develop Child-Resistant Zipper Technology | Captures high-margin opportunities in pharmaceutical and nutraceutical applications, meeting strict safety standards. |
| Target Cold-Chain Compatible Materials | Addresses the growing demand from refrigerated and frozen food delivery services for durable pouches. |
| Acquire Regional Flexible Packaging Converters | Consolidates market share and expands manufacturing footprint in high-demand regions like North America. |
Research Approach
Independent corroboration across industry reports, company financial filings, and trade association publications underwrites the qualitative findings. Primary interviews with packaging executives, material scientists, brand managers, and regulatory affairs specialists provided critical market insights. This approach combined bottom-up data aggregation with top-down market sizing, ensuring robust triangulation. Secondary sources included FDA guidelines and EU Packaging and Packaging Waste Regulation documents.
Rate-of-change decomposition analyzes growth across product types, material compositions, end-user applications, and closure mechanisms over the projection horizon. The analytical framework integrated historical trends with future projections, deriving compound annual growth rates from supply-demand imbalances. Modeled segmentation dimensions included pouch format, material type, and regional regulatory clusters. Key forecast inputs included polymer resin price forecasts and e-commerce expansion.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid shifts in consumer preferences for rigid packaging. Forecasts reflect assumptions regarding regulatory stability and material science innovation. Practitioners should monitor new legislative mandates and major polymer capacity expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Cold Seal Lamination Pouch Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Flat Bottom Pouch Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Clipless Vertical Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Doyen Style Pouches Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Inverted Pouch Market
Pouch
Brazil Pouch Packaging Market
Pouch
Retort Pouch Market
Pouch
Colombia Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Inflatable Pouches Market
Pouch
Pouch Equipment Market