
 Egypt Pouch Packaging Market | 2026-2036
Egypt Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Pouch Packaging Market Insights
Aftermarket technical service revenue is rewriting value capture dynamics in Egypt's pouch packaging sector. Huhtamaki Oyj leverages its regional technical service infrastructure to secure long-term converter partnerships. Amcor Group GmbH anchors its position through backward integration into film extrusion, reducing resin cost volatility for Egyptian customers. Mondi PLC differentiates via specialized kraft-paper barrier solutions tailored to North African humidity conditions.
Pouch packaging denotes a flexible containment format fabricated from mono- or multilayer films, typically incorporating polyethylene, polypropylene, or aluminum oxide barrier coatings, and sealed through heat- or ultrasonic-welding processes to preserve shelf stability for flowable, granular, or viscous contents. Stand-up pouches occupy the dominant share among product types due to their retail shelf presence and material efficiency versus rigid alternatives. Plastic-based composites lead material demand, though paper and aluminum laminates are gaining traction in premium personal care and pharmaceutical applications where oxygen and moisture ingress must be controlled. Food & Beverage end users drive volume, with pharmaceuticals representing a higher-margin segment where compliance with NFSA and Ministry of Health requirements adds qualification barriers.
Egypt's National Food Safety Authority (NFSA) mandates migration testing and additive disclosure for food-contact materials, compelling importers and local converters to maintain certified laboratory partnerships. The Egyptian Organization for Standardization and Quality (EOS) aligns with ISO 9001 and ISO 22000 frameworks, creating audit overhead that favors established players with dedicated quality systems. Stakeholders must monitor NFSA's anticipated expansion of recycled-content thresholds, as this will reshape material sourcing decisions and supplier qualification timelines for converters serving export markets.
Market Dynamics
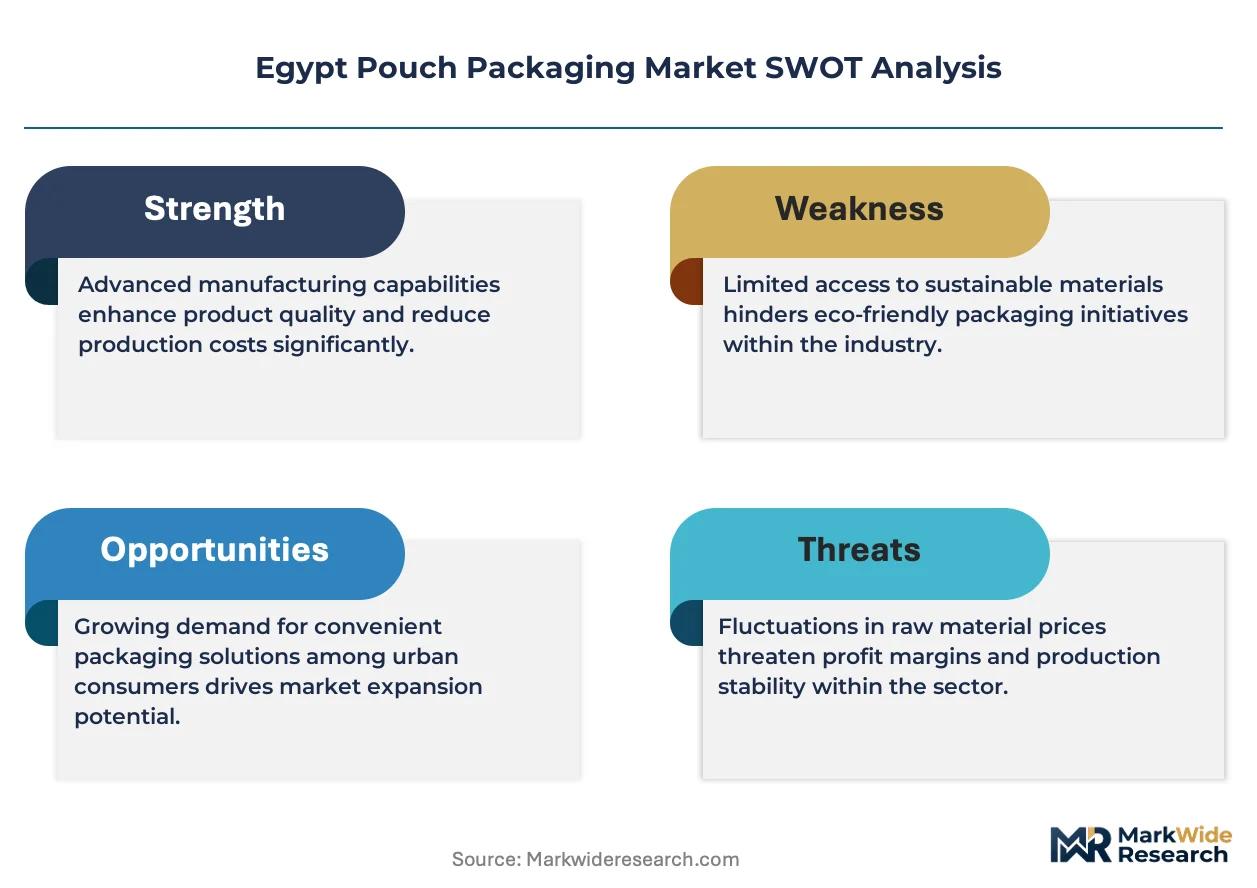
Egypt's NFSA is tightening food-contact material standards faster than local testing infrastructure can expand, forcing converters to absorb certification delays or lose export contracts to Turkish and UAE competitors with established laboratory partnerships.
Growth Catalysts
- Stand-up pouch adoption:Food & Beverage processors in Greater Cairo are replacing rigid containers with stand-up pouches for dairy and sauce applications, cutting logistics costs and extending shelf presence in modern retail chains.
- NFSA compliance mandates:Migration testing requirements are filtering out informal converters, concentrating volume among qualified suppliers with ISO 22000-certified quality systems and dedicated laboratory access.
- Port logistics clustering:Alexandria's container terminal infrastructure enables export-oriented pouch production for North African and Levantine markets, attracting film suppliers to co-locate extrusion capacity nearby.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene prices track Gulf petrochemical feedstock movements, squeezing converter margins when Egyptian pound depreciation accelerates import cost pass-through.
- Multilayer film supply concentration:Barrier film expertise concentrates among a handful of European and Turkish suppliers, creating qualification bottlenecks for local converters seeking aluminum oxide-coated substrates.
- Substitution by rigid formats:Glass and metal cans retain preference in premium olive oil and traditional preserves segments where consumers associate rigidity with authenticity and extended shelf stability.
Strategic Opportunities
- Upper Egypt penetration:Food processing clusters in Minya and Sohag remain underserved by qualified pouch converters, creating first-mover advantage for suppliers establishing technical service presence beyond Cairo-Alexandria corridor.
- Pharmaceutical compliance specialization:Ministry of Health registration pathways for primary drug packaging present margin expansion potential for converters investing in cleanroom slitting and barrier validation protocols.
- Kraft-paper barrier convergence:Combining FSC-certified paper substrates with water-based barrier coatings addresses humidity-sensitive applications in personal care, differentiating offerings from pure plastic alternatives.
Industry Challenges
- Migration testing talent scarcity:Qualified analytical chemists capable of executing NFSA-compliant extractables studies command premium salaries, constraining converter expansion timelines.
- Multilayer lamination capex intensity:Solventless adhesive lamination lines require foreign currency-denominated equipment purchases, exposing investment returns to exchange rate risk.
- Recycled content integration complexity:Anticipated NFSA thresholds for post-consumer recycled material in food-contact layers demand requalification of entire supply chains without guaranteed feedstock availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Pouch Packaging Market |
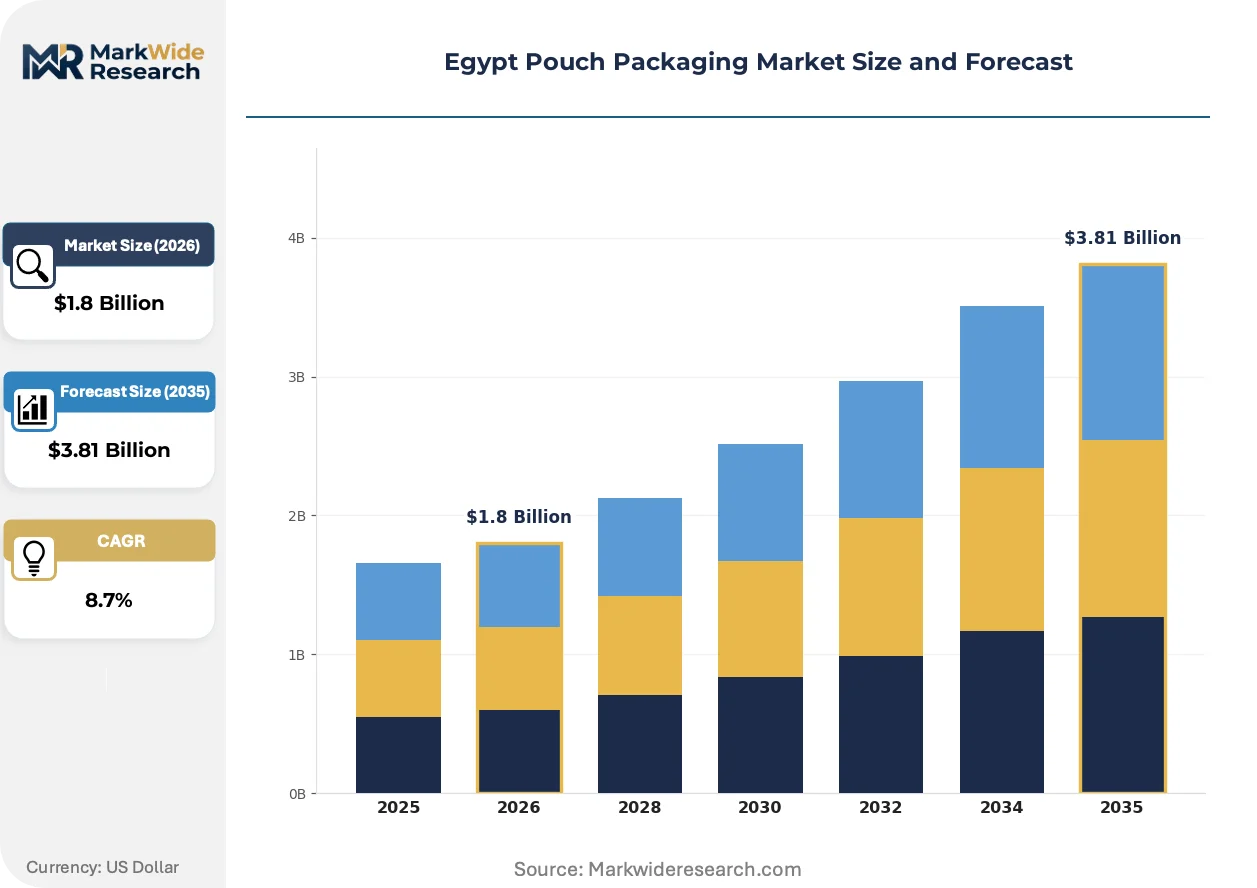
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zip Pouches, Vacuum Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Press-to-Close, Zipper, Spout, Others |
| Companies Covered | Huhtamaki Oyj, Amcor Group GmbH, Mondi PLC, Coveris Management GmbH, The Tetra Pak Group, International Printing & Packaging Materials Co, SofiPack, Taghleef Industries SpA, Flexi Pack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging features are compressing minimum order quantities and enabling brand-specific traceability, while regulatory pressure on plastic waste accelerates material substitution experiments across Egypt's packaging value chain.
High-definition flexographic and digital inkjet systems are rendering obsolete the traditional gravure cylinder setup for short-run pouch decoration. Regional brand owners in condiments and personal care are adopting digitally printed pouches for seasonal promotions and limited editions. The technology is rendering obsolete the economic advantage of long print runs, enabling micro-segmentation strategies that were previously uneconomical at Egyptian volume scales.
NFSA's anticipated expansion of recycled-content thresholds is compelling converters to establish supplier qualification protocols for post-industrial and post-consumer polyethylene streams. The policy trajectory mirrors EU Packaging and Packaging Waste Regulation alignment pressures facing Egyptian exporters. Pharmaceutical and premium food segments are responding by segregating supply chains—maintaining virgin-only streams for regulated applications while developing certified recycled streams for non-food industrial packaging.
Brand owners are consolidating pouch procurement under technical service contracts that bundle material supply, graphic design adaptation, and inventory management. This displaces the traditional spot-market purchasing model dominated by trading intermediaries. The shift is most visible among multinational FMCG subsidiaries operating Egyptian manufacturing facilities, where global procurement mandates favor integrated supplier relationships over transactional converter engagements.
Egypt Pouch Packaging Market Segmentation
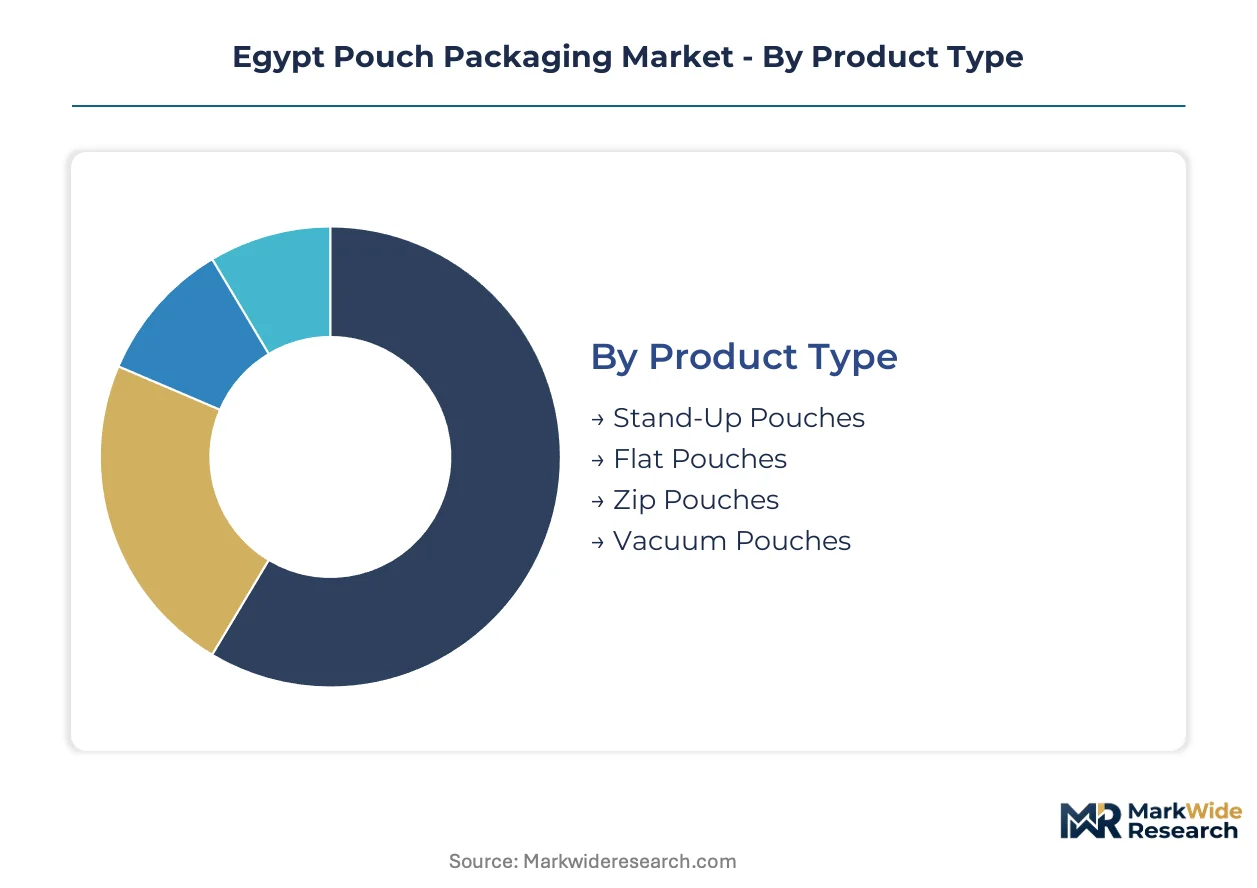
Egypt's pouch packaging market segments across four functional dimensions that determine converter capability requirements and margin structures. Product geometry, material composition, end-use compliance burdens, and closure complexity each create distinct supplier qualification tiers.
Product Type:
Stand-up pouches dominate retail shelf presence across Egyptian supermarkets and hypermarkets, while flat formats retain cost advantages in bulk industrial applications.
- Stand-Up Pouches:Multilayer laminates with gusseted bases enable vertical display and optimize shelf space utilization. Dairy processors in Greater Cairo and Alexandria are converting yogurt and labneh lines from rigid tubs to stand-up formats, driven by logistics cost reduction and modern retail chain requirements.
- Flat Pouches:Two-dimensional sealed bags minimize material usage for dry goods and frozen products. Frozen vegetable packagers in the 10th of Ramadan industrial zone favor flat pouches for export shipments to Gulf markets, where pallet density and shipping cube efficiency outweigh shelf-display priorities.
- Zip Pouches:Reclosable interlocking strips extend product usability for multi-serve applications. Snack brands targeting Egyptian households with children specify zip closures to differentiate from commodity single-serve packs.
- Vacuum Pouches:High-barrier multilayer structures with air evacuation capability preserve protein freshness. Processed meat manufacturers serving hotel and catering channels require vacuum formats compliant with NFSA migration limits.
Established volume favors stand-up configurations; emerging adoption favors zip-enabled convenience formats.
Material:
Material selection in Egypt balances barrier performance against NFSA compliance timelines and import cost exposure from resin and substrate sourcing.
- Plastic:Polyethylene and polypropylene laminates constitute the baseline for cost-sensitive food applications. Egyptian converters face margin pressure when Gulf petrochemical feedstock prices spike and pound depreciation accelerates import pass-through.
- Paper:Kraft substrates with water-based barrier coatings address humidity-sensitive personal care segments. Mondi PLC has established regional supply chains for FSC-certified paper solutions tailored to North African climate conditions.
- Aluminum:Foil laminates deliver oxygen and light barrier performance for pharmaceutical blister packs and premium coffee. Ministry of Health registration requirements create qualification bottlenecks for converters lacking validated cleanroom slitting capacity.
- Composites:Engineered multilayer structures combine plastic, paper, and aluminum oxide coatings for tailored barrier profiles. Export-oriented converters in Alexandria are qualifying composite substrates from Turkish suppliers to meet EU-bound customer specifications.
Plastic maintains cost leadership at volume; composites command premium positioning in regulated export channels.
End User:
End-use segmentation determines compliance burden intensity and technical service requirements for Egyptian pouch converters.
- Food & Beverage:Sauces, dairy, and ready-to-eat meals drive the majority of Egyptian pouch volume. NFSA migration testing mandates and ISO 22000 certification requirements filter out informal suppliers, concentrating contracts among established players with dedicated laboratory partnerships.
- Personal Care:Shampoo, conditioner, and lotion pouches demand humidity-resistant barrier performance. Premium brands are experimenting with kraft-paper composite formats to differentiate from conventional plastic tubes.
- Pharmaceuticals:Primary drug packaging requires Ministry of Health registration and cleanroom manufacturing protocols. This segment offers margin expansion potential but demands capital investment in barrier validation and extractables testing capability.
- Household Products:Detergent and cleaning chemical pouches prioritize chemical resistance and child-resistant closure compatibility. Industrial laundries and hospitality procurement channels specify large-format pouches with spout dispensers.
Food & Beverage anchors converter revenue; pharmaceuticals present the steepest expansion trajectory for qualified suppliers.
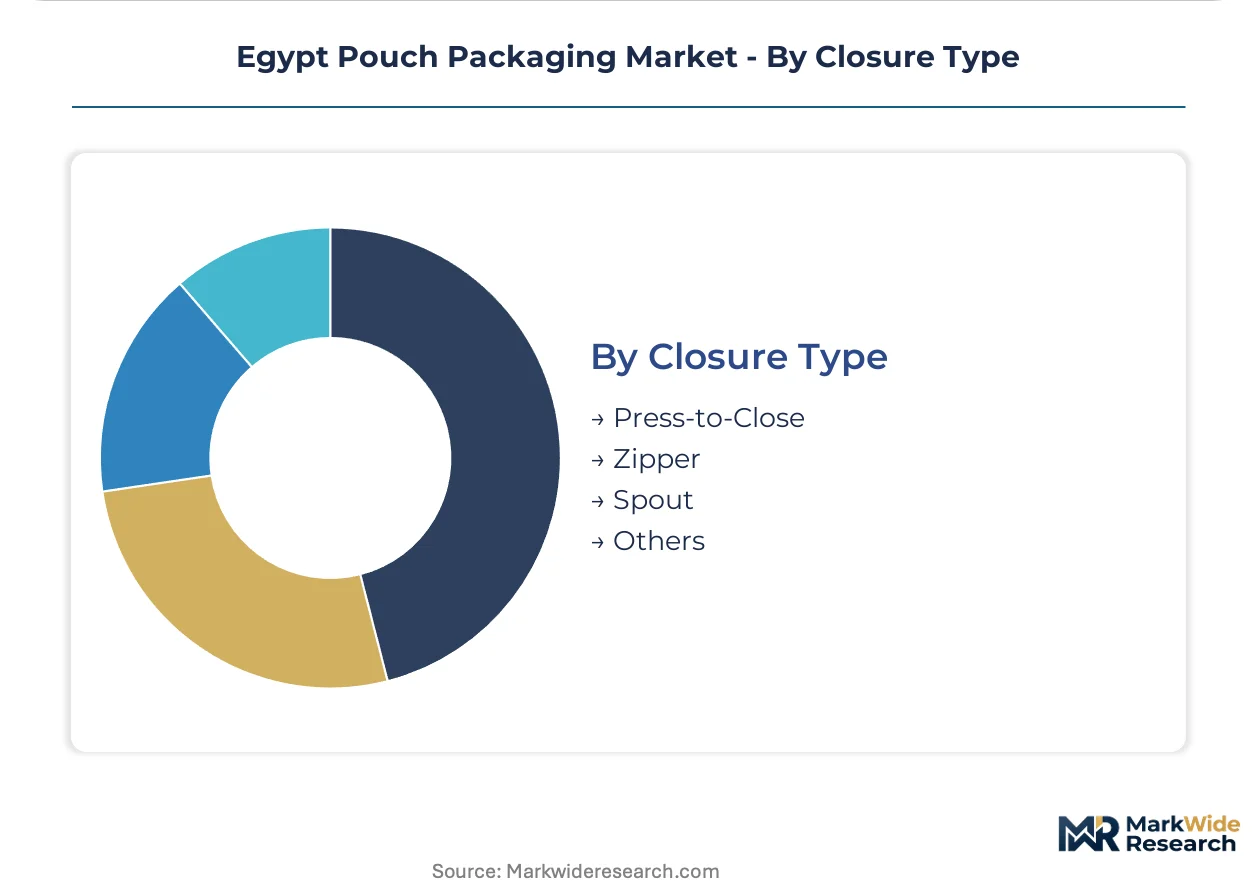
Closure Type:
Closure complexity determines equipment investment requirements and per-unit manufacturing economics for Egyptian converters.
- Press-to-Close:Simple interlocking tracks minimize machinery cost and maintenance burden. Commodity snack and confectionery applications in price-sensitive Egyptian retail channels favor this format.
- Zipper:Reclosable profiles require precision extrusion and alignment during form-fill-seal operations. Family-size dairy and dried fruit brands specify zipper closures to support multi-serve consumption patterns.
- Spout:Integrated dispensing nozzles enable controlled pouring for liquids and viscous products. Cooking oil and sauce manufacturers in 6th of October City industrial zone are adopting spout pouches to replace rigid bottles in modern trade.
- Others:Tear notches, laser scoring, and hook-and-loop systems serve niche applications. Pharmaceutical sample pouches and single-serve condiment packs utilize specialized opening features.
Press-to-close dominates unit economics; spout integration is gaining share fastest in liquid food conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Egypt's industrial geography. Greater Cairo and Alexandria buyers prioritize technical service reliability over unit cost, while Upper Egypt processors remain acutely price-sensitive, delaying pouch conversion until margin structures justify qualification investments.
Greater Cairo
Dairy and sauce manufacturers in 6th of October City and 10th of Ramadan industrial zones drive stand-up pouch adoption for modern retail channels. NFSA migration testing mandates filter supplier pools, concentrating contracts among converters with ISO 22000-certified quality systems. Obour City hosts the densest cluster of qualified laminators serving multinational FMCG subsidiaries.
Alexandria
Port logistics infrastructure enables export-oriented pouch production for North African and Levantine markets. The Dekheila container terminal attracts film suppliers co-locating extrusion capacity to reduce resin import lead times. Local converters qualify composite substrates from Turkish suppliers to meet EU-bound customer specifications.
Delta Region
Food processing clusters in Mansoura and Tanta remain underserved by qualified pouch converters, relying on Cairo-based suppliers with extended delivery cycles. Provincial manufacturers of frozen vegetables and traditional preserves retain rigid format preference due to lower qualification barriers. The gap creates first-mover opportunity for technical service expansion.
Upper Egypt
Minya and Sohag processing clusters exhibit the lowest pouch penetration rates nationally, constrained by converter absence and capital scarcity among local food manufacturers. Agricultural commodity packagers dominate, with limited shelf-stable product development requiring barrier packaging. Anticipated NFSA enforcement expansion may accelerate formalization and supplier qualification timelines.
Suez Canal Zone
Special economic zone incentives attract foreign packaging material distributors establishing regional fulfillment hubs. Port Said and Ismailia logistics platforms support re-export of European-manufactured barrier films to Gulf markets. Local value-add remains limited to warehousing and customs clearance rather than conversion activity.
Egypt Pouch Packaging Market Competitive Landscape
Capability concentration sits with multinational converters possessing dedicated laboratory partnerships and NFSA pre-qualification; scale advantage sits with regional players leveraging Cairo-Alexandria logistics clustering for domestic volume. The market structure reflects a two-tier dynamic where compliance overhead filters informal competitors, concentrating premium contracts among established technical service providers. Three archetypes dominate: integrated multinationals with backward film extrusion, specialized barrier converters, and trading intermediaries being displaced by bundled procurement contracts. Competitive moves center on laboratory partnership investments and geographic expansion into underserved Upper Egypt clusters.
Among European-anchored multinationals, Huhtamaki Oyj and Amcor Group GmbH exemplify the integrated archetype combining material supply with technical service infrastructure. Mondi PLC occupies a distinct position emphasizing paper-based barrier solutions. Egyptian specialists including International Printing & Packaging Materials Co and SofiPack represent the regional converter tier navigating resin cost volatility through spot-market purchasing flexibility. These domestic players sit within a contracting middle tier as multinational procurement mandates consolidate supplier relationships.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Amcor Group GmbH |
| Mondi PLC |
| Coveris Management GmbH |
| The Tetra Pak Group |
| International Printing & Packaging Materials Co |
| SofiPack |
| Taghleef Industries SpA |
| Flexi Pack |
| Others |
Pricing and Supply Chain Analysis
Alexandria's Dekheila port cluster concentrates barrier film extrusion capacity, granting co-located converters pricing leverage over Cairo-based competitors facing resin import markups. Egyptian pound depreciation against Gulf petrochemical currencies squeezes converter margins unevenly—proximity to import logistics determines who absorbs cost shocks versus passes them downstream.
Pricing Analysis
Technical service contract bundling drives lifetime value capture beyond per-unit material margins. Three-tier pricing structure across premium, standard, and economy levels separates NFSA-prequalified converters with laboratory partnerships from informal suppliers lacking migration testing capability. Cost compression in standard-tier commodity pouches is intensifying because Turkish competitors leverage established EU laboratory relationships to underbid on export contracts. Multinational FMCG subsidiaries show least price sensitivity, prioritizing compliance documentation over unit cost.
Supply Chain Analysis
Turkish export-control alignment with EU Packaging and Packaging Waste Regulation limits flow of advanced barrier substrates to Egyptian converters lacking pre-qualification. Resin supply draws from Saudi Arabia, UAE, and Qatar petrochemical complexes; aluminum oxide-coated films hinge on German and Italian specialty coating equipment. Single-source vulnerability concentrates in solventless adhesive lamination lines denominated in euros, exposing investment timelines to exchange rate volatility. Distribution runs through Alexandria port warehousing for export-bound production and direct converter delivery for domestic Greater Cairo demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational FMCG procurement offices consolidating supplier panels under global technical service mandates, fragmenting spot-market trading intermediaries.
For Market Incumbents: Build laboratory partnership moats through exclusive NFSA pre-certification arrangements with Cairo and Alexandria testing facilities. Deepen upstream control over film extrusion to buffer Gulf resin price volatility. Defend against Turkish converter encroachment by embedding inventory management services into long-term contracts. For New Entrants and Emerging Players: Establish a beachhead in Upper Egypt's Minya and Sohag processing clusters where qualified converter absence creates first-mover technical service opportunity. Target frozen vegetable packagers in Delta Region cities underserved by Cairo-based logistics. Lead with spout pouch capability for cooking oil manufacturers seeking rigid format replacement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized barrier converters with pharmaceutical cleanroom validation capability over commodity plastic laminators. Long-term viability rests on NFSA regulatory alignment and EU export qualification infrastructure. Watch for Ministry of Health registration pathway simplification as inflection signal for pharmaceutical packaging investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin conversion reduces Egyptian pound import exposure for Greater Cairo converters. |
| NFSA Laboratory Partnership Expansion | Pre-certified testing access accelerates converter qualification timelines for export contracts. |
| Upper Egypt Technical Service Presence | First-mover positioning in Minya and Sohag clusters captures underserved food processor demand. |
| Pharmaceutical Cleanroom Validation Investment | Ministry of Health registration capability unlocks premium-margin primary drug packaging segments. |
| Kraft-Paper Barrier Solution Development | FSC-certified substrates differentiate offerings in humidity-sensitive personal care applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with packaging converters, resin distributors, and NFSA compliance officers; and secondary validation through Egyptian Organization for Standardization and Quality technical bulletins, customs import records for polyethylene and polypropylene, and Ministry of Health pharmaceutical packaging registration databases. Bottom-up triangulation across converter capacity surveys and top-down demand estimation from food processor procurement data established volume baselines.
Forecast inputs incorporated stand-up pouch adoption rates across dairy and sauce applications, NFSA enforcement intensity projections, and Gulf petrochemical feedstock price correlation models. Segmentation dimensions spanned product geometry, material composition, end-use compliance burden, and closure complexity. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines reported by qualified converters.
Stress conditions across Egyptian pound depreciation bands, NFSA recycled-content threshold acceleration, and Turkish competitor pricing aggression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and feedstock market structure. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
MAP Flow Wrappers Market
Pouch
Compostable Pouches Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Foil Zipper Bags Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Feminine Care Pouch Film Market
Pouch
Squeeze Pouch Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Open Mouth Sacks Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Canada Pouch Packaging Market
Pouch
Flat Bottom Pouch Market