
 North America Pouch Packaging Market | 2026-2036
North America Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pouch Packaging Market Insights
Mexico's converting corridor from Guadalajara to Querétaro is rewriting regional supply dynamics for flexible packaging substrates. Amcor PLC leverages integrated film extrusion and converting assets across the US Midwest to sustain cost leadership in high-volume food applications. ProAmpac Intermediate Inc. anchors specialty retort and sustainable material platforms that differentiate its positioning against commodity-oriented competitors. Sealed Air Corporation dominates barrier innovation through controlled-atmosphere packaging systems that extend protein shelf life.
North America pouch packaging comprises flexible, sealed containers typically constructed from multi-layer plastic films, aluminum laminates, or fiber-based composites with barrier coatings, formed through horizontal or vertical form-fill-seal processes to protect contents from moisture, oxygen, and light. These structures serve primary containment functions across ambient, chilled, and retort-processed distribution chains. Stand-up pouches with spout closures command premium positioning in beverages and personal care, while flat pouches in heat-seal configurations occupy high-volume, cost-sensitive segments. Retort pouches for ready meals represent the fastest-growing material-application intersection as microwaveable convenience formats displace rigid trays. Composites incorporating post-consumer recycled content are gaining structural share despite yield and seal-strength trade-offs.
The US FDA regulates food-contact substances under 21 CFR, while Health Canada/PMRA oversees analogous safety standards, and California's SB 54 mandates recycled content minimums that reshape material procurement across North American supply chains. The EPA's emerging per- and polyfluoroalkyl substance restrictions will force reformulation of grease-resistant barrier layers by mid-decade. Stakeholders must monitor state-level extended producer responsibility enactments and pre-emptively qualify alternative barrier chemistries before compliance deadlines compress sourcing flexibility.
Market Dynamics
California's SB 54 recycled content mandates and the EPA's emerging PFAS restrictions are forcing simultaneous material requalification across North American flexible packaging supply chains, compressing reformulation timelines while brand owners accelerate single-serve format adoption.
Growth Catalysts
- Retort Pouch Technology:Microwaveable ready-meal formats are displacing rigid aluminum trays in protein and prepared food distribution, with foodservice operators and CPG brands converging on high-barrier flexible structures for shelf-stable convenience.
- Health Canada/PMRA Food-Contact Standards:Harmonized safety protocols across the US-Canada border are streamlining cross-border substrate qualification, reducing redundant testing cycles for multi-national food manufacturers operating integrated North American production networks.
- Atlanta-Charlotte Converting Cluster:Concentrated film extrusion, printing, and pouch converting capacity within the US Southeast creates logistics advantages for brand headquarters co-located in this corridor, accelerating prototype-to-production cycles for regional food and beverage launches.
Market Restraints
- Post-Consumer Recycled Content Yield Degradation:Mechanical recycling of multi-layer flexible films produces output with diminished tensile strength and heat-seal reliability, forcing converters to over-engineer structures or accept higher scrap rates in high-speed form-fill-seal operations.
- Resin Supply Concentration:Specialty barrier polymers and adhesive chemistries for retort and high-oxygen-barrier applications concentrate among a limited supplier base, exposing converters to allocation risk during upstream petrochemical disruptions.
- California Extended Producer Responsibility:SB 54 compliance infrastructure requires brand owners to fund collection and recycling systems, adding administrative cost layers that commodity pouch applications cannot absorb without price escalation.
Strategic Opportunities
- Mexico Guadalajara-Querétaro Corridor:Underdeveloped flexible packaging converting capacity relative to growing food processing investment creates white space for substrate suppliers and toll converters to establish regional supply nodes serving US Southwest and Central American markets.
- Fiber-Based Barrier Composites:Convergence of paperboard forming with thin-film barrier deposition is opening shelf-stable applications previously reserved for full plastic laminates, with pulp and paper majors repositioning toward food-contact barrier markets.
- US Southeast Protein Processing Expansion:Poultry and seafood processing capacity growth in Alabama and Mississippi is generating localized demand for vacuum and modified-atmosphere pouch formats, enabling geographic co-location strategies for dedicated converting lines.
Industry Challenges
- Multi-Layer Structure Design Expertise:Shortage of polymer scientists and packaging engineers capable of optimizing coextrusion layer ratios and adhesive selection for specific shelf-life targets limits converter innovation velocity and extends customer qualification cycles.
- Legacy Equipment Retrofit Complexity:Existing horizontal and vertical form-fill-seal lines require mechanical and control system modifications to handle thinner-gauge sustainable substrates and recycled-content films without compromising seal integrity or throughput rates.
- PFAS Alternative Qualification Timeline:Food manufacturers must complete migration testing and sensory validation for replacement grease-resistant barrier chemistries before EPA enforcement deadlines, compressing reformulation windows while maintaining existing product shelf-life specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pouch Packaging Market |
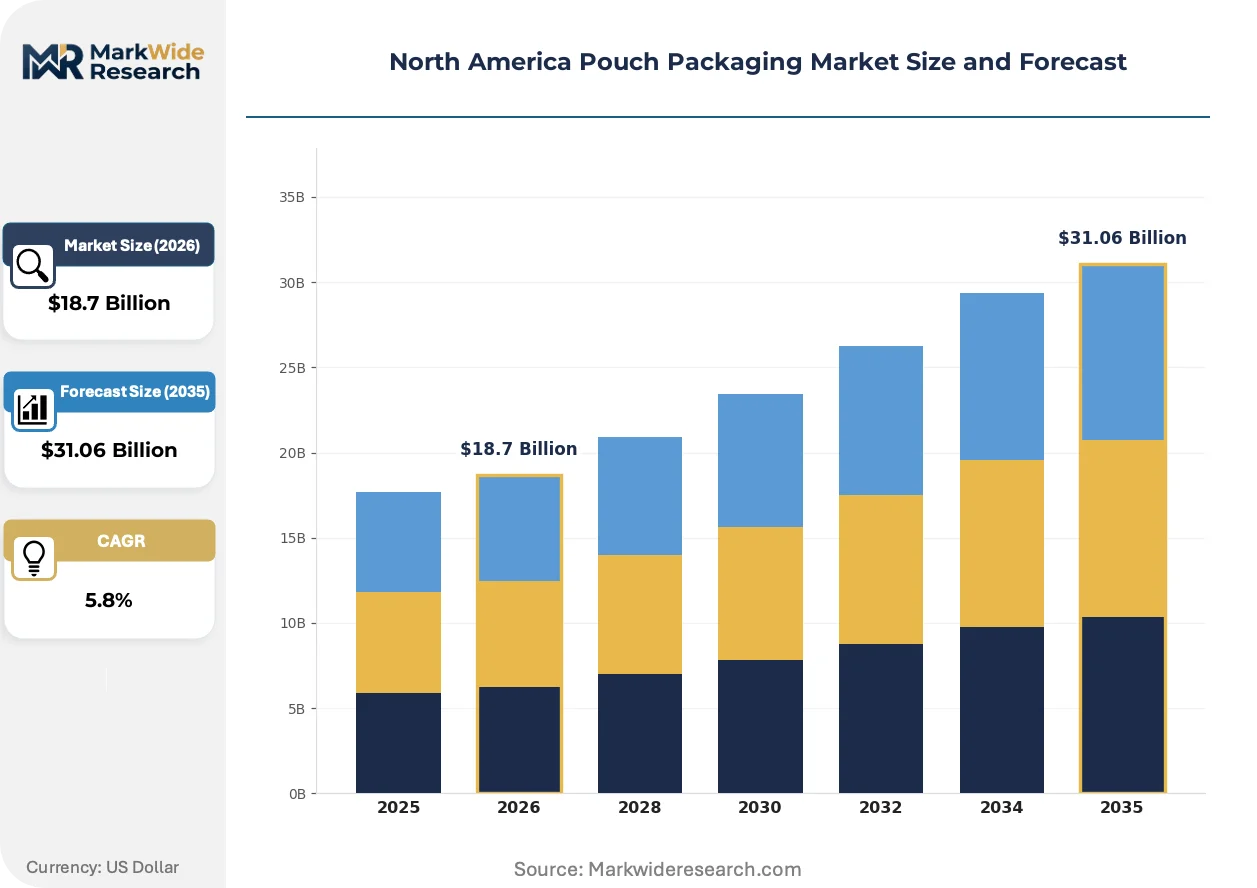
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Vacuum Pouches, Retort Pouches Material: Plastic, Paper, Aluminum Foil, Composites End User: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Products Closure Type: Zip Lock, Spout, Screw Cap, Heat Seal |
| Companies Covered | Amcor PLC, ProAmpac Intermediate Inc., Mondi Group, Constantia Flexibles Group GmbH, SIG Group AG, Sealed Air Corporation, Smurfit Kappa Group PLC, Coveris, Goglio Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pouch Packaging Market Trends and Innovations
Active and intelligent packaging integration, sustainable substrate re-engineering, and e-commerce-optimized format design are converging to redefine performance benchmarks and procurement criteria across North American pouch applications.
Mono-material polyethylene and polypropylene structures with tuned seal-layer rheology are rendering obsolete traditional multi-layer nylon-EVOH laminates in non-retort food categories. Mid-market snack and frozen food brands are adopting these structures at accelerated pace to meet retailer sustainability scorecard requirements. The shift is compressing demand for complex coextrusion equipment while elevating importance of single-resin supply chain security.
The EPA's anticipated per- and polyfluoroalkyl substance restrictions under TSCA Section 6 are forcing systematic replacement of fluorinated grease-resistant treatments in microwave popcorn and fast-food packaging applications. Converters must qualify plant-based wax and clay-based barrier coatings without sacrificing heat-seal performance or print adhesion. Protein and prepared meal segments face the steepest compliance curves given their reliance on oil and moisture resistance.
Direct-to-consumer subscription models for pet food, coffee, and nutritional supplements are consolidating order volumes among fewer, larger pouch converters capable of managing variable print runs and inventory-positioning logistics. Traditional distributor-dependent procurement is giving way to integrated supply partnerships where converters assume finished-goods fulfillment responsibility. This pattern concentrates most visibly in Pacific Northwest coffee roasting and Northeast specialty pet food clusters.
North America Pouch Packaging Market Segmentation
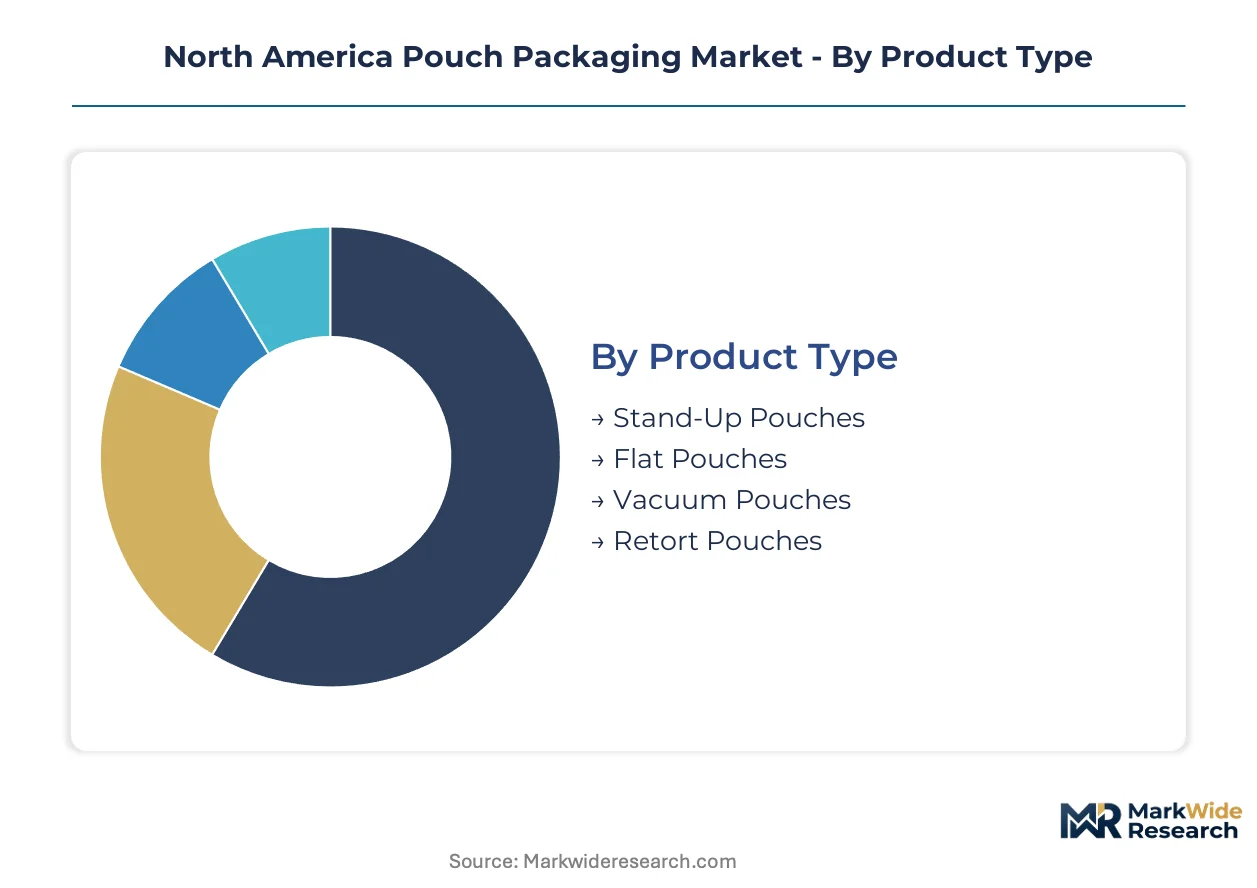
Pouch packaging segmentation in North America reflects divergent technical requirements across shelf-stable food, pharmaceutical compliance, and e-commerce fulfillment. Each dimension—product architecture, substrate composition, end-use application, and closure mechanism—carries distinct margin profiles and regulatory exposure that shape procurement strategy.
Product Type:
After-sales service intensity varies sharply across pouch formats, with retort and vacuum structures demanding specialized field support for seal-validation and shelf-life failure analysis.
- Stand-Up Pouches:Self-supporting bottom gusset construction with multi-layer barrier films enables vertical retail display and consumer convenience. Beverage and personal care brands in the US Southeast cluster around Atlanta-Charlotte converting capacity for rapid prototype iteration.
- Flat Pouches:Two-dimensional heat-sealed envelopes minimize material usage and shipping cube for high-volume commodity applications. Frozen food processors in the US Midwest specify these for cost-sensitive vegetable and protein portions where vertical shelf presence is unnecessary.
- Vacuum Pouches:Multi-layer coextruded structures with oxygen barrier layers for extended protein preservation.
- Retort Pouches:High-temperature sterilizable laminates replacing rigid trays in shelf-stable ready meals.
Stand-up pouches hold the largest share; momentum sits with retort pouches.
Material:
Cost tier stratification separates premium barrier laminates from commodity mono-materials, with California SB 54 compliance costs compressing margins on recycled-content specifications.
- Plastic:Polyethylene and polypropylene mono-materials with tuned seal-layer rheology are displacing complex nylon-EVOH laminates in snack and frozen food segments. Health Canada/PMRA harmonized standards accelerate cross-border qualification for these substrates.
- Aluminum Foil:Ultra-high barrier metalized laminates for retort and pharmaceutical applications requiring zero oxygen transmission. EPA PFAS restrictions are forcing reformulation of associated adhesive and coating chemistries before enforcement deadlines.
- Paper:Fiber-based barrier composites with thin-film deposition for shelf-stable dry goods.
- Composites:Multi-substrate laminates combining plastic, foil, and paper layers for engineered performance.
Plastic dominates volume; aluminum foil commands premium positioning.
End User:
Application-specific performance requirements separate pharmaceutical validation cycles from food-grade speed-to-market, with industrial procurement emphasizing durability over barrier sophistication.
- Food & Beverage:Largest addressable demand spanning ambient, chilled, frozen, and retort distribution chains. Single-serve format adoption by CPG brands in the US Southeast is accelerating pouch conversion from rigid alternatives.
- Pharmaceuticals:Child-resistant and senior-friendly compliance packaging with tamper-evident features. FDA 21 CFR food-contact substance regulations govern barrier material selection for oral dosage and medical device applications.
- Personal Care:Spout-equipped stand-up formats for lotions, shampoos, and cosmetic concentrates.
- Industrial Products:Heavy-duty laminated structures for chemicals, lubricants, and agricultural inputs.
Food & Beverage anchors volume; Pharmaceuticals generates the steepest expansion trajectory.
Closure Type:
Customer-type segmentation separates retail-ready convenience features from industrial bulk handling, with resealability commanding material cost premiums.
- Heat Seal:Permanent fusion bonding for single-use commodity applications with lowest unit cost. High-speed form-fill-seal operations across the US Southeast rely on these for breakfast cereal, snack, and frozen vegetable volumes.
- Spout:Integrated dispensing fitments for controlled pouring and repeated access. Beverage and personal care brands specify these for premium positioning, with California's extended producer responsibility frameworks adding compliance cost layers.
- Zip Lock:Press-to-close interlocking profiles for resealable food and household applications.
- Screw Cap:Rigid threaded closures for liquid products requiring precise dosing control.
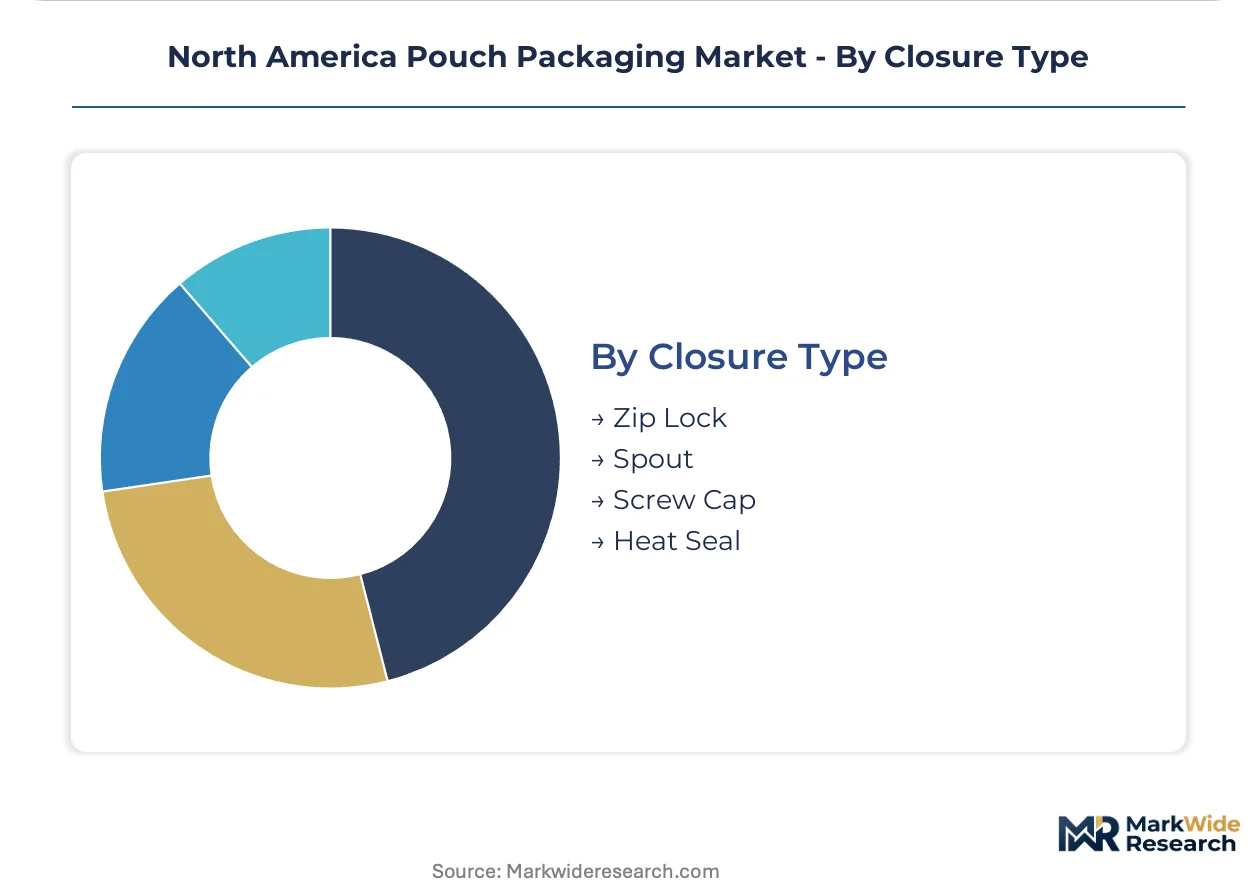
Heat Seal captures the highest unit volume; spout closures are gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations under 21 CFR anchor material compliance across the dominant United States geography, while Health Canada/PMRA standards and Mexico's evolving packaging norms create a harmonized yet distinct regulatory landscape for cross-border substrate qualification.
United States
Single-serve format adoption by CPG brands accelerates pouch conversion from rigid alternatives in ready-to-eat meals and beverages. California's SB 54 mandates recycled content minimums that reshape material procurement across national supply chains. The Atlanta-Charlotte corridor concentrates film extrusion, printing, and pouch converting capacity, enabling rapid prototype-to-production cycles for regional food and beverage launches.
Canada
Health Canada/PMRA food-contact standards streamline cross-border substrate qualification with the United States, reducing redundant testing cycles for integrated North American production networks. Harmonized safety protocols govern barrier material selection for protein preservation and pharmaceutical applications. Ontario and Quebec host converting operations serving both domestic distribution and US Midwest supply chains.
Mexico
Food processing investment from Guadalajara to Querétaro generates underdeveloped flexible packaging converting capacity relative to demand growth. The country's national packaging regulator oversees evolving food-contact safety frameworks as export-oriented manufacturers qualify substrates for US market access. This corridor creates white space for substrate suppliers establishing regional supply nodes serving US Southwest and Central American markets.
Southeast United States
Poultry and seafood processing expansion in Alabama and Mississippi generates localized demand for vacuum and modified-atmosphere pouch formats. Protein processors specify high-barrier structures for extended shelf-life distribution. Geographic co-location strategies enable dedicated converting lines positioned adjacent to processing facilities.
US Midwest
Amcor PLC leverages integrated film extrusion and converting assets to sustain cost leadership in high-volume food applications. Frozen food processors specify flat pouches for cost-sensitive vegetable and protein portions. Breakfast cereal, snack, and frozen vegetable volumes flow through high-speed form-fill-seal operations optimized for heat-seal configurations.
North America Pouch Packaging Market Competitive Landscape
Integrated multinationals and specialized converters split the market into distinct capability tiers. The vendor base concentrates around film extrusion assets, barrier innovation platforms, and sustainable material portfolios. Three archetypes dominate: vertically integrated substrate-to-converter operators, specialty barrier and retort specialists, and fiber-based composite innovators. Competitive dynamics center on M&A-driven geographic expansion and strategic partnerships for recycled-content supply security.
Within the integrated multinational tier, Amcor PLC and Sealed Air Corporation exemplify scale-driven positions anchored by captive film production and barrier technology platforms. ProAmpac Intermediate Inc. occupies a specialist position differentiated by retort and sustainable material capabilities. These three entities represent the structural segmentation between commodity volume leadership and premium application focus.
| Leading Market Players |
|---|
| Amcor PLC |
| ProAmpac Intermediate Inc. |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| SIG Group AG |
| Sealed Air Corporation |
| Smurfit Kappa Group PLC |
| Coveris |
| Goglio Group |
| Others |
Pricing and Supply Chain Analysis
California SB 54 recycled content mandates expose converters to simultaneous compliance cost inflation and feedstock scarcity, forcing pricing stratification across premium certified-sustainable, standard compliant, and economy non-compliant tiers while reshaping procurement geography toward Mexico and the US Southeast.
Pricing Analysis
Price spreads between Atlanta-Charlotte corridor converters and Midwest integrated operators compress under resin allocation pressure. Three-tier pricing structure across premium certified-sustainable, standard SB 54-compliant, and economy virgin-material tiers reflects compliance cost layering. Pricing pressure stems from mechanical recycling yield degradation forcing over-engineering or scrap rate acceptance. Commodity heat-seal pouch buyers exhibit highest price sensitivity; retort and spout-equipped premium formats retain pricing power.
Supply Chain Analysis
Upstream petrochemical feedstock concentration in the US Gulf Coast and Alberta tar sands regions anchors resin supply security for polyethylene and polypropylene mono-materials. Specialty barrier polymers for retort applications draw from limited German and Japanese chemical suppliers. Single-source vulnerability in adhesive chemistries for aluminum foil laminates intensifies under EPA PFAS restriction timelines. Distribution runs through converter-direct partnerships with CPG brand headquarters clusters, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America pouch packaging market sits at a platform-economics inflection where direct-to-consumer subscription fulfillment and integrated converter-brand data interoperability are displacing arm's-length procurement. Ecosystem consolidation around Guadalajara-Querétaro supply nodes and Pacific Northwest coffee roasting clusters exemplifies this shift.
For Market Incumbents: Entrench barrier innovation leadership through captive film extrusion expansion in the US Southeast, defending against specialty retort specialists eroding premium positioning. Accelerate PFAS-alternative qualification pipelines before EPA enforcement compresses reformulation windows. Secure post-consumer recycled content supply through backward integration into mechanical recycling or tolling partnerships with emerging Mexican converters.
For New Entrants and Emerging Players: Build out toll converting capacity in the Guadalajara-Querétaro corridor to capture food processing investment outpacing regional flexible packaging supply. Target vacuum and modified-atmosphere pouch formats for Alabama-Mississippi protein processing expansion where geographic co-location enables dedicated line economics. Pursue direct-to-consumer fulfillment partnerships with Pacific Northwest coffee and Northeast specialty pet food brands as entry wedge.
For Investors and Strategic Acquirers: Fiber-based barrier composite specialists with thin-film deposition capabilities represent the priority acquisition archetype for pulp and paper majors repositioning into food-contact markets. Long-term viability hinges on qualification velocity for microwaveable and shelf-stable applications previously reserved for full plastic laminates. Watch California SB 54 enforcement granularity and EPA PFAS alternative approval timelines as inflection signals for material portfolio repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Capacity Expansion | Captures microwaveable ready-meal displacement of rigid aluminum trays in protein distribution. |
| Backward Integration into Film Extrusion | Secures resin supply continuity and cost position for high-volume food applications. |
| PFAS-Alternative Barrier Qualification | Preempts EPA enforcement deadlines for grease-resistant coatings in popcorn and fast-food packaging. |
| Post-Consumer Recycled Content Partnership | Addresses California SB 54 compliance while managing yield degradation in mechanical recycling streams. |
| Geographic Co-Location with Protein Processors | Reduces logistics cost and accelerates prototype-to-production cycles for vacuum pouch formats. |
Research Methodology
Operator-level perspectives from film extrusion plant managers, CPG brand packaging directors, retail category buyers, and toll converting operators anchored the qualitative base for this analysis. Secondary validation drew from FDA 21 CFR food-contact substance filings, EPA emerging contaminant regulatory dockets, California SB 54 implementation guidance, and trade flow data from USITC and Statistics Canada. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers across the projection horizon.
Scenario-bracketing around resin price volatility, recycled content yield degradation, and PFAS enforcement timing bounded the forecast envelope. Segmentation dimensions modeled include pouch architecture, substrate composition, closure mechanism, and end-use application intensity. CAGRs derived from regression analysis against historical converting capacity utilization and food processing investment patterns. Cross-border regulatory harmonization between FDA and Health Canada/PMRA standards informed Canada-US demand elasticity assumptions.
Stress conditions across polyethylene resin supply disruptions, mechanical recycling yield variance, and California EPR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding brand owner format conversion velocity and retailer sustainability scorecard weighting. Cross-checking against Amcor PLC and Sealed Air Corporation public disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Kraft Paper Pouch Market
Pouch
India Pouch Packaging Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Utility Pouches Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Digital Printed Pouch Market
Pouch
Stand Up Paper Pouches Market
Pouch
Child Resistant Pouches Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Retort Pouch Packaging Market
Pouch
Portion Control Packs Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market