
 Kraft Pouch Market | 2026-2036
Kraft Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Pouch Market Foresight
A widening capital-intensity gap between integrated paperboard producers and standalone converters is redrawing competitive boundaries in the kraft pouch landscape. Amcor Limited leverages its global film extrusion and paper lamination infrastructure to sustain cost advantages across multi-layer formats. Mondi Group anchors its position through captive pulp supply and integrated kraft paper mills in Europe. Smurfit Kappa competes by extending its corrugated expertise into value-added flexible packaging segments.
Kraft pouches are multi-layer flexible containers constructed from unbleached sulfate pulp paper laminated with polyethylene or biopolymer barrier films, typically ranging from 60 to 150 microns in total caliper, designed to package dry goods, liquids, and semi-perishables with moisture and oxygen protection. Stand-up pouches with bottom gussets occupy the dominant share of value owing to premium shelf presence and brand differentiation in coffee and pet food categories. Zipper closure formats represent the fastest-expanding segment as resealability becomes a non-negotiable feature for household products and personal care applications. Flat pouches remain a mature, cost-driven category where margin pools have compressed amid commoditization in bulk grain and ingredient packaging.
The EU F-Gas Regulation and REACH compliance requirements are elevating barrier film specifications and restricting certain fluorinated chemistries in kraft pouch laminates. FDA food contact substance notifications govern polyethylene and adhesive layers for U.S.-destined products, while BIS certification for paper-based food packaging materials shapes import eligibility into India. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mono-material recyclable structures or maintain multi-barrier performance at higher compliance cost.
Market Dynamics
Stand-up pouch formats with resealable closures are displacing rigid containers across European coffee and snack aisles, forcing converters to retool lamination lines for multi-layer kraft structures.
Growth Catalysts
- EU PPWR Recyclability Mandates:The Packaging and Packaging Waste Regulation is accelerating brand migration from plastic-only formats toward fiber-based alternatives with certified recyclable barriers.
- Zipper Technology Maturation:Child-safe reseal mechanisms are expanding kraft pouch penetration into household chemicals and personal care segments previously locked into rigid bottles.
- German Private-Label Standardization:Discounter consolidation around kraft-based flexible formats is creating template specifications that cascade across Central European supply chains.
Market Restraints
- PE Film Price Volatility:Polyethylene barrier layers constitute 35-45% of material cost; ethylene feedstock swings compress converter margins unpredictably.
- Captive Pulp Supply Concentration:Nordic integrated paperboard producers control premium unbleached kraft furnish, limiting independent converter access to consistent caliper specifications.
- Fluorinated Chemistry Restrictions:REACH Annex XVII and EU F-Gas Regulation are eliminating high-barrier PFAS treatments without commercially viable mono-material replacements at scale.
Strategic Opportunities
- Indian BIS Certification Pathway:Paper-based food packaging standards are tightening import eligibility, creating first-mover advantage for converters achieving IS 15495 compliance ahead of enforcement.
- Biopolymer Barrier Convergence:PLA and PHA film lamination with kraft substrates opens compostable certification routes for organic food brands seeking end-of-life differentiation.
- D2C Subscription Channel Expansion:Coffee roasters and specialty pet food brands are bypassing retail slotting fees through direct shipment in customized kraft pouches with QR-traceable batch codes.
Industry Challenges
- Multi-Layer Delamination Expertise Gap:Skilled technicians capable of calibrating adhesive coat weights for kraft-PE bonding remain scarce in Eastern European converter bases.
- Extended Producer Responsibility Registration:National packaging registries in France, Italy, and Spain impose divergent fee structures and reporting cadences that fragment compliance workflows.
- Legacy Flexo-to-Digital Press Transition:Short-run customization demand outpaces converter capex cycles, stranding mid-tier players with obsolete plate-based workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Pouch Market |
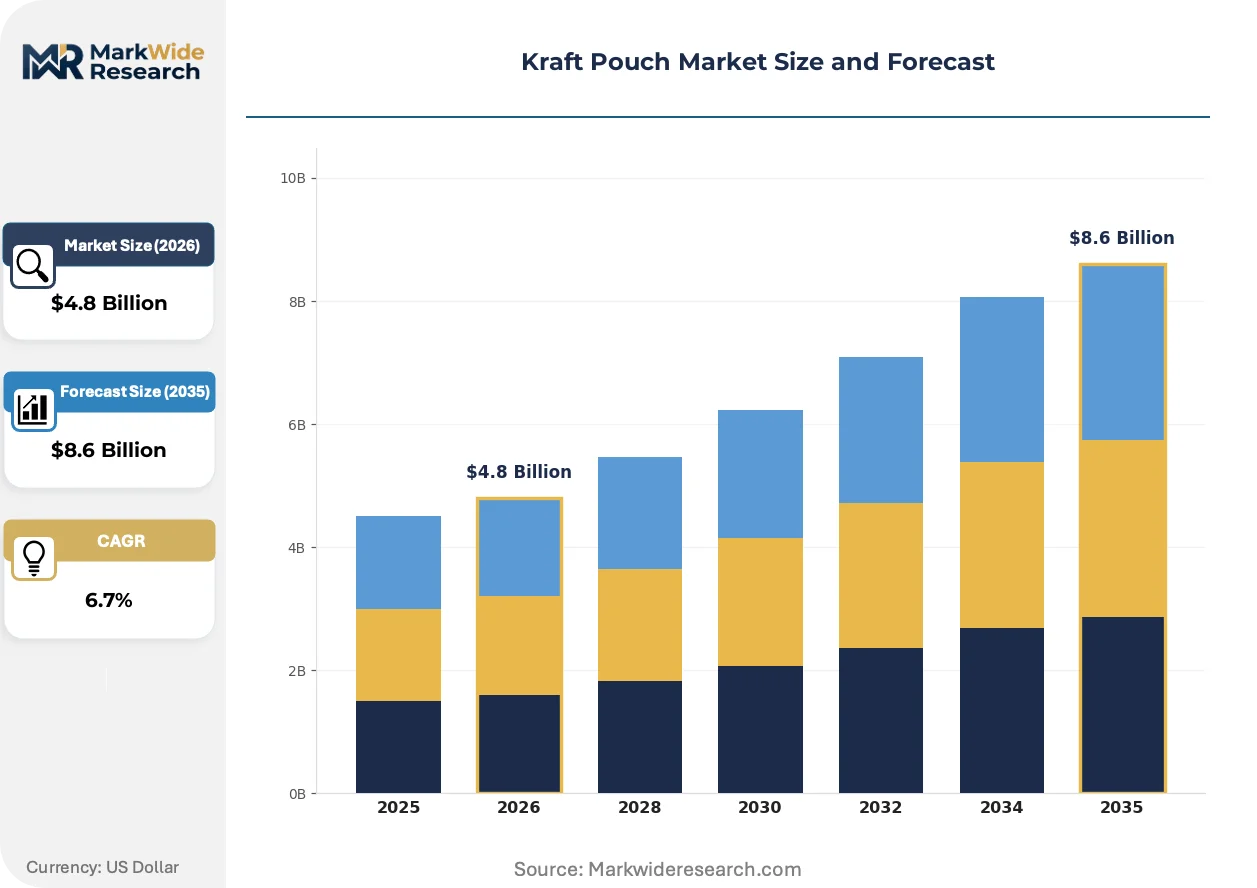
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Gusseted Pouches End Use Industry: Food & Beverages, Personal Care, Healthcare, Household Products Size: Small, Medium, Large, Extra Large Closure Type: Heat Seal, Screw Cap, Zipper, Tear Notch |
| Companies Covered | Amcor Limited, Mondi Group, WestRock Company, Smurfit Kappa Group, Sealed Air Corporation, ProAmpac, Sonoco Products Company, Glenroy, Inc., ULINE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Pouch Market Shifts & Advancements
Barrier film chemistry and closure mechanism engineering are diverging along sustainability-performance axes, splitting the market into compostable-certified and high-barrier recyclable lanes.
Water-based adhesive lamination is bifurcating converter investment strategies. Solvent-free bonding systems eliminate VOC emissions and enable food-contact compliance without extended cure times. Specialty coffee roasters in Scandinavia and the Pacific Northwest are specifying these structures for single-origin lines. The technology is compressing margin pools among solvent-based converters while rewarding early adopters with premium brand partnerships.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing barrier film reformulation across EU-serving supply chains. Fluorine-free grease-resistant treatments using clay coatings and bio-waxes are achieving comparable oil holdout for dry food applications. German snack producers are qualifying these structures ahead of 2025 enforcement deadlines, pushing specification changes through their converter networks.
Brand procurement teams are consolidating supplier panels around vertically integrated partners capable of delivering FSC-certified kraft, barrier lamination, and pre-press design in single-source contracts. This consolidation displaces fragmented converter-distributor relationships that dominated the 2015-2020 period. The shift is most visible in Benelux and Nordics, where private-label concentration accelerates template standardization.
Kraft Pouch Market Segmentation
Kraft pouch specifications diverge sharply by distribution channel, with retail shelf requirements driving premium formats while e-commerce fulfillment favors lightweight, damage-resistant structures. Brand procurement teams segment supplier qualifications around barrier performance tiers and regional certification portfolios rather than commodity pricing alone.
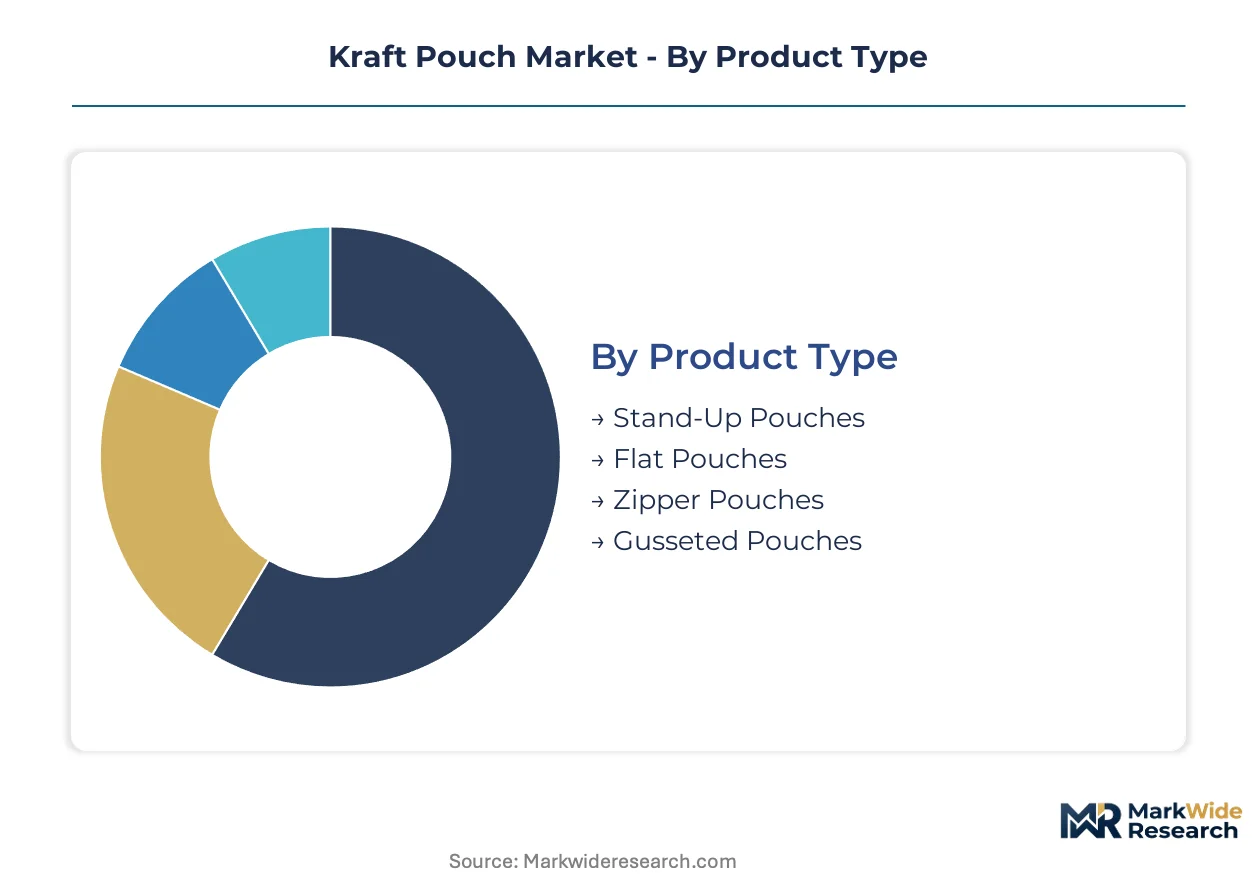
Product Type:
Retail coffee and pet food aisles favor stand-up formats for shelf presence, while flat pouches dominate bulk ingredient and subscription channels where shipping cube efficiency matters most.
- Stand-Up Pouches:Bottom-gusseted structures with multi-layer kraft-PE lamination provide vertical stability for retail display. German discounters and Nordic specialty coffee roasters specify these formats for private-label lines requiring premium differentiation against rigid containers. REACH-compliant barrier films and FSC-certified kraft furnish are becoming baseline requirements.
- Zipper Pouches:Child-safe reseal mechanisms expand addressable market into household chemicals and personal care previously locked in rigid bottles. Scandinavian organic food brands specify compostable-certified zipper structures for direct-to-consumer subscription channels, driving fastest specification change velocity across converter networks.
- Flat Pouches:Three-side-seal formats minimize material usage for bulk grain and ingredient packaging where cost compression dominates procurement criteria.
- Gusseted Pouches:Side-gusset variants accommodate higher fill volumes for industrial foodservice and institutional supply chains.
By volume, flat pouches lead. By growth pace, zipper formats are expanding most quickly.
End Use Industry:
Cost tier stratification separates commodity food packaging from premium personal care applications, with barrier specification and print quality driving 3-4x material cost differentials.
- Food & Beverages:Coffee, snacks, and dry goods represent the revenue anchor. EU PPWR recyclability mandates are accelerating migration from plastic-only formats toward fiber-based alternatives with certified recyclable barriers. German private-label standardization creates template specifications cascading through Central European supply chains.
- Personal Care:Organic and natural brands specify kraft substrates for sustainability signaling. Water-based adhesive lamination and fluorine-free grease-resistant treatments using clay coatings achieve compliance ahead of enforcement deadlines.
- Healthcare:Medical device and pharmaceutical applications require sterile barrier validation and FDA food contact substance notifications for U.S. market access.
- Household Products:Concentrated detergents and cleaning chemicals leverage kraft's puncture resistance for refill and concentrate formats.
Food and beverage commands absolute volume, while personal care posts the steepest expansion trajectory as sustainability premiums justify material cost.
Size:
Volume concentration in retail-ready formats is reshaping converter equipment footprints toward mid-range capacity lines.
- Small:Single-serve coffee and sample formats dominate D2C subscription channels with QR-traceable batch codes.
- Medium:Retail standard for coffee and snacks, specified by German discounters across private-label portfolios.
- Large:Pet food and institutional foodservice formats requiring enhanced puncture resistance.
- Extra Large:Bulk ingredient and industrial supply applications with minimal print complexity.
Medium sizes anchor production schedules, though small formats gain share fastest through e-commerce penetration.
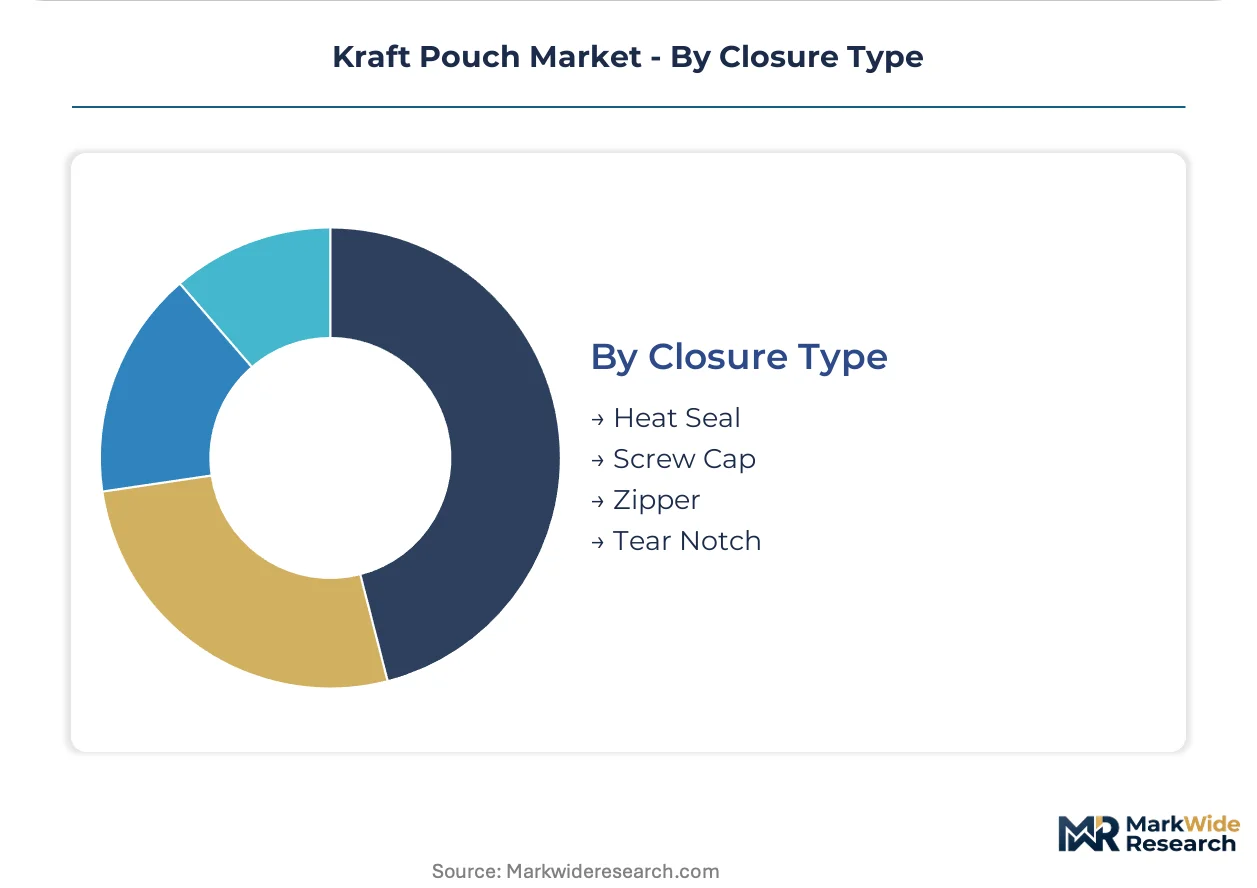
Closure Type:
Supply concentration in zipper mechanism production is limiting independent converter access to child-safe certified components.
- Heat Seal:Cost-minimal option for single-use applications with no reseal requirement.
- Zipper:Fastest-growing specification as resealability becomes non-negotiable for household products and personal care. Child-safe mechanisms expand addressable market beyond food into chemicals.
- Tear Notch:Convenience feature for consumer opening ease without reseal functionality.
- Screw Cap:Premium dispensing format for liquids and semi-fluids in personal care applications.
Heat seal closures dominate existing installed base, while zipper mechanisms are climbing the fastest as brand specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys kraft pouches primarily for private-label coffee standardization, while India channels demand toward BIS-certified food imports and the United States emphasizes D2C subscription formats with customized batch coding.
Germany
Discounter consolidation around kraft-based flexible formats creates template specifications cascading through Central European supply chains. The EU Packaging and Packaging Waste Regulation accelerates brand migration from plastic-only formats toward fiber-based alternatives with certified recyclable barriers. The Rhine-Ruhr industrial corridor hosts converter networks retooling lamination lines for multi-layer kraft structures.
United States
FDA food contact substance notifications govern polyethylene and adhesive layers for U.S.-destined products, shaping import eligibility criteria. Specialty coffee roasters and pet food brands bypass retail slotting fees through direct shipment in customized kraft pouches. The Pacific Northwest cluster anchors demand for water-based adhesive lamination in single-origin coffee lines.
India
BIS certification for paper-based food packaging materials tightens import eligibility, creating first-mover advantage for converters achieving IS 15495 compliance. The country's national food safety regulator shapes market access through evolving packaging standards. Maharashtra and Gujarat industrial belts concentrate converter investment targeting domestic F&B brand procurement.
France
National packaging registries impose divergent fee structures and reporting cadences that fragment compliance workflows across extended producer responsibility frameworks. ECHA REACH Annex XVII restrictions on fluorinated chemistries eliminate high-barrier PFAS treatments without commercially viable mono-material replacements. The Paris Basin hosts brand procurement teams consolidating supplier panels around vertically integrated partners.
Sweden
Scandinavian organic food brands specify compostable-certified zipper structures for direct-to-consumer subscription channels. The EU F-Gas Regulation elevates barrier film specifications and restricts certain fluorinated chemistries in kraft pouch laminates. Stockholm and Gothenburg industrial zones drive fastest specification change velocity across Nordic converter networks.
Kraft Pouch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into pulp supply and captive film extrusion infrastructure determining cost position. The upper tier commands premium specifications through in-house production of FSC-certified kraft furnish and multi-layer lamination. Three archetypes dominate: Nordic integrated paperboard producers with captive pulp mills, global flexible packaging conglomerates with film extrusion networks, and regional converters specializing in short-run digital customization. Competitive moves center on M&A to secure barrier film technology and capacity expansion in Central European converter bases.
Within the integrated paperboard tier, Mondi Group anchors positioning through European kraft paper mill ownership and captive pulp supply. Amcor Limited exemplifies the global flexible packaging archetype with film extrusion and paper lamination infrastructure spanning multiple geographies. Smurfit Kappa occupies a position extending corrugated expertise into value-added flexible packaging segments. These three represent the structural fault lines between pulp-integrated, film-integrated, and corrugated-originated competitive vectors.
| Leading Market Players |
|---|
| Amcor Limited |
| Mondi Group |
| WestRock Company |
| Smurfit Kappa Group |
| Sealed Air Corporation |
| ProAmpac |
| Sonoco Products Company |
| Glenroy, Inc. |
| ULINE |
| Others |
Supply & Pricing Matrix
Mill-scale efficiencies at Nordic integrated paperboard producers compress unit costs for premium unbleached kraft furnish, concentrating pricing power among pulp-captive operators while independent converters absorb polyethylene barrier layer volatility. German private-label standardization cascades template specifications through Central European supply chains, locking price floors to FSC-certified kraft and REACH-compliant film laminates.
Pricing Analysis
After-sales specification engineering and extended compliance consulting drive lifetime value for converter-brand relationships. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified specialty coffee formats from commodity bulk grain pouches and private-label discounter lines. Price differentiation hinges on barrier performance tier and zipper mechanism certification. Pricing pressure stems from PE film feedstock swings compressing converter margins unpredictably. Bulk ingredient procurement teams exhibit highest price sensitivity, while Scandinavian organic brands tolerate premium positioning for compostable-certified structures.
Supply Chain Analysis
Inventory cycles for unbleached kraft paper extend 8-12 weeks from Nordic mill to Central European converter, creating working capital intensity that favors integrated operators. Supply concentrates in Sweden, Finland, and Germany for premium kraft furnish, with PE barrier films sourcing from Netherlands and Belgium extrusion hubs. Raw material dependencies rest on unbleached sulfate pulp, polyethylene resin, and water-based adhesive chemistries. Single-source vulnerability in child-safe zipper mechanisms limits independent converter access to certified components. Distribution runs through brand procurement panels consolidating around vertically integrated partners capable of single-source FSC kraft, barrier lamination, and pre-press design contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kraft pouch market tracks a cyclical recovery aligned with EU PPWR enforcement waves accelerating brand migration from plastic-only formats. Each regulatory tightening cycle resets specification baselines and rewards early compliance investment.
For Market Incumbents: Consolidate barrier film technology through selective acquisition of fluorine-free coating specialists ahead of REACH Annex XVII enforcement deadlines. Deepen captive pulp supply relationships with Nordic mill operators to secure consistent caliper specifications as independent converter access tightens. Extend water-based adhesive lamination capacity in Rhine-Ruhr and Benelux industrial corridors to capture premium brand partnerships from solvent-based competitors.
For New Entrants and Emerging Players: Differentiate on compostable-certified zipper structures for Scandinavian D2C subscription channels where specification change velocity outpaces incumbent capex cycles. Target Indian BIS certification pathways ahead of IS 15495 enforcement to establish first-mover positioning in Maharashtra and Gujarat industrial belts. Pursue white-label digital customization partnerships with Pacific Northwest specialty coffee roasters bypassing retail slotting fees.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated FSC kraft furnish and water-based lamination infrastructure over fragmented solvent-dependent operators. Five-to-ten year viability hinges on mono-material recyclable structure commercialization at scale. Acquisition target archetype: mid-cap Central European converters with dormant digital press capacity and established brand panel relationships. The signal to watch is German discounter template specification releases cascading private-label standardization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Lamination Scale-Up | Eliminates VOC emissions and unlocks Scandinavian specialty coffee brand partnerships requiring food-contact compliance. |
| Fluorine-Free Barrier Film Qualification | German snack producers are qualifying clay-coated grease-resistant treatments ahead of ECHA REACH enforcement deadlines. |
| FSC-Certified Kraft Mill Integration | Captive pulp supply secures consistent caliper specifications as Nordic furnish access tightens for independent converters. |
| Child-Safe Zipper Mechanism Certification | Expands addressable market into household chemicals and personal care segments previously locked in rigid bottles. |
| Digital Press Workflow Transition | Short-run customization demand from D2C coffee roasters outpaces legacy flexo converter capex cycles. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations managers, brand procurement leads, barrier film R&D directors, and Nordic pulp mill supply planners and refined through secondary validation. Primary fieldwork combined structured interviews across 15 stakeholder touchpoints with trade data analysis from EUROPEN, FEFCO, and Flexible Packaging Europe industry filings. Secondary sources encompassed ECHA REACH substance restriction databases, FDA food contact substance notification registers, and BIS IS 15495 certification records. Bottom-up volume modeling triangulated against top-down macro demand projections across the analysis window.
Variance decomposition across product type, closure mechanism, barrier performance tier, and regional regulatory cluster shaped the analytical framework. Modeled segmentation captured stand-up, zipper, flat, and gusseted pouch formats crossed with food and beverage, personal care, healthcare, and household end-use applications. CAGRs derived from logistic adoption curves fitted to historical specification change velocity in German private-label coffee and Scandinavian organic food channels. Industry-specific forecast inputs included EU PPWR implementation timelines and BIS certification enforcement readiness across Indian state industrial belts.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated biopolymer barrier commercialization would require recalibration. Forecasts reflect documented assumptions on specification migration rates and converter capacity expansion cadences. PE feedstock volatility, fluorinated chemistry substitution delays, and national EPR fee fragmentation present specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Japan Pouch Packaging Market
Pouch
Argentina Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
France Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Monodose Packs Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Open Mouth Sacks Market
Pouch
Europe Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Peelable Pouches Market
Pouch
Paper Pouch Market
Pouch
Dual-Chamber Pouches Market