
 Vented Stretch Wrap Market | 2026-2036
Vented Stretch Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Vented Stretch Wrap Market Analytics
Industrial distribution channels for pallet containment films is reconfiguring as direct mill-to-warehouse contracts replace layered distributor networks. Paragon Films, Inc. leverages blown film extrusion capacity in the Midwest to sustain same-day fulfillment for regional dairy cooperatives. Sigma Plastics Group anchors its position through captive resin sourcing and toll manufacturing partnerships across the Southeast. Integrated Packaging Group competes on custom perforation patterns that match specific respiration rates for ethylene-sensitive commodities.
Vented stretch wrap denotes a perforated polyethylene film engineered with precisely spaced apertures, typically between 0.5 and 2 millimeters in diameter, that permit air circulation while maintaining unitizing tension around palletized loads. The perforation pattern prevents condensation buildup on temperature-variable shipments, preserving package integrity for fresh agricultural products and hygroscopic industrial components. Machine stretch wrap dominates volume throughput in automated beverage bottling facilities where throughput exceeds 100 pallets hourly. Recycled plastics represent the fastest-expanding material category as post-industrial scrap streams achieve food-contact certification through advanced melt filtration. Hand stretch wrap occupies stable demand in small-format produce packing sheds where capital constraints preclude turntable automation.
EPA guidelines on volatile organic compound emissions from solvent-based adhesives influence converter equipment investments and coating technology selections. FDA food-contact substance notifications govern perforation additives and slip agents in films touching unpackaged produce. OSHA ergonomic standards for manual pallet wrapping shape hand-roll specifications and dispenser design. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that will redefine cost allocation between resin suppliers, converters, and end-user recyclers.
Market Dynamics
REACH compliance deadlines and EU Green Deal mandates are forcing converters to requalify resin formulations, compressing certification timelines while food logistics teams simultaneously demand perforation precision for ethylene-sensitive produce loads.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled-content requirements for pallet containment films are accelerating converter investments in post-industrial scrap processing lines across Germany and the Netherlands.
- Fresh produce cold chain expansion:Temperature-variable shipments of berries and leafy greens now specify vented films to prevent condensation-related spoilage in automated distribution centers.
- Perforation automation:Laser and mechanical punching systems are achieving aperture tolerances below 0.1 millimeters, enabling respiration-rate matching for climacteric fruits.
Market Restraints
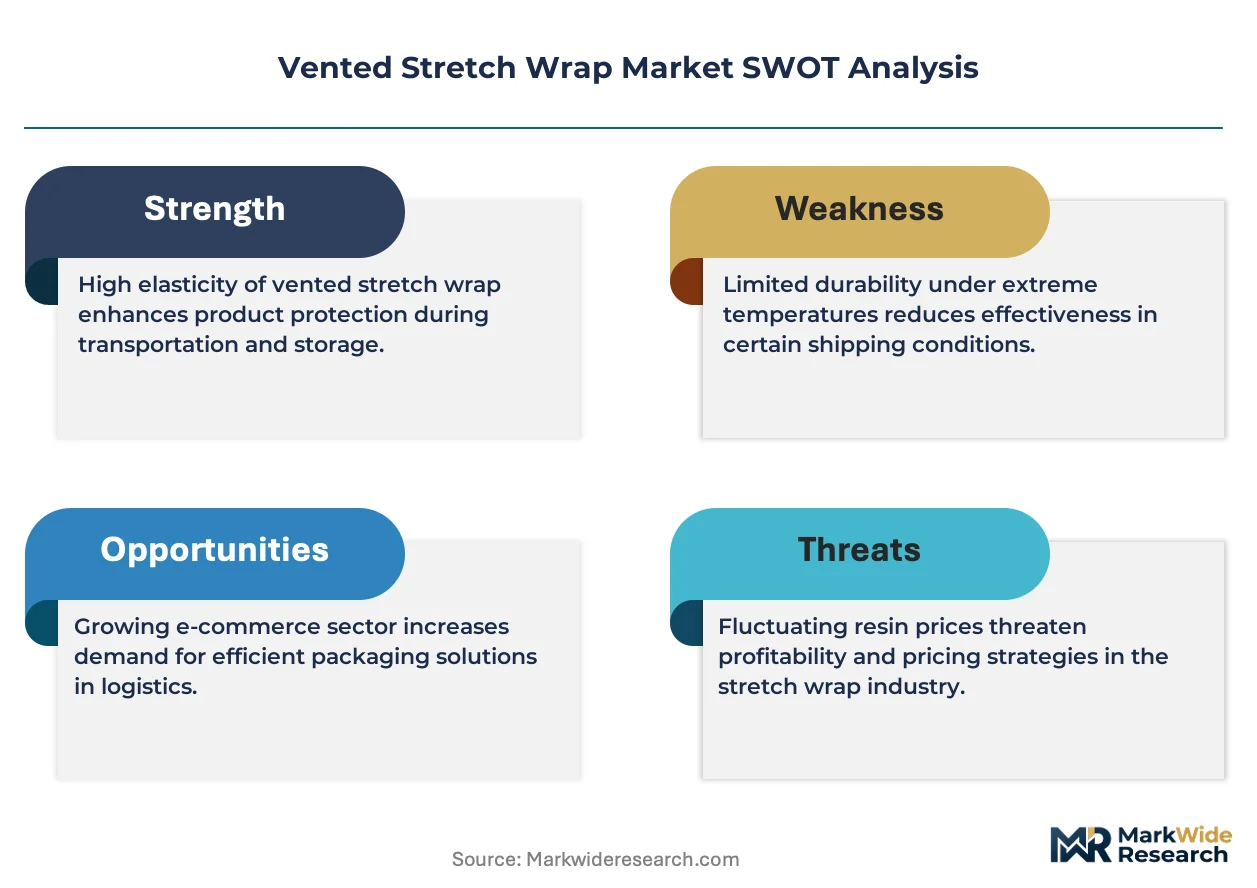
- Resin price volatility:Linear low-density polyethylene feedstock costs fluctuate with naphtha and ethane indices, squeezing converter margins on fixed-price annual contracts.
- Food-contact certification bottlenecks:FDA substance notifications and EFSA safety assessments for recycled-content perforation additives extend qualification cycles to 18-24 months.
- Substitution by rigid containers:Reusable plastic crates and corrugated alternatives capture palletized fresh produce volumes where breathability is less critical.
Strategic Opportunities
- India cold chain infrastructure:FSSAI-mandated food safety modernization is creating specification demand for vented containment films in dairy and horticulture logistics.
- Pharmaceutical hygroscopic packaging:Moisture-sensitive active ingredients and excipients require breathable yet secure pallet unitization for temperature-controlled distribution.
- Extended producer responsibility frameworks:State-level EPR legislation in California and New York is reallocating recycling cost accountability toward brand owners and converters.
Industry Challenges
- Melt filtration expertise scarcity:Post-industrial scrap purification to food-contact standards requires polymer scientists and process engineers in short supply across the Midwest and Southeast.
- Perforation pattern IP fragmentation:Proprietary aperture geometries for specific respiration rates are locked behind overlapping patent portfolios, complicating new product development.
- Legacy equipment retrofit costs:Cast film lines require substantial capital expenditure to convert to blown film extrusion capable of precise vented film production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vented Stretch Wrap Market |
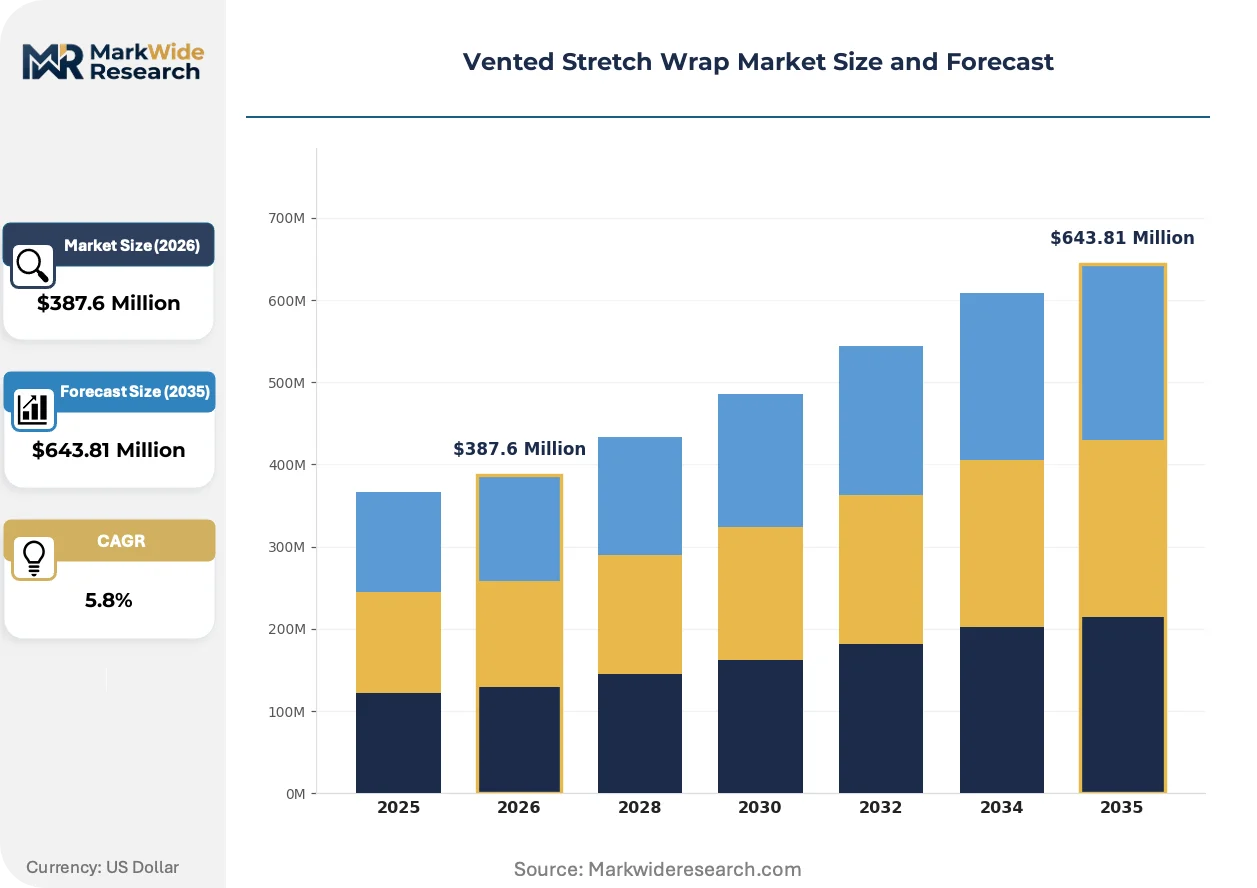
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Stretch Wrap, Machine Stretch Wrap, Pre-Stretched Wrap, Custom Stretch Wrap Material: Polyethylene, PVC, Polypropylene, Recycled Plastics Application: Packaged Food, Pharmaceuticals, Retail Packaging, Industrial Goods End User: Food & Beverage, Healthcare, Consumer Goods, E-Commerce |
| Companies Covered | Integrated Packaging Group, Inteplast Group, AEP Industries Inc., Darnel, Inc., Intertape Polymer Group, Paragon Films, Inc., Sigma Plastics Group, Excel Pac LLC, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vented Stretch Wrap Market Evolving Landscape
Digital perforation control systems and regulatory pressure on material circularity are converging to redefine converter competitive advantage across fresh produce and industrial logistics segments.
Smart perforation technology is digitizing quality assurance in vented film manufacturing. Machine vision systems inspect every square meter for aperture consistency and edge integrity at line speeds exceeding 300 meters per minute. Fresh produce packers in California's Central Valley and Florida's citrus belt are specifying these certified rolls for automated wrapping equipment. The technology is digitizing converter customer relationships by replacing sample-based acceptance with continuous digital compliance documentation.
REACH authorization requirements for slip agents and anti-fog additives are restructuring European formulation portfolios. ECHA substance evaluations have flagged several legacy perforation lubricants for reproductive toxicity concerns, forcing converters to validate replacements. German automotive chemical exporters are absorbing 8-12 month requalification delays as their stretch wrap suppliers navigate alternative additive registrations.
Direct mill-to-warehouse contracting is displacing layered distributor networks in North American pallet containment procurement. Large dairy cooperatives and beverage bottlers now negotiate annual volume agreements with blown film extruders, bypassing regional packaging distributors. This concentration is most visible in Wisconsin and Michigan, where capital-constrained produce packing sheds still rely on hand-wrap distributors while automated facilities consolidate supplier relationships.
Vented Stretch Wrap Market Segmentation
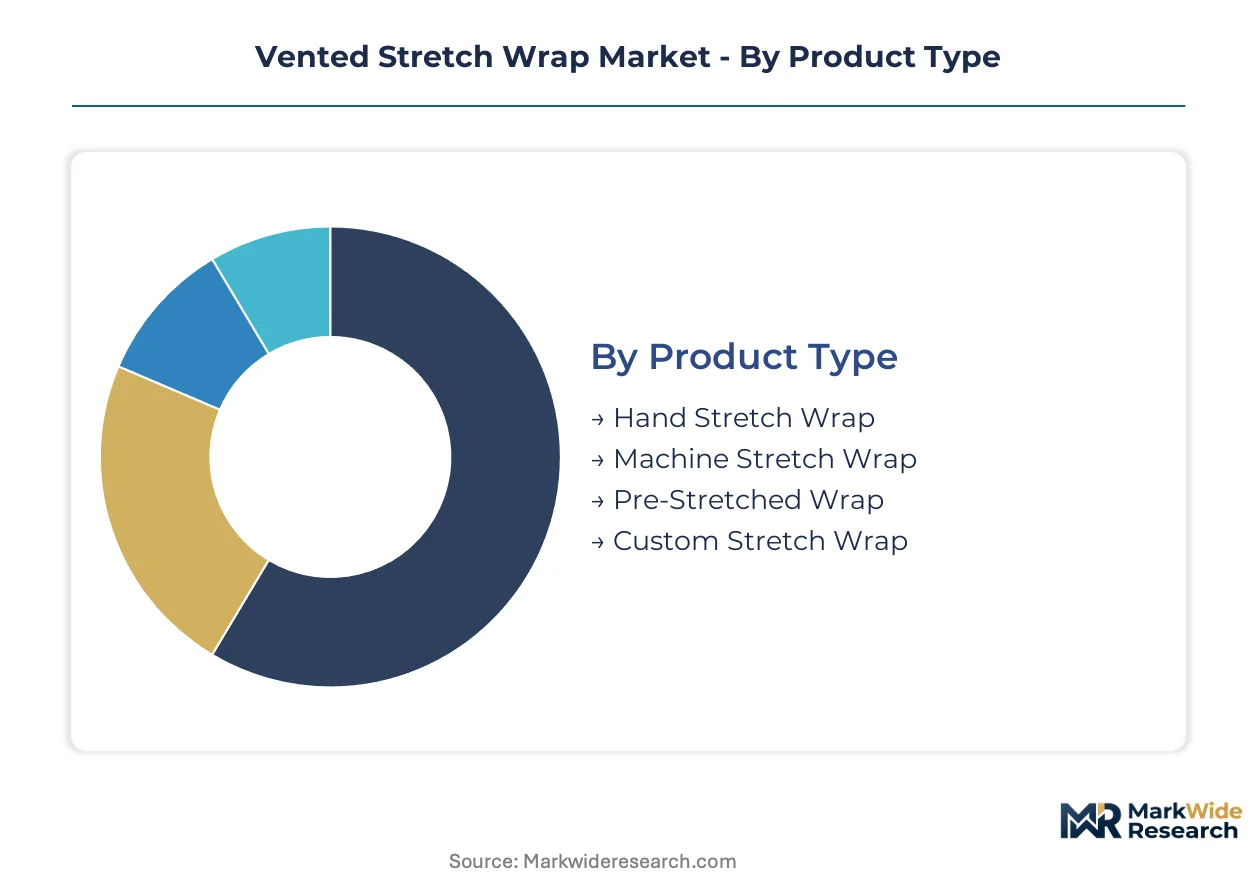
Segmentation in vented stretch wrap reflects divergent equipment investments, resin qualification burdens, and regulatory exposure across customer types. Converters must align perforation precision, automation compatibility, and food-contact certification to specific buyer workflows rather than pursuing undifferentiated volume.
Product Type:
After-sales-service intensity varies sharply across equipment categories, with machine wrap installations demanding field calibration support while hand wrap operates on minimal technical intervention.
- Machine Stretch Wrap:Blown film extrusion yields consistent gauge control for automated turntable and rotary arm systems operating above 50 pallets hourly. Dairy cooperatives in Wisconsin and beverage bottlers in Michigan specify these rolls for throughput-critical lines where downtime costs exceed resin savings.
- Hand Stretch Wrap:Lower-gauge formulations reduce ergonomic load for manual application in capital-constrained produce packing sheds. Demand concentrates in Florida's citrus belt and California's Central Valley where seasonal labor flexibility outweighs automation economics.
- Pre-Stretched Wrap:Factory elongation reduces neckdown and application force requirements for mixed pallet loads.
- Custom Stretch Wrap:Perforation pattern engineering matches specific respiration rates for ethylene-sensitive commodities.
Machine stretch wrap holds the largest share; momentum sits with custom perforation configurations.
Material:
Resin selection determines regulatory pathway complexity, with recycled-content formulations requiring extended certification timelines compared to virgin polymer streams.
- Polyethylene:Linear low-density grades dominate blown film extrusion for pallet containment, offering puncture resistance and cling balance across temperature-variable shipments. German automotive exporters and Dutch flower logistics specify LLDPE-based vented films for moisture-resistant yet breathable transit packaging.
- Recycled Plastics:Post-industrial scrap purification to food-contact standards demands advanced melt filtration and polymer science expertise. FDA substance notifications and EFSA safety assessments for perforation additives extend qualification cycles, compressing converter margins during resin price volatility.
- Polypropylene:Higher stiffness suits rigid load containment where breathability requirements are secondary.
- PVC:Legacy formulations persist in industrial goods applications with limited food-contact exposure.
Polyethylene dominates volume; recycled plastics are climbing the fastest amid EU Green Deal mandates.
Application:
Application-driven segmentation separates temperature-controlled supply chains from ambient industrial logistics, with condensation prevention requirements dictating perforation density specifications.
- Packaged Food:Fresh produce cold chains specify aperture patterns preventing moisture accumulation on berries and leafy greens during automated distribution center handling. California's Central Valley packers and Florida citrus shippers drive specification demand for respiration-rate-matched films.
- Pharmaceuticals:Hygroscopic active ingredients and excipients require breathable yet secure pallet unitization for temperature-controlled distribution, with moisture-sensitive compounds demanding precise humidity management.
- Retail Packaging:Shelf-ready pallet loads prioritize optical clarity and printability for brand visibility.
- Industrial Goods:Chemical and automotive components specify vented containment for hygroscopic parts where corrosion prevention meets load stability.
Packaged food commands the largest application share; pharmaceuticals show steepest expansion trajectory on cold chain infrastructure investments.
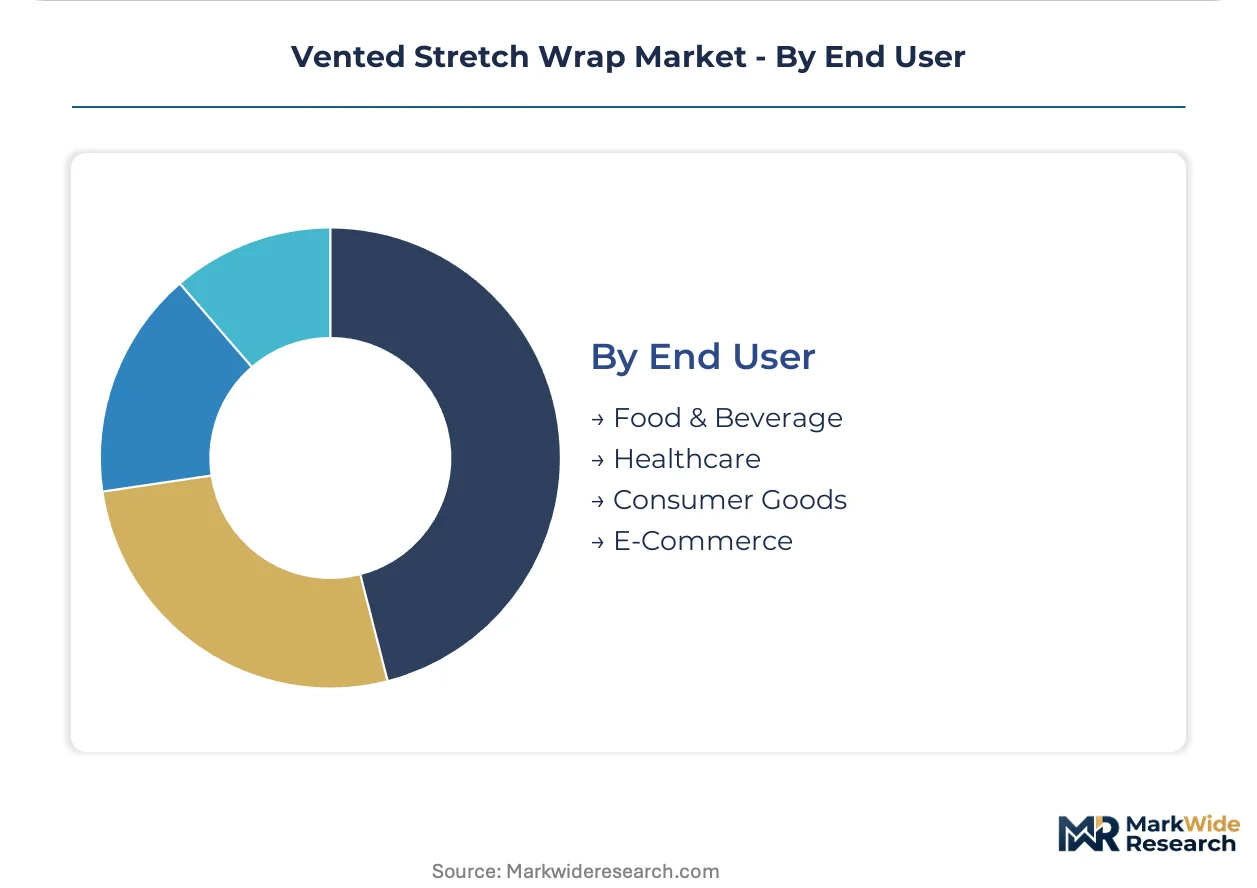
End User:
End-user concentration reflects procurement consolidation patterns, with large cooperatives negotiating direct mill contracts while fragmented operators rely on distributor networks.
- Food & Beverage:Logistics teams at dairy cooperatives and beverage bottlers now specify vented films for breathable pallet loads, with automated facilities in Wisconsin and Michigan consolidating supplier relationships through annual volume agreements.
- E-Commerce:Fulfillment center throughput requirements drive demand for machine-compatible rolls with consistent unwind tension and minimal end-user adjustment.
- Healthcare:Hospital and pharmaceutical distribution networks prioritize lot traceability and contamination prevention in pallet containment specifications.
- Consumer Goods:Brand owners face extended producer responsibility cost reallocation under state-level EPR frameworks in California and New York.
Food & Beverage holds the largest end-user position; e-commerce fulfillment networks are gaining share fastest on automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain corridors and automated container handling systems anchor Europe's vented stretch wrap distribution networks for perishable exports.
Germany
Automotive chemical exporters in Baden-Württemberg and North Rhine-Westphalia specify moisture-resistant breathable films for hygroscopic component shipments. REACH authorization deadlines for slip agents and anti-fog additives are forcing eight-to-twelve month requalification cycles at converter facilities. Stuttgart's automotive logistics clusters absorb these delays while maintaining pallet containment specifications for just-in-time supply chains.
United States
Dairy cooperatives in Wisconsin and beverage bottlers in Michigan negotiate direct mill-to-warehouse contracts for machine-grade vented films. FDA food-contact substance notifications govern perforation additives in films touching unpackaged produce. California's Central Valley packing sheds drive hand-wrap demand where seasonal labor flexibility outweighs turntable automation economics.
Netherlands
Flower logistics operators at Aalsmeer FloraHolland require LLDPE-based vented films balancing breathability with moisture resistance for temperature-variable shipments. EU Green Deal recycled-content mandates are accelerating post-industrial scrap processing investments at Dutch converter facilities. Rotterdam's port-centric distribution infrastructure enables rapid fulfillment for continental European horticulture exporters.
India
FSSAI-mandated food safety modernization is creating specification demand for vented containment films in dairy and horticulture cold chains. The country's national food regulator enforces packaging material compliance through centralized licensing frameworks. Maharashtra's dairy processing clusters and Karnataka's grape export corridors are piloting perforated film specifications for automated distribution center handling.
China
Yangtze River Delta fresh produce distribution centers specify aperture patterns preventing condensation accumulation on berries and leafy greens. The national standards administration governs food-contact plastics through GB standards with evolving recycled-content provisions. Shanghai's automated logistics parks are integrating machine-wrap systems operating above fifty pallets hourly for domestic e-commerce fulfillment networks.
Vented Stretch Wrap Market Competitive Landscape
On the supply side, the industry is consolidating around blown film extrusion specialists with captive resin sourcing and toll manufacturing partnerships. Tiered competitive positioning separates scale-driven volume producers from precision perforation engineers serving ethylene-sensitive commodity segments. Three archetypes dominate: integrated resin-to-film converters, regional toll manufacturers, and custom perforation technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants secure food-contact certification for recycled-content formulations.
Among North American fabricators, Paragon Films, Inc. and Sigma Plastics Group exemplify distinct strategic positions within the supply base. Paragon Films, Inc. occupies a role tied to Midwest extrusion capacity and same-day fulfillment capabilities for regional dairy networks. Sigma Plastics Group anchors a position through upstream resin control and distributed manufacturing partnerships across the Southeast. Integrated Packaging Group represents the custom perforation archetype, with pattern engineering capabilities matching specific respiration rates for climacteric fruit logistics.
| Leading Market Players |
|---|
| Integrated Packaging Group |
| Inteplast Group |
| AEP Industries Inc. |
| Darnel, Inc. |
| Intertape Polymer Group |
| Paragon Films, Inc. |
| Sigma Plastics Group |
| Excel Pac LLC |
| Berry Global Inc. |
| Others |
Value Network & Pricing Analysis
LLDPE resin concentration in US Gulf Coast petrochemical corridors and Middle Eastern feedstock hubs funnels pricing power toward integrated converters with captive naphtha or ethane access, leaving toll-dependent regional fabricators exposed to margin compression during feedstock volatility cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates custom perforation engineering with respiration-rate certification from commodity machine-wrap grades and hand-wrap volumes. Price differentiation hinges on FDA food-contact certification tier and volume scale, with automated dairy cooperatives locking annual contracts while seasonal produce sheds absorb spot-price exposure. Pricing pressure stems from recycled-content qualification delays compressing converter margins during resin price spikes. Hand-wrap buyers in California's Central Valley show highest price sensitivity; pharmaceutical logistics teams demonstrate lowest.
Supply Chain Analysis
Toll manufacturing partnerships concentrate blown film extrusion capacity across the US Midwest, Southeast, and Germany's industrial belt. Raw material flows draw from LLDPE resin streams, post-industrial scrap purification systems, and perforation additive formulations. Single-source vulnerability sits with specialized melt filtration equipment for food-contact recycled content. Distribution runs through direct mill-to-warehouse contracts for automated facilities, layered distributor networks for capital-constrained seasonal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as dairy cooperatives and beverage bottlers consolidate supplier relationships through direct annual contracts, fragmenting price-setting leverage for converters without food-contact certification or captive resin sourcing.
For Market Incumbents: Build regulatory moats by accelerating FDA and EFSA recycled-content additive registrations before REACH deadlines force competitor requalification cycles. Secure backward integration into post-industrial scrap purification to defend margin position against resin price volatility. Anchor capacity expansion in Wisconsin and Michigan dairy corridors where automated facilities lock multi-year volume agreements. For New Entrants and Emerging Players: Build out pharmaceutical hygroscopic packaging specifications where moisture-sensitive active ingredient logistics demand breathable pallet containment with limited incumbent penetration. Target India's Maharashtra dairy clusters and Karnataka grape export corridors where FSSAI modernization creates specification windows without entrenched supplier relationships. Lead with laser perforation precision capabilities that match respiration rates for climacteric fruits. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed blown film extruders lacking food-contact certification infrastructure for recycled-content formulations. Five-to-ten-year viability favors converters with captive resin sourcing and toll manufacturing networks spanning multiple geographies. Watch for state-level EPR legislation in California and New York accelerating consolidation cost pressure on undifferentiated regional players.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Contact Certification Investment | FDA substance notifications for recycled-content perforation additives unlock pharmaceutical and premium produce segments. |
| Captive Resin Sourcing Integration | Backward integration into LLDPE feedstock hedges margin compression during naphtha and ethane index volatility. |
| Custom Perforation Technology Licensing | Proprietary aperture geometries for ethylene-sensitive commodities command specification premiums from California berry packers. |
| Toll Manufacturing Network Expansion | Distributed blown film capacity across Southeast and Midwest enables same-day fulfillment for regional dairy cooperatives. |
| Direct Mill-to-Warehouse Contracting | Bypassing distributor layers captures volume consolidation as Wisconsin and Michigan automated facilities consolidate supplier relationships. |
Research Methodology
The analysis maps machine-wrap, hand-wrap, pre-stretched, and custom perforation product categories, each validated through converter plant managers, dairy cooperative procurement leads, produce packing shed operators, and pharmaceutical logistics directors. Primary interviews combined with secondary validation from FDA food-contact substance notifications, EPA VOC emission guidelines, EU ECHA substance evaluations, and customs trade data on LLDPE film imports. Bottom-up volume triangulation across end-user segments cross-checked against top-down resin consumption estimates.
Assumptions held fixed include REACH authorization timelines for slip agent replacements, EPR framework adoption pace in California and New York, and laser perforation technology diffusion rates. Segmentation dimensions modeled span product type, material grade tier, application temperature requirements, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections across fresh produce cold chain expansion and pharmaceutical logistics automation. Industry-specific inputs incorporated ethylene sensitivity respiration rates for climacteric fruits and FSSAI compliance timelines for Indian dairy infrastructure.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Gulf Coast petrochemical-integrated converters or accelerated EPR enforcement by state regulators would shift outcomes beyond modeled ranges. Quarterly review of FDA food-contact certification backlogs, naphtha-ethane feedstock spreads, and Indian FSSAI licensing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Kraft Paper Pouch Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Heat Seal Pouch Market
Pouch
Clear Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Retort Pouch Market
Pouch
Zipper Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Utility Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Spouted Pouches Market
Pouch
Portion Control Packs Market
Pouch
Digital Printed Pouch Market
Pouch
Kraft Block Bottom Pouch Market