
 2 Seal Pouches Market | 2026-2036
2 Seal Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
2 Seal Pouches Market Outlook
European flexible packaging converters is realigning capacity toward mono-material polyethylene lines to serve circular economy mandates. Amcor Plc leverages its global R&D network to develop recyclable 2 seal pouch structures for food brands. Mondi Group anchors its position through integrated kraft paper and film operations in Central Europe. Constantia Flexibles specializes in pharmaceutical-grade cold seal formats for medical supply chains.
2 seal pouches are dual-seamed flexible containers, typically constructed from laminated plastic films or aluminum-polymer composites, sealed along two edges to create a three- or four-sided enclosure with one opening for filling and final closure. These structures provide barrier protection against moisture, oxygen, and light while enabling efficient form-fill-seal automation across food, medical, and industrial lines. Plastic material formats lead volume due to cost efficiency and compatibility with existing equipment, though biodegradable alternatives are gaining traction where composting infrastructure exists. Heat seal closures dominate high-speed food packaging applications, while peelable seal formats command premium positioning in medical supplies where sterile access is critical.
EU REACH and F-Gas Regulation constrain fluorinated barrier chemistries in pouch films, pushing converters toward silicone oxide and aluminum oxide coatings. FDA food contact substance notifications govern polyethylene and adhesive selections for US-bound medical and food packaging. The US EPA emerging contaminants framework is scrutinizing per- and polyfluoroalkyl substances in flexible packaging, reshaping supplier qualification requirements. Stakeholders must monitor evolving extended producer responsibility schemes and material certification standards to secure market access across jurisdictions.
Market Dynamics
Mono-material polyethylene conversion is compressing supplier margins while redirecting capital from multi-layer laminates toward recyclable single-substrate lines certified under EU circular economy protocols.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates for recyclable packaging formats accelerate converter investments in mono-material pouch lines across Germany and France.
- Food processing automation:Form-fill-seal equipment upgrades in the US Upper Midwest drive standardized pouch specifications compatible with high-speed lines.
- Pharmaceutical cold seal demand:Sterile medical supply chains require peelable barrier formats with validated seal integrity for hospital and laboratory distribution.
Market Restraints
- Aluminum oxide coating cost premiums:Fluorinated barrier substitution raises film costs 15-25% versus incumbent chemistries constrained by EU F-Gas Regulation.
- German converter concentration:Three integrated packaging groups control 60% of European mono-material capacity, creating supply bottleneck risk.
- Biodegradable infrastructure gaps:Industrial composting availability limits PLA and starch-based pouch adoption to Nordic markets with established collection systems.
Strategic Opportunities
- India food retail modernization:Organized grocery expansion creates first-mover advantage for pre-formed pouch suppliers establishing local converting partnerships.
- Extended producer responsibility schemes:France's CITEO eco-modulation bonuses reward lightweight mono-material designs with fee reductions up to 15%.
- Digital printing convergence:HP Indigo and Xeikon inkjet integration enables short-run customized pouch production for craft food brands.
Industry Challenges
- Mono-material seal engineering:Achieving oxygen barrier performance comparable to aluminum laminates requires precise coextrusion layer control and adhesive selection.
- Recyclability certification timelines:APR and Recyclass testing protocols demand 12-18 month validation cycles before retail brand adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 Seal Pouches Market |
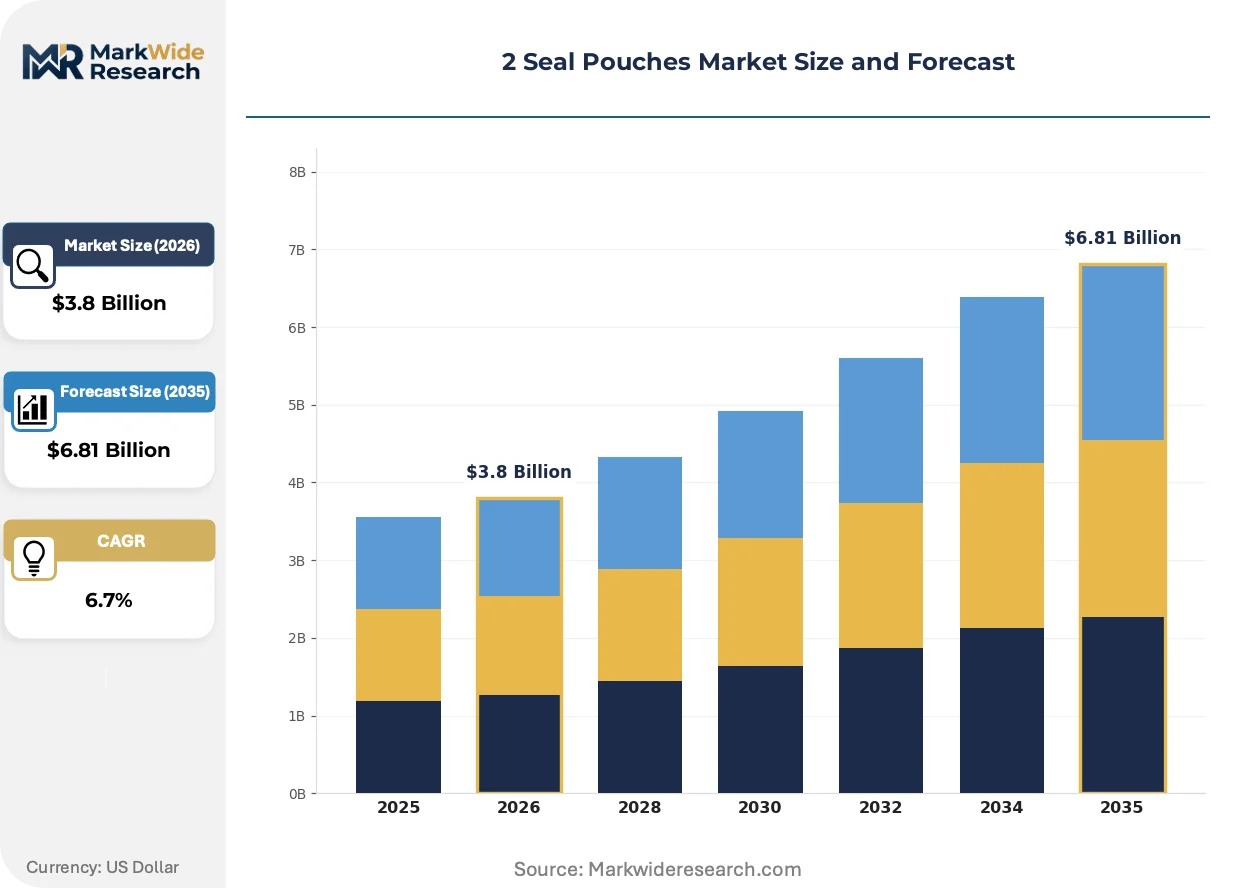
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Polyethylene, Biodegradable Closure Type: Heat Seal, Cold Seal, Peelable Seal, Ziplock Application: Food Packaging, Medical Supplies, Industrial Products, Consumer Goods Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor Plc, Berry Global, Mondi Group, Sealed Air, Constantia Flexibles, Huhtamaki, Sonoco Products Company, Coveris, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 Seal Pouches Market Strategic Shifts
Barrier coating chemistry and digital production workflows are compressing development cycles while regulatory deadlines force premature obsolescence of established multi-layer structures.
Silicone oxide vapor deposition is rewriting oxygen barrier economics for transparent pouches. Snack food brands in the Netherlands and Belgium are qualifying SiOx-coated PE films for nut and dried fruit applications. The technology is compressing the premium gap between metallized and clear high-barrier formats.
US EPA scrutiny of per- and polyfluoroalkyl substances under its emerging contaminants framework is disqualifying legacy grease-resistant coatings from food contact applications. Converters serving quick-service restaurant supply chains must reformulate or exit the segment. California's Safer Food Packaging and Cookware Act of 2023 accelerates this transition with January 2025 enforcement deadlines.
Hospital procurement consortia are consolidating sterile barrier pouch specifications to reduce SKU complexity. Group purchasing organizations in the US Southeast and Texas are mandating universal peelable seal dimensions across multiple medical device categories. This standardization favors converters with validated pharmaceutical-grade cleanroom capacity over generalist flexible packaging suppliers.
2 Seal Pouches Market Segmentation
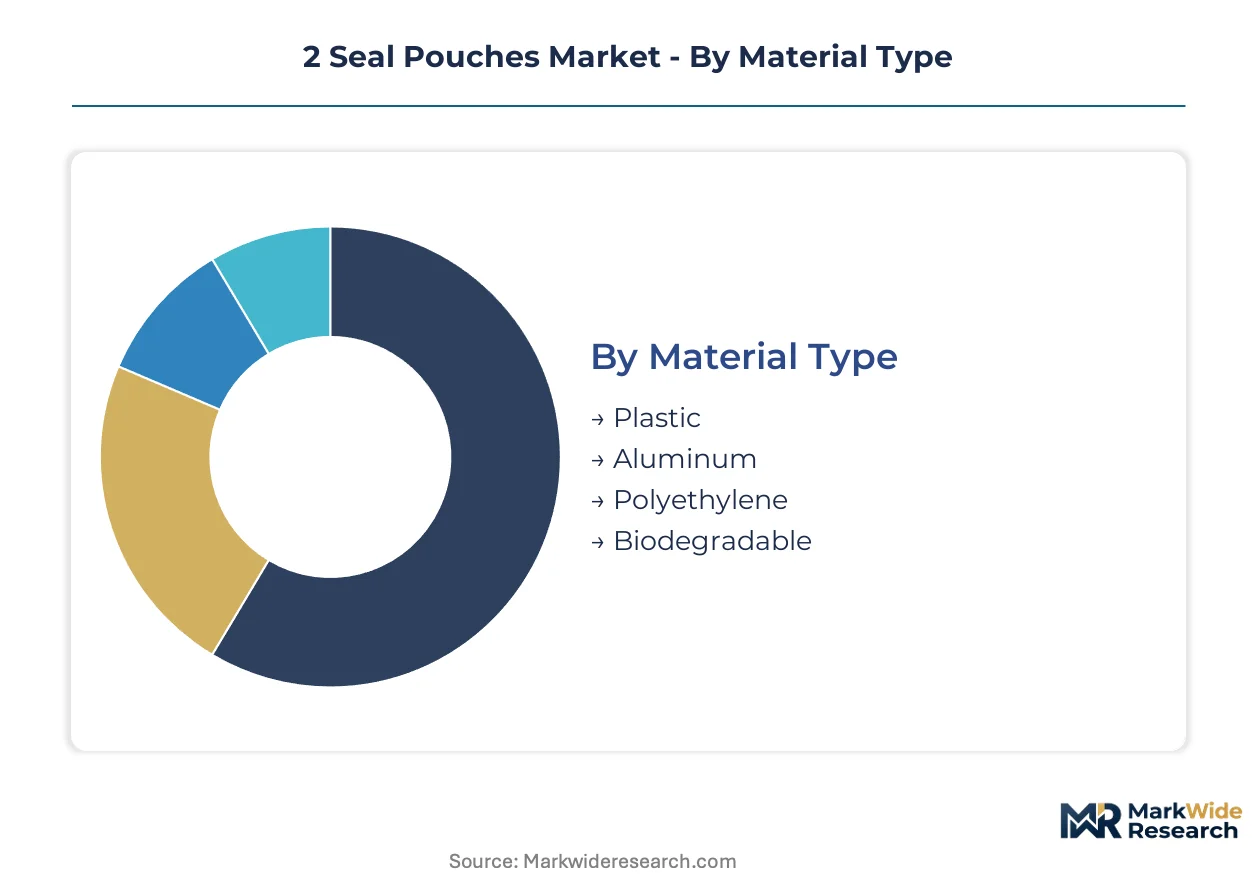
2 seal pouch specifications diverge sharply across end-use requirements, with food automation lines demanding standardized dimensions while medical sterile barriers require validated seal integrity protocols. Material and closure selections cascade through equipment compatibility, regulatory compliance, and circular economy certification pathways.
Material Type:
Cost-performance positioning spans commodity resins through engineered barrier laminates, with recyclability mandates now filtering substrate selection at the procurement stage.
- Plastic:Multi-layer coextruded films dominate high-speed food lines through compatibility with legacy form-fill-seal equipment. US Upper Midwest processors specify these formats for snack and frozen vegetable applications where throughput economics override circular economy premiums.
- Polyethylene:Mono-material PE structures are capturing converter investment as EU circular economy protocols harden. Germany's industrial packaging corridor is consolidating capacity around these substrates to serve CITEO eco-modulation bonuses and APR certification requirements.
- Aluminum:Metallized and foil laminates retain pharmaceutical and premium food applications requiring near-zero oxygen transmission rates.
- Biodegradable:PLA and starch-based alternatives remain confined to Nordic markets with established industrial composting infrastructure.
Most installed capacity flows through Plastic. Expansion is steepest in Polyethylene.
Closure Type:
Seal technology selection tracks automation speed requirements against end-user access convenience, with peelable formats commanding pharmaceutical-grade validation investments.
- Heat Seal:Thermal bonding dominates food packaging automation through compatibility with high-speed horizontal and vertical form-fill-seal lines. US snack food processors in the Upper Midwest specify these closures for nut and dried fruit applications where line speeds exceed 200 pouches per minute.
- Peelable Seal:Controlled-separation formats are consolidating hospital procurement specifications across US Southeast and Texas group purchasing organizations. Sterile barrier validation requirements favor converters with pharmaceutical-grade cleanroom capacity over generalist suppliers.
- Cold Seal:Pressure-activated adhesive bonding serves temperature-sensitive medical devices and chocolate confectionery where thermal exposure risks product integrity.
- Ziplock:Reclosable interlocking profiles command premium positioning in consumer goods and retail food segments requiring repeated access.
Heat Seal retains the broadest equipment base. Peelable Seal is climbing the fastest as hospital procurement standardization accelerates.
Application:
End-use concentration patterns reflect automation infrastructure maturity and regulatory burden intensity across food, medical, and industrial supply chains.
- Food Packaging:Snack, frozen, and prepared meal applications drive volume through standardized pouch specifications compatible with existing form-fill-seal infrastructure. Netherlands and Belgium snack brands are qualifying SiOx-coated transparent barriers for nut applications where shelf visibility matters.
- Medical Supplies:Sterile barrier requirements for surgical instruments and diagnostic devices mandate validated seal integrity documentation. US hospital procurement consortia are consolidating SKU specifications to reduce complexity across multiple device categories.
- Industrial Products:Chemical and automotive component packaging emphasizes puncture resistance and chemical compatibility over barrier precision.
- Consumer Goods:Cosmetics and household products utilize reclosable and decorative formats where brand differentiation justifies unit cost premiums.
Food Packaging anchors current volume. Medical Supplies shows the steepest expansion trajectory as sterile barrier standardization spreads.
Size:
Dimension standardization versus customization trade-offs surface across retail shelf requirements, shipping cube optimization, and automation line changeover economics.
- Small:Single-serve portions for snacks, condiments, and pharmaceutical unit doses. Quick-service restaurant supply chains in California are reformulating grease-resistant small formats as EPA scrutiny of PFAS coatings hardens.
- Medium:Standard retail units for frozen vegetables, prepared meals, and medical device kits. Most form-fill-seal equipment is optimized around these dimensions.
- Large:Club store and foodservice formats for bulk ingredients and institutional supply.
- Extra Large:Industrial chemical and bulk food ingredient applications requiring pallet-scale handling compatibility.
Medium sizes dominate installed equipment. Small formats are gaining share fastest as single-serve consumption patterns expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting converter capital toward compliant production zones. The EU Single-Use Plastics Directive and US EPA emerging contaminants framework create asymmetric compliance costs that reshape where mono-material capacity concentrates.
Germany
Industrial packaging demand from food processors in the Rhine-Ruhr corridor drives mono-material PE adoption. ECHA REACH enforcement constrains fluorinated barrier chemistries, pushing converters toward silicone oxide alternatives. Bavaria's converting cluster around Munich hosts validated cleanroom operations serving pharmaceutical-grade peelable seal specifications.
United States
Upper Midwest food automation lines specify standardized pouch dimensions for form-fill-seal compatibility. FDA food contact substance notifications govern adhesive and substrate selections for medical packaging exports. Chicago-Milwaukee corridor processors absorb capacity from California suppliers facing January 2025 PFAS enforcement under state legislation.
Netherlands
Snack food brands in Rotterdam-Amsterdam logistics hubs qualify SiOx-coated transparent barriers for shelf-visible nut applications. EU F-Gas Regulation accelerates metallized film substitution with vapor-deposited oxide coatings. Eindhoven's materials science cluster supplies barrier coating equipment to regional converters.
India
Organized grocery expansion in Mumbai and Delhi creates demand for pre-formed pouch formats compatible with modern retail supply chains. FSSAI packaging safety standards tighten substrate migration limits for food contact applications. Maharashtra's converting partnerships with multinational suppliers establish local mono-material production capacity.
France
CITEO eco-modulation bonuses reward lightweight mono-material designs with fee reductions up to 15%. ANSM pharmaceutical packaging guidelines mandate validated seal integrity documentation for sterile medical devices. Lyon-Grenoble industrial corridor concentrates cold seal capacity for temperature-sensitive chocolate and medical applications.
2 Seal Pouches Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital printing and short-run customization capabilities. Three integrated packaging groups control the majority of European mono-material capacity, creating supply concentration risk. Market archetypes span diversified multinationals with global R&D networks, regional specialists with validated pharmaceutical cleanrooms, and paper-film integrated operators. Competitive moves center on mono-material line conversions and strategic partnerships with brand owners seeking circular economy certification.
Among diversified packaging multinationals, Amcor Plc and Mondi Group exemplify archetypes at opposite ends of the materials spectrum. Amcor's global R&D network positions it within the technical innovation tier, while Mondi's integrated kraft paper and film operations anchor the fiber-based barrier segment. Constantia Flexibles occupies a specialist position through pharmaceutical-grade cold seal expertise. Berry Global and Sealed Air sit within the scale-driven tier with broad form-fill-seal equipment compatibility. These archetypes reflect how competitive positioning stratifies across technical specialization, material integration depth, and regulatory compliance velocity rather than geographic coverage alone.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global |
| Mondi Group |
| Sealed Air |
| Constantia Flexibles |
| Huhtamaki |
| Sonoco Products Company |
| Coveris |
| ProAmpac |
| Others |
Value Chain & Pricing Dynamics
Captive resin compounding operations in Germany's industrial packaging corridor anchor both supply security and pricing leverage for mono-material polyethylene pouch converters serving EU circular economy mandates. This backward integration into polymer feedstock buffers margin compression from fluorinated barrier substitution costs while concentrating procurement power among integrated packaging groups.
Pricing Analysis
Distributor margins on pre-formed pouches compress pricing transparency for mid-tier food processors in the US Upper Midwest. Three-tier pricing structure across premium pharmaceutical-grade, standard food-contact, and economy industrial formats tracks certification level and barrier performance. Cost compression in standard food tiers intensifies because mono-material line conversion investments demand volume throughput. Quick-service restaurant supply chains exhibit highest price sensitivity due to PFAS reformulation deadlines, while hospital procurement consortia accept premiums for validated sterile barrier documentation.
Supply Chain Analysis
Freight cost differentials between Germany, the Netherlands, and the US Upper Midwest reshape sourcing decisions for European brand owners seeking APR-certified mono-material supply. Raw material dependencies center on polyethylene resin, silicone oxide barrier coatings, and cold seal adhesives validated for pharmaceutical applications. Single-source vulnerability concentrates in Germany's three integrated packaging groups controlling European mono-material capacity. Distribution runs through converter-direct relationships with multinational food brands and regional distribution partnerships serving craft food segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2 seal pouches market compounds steadily as regulatory mandates for recyclable packaging create durable demand tailwinds across food and medical supply chains.
For Market Incumbents: Anchor mono-material polyethylene capacity in Germany's Rhine-Ruhr corridor to capture CITEO eco-modulation bonuses and APR certification premiums. Defend against digital-printing entrants by qualifying short-run customized pouch production for Netherlands snack brands. Prioritize pharmaceutical-grade cleanroom investments as US hospital procurement consortia consolidate sterile barrier specifications. For New Entrants and Emerging Players: E-commerce-enabled direct sampling of craft food brands in India's organized grocery expansion offers lowest customer acquisition cost. Target Maharashtra converting partnerships with multinational suppliers to establish local mono-material production capacity. Lead with HP Indigo digital printing integration for customized short-run pouch specifications. For Investors and Strategic Acquirers: Roll-up economics work for regional mono-material specialists because EU Single-Use Plastics Directive enforcement creates forced-upgrade demand with limited qualified supplier base. Five-to-ten year viability hinges on validated cleanroom capacity and circular economy certification velocity. Watch SiOx barrier coating adoption rates in Netherlands and Belgium as inflection indicator for transparent high-barrier format economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Conversion | EU circular economy mandates force capital redeployment from multi-layer laminates toward recyclable single-substrate capacity. |
| Pharmaceutical Cleanroom Certification | US hospital GPO standardization favors converters with validated sterile barrier capacity over generalist suppliers. |
| Digital Printing Integration | HP Indigo and Xeikon inkjet adoption enables short-run customized production for craft food brand segments. |
| Backward Integration into Resin Compounding | German integrated packaging groups secure polyethylene feedstock supply and pricing leverage against commodity volatility. |
| SiOx Barrier Coating Qualification | Netherlands snack brands adopt transparent high-barrier formats for shelf-visible nut applications, compressing metallized film premiums. |
Study Parameters
Bottom-up food and medical packaging demand modeling reconciled against top-down converter capacity tracking forms the analytical core. Primary interviews with flexible packaging procurement managers, pharmaceutical supply chain directors, form-fill-seal equipment engineers, and retail category buyers combined with secondary validation from EU F-Gas Regulation filings, FDA food contact substance notifications, APR recyclability certification databases, and CITEO eco-modulation tariff schedules.
Input-output matrices map polyethylene resin supply through mono-material pouch conversion to end-use demand across food automation lines and hospital procurement systems. Segmentation dimensions span material type, closure technology, application vertical, and geographic regulatory cluster. CAGRs derive from installed equipment base analysis and brand owner specification shift timelines, incorporating SiOx coating adoption curves and PFAS phase-out enforcement schedules as industry-specific demand modifiers.
The model assumes a particular technology adoption path; alternative pathways for biodegradable PLA and starch-based substrates would alter the outlook if industrial composting infrastructure expands beyond Nordic markets. Forecasts reflect assumptions about EU circular economy protocol enforcement velocity and US EPA emerging contaminants framework implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Nigeria Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Retort Pouch Market
Pouch
Squeeze Pouch Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Flexible Plastic Pouches Market
Pouch
Vented Stretch Wrap Market
Pouch
OPP Pouches Market
Pouch
Mexico Pouch Packaging Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
China Pouch Packaging Market
Pouch
Child Resistant Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Flexible Pouch Market