
 Global Vinyl Ester Market | 2026-2036
Global Vinyl Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinyl Ester Market Foresight
The EU Green Deal is restructuring demand patterns across the vinyl ester value chain by mandating lower volatile organic compound emissions in industrial coatings and composite manufacturing. INEOS leverages its integrated petrochemical feedstock position to stabilize bisphenol A vinyl ester supply costs across European and Asian markets. Swancor anchors its competitive position through specialized novolac and flame-retardant resin grades targeting wind energy and chemical processing applications. Scott Bader Company Ltd differentiates via formulated gelcoat systems that extend performance warranties for marine and infrastructure customers.
Vinyl ester resins constitute thermosetting polymers synthesized through epoxy resin esterification with methacrylic acid, yielding materials with tensile strengths exceeding 80 MPa and superior chemical resistance compared to standard polyester resins. These properties position vinyl esters as critical matrices for fiber-reinforced composites in corrosive environments and structural load-bearing applications. Bisphenol A grades dominate volume consumption due to their balanced cost-performance profile in marine coatings and chemical processing equipment. Novolac variants represent the fastest-expanding product category, driven by elevated temperature requirements in power generation flue gas desulfurization systems and refinery infrastructure. Phenolic vinyl esters command premium positioning in aerospace and electronics applications where smoke toxicity standards restrict conventional resin options.
The EPA enforces National Emission Standards for Hazardous Air Pollutants affecting composite manufacturing facilities, compelling resin producers to reformulate with reduced styrene monomer content. REACH registration requirements in Europe govern chemical substance authorization, directly influencing raw material sourcing flexibility and product registration costs for vinyl ester suppliers. China's MEE implements increasingly stringent emissions controls on petrochemical operations, reshaping local production economics and import dependency patterns. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-content certification schemes as these frameworks increasingly determine market access and contract eligibility across major demand centers.
Market Dynamics
The EU Green Deal's industrial emissions mandates are forcing vinyl ester formulators to eliminate high-styrene chemistries and validate bio-based feedstocks, restructuring raw material sourcing and product registration economics across European and Asian supply chains.
Growth Catalysts
- Offshore wind installation surge:China's coastal provinces are adding chemical processing capacity that demands novolac vinyl esters for flue gas desulfurization systems in power generation infrastructure.
- REACH authorization pathways:ECHA's streamlined substance registration for lower-styrene alternatives is accelerating reformulation approvals for marine coating applications across EU shipyards.
- Flame-retardant specification tightening:Aerospace smoke toxicity standards in commercial aircraft interiors are displacing conventional polyester resins with phenolic vinyl ester systems.
Market Restraints
- Bisphenol A feedstock volatility:Petrochemical cracking economics in the US Gulf Coast and Rotterdam clusters create raw material cost instability that compresses formulation margins.
- Styrene monomer regulatory compression:EPA National Emission Standards for Hazardous Air Pollutants enforcement adds compliance capital burdens for composite manufacturing facilities.
- Thermoset recycling incapability:Cross-linked polymer chemistry prevents mechanical reprocessing, exposing producers to extended producer responsibility liabilities under EU circular economy frameworks.
Strategic Opportunities
- India coastal infrastructure buildout:Paradip and Hazira port expansions require corrosion-resistant materials for chemical storage tanks and marine pilings.
- Bio-based methacrylic acid pathways:Agricultural waste-derived feedstocks from Brazilian sugarcane and European lignocellulosic sources enable carbon-intensity certification for EU Green Deal compliance.
- Digital formulation platforms:AI-accelerated resin design tools are compressing development cycles for customer-specific gelcoat systems in marine and infrastructure segments.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise in epoxy-ester synthesis and rheology control resides with aging technical workforces in Germany and Japan.
- Multi-jurisdiction registration synchronization:REACH dossiers, EPA TSCA notifications, and China MEE substance filings require parallel capital deployment without coordinated timelines.
- Legacy equipment incompatibility:Lower-styrene vinyl esters demand modified spray equipment and cure monitoring systems that disrupt established fabrication shop workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinyl Ester Market |
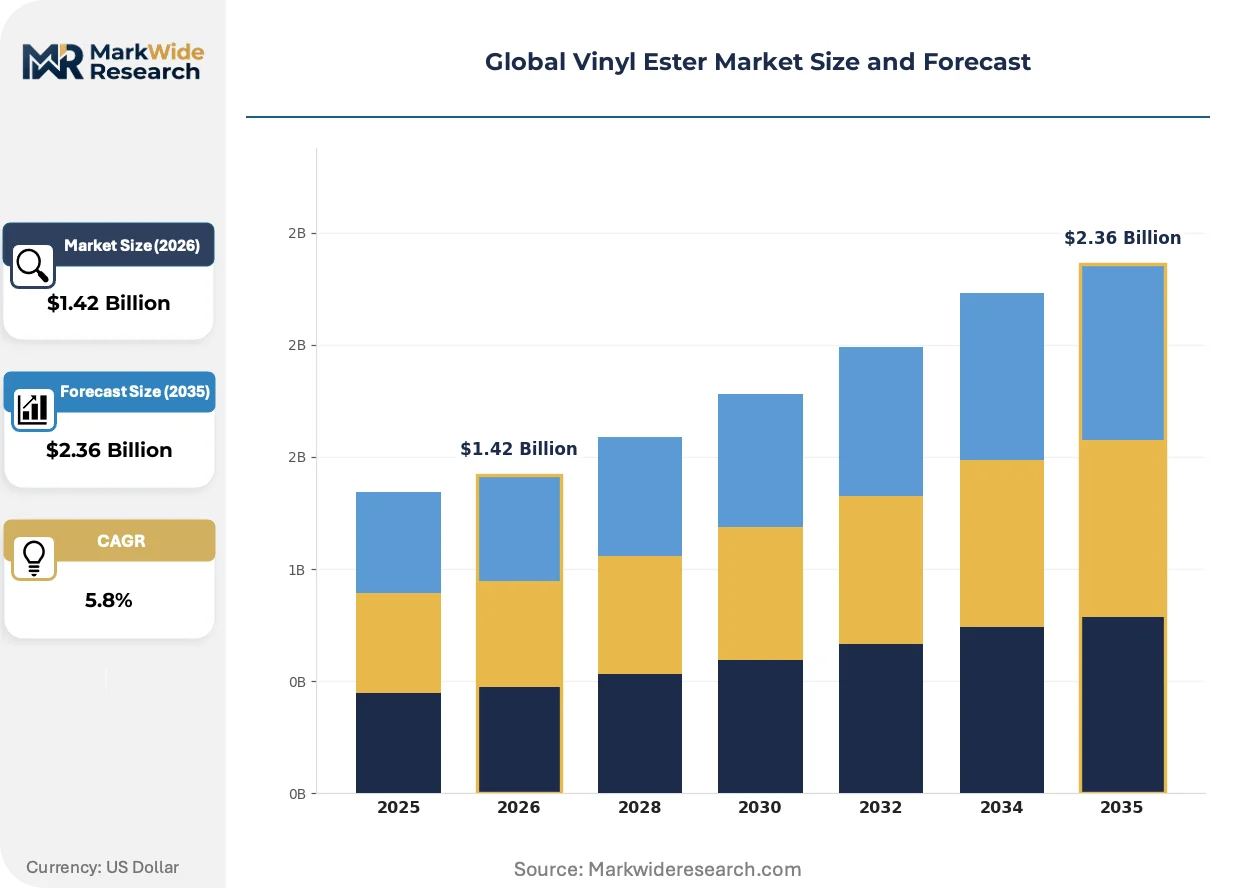
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dicyclopentadiene, Brominated, Phenolic, Bisphenol A, Novolac Application: Marine Coatings, Chemical Processing, Infrastructure, Electrical Insulation, Aerospace End User Industry: Water Treatment, Power Generation, Electronics, Construction, Transportation Form: Liquid, Gel, Paste, Powder, Emulsion |
| Companies Covered | Interplastic Corporation, SHOWA DENKO K.K, AOC, DIC CORPORATION, Swancor, INEOS, Scott Bader Company Ltd, Ashland, Polynt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinyl Ester Market Shifts & Advancements
Formulation chemistry, regulatory compliance architectures, and procurement specifications are converging to redefine competitive advantage in corrosion-resistant thermosets.
Hybrid vinyl ester-urethane systems are rewriting performance benchmarks for chemical processing equipment. Dow and Huntsman are advancing these materials for sulfuric acid storage tanks in US Gulf Coast refineries. The technology is compressing the traditional trade-off between chemical resistance and fracture toughness that has segmented bisphenol A and novolac grades.
China's MEE emissions controls on petrochemical operations are mandating closed-loop manufacturing and real-time monitoring for styrene handling. Facilities in Ningbo and Shanghai are retrofitting with vapor recovery systems. Domestic producers are responding by localizing novolac resin production to reduce import exposure and logistics emissions.
Shipyards in South Korea and Japan are unbundling coating warranties from hull fabrication contracts. Hyundai Heavy Industries and Imabari Shipbuilding now require resin suppliers to assume performance liability for 15-year anti-corrosion protection. This concentrates procurement authority with technical qualification teams and displaces price-driven spot purchasing.
Global Vinyl Ester Market Segmentation
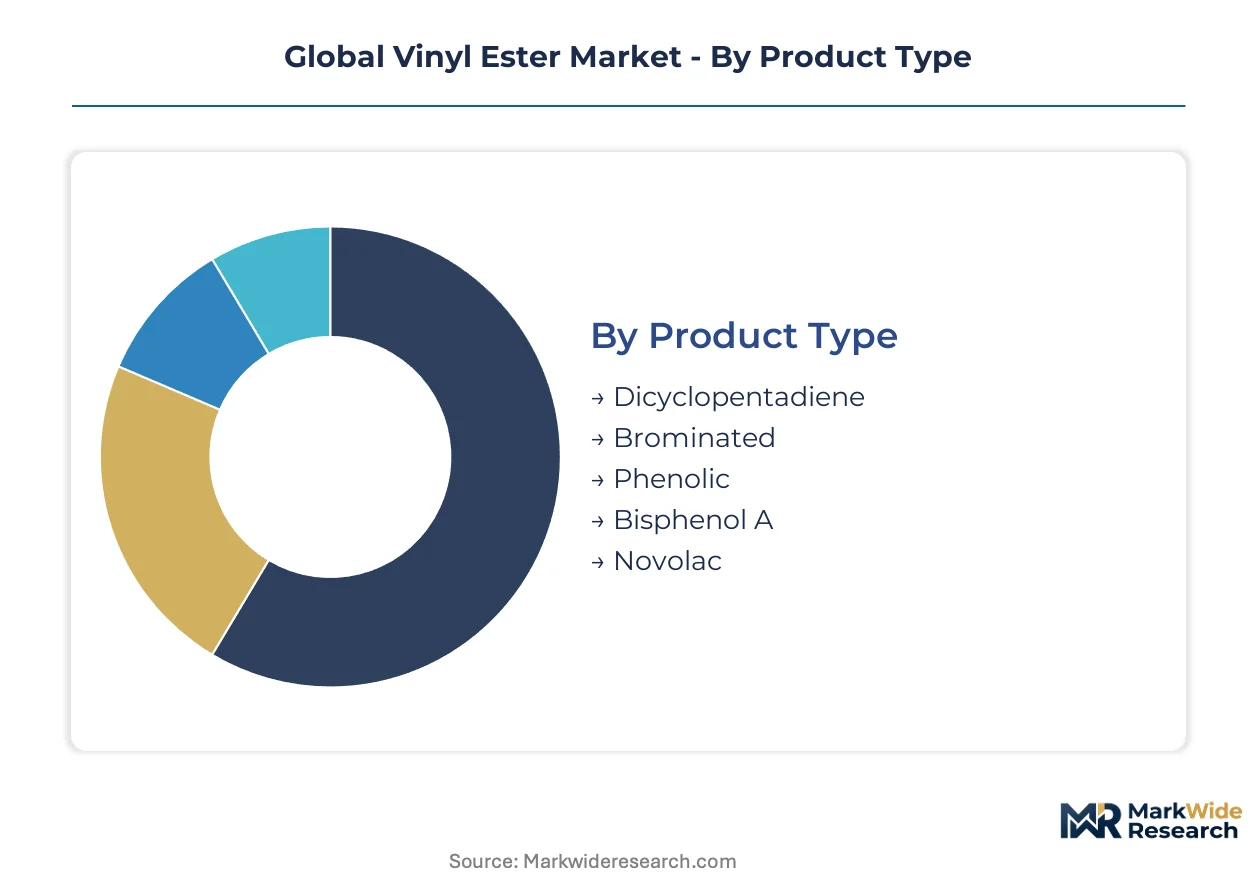
Vinyl ester purchasing decisions pivot on corrosion resistance thresholds, thermal stability requirements, and fabrication compatibility. End-users specify resin chemistry against chemical exposure profiles and regulatory compliance mandates rather than commodity pricing alone.
Product Type:
Formulation cost tiers separate commodity-grade marine coatings from specialized aerospace and chemical processing specifications.
- Bisphenol A:The dominant chemistry balances epoxy backbone toughness with methacrylic acid functionality for general-purpose corrosion protection. Shipyards in South Korea and Japan specify this grade for hull coating systems requiring 15-year performance warranties.
- Novolac:Epoxy novolac backbones deliver elevated temperature resistance above 120°C for flue gas desulfurization units in China's coastal power plants. MEE emissions controls are accelerating domestic production localization to reduce import logistics.
- Dicyclopentadiene:Cycloaliphatic structures improve UV stability and surface finish quality for gelcoat applications.
- Brominated:Halogenated formulations meet UL 94 V-0 flame spread ratings for electrical enclosure applications.
- Phenolic:Aromatic backbone chemistry achieves lowest smoke toxicity indices for commercial aircraft interior components under FAA certification.
Bisphenol A leads on scale; novolac leads on momentum.
Application:
Specification authority concentrates with asset owners operating in regulated corrosive environments rather than fabrication contractors.
- Chemical Processing:Sulfuric acid storage tanks and chlorine handling equipment demand novolac and bisphenol A matrices with glass fiber reinforcement. US Gulf Coast refineries are adopting hybrid vinyl ester-urethane systems from Dow and Huntsman for improved fracture toughness.
- Marine Coatings:Anti-corrosion protection for ship hulls and offshore platforms represents the largest volume outlet. Hyundai Heavy Industries and Imabari Shipbuilding now unbundle coating warranties from fabrication contracts, transferring performance liability to resin suppliers.
- Infrastructure:Bridge decks, wastewater treatment structures, and marine pilings require moisture-resistant gelcoat systems.
- Electrical Insulation:Transformer housings and switchgear enclosures utilize flame-retardant grades for arc tracking resistance.
- Aerospace:Interior paneling and cargo liner applications prioritize phenolic variants for smoke toxicity compliance.
Marine coatings leads on scale; chemical processing leads on momentum.
End User Industry:
Capital expenditure cycles in energy and infrastructure determine volume timing more than consumer-driven replacement patterns.
- Power Generation:Flue gas desulfurization systems in coal and gas-fired plants consume novolac vinyl esters for scrubber vessel linings. China's provincial additions of chemical processing capacity are expanding this segment fastest.
- Water Treatment:Municipal and industrial wastewater infrastructure requires corrosion-resistant materials for clarifier tanks and chemical feed systems. India's Paradip and Hazira port expansions are driving tankage demand.
- Construction:Reinforced concrete repair and protective coatings utilize liquid and gel formulations.
- Transportation:Rail and marine OEMs specify gelcoat systems for exterior durability.
- Electronics:Printed circuit board substrates and electrical housings require low-halogen grades.
Power generation leads on scale; water treatment leads on momentum.
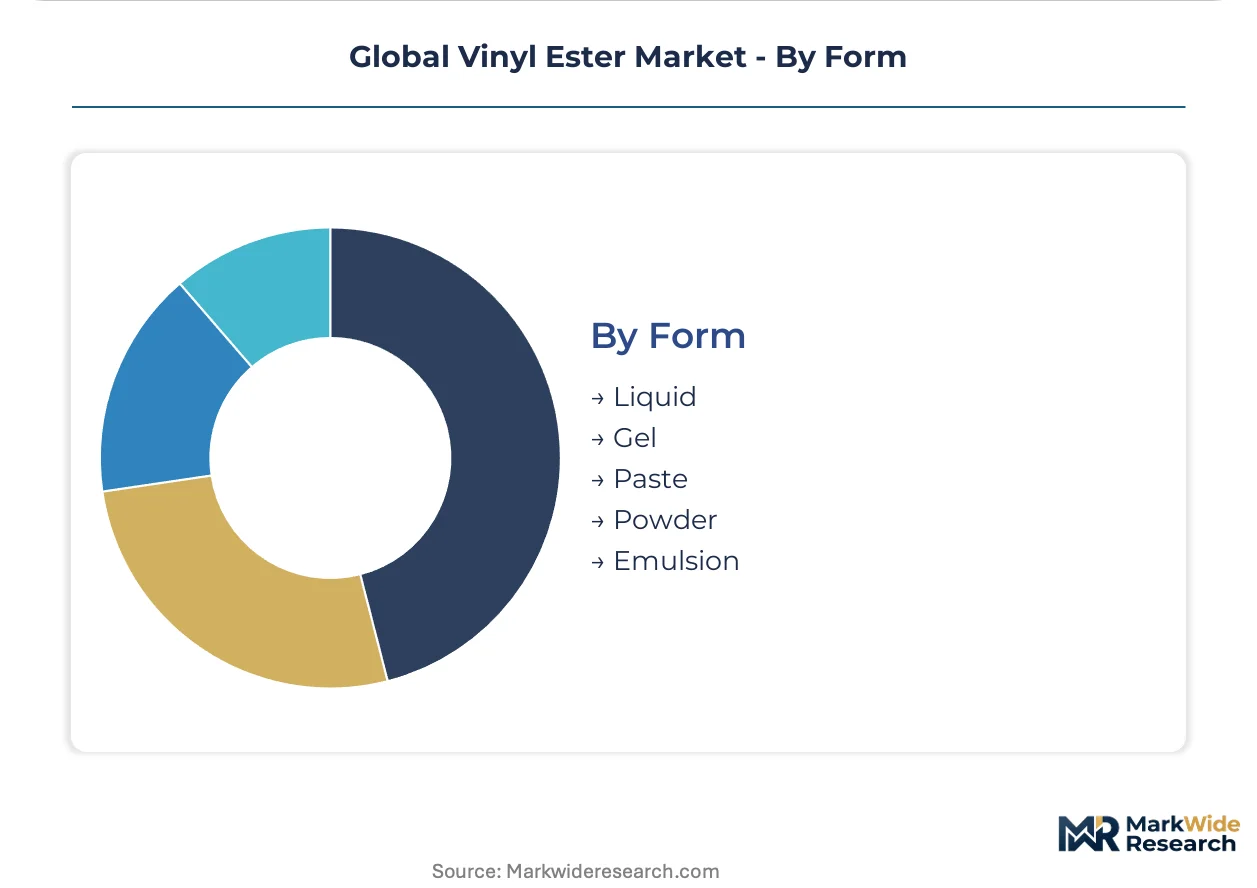
Form:
Fabrication method—spray, hand lay-up, resin transfer molding—dictates viscosity and thixotropy requirements.
- Liquid:Low-viscosity resins enable spray application and vacuum infusion for large marine and infrastructure components. EPA National Emission Standards for Hazardous Air Pollutants are forcing reformulation to reduced-styrene liquid systems requiring modified spray equipment.
- Gel:Thixotropic formulations prevent sag on vertical surfaces and overhead applications in chemical tank linings.
- Paste:Filled compounds provide gap-filling and adhesive properties for repair applications.
- Powder:Solid resin forms enable controlled metering in automated compounding.
- Emulsion:Water-dispersed systems reduce VOC emissions for interior coating applications.
Liquid leads on scale; gel leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and polymer engineers concentrate in Germany's industrial clusters, Japan's chemical corridors, and China's coastal manufacturing zones. These talent pools anchor regional production capabilities and determine where specialty resin development occurs.
United States
Gulf Coast refineries drive demand for hybrid vinyl ester-urethane systems in sulfuric acid storage tanks. EPA National Emission Standards for Hazardous Air Pollutants compel reformulation toward reduced-styrene liquid resins. Houston and Beaumont host the principal formulation facilities serving petrochemical infrastructure.
Germany
Automotive and aerospace OEMs specify phenolic vinyl esters for smoke toxicity compliance in interior components. EU Green Deal industrial emissions mandates accelerate validation of bio-based methacrylic acid feedstocks. The Cologne-Düsseldorf corridor houses specialized polymer research centers advancing novolac synthesis.
China
Coastal power plants and chemical processing expansions consume novolac grades for flue gas desulfurization scrubbers. MEE emissions controls mandate closed-loop manufacturing and vapor recovery systems in Ningbo and Shanghai. Domestic producers localize production to reduce import dependency and logistics emissions.
Japan
Shipbuilders and electronics manufacturers drive specification-grade demand for brominated and phenolic variants. METI industrial standards govern flame-retardant certification for electrical enclosure applications. The Osaka-Kobe manufacturing belt concentrates gelcoat formulation expertise for marine coating warranties.
India
Paradip and Hazira port expansions require corrosion-resistant materials for chemical storage tanks and marine pilings. BIS standards for construction chemicals influence resin qualification protocols for infrastructure projects. Gujarat's chemical processing corridor attracts formulation investments serving water treatment and power generation sectors.
Global Vinyl Ester Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct capability tiers. Integrated petrochemical groups control feedstock costs through backward integration into bisphenol A and methacrylic acid supply. Specialty resin houses differentiate through formulated gelcoat systems and application-specific technical service. The competitive terrain rewards either scale economies in commodity grades or formulation intimacy in specification-driven segments. M&A activity concentrates among mid-cap European and Asian players seeking geographic coverage, while technology licensing agreements proliferate for lower-styrene and bio-based chemistries.
Within the integrated petrochemical tier, INEOS exemplifies feedstock-backed supply stability across European and Asian markets. Swancor occupies a position among specialized resin architects focused on novolac and flame-retardant grades. Scott Bader Company Ltd anchors the formulated systems segment through gelcoat warranties extending to marine and infrastructure end-users.
| Leading Market Players |
|---|
| Interplastic Corporation |
| SHOWA DENKO K.K |
| AOC |
| DIC CORPORATION |
| Swancor |
| INEOS |
| Scott Bader Company Ltd |
| Ashland |
| Polynt |
| Others |
Supply & Pricing Matrix
EU Green Deal industrial emissions mandates gate qualified supply and premium-tier pricing access by compelling reformulation investments that only integrated producers can amortize across volume bases. Buyers seeking 15-year marine coating warranties or aerospace smoke toxicity certification face supplier pools narrowed to those with REACH-registered lower-styrene alternatives and bio-based feedstock validation.
Pricing Analysis
Bundled formulation-and-warranty contracts now separate from unbundled commodity resin supply as Hyundai Heavy Industries and Imabari Shipbuilding transfer performance liability to suppliers. Price differentiation hinges on certification tier—REACH-registered novolac grades command substantial premia over standard bisphenol A—and volume scale, with spot purchasers in marine fabrication facing cost compression from styrene monomer regulatory compliance burdens. Margins are tightening in commodity marine coatings due to EPA National Emission Standards enforcement, while chemical processing and aerospace segments show lowest price sensitivity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns serving fabrication clusters. Manufacturing concentrates in Germany, China, and the United States, with domestic production localization accelerating in Ningbo and Shanghai under MEE emissions controls. Feedstock supply draws from petrochemical cracking economics in the US Gulf Coast and Rotterdam clusters, creating bisphenol A and methacrylic acid cost volatility. Single-source vulnerability runs through integrated petrochemical groups controlling upstream inputs. Distribution runs through formulated systems houses providing technical service and application engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vinyl ester market represents a late-cycle quality story as procurement authority concentrates with asset owners demanding validated performance warranties rather than price-driven spot purchasing. Novolac and phenolic specifications for flue gas desulfurization and aerospace interiors are displacing commodity-grade volumes.
For Market Incumbents: Anchor competitive position through backward integration into bisphenol A and methacrylic acid supply to stabilize formulation margins against feedstock volatility. Invest in REACH-registered lower-styrene alternatives and bio-based feedstock certification to defend against specialty resin houses capturing specification-grade demand. Prioritize technical service capabilities supporting 15-year marine coating warranties.
For New Entrants and Emerging Players: Formulation chemists in India's Gujarat corridor offer partnership pathways into coastal infrastructure and water treatment segments where BIS standards are still evolving. Target novolac production for China's flue gas desulfurization expansions as domestic localization creates white space for technology licensing. Pursue joint development agreements with port authorities at Paradip and Hazira specifying corrosion-resistant tankage materials.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap European and Asian specialty resin houses because geographic coverage gaps and fragmented formulation expertise create accretive combination opportunities. The 5-10 year viability window favors platforms with REACH dossiers and established aerospace certification. Monitor EU carbon border adjustment mechanism implementation as inflection indicator for bio-based feedstock premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive bisphenol A supply insulates INEOS from Rotterdam cluster feedstock volatility. |
| Green Manufacturing Transition | Bio-based methacrylic acid from Brazilian sugarcane enables EU Green Deal compliance certification. |
| Long-term Supply Agreement | Hyundai Heavy Industries unbundles 15-year coating warranties from hull fabrication contracts. |
| Joint Venture | Domestic novolac production partnerships in Ningbo reduce import logistics under MEE controls. |
| Acquisition of Specialist Firm | Mid-cap European resin houses target gelcoat formulation expertise for infrastructure warranties. |
Research Methodology
Multiple input streams—primary interviews with resin plant managers, procurement leads at marine OEMs, and technical R&D directors; secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings; plus regulatory dossier review—were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against expert panel inputs across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry application, fabrication form factor, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating offshore wind installation pipelines, flue gas desulfurization capacity additions, and shipbuilding order backlogs as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation, styrene monomer regulatory evolution, and bio-based feedstock certification pathway clarity. Outputs reflect documented assumptions regarding MEE enforcement timelines and REACH authorization streamlining. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market