
 Wood Coating Resins Market | 2026-2036
Wood Coating Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Coating Resins Market Intelligence
The displacement of traditional solvent-based formulations by water-based and UV-cured alternatives is restructuring product economics and performance benchmarks. Akzo Nobel N.V. leverages its extensive R&D in low-VOC technologies to capture premium segments. The Sherwin-Williams Company competes on its vast distribution network and brand recognition in architectural and industrial applications, while BASF SE differentiates through its broad portfolio of advanced polymer chemistries.
Wood coating resins are polymers engineered to form protective and decorative films on wooden substrates. These binders, including acrylic and polyurethane types, are formulated to deliver specific performance characteristics such as hardness, UV stability, and chemical resistance. Polyurethane resins command a significant share for applications like flooring that demand high durability. In parallel, water-based technology is gaining traction across furniture and cabinetry due to environmental compliance.
Regulatory mandates from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) are central to market evolution. These bodies enforce strict limits on volatile organic compounds (VOCs), directly influencing resin formulation choices. Compliance with standards like China's GB standards for coatings is also critical for market access. Decisions on investment in bio-based and UV-cured resin systems will determine future competitive positioning.
Market Dynamics
The fundamental market dynamic is the regulatory-driven substitution of solvent-based resins with lower-VOC alternatives like water-based and UV-cured systems. This transition is reshaping formulation costs, application processes, and performance standards across the wood coatings value chain, directly influenced by mandates from the EPA and ECHA.
Growth Catalysts
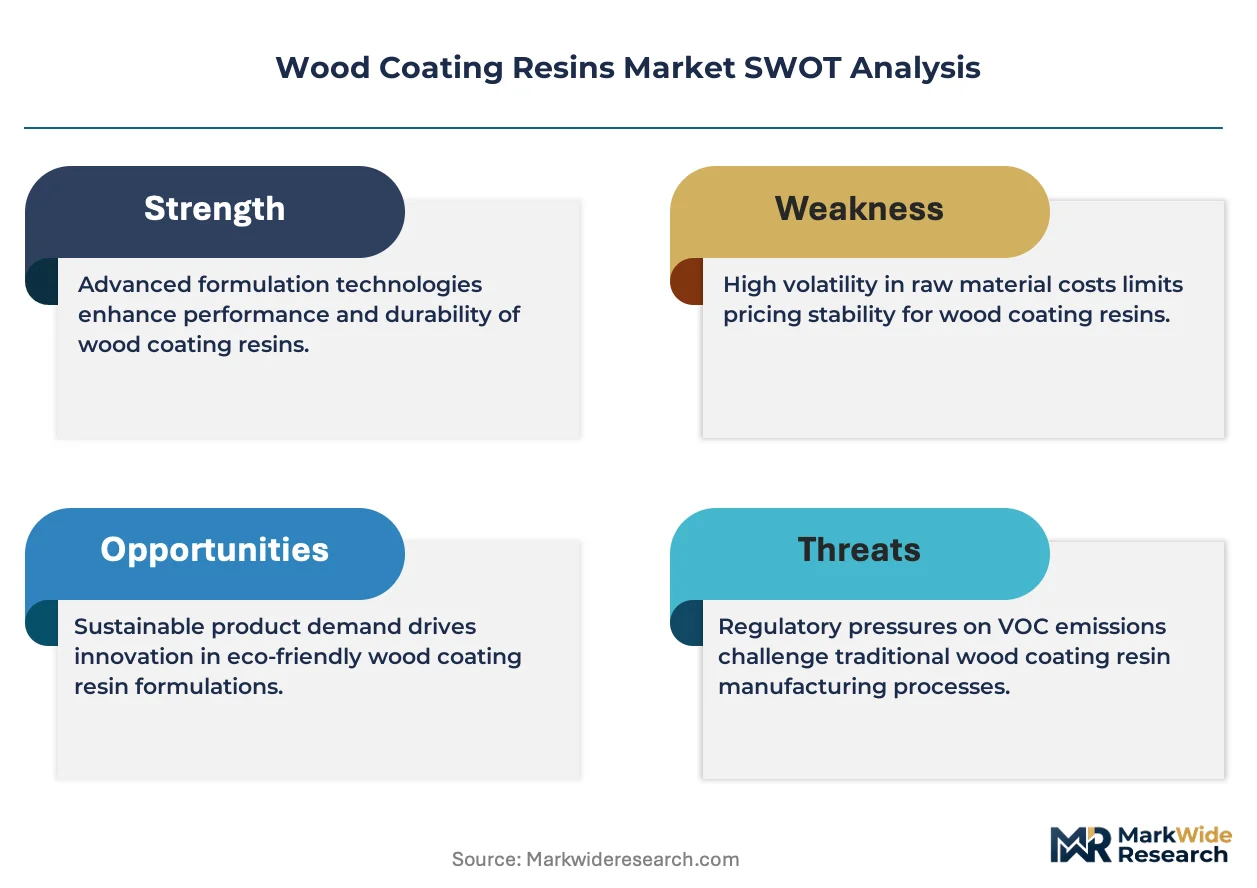
- Regulatory Mandates:Stringent environmental regulations, including China's GB standards for coatings and the EU's REACH framework, are compelling manufacturers to adopt compliant resin technologies, particularly in the export-oriented furniture industry.
- Construction Sector Expansion:A rising volume of residential and commercial construction projects globally fuels demand for durable wood coatings for flooring, decking, and structural timber, where polyurethane and acrylic resins offer necessary protection.
- Aesthetic & Performance Demands:The furniture and cabinetry sectors require finishes that offer superior aesthetics, scratch resistance, and chemical stability, driving the specification of advanced polyurethane and UV-cured resin systems.
Market Restraints
- Raw Material Volatility:The pricing and availability of key petrochemical feedstocks, such as acrylic and vinyl monomers used in many resin formulations, are subject to significant volatility, impacting production costs and margin stability.
- Performance Trade-Offs:While improving, some water-based resin formulations still exhibit performance gaps compared to solvent-based counterparts, such as longer cure times or lower hardness, which can limit adoption in demanding industrial applications.
- Threat of Material Substitution:The increasing use of non-wood materials like metal, plastic composites, and laminates in furniture, flooring, and cabinetry reduces the total addressable market for wood-specific coating resins.
Strategic Opportunities
- Bio-Based Resin Development:There is a significant opportunity in formulating bio-based resins from renewable sources like plant oils and starches, which aligns with corporate sustainability goals and appeals to environmentally conscious consumers.
- UV-Cured Systems in Industrial Finishing:Expanding the application of UV-cured resins beyond niche uses into mainstream industrial wood finishing for items like cabinetry and furniture offers major productivity gains due to rapid curing speeds.
- Geographic Expansion in Southeast Asia:Furniture manufacturing hubs in countries like Vietnam and Indonesia represent underpenetrated markets for high-performance, low-VOC coating resins as their export activities increase.
Industry Challenges
- Formulation Complexity:Reformulating coating systems to meet disparate and evolving VOC regulations from bodies like the EPA and ECHA requires significant R&D investment and technical expertise, creating a barrier for smaller producers.
- Specialty Additive Sourcing:Securing a consistent supply of specialized performance additives, such as coalescing agents and rheology modifiers essential for advanced water-based systems, presents a significant supply chain challenge.
- Application Skill Gap:The transition to water-based and UV-cured technologies requires applicators to develop new skills and invest in updated equipment, slowing adoption where training and capital are limited.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Coating Resins Market |
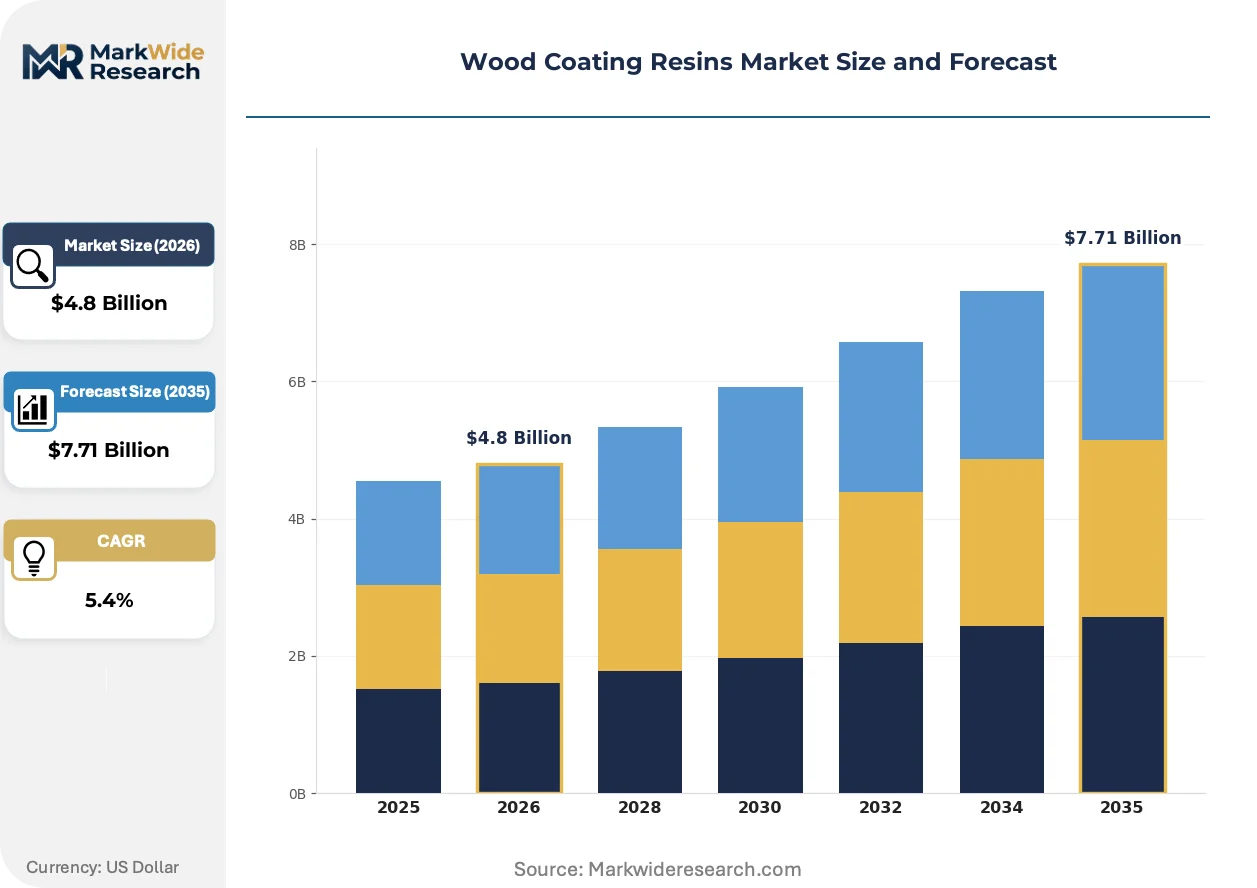
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Nitrocellulose Application: Furniture, Flooring, Cabinets, Door, Moldings Technology: Water-Based, Solvent-Based, UV-Cured, Powder Coating End User: Construction, Interior Design, Manufacturing, DIY |
| Companies Covered | BASF SE, Berger Paints India Limited, Akzo Nobel N.V., Axalta Coating Systems, LLC, RPM International Inc., PPG Industries, Inc., Asian Paints Limited, Kansai Paint Co., Ltd., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Coating Resins Market Strategic Shifts & Innovations
The industry's evolution is defined by the dual pursuit of environmental compliance and enhanced coating performance. Innovations are focused on creating resins that not only meet strict VOC limits but also deliver superior durability, faster processing times, and improved aesthetics for wooden substrates.
UV-cured resin technology offers nearly instantaneous curing when exposed to ultraviolet light, eliminating the need for long drying times. Industrial manufacturers of flooring, cabinetry, and flat-pack furniture are adopting it to increase factory throughput. This technology is consolidating its position in high-volume automated finishing lines, compressing production cycles and lowering energy costs versus traditional thermal curing.
The European Union's REACH regulation imposes stringent registration and evaluation criteria on all chemical substances, including the monomers and isocyanates used in resin synthesis. This directly governs raw material selection, compelling formulators to phase out certain chemicals of high concern. Polyurethane and epoxy resin segments are most affected, prompting R&D into safer, compliant chemistries to ensure continued market access in Europe.
A distinct shift in buyer behavior is the growing preference for finishes backed by third-party environmental certifications. This is altering traditional procurement criteria, as architects and large furniture brands now prioritize products with credentials like GREENGUARD or other validated low-emission labels. This demand pattern is most visible in North America and Europe, especially for products used in institutional and residential interior applications.
Wood Coating Resins Market Segmentation
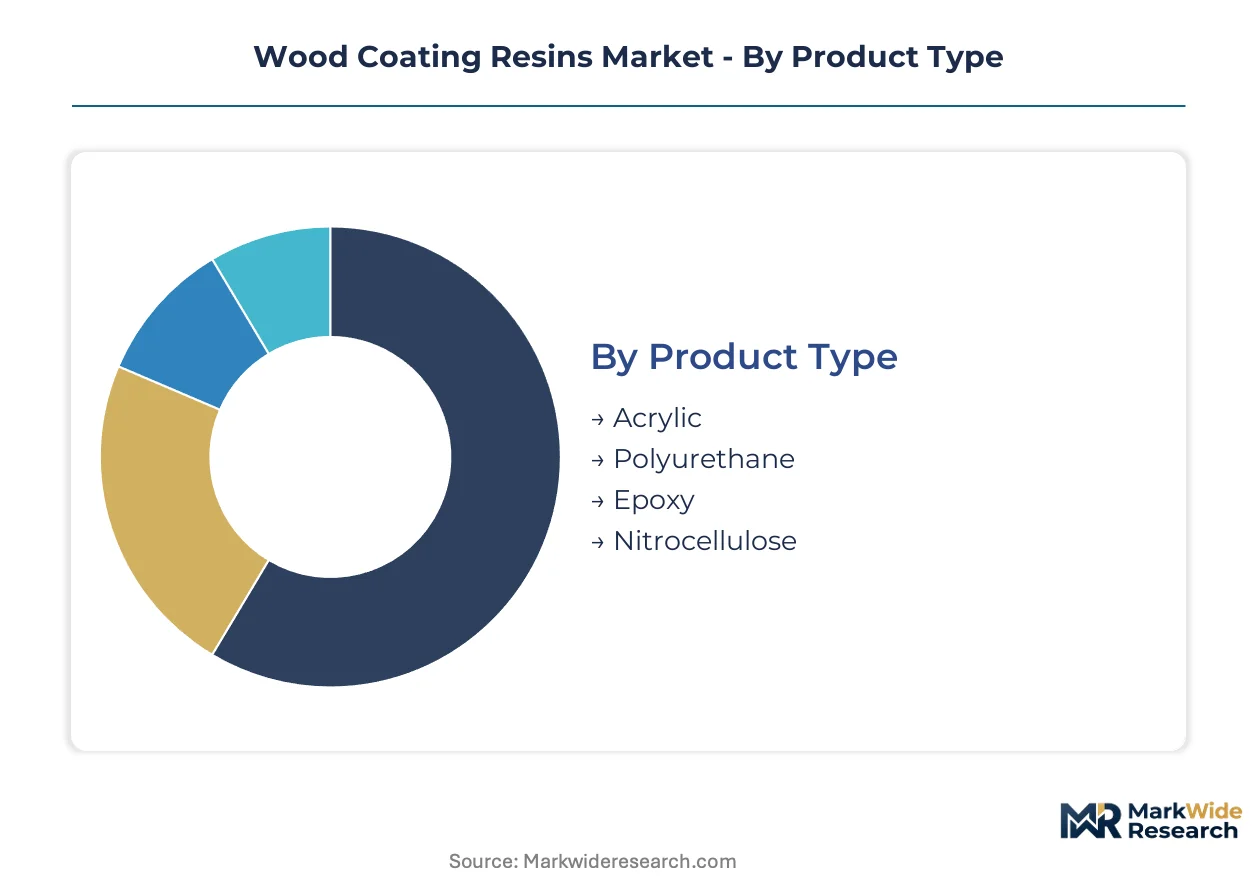
The Wood Coating Resins market fragments into distinct categories, reflecting diverse material compositions, application methods, and end-user requirements. Understanding these segments is crucial for identifying areas of concentrated demand and specific regulatory compliance pathways. Each segment addresses unique performance needs and market dynamics.
Product Type:
Product type classifications often dictate the specific regulatory approvals required for market access, with certain chemistries facing more stringent evaluation by bodies like ECHA for their environmental impact.
- Acrylic:These resins offer excellent UV resistance and color retention, making them suitable for exterior wood applications and clear topcoats. Demand is concentrating in Europe, driven by stringent VOC regulations and the need for durable, weather-resistant finishes.
- Polyurethane:Known for superior hardness, abrasion resistance, and chemical stability, polyurethane resins are essential for high-traffic surfaces like wooden flooring and countertops. Manufacturers in China prioritize these resins for export-oriented furniture requiring robust protective layers.
- Epoxy:Epoxy resins provide exceptional adhesion and chemical resistance, often used as primers or sealers.
- Nitrocellulose:Traditional nitrocellulose lacquers offer fast drying and good aesthetics, primarily for furniture finishing.
Leading the category by volume: Polyurethane. Growing fastest: Acrylic.
Application:
Application segments are defined by the end-use article, which directly influences the required performance attributes and aesthetic criteria for wood coating resins.
- Furniture:This segment demands resins offering superior aesthetics, scratch resistance, and chemical stability for various interior and exterior pieces. Manufacturers in Southeast Asia are increasingly specifying advanced UV-cured systems for faster production cycles and enhanced surface properties.
- Flooring:Coatings for wooden flooring require extreme durability, abrasion resistance, and chemical resistance to withstand heavy foot traffic and cleaning agents. North American construction projects frequently specify polyurethane-based resins for their long-term protective qualities.
- Cabinets:Resins for cabinetry must provide good stain resistance and a smooth, easy-to-clean finish.
- Door:Coatings for doors need to balance weather resistance for exterior with aesthetic appeal for interior.
- Moldings:This segment utilizes resins offering good adhesion and flexibility to decorative wood trim.
Furniture applications consistently drive the largest share of resin consumption. Flooring applications show the steepest expansion trajectory.
Technology:
Technology types delineate the formulation approach and curing mechanisms, directly influencing application processes, environmental footprint, and production line efficiency.
- Water-Based:These systems use water as the primary solvent, significantly reducing VOC emissions and aligning with strict environmental regulations like those from the EPA and ECHA. Adoption is expanding across furniture and cabinetry sectors due to environmental compliance and improved performance.
- UV-Cured:UV-cured resins polymerize rapidly under ultraviolet light, enabling instantaneous drying and high throughput on industrial finishing lines. This technology is gaining share in flat-panel furniture and flooring manufacturing due to major productivity gains.
- Solvent-Based:Traditional solvent-based resins offer excellent film build but face pressure from VOC regulations.
- Powder Coating:Powder coatings for wood provide durable, VOC-free finishes, primarily for flat-panel applications.
Water-based technologies command the largest market volume. UV-cured systems are gaining share fastest among industrial users.
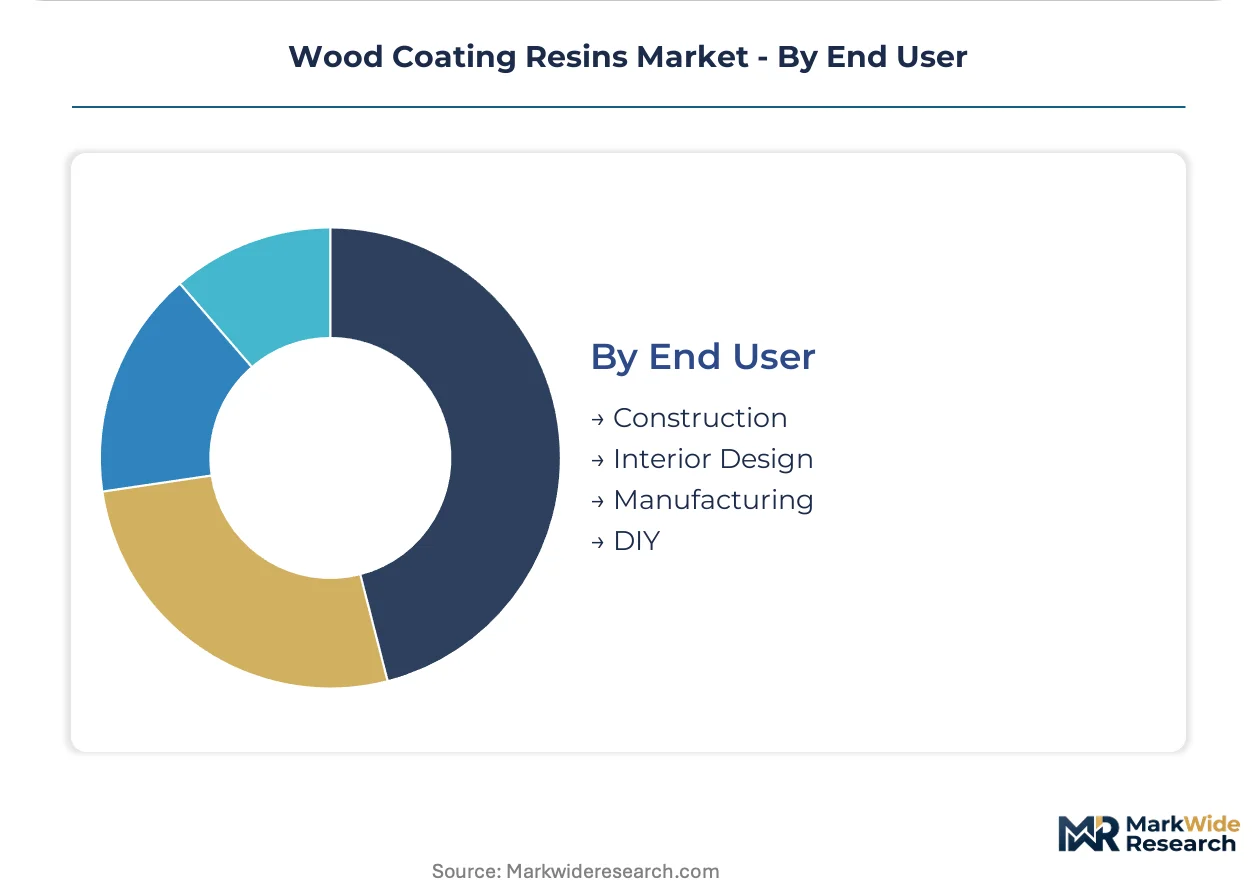
End User:
End-user segments categorize the primary consumer of wood coating resins, each with distinct volume requirements, purchasing patterns, and performance expectations.
- Construction:This segment encompasses large-scale residential and commercial projects requiring durable coatings for structural timber, flooring, and interior finishes. Demand in China is particularly robust, driven by its expansive real estate development and infrastructure investments.
- Manufacturing:Industrial manufacturers of furniture, cabinets, and other wood products utilize resins for high-volume, automated finishing processes. European furniture producers prioritize resins that meet stringent performance and environmental criteria for export markets.
- Interior Design:Professionals specify wood coatings for custom furniture and architectural elements, emphasizing aesthetics.
- DIY:Do-It-Yourself consumers purchase resins for home improvement, prioritizing ease of application and availability.
Manufacturing end-users represent the largest consumption segment. Construction end-users exhibit the most significant growth in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the Wood Coating Resins Market is particularly pronounced across key manufacturing and construction hubs globally. Stringent environmental regulations and consumer preferences for durable, aesthetic finishes influence regional growth trajectories. This market dynamic drives innovation in low-VOC and high-performance resin systems.
China
Demand for polyurethane resins in China is high, driven by its large-scale construction and export-oriented furniture manufacturing. China's GB standards for coatings compel local manufacturers to adopt compliant, lower-VOC formulations. The Pearl River Delta region sees significant investment in UV-cured systems for high-volume flat-pack furniture production, enhancing throughput.
United States
Residential and commercial construction projects consistently fuel demand for durable wood coatings, particularly for flooring and structural timber. The US Environmental Protection Agency (EPA) mandates drive widespread adoption of water-based and low-VOC alternatives. North American construction hubs, such as in Texas, frequently specify advanced acrylic and polyurethane resins for their protective qualities.
Germany
Aesthetic and performance demands from the furniture and cabinetry sectors boost specification of advanced polyurethane and UV-cured resins. The EU's REACH framework directly influences resin formulation choices and raw material selection for market access. Manufacturers in Baden-Württemberg focus on R&D for compliant, high-performance wood coating solutions to serve demanding European markets.
Vietnam
Furniture manufacturing hubs in Vietnam represent underpenetrated markets for high-performance, low-VOC coating resins. Vietnamese manufacturers are increasingly adopting advanced water-based systems to meet stringent export market requirements. Production facilities in Binh Duong province are investing in modern finishing lines for cabinetry and furniture, driving efficiency gains.
Wood Coating Resins Market Key Industry Players
Strategic partnerships and portfolio diversification dominate the current competitive landscape, characterized by a tiered structure. Large multinational chemical companies form the top tier, while specialized regional players occupy niche segments. The market sees intense competition for advanced low-VOC technologies and sustainable resin formulations. Geographic expansion into high-growth regions and targeted acquisitions are also prominent competitive moves.
Leading global players like Akzo Nobel N.V. and The Sherwin-Williams Company anchor the premium segment, leveraging extensive R&D in low-VOC technologies and vast distribution networks. BASF SE, a German-based chemical giant, exemplifies a diversified polymer chemistry provider, differentiating through its broad portfolio of advanced materials and sustainable solutions. These companies consistently invest in next-generation resin systems to meet evolving regulatory standards and performance benchmarks across various applications. Their strategies often involve developing bio-based and UV-cured alternatives to capture future market share, particularly in industrial finishing.
| Leading Market Players |
|---|
| BASF SE |
| Berger Paints India Limited |
| Akzo Nobel N.V. |
| Axalta Coating Systems, LLC |
| RPM International Inc. |
| PPG Industries, Inc. |
| Asian Paints Limited |
| Kansai Paint Co., Ltd. |
| The Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
Acrylic monomer prices, for example, directly influence the cost structure of acrylic resins, creating distinct pricing tiers for performance-grade and commodity-grade products. This volatility then cascades through the value chain to end-users.
Pricing Analysis
Volume sales of standard water-based resins often yield tighter margins, while specialized UV-cured systems command premium pricing due to performance. The market operates on a contract-based long-term offtake model for large industrial buyers, supplemented by spot pricing for smaller orders. Performance characteristics like UV stability and scratch resistance, alongside environmental certifications such as GREENGUARD, drive price differentiation. Pricing softness in commodity solvent-based resins stems from regulatory displacement and competition from lower-VOC alternatives. DIY consumers are most price-sensitive, while large furniture manufacturers prioritize performance and compliance over lowest cost.
Supply Chain Analysis
Skilled labor availability in key manufacturing hubs like China's Pearl River Delta and Vietnam's Binh Duong province impacts production efficiency for complex resin formulations. Production of key resin intermediates concentrates in China and Germany, impacting global availability. The supply chain relies heavily on petrochemical feedstocks like acrylic monomers and isocyanates, alongside specialized performance additives. Raw material volatility represents a significant structural risk, affecting production costs and margin stability. Distribution runs through a network of specialized chemical distributors and direct sales to large industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood coating resins market functions as a supply-constrained environment. Limited global capacity for high-performance UV-cured resin photoinitiators props up pricing for advanced systems.
For Market Incumbents: Extend R&D investments into bio-based resin chemistries to counter the threat of petrochemical feedstock volatility. Acquire niche technology firms specializing in advanced water-based or UV-cured additives to secure intellectual property. Strengthen distribution networks in high-growth Southeast Asian markets like Vietnam to mitigate regional competition. Invest in applicator training programs to accelerate adoption of new low-VOC technologies, addressing the application skill gap.
For New Entrants and Emerging Players: Online B2B marketplaces offer a direct route to penetrate the fragmented DIY and small-to-medium enterprise (SME) segments. Target the underpenetrated furniture manufacturing hubs in Indonesia with localized, cost-effective water-based formulations. Develop modular resin systems that simplify formulation complexity for smaller manufacturers. Leverage social media platforms to showcase application benefits and environmental compliance for specific product lines.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term growth in sustainable chemistry. Focus on mid-cap resin manufacturers with strong R&D in bio-based or UV-cured technologies. Look for targets that possess established market access in high-growth regions like China or Southeast Asia. A significant shift in regulatory enforcement or a breakthrough in bio-based resin performance would indicate an inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for UV-Cured Resins | Supports demand from automated industrial finishing lines in furniture manufacturing. |
| R&D in Bio-Based Feedstocks | Addresses raw material volatility and aligns with corporate sustainability goals. |
| Strategic Partnership with Additive Suppliers | Secures consistent supply of specialized performance additives for water-based systems. |
| Geographic Expansion into Vietnam | Captures demand from export-oriented furniture manufacturers seeking compliant low-VOC coatings. |
| Investment in Applicator Training | Accelerates adoption of new water-based and UV-cured technologies, bridging the skill gap. |
Research Approach
Industry association reports, customs trade data, and company financial filings formed the secondary backbone, validated through primary interviews. Discussions with R&D directors, procurement managers, plant operators, and distribution channel partners provided qualitative insights. This approach ensured a comprehensive understanding of market dynamics, integrating both top-down and bottom-up perspectives. Data triangulation across these sources enhanced accuracy and reliability.
Historical trendline analysis established baseline growth rates, projected across the analysis window using econometric models. The framework segmented the market by product type, application, technology, end-user, and regional regulatory compliance. CAGRs were derived by integrating supply-side capacity expansions with demand-side growth catalysts. Key inputs included construction spending forecasts and furniture export volumes.
The model holds under current regulatory stability and predictable raw material supply; deviation in global trade policies or petrochemical prices would shift projections. Forecasts reflect these assumptions, acknowledging inherent market uncertainties. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Bio-Polybutadiene Market