
 Smart Textiles for Military Market | 2026-2036
Smart Textiles for Military Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Textiles for Military Market Analysis
Market Context
Defense contractors are collapsing the traditional procurement gap between frontline military personnel and research institutions as end users. BAE Systems plc leverages its UK-US transatlantic defense relationships to sustain integrated electronic textile programs for coalition forces. DuPont de Nemours Inc. anchors its position through Kevlar-based conductive substrates that dominate ballistic-smart hybrid fabrics. Schoeller Textil AG competes via alpine-to-tactical technology transfer, extending its civilian soft-shell expertise into military environmental adaptation systems.
Technical Definition and Segment Structure
Smart textiles for military applications are engineered fabrics embedding conductive fibers, microelectronics, and sensor arrays directly into woven or non-woven substrates to enable real-time physiological monitoring, encrypted tactical communication, and adaptive thermal regulation under combat conditions. Body Armor represents the most mature revenue pool, while Communication Fabrics and Monitoring Fabrics capture the fastest expansion as wearable sensors and electrically conductive fabrics converge into unified soldier-worn networks. Energy Harvesting within the technology dimension remains pre-commercial but holds the highest margin potential for defense contractors seeking to eliminate battery dependency in extended field operations.
Regulatory Frame and Outlook
The US Army's Natick Soldier Research Center, the EU's CE marking framework under the MDR, and NATO's Standardization Office collectively dictate electromagnetic compatibility, biocompatibility, and interoperability thresholds for field-deployable smart textiles. FDA oversight applies where health monitoring fabrics cross into medical device classification, creating dual-certification burdens that favor established players with regulatory infrastructure. Stakeholders must monitor whether emerging spectrum allocation rules from the FCC and equivalent bodies will mandate frequency-hopping capabilities in all tactical communication fabrics, fundamentally altering R&D prioritization across supplier tiers.
Market Dynamics
Electromagnetic spectrum warfare requirements are collapsing the traditional boundary between textile procurement and electronic systems certification, forcing defense contractors to restructure R&D pipelines around dual-use electromagnetic compatibility standards before fabric production begins.
Growth Catalysts
- SOCOM Modernization Mandates:US Special Operations Command budgets prioritize integrated soldier-worn sensor networks, creating immediate procurement pull for conductive fabric systems with embedded physiological monitoring.
- EU Cyber Resilience Act:The European Union's mandatory cybersecurity certification for connected devices is accelerating textile-electronics integration timelines, as military uniforms with data transmission capabilities fall under scope.
- Kevlar-Conductive Hybridization:Advances in ballistic fiber substrates that simultaneously carry electrical signals enable single-layer protection-communication fabrics, reducing weight burden for dismounted infantry.
Market Restraints
- Silver Nanowire Cost Volatility:Conductive textile production depends on silver-based nanomaterials subject to precious metal price swings, compressing margins for mid-tier suppliers without long-term commodity hedging.
- Natick Certification Bottleneck:The US Army's Natick Soldier Research Center maintains sole authority over field-deployable smart textile validation, creating single-point-of-failure delays for multi-national coalition procurement.
- Legacy Radio Substitution:Existing tactical communication hardware represents sunk investment across NATO forces, slowing displacement rates even where fabric-integrated alternatives demonstrate superior spectral efficiency.
Strategic Opportunities
- Polish Defense Modernization:Poland's accelerated military spending under its 2035 technical modernization plan includes dedicated lines for soldier systems, creating entry points for smart textile suppliers outside established US-German supply chains.
- FDA Dual-Classification Pathway:Health monitoring fabrics that achieve medical device clearance unlock parallel civilian first-responder markets, expanding addressable demand beyond defense-only procurement cycles.
- Photovoltaic-Textile Convergence:Integration of flexible solar harvesting layers with conductive fabric backbones addresses the battery dependency bottleneck in extended special reconnaissance missions.
Industry Challenges
- Electromagnetic Compatibility Engineering Talent:The intersection of textile manufacturing and RF engineering requires specialists scarce in traditional defense labor pools, forcing contractors to poach from commercial telecommunications.
- CE-MDR Dual Certification Burden:European market entry demands simultaneous compliance with CE marking for electronics and MDR for biocompatible skin-contact materials, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Textiles for Military Market |
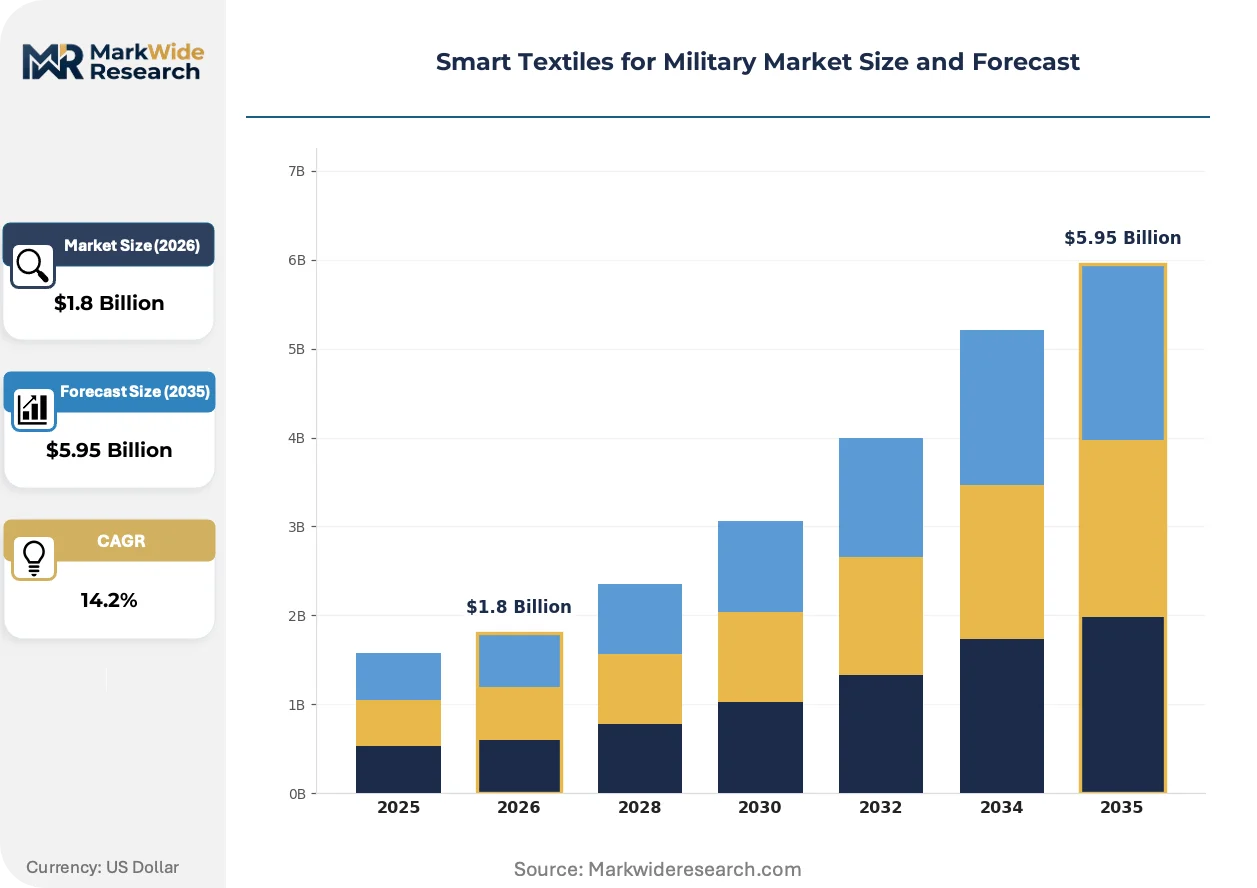
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Communication Fabrics, Monitoring Fabrics, Smart Insulation Technology: Wearable Sensors, Electrically Conductive Fabrics, RFID Integration, Energy Harvesting Application: Surveillance, Health Monitoring, Environmental Adaptation, Tactical Communication End User: Military Personnel, Defense Contractors, Research Institutions, Government Agencies |
| Companies Covered | Texas Instruments Inc., Advanced Fabric Technology LLC, BAE Systems plc, Sioen Industries NV, WL Gore & Associates Inc., DuPont de Nemours Inc., Schoeller Textil AG, Teijin Limited, TenCate Protective Fabrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Textiles for Military Market Emerging Trajectories
Active research programs across NATO defense ministries are compressing the gap between laboratory demonstration and field deployment for textile-integrated electronics, with particular urgency around power autonomy and spectral security.
Conductive polymer fiber architectures are fragmenting the traditional separation between ballistic protection layers and electronic infrastructure in combat uniforms. Special operations units in the United States and United Kingdom are piloting single-substrate garments that route encrypted data through Kevlar-based conductive pathways. This convergence is fragmenting supplier tiers, as pure-play textile manufacturers without in-house RF engineering capabilities lose access to prime contractor procurement channels.
REACH amendments targeting persistent organic pollutants in flame-retardant treatments are forcing reformulation of the chemical coatings that simultaneously provide thermal protection and electrical insulation in military fabrics. The European Chemicals Agency's substance restriction timeline is compressing R&D cycles for suppliers serving EU member state defense ministries. Body armor segments face the steepest compliance burden, as legacy halogenated flame retardants must be replaced without degrading dielectric properties.
Buyer concentration around Army Futures Command and SOCOM is compressing vendor qualification timelines from multi-year to sub-18-month cycles. Prime contractors are responding by pre-qualifying tier-two textile suppliers against anticipated specification releases rather than waiting for final RFP documentation. This behavioral shift is most pronounced in communication fabric procurement, where rapid spectral reallocation requirements demand supplier agility unmatched by traditional defense acquisition pacing.
Smart Textiles for Military Market Segmentation
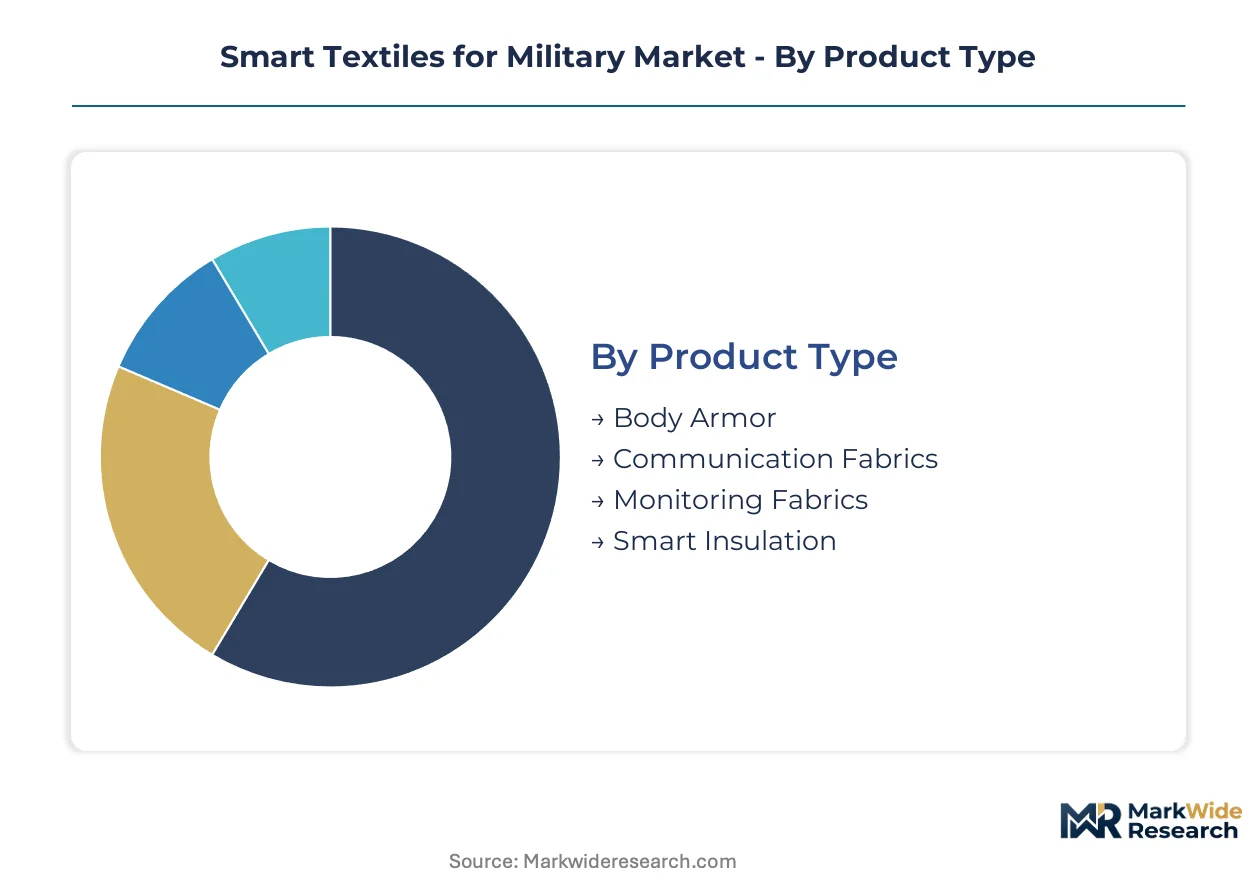
Smart textiles for military applications fragment across four intersecting dimensions that determine procurement pathways and certification burdens. Product type defines the hardware-software integration depth, while technology selection dictates electromagnetic compatibility requirements and supply chain concentration.
Product Type:
Margin pools concentrate in segments where ballistic protection converges with electronic infrastructure, creating premium pricing for single-substrate solutions.
- Body Armor:Kevlar-based conductive substrates integrate electrical pathways directly into ballistic fiber architectures. US Army Futures Command procurement prioritizes these hybrids for dismounted infantry modernization, though REACH amendments on flame-retardant coatings compress formulation timelines for EU-bound contracts.
- Communication Fabrics:Encrypted data transmission through woven conductive arrays enables spectral efficiency gains over legacy radio hardware. SOCOM validation cycles for these fabrics have compressed below 18 months, accelerating vendor qualification demands.
- Monitoring Fabrics:Real-time physiological tracking via embedded sensor arrays.
- Smart Insulation:Adaptive thermal regulation responding to environmental conditions.
Body Armor holds installed capacity. Communication Fabrics is rotating up the share rankings.
Technology:
Technology selection determines whether suppliers compete on materials science or RF engineering capabilities, fragmenting the vendor landscape.
- Wearable Sensors:Miniaturized biometric capture devices embedded at fiber level. FDA dual-classification pathways for health-monitoring variants unlock parallel first-responder markets beyond defense procurement.
- Electrically Conductive Fabrics:Silver nanowire and conductive polymer architectures enabling signal transmission. Precious metal price volatility forces mid-tier suppliers toward long-term commodity hedging or alternative conductive formulations.
- RFID Integration:Asset tracking and personnel identification through woven transponders.
- Energy Harvesting:Photovoltaic-textile convergence addressing battery dependency in extended reconnaissance.
Wearable Sensors command premium pricing. Energy Harvesting is climbing the fastest as power autonomy becomes mission-critical.
Application:
Application segmentation maps directly to military operational requirements and corresponding certification authorities.
- Surveillance:Textile-integrated sensing for signature management and detection. NATO Standardization Office protocols govern electromagnetic emissions, creating interoperability mandates across coalition forces.
- Health Monitoring:Continuous vital signs transmission for casualty prevention. EU Cyber Resilience Act certification now applies where data transmission capabilities cross into connected device classification.
- Environmental Adaptation:Temperature and moisture-responsive fabric properties.
- Tactical Communication:Encrypted voice and data through garment-integrated networks.
Surveillance dominates current procurement volumes. Health Monitoring is gaining share fastest as casualty reduction becomes a measurable operational metric.
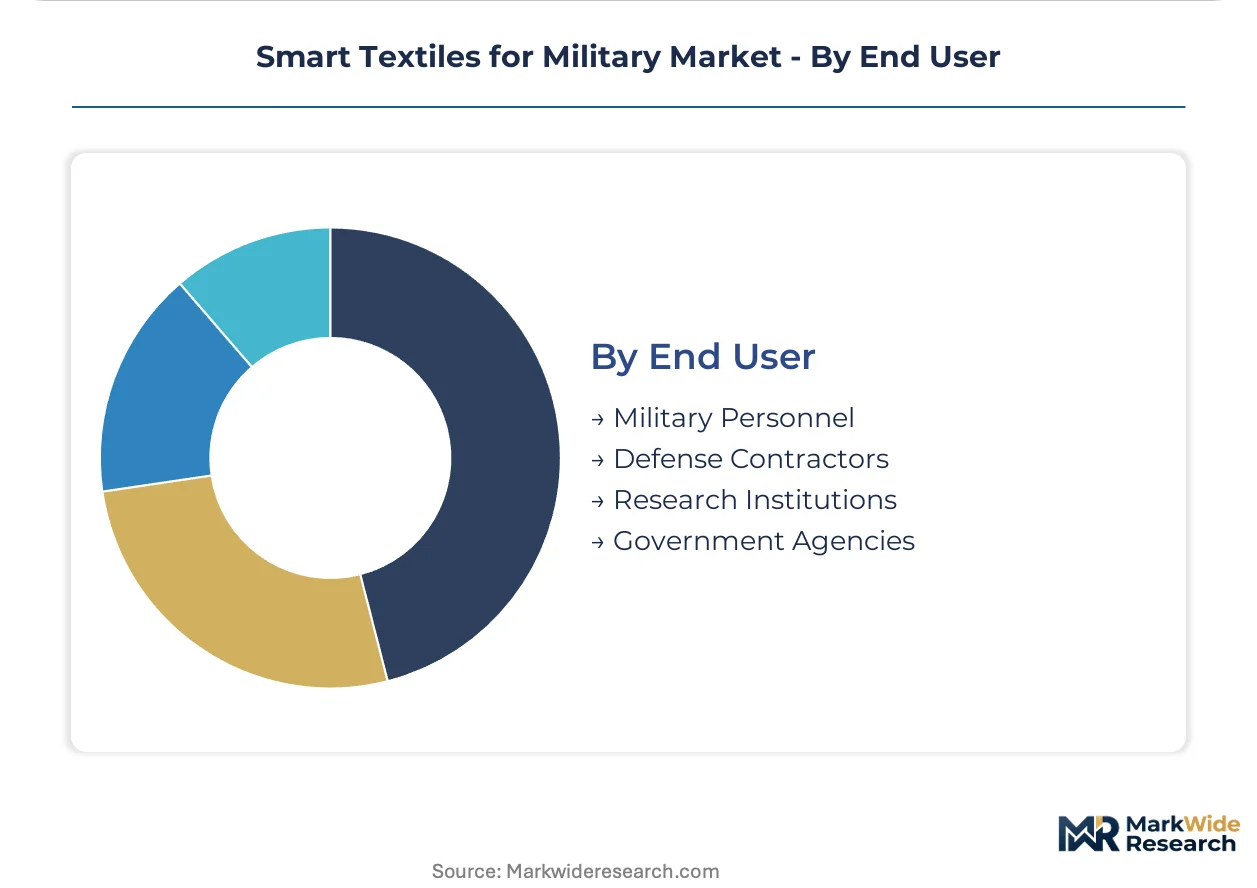
End User:
End user concentration determines pricing power and contract structure, with direct military procurement favoring established primes over emerging specialists.
- Military Personnel:Frontline combat uniforms with integrated sensor-communication- protection layers. Natick Soldier Research Center maintains sole US validation authority, creating bottleneck risks for multi-national suppliers.
- Defense Contractors:Prime-tier systems integrators sourcing textile subcomponents. BAE Systems and tier-one primes are collapsing traditional procurement gaps by pre-qualifying suppliers against anticipated specifications.
- Research Institutions:Developmental contracts for pre-commercial technologies.
- Government Agencies:Standards-setting and certification oversight roles.
Military Personnel represents the anchor demand pool. Defense Contractors are rotating up the share rankings as prime-tier integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transatlantic fiber-optic cable networks and NATO's integrated air defense infrastructure underwrite the United States' and Germany's dominant positions in military smart textile development and procurement coordination.
United States
Army Futures Command and SOCOM procurement cycles now compress below 18 months for communication fabric validation. The Natick Soldier Research Center maintains sole authority over field-deployable smart textile certification. Boston's Route 128 corridor hosts concentrated RF engineering talent pools that defense contractors actively recruit for electromagnetic compatibility programs.
Germany
Bundeswehr technical modernization prioritizes soldier systems with integrated sensor networks under the 2035 capability roadmap. REACH amendments from the European Chemicals Agency force reformulation of flame-retardant coatings without degrading dielectric properties. Bavaria's technical textile cluster around Augsburg anchors conductive polymer R&D for alpine-to-tactical technology transfer.
United Kingdom
UK Special Forces procurement channels accelerate adoption of single-substrate protection-communication garments. Ministry of Defence electronics certification requirements align with NATO Standardization Office electromagnetic compatibility protocols. Bristol's aerospace-defense corridor concentrates systems integrators collapsing traditional textile-electronics procurement boundaries.
Poland
Accelerated defense spending under the 2035 technical modernization plan creates entry points for suppliers outside established US-German supply chains. EU Cyber Resilience Act certification applies to connected military uniforms with data transmission capabilities. Warsaw's emerging defense industrial zone attracts tier-two textile suppliers seeking prime contractor pre-qualification.
Japan
Japan Self-Defense Forces modernization emphasizes lightweight soldier-worn networks for island defense scenarios. METI standards coordination with US Natick protocols enables bilateral procurement alignment. Osaka-Kobe's technical textile basin specializes in conductive fiber architectures for extreme environmental adaptation.
Smart Textiles for Military Market Vendor Landscape
Listed leaders compete with private specialists across defense-electronics integration depth, creating a tiered structure where scale-driven primes face agile technology specialists. The vendor base concentrates around three strategic archetypes: systems integrators with transatlantic defense relationships, materials science anchors with conductive substrate expertise, and alpine-to-tactical technology transfer specialists. Dominant competitive moves include pre-qualification of tier-two suppliers against anticipated specification releases and backward integration into conductive fiber production to secure supply continuity.
Within the systems integrator tier, BAE Systems plc and Texas Instruments Inc. represent contrasting scale positions, with the former leveraging UK-US defense relationships and the latter anchoring semiconductor-to-textile integration pathways. Among materials specialists, DuPont de Nemours Inc. exemplifies the conductive substrate archetype through Kevlar-based hybridization expertise, while Schoeller Textil AG occupies the technology transfer position extending civilian soft-shell capabilities into military environmental adaptation systems.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Advanced Fabric Technology LLC |
| BAE Systems plc |
| Sioen Industries NV |
| WL Gore & Associates Inc. |
| DuPont de Nemours Inc. |
| Schoeller Textil AG |
| Teijin Limited |
| TenCate Protective Fabrics |
| Others |
Supply Flow & Price Mechanics
Eighteen-month validation cycles at the Natick Soldier Research Center compress procurement timelines while amplifying pricing power for pre-qualified suppliers, concentrating margin capture among defense primes with backward integration into conductive fiber production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers commanding spreads based on NATO electromagnetic compatibility certification and integrated ballistic-electronic performance. Price differentiation hinges on silver nanowire purity grades and volume scale commitments from Army Futures Command. Cost compression in standard tiers is intensifying because mid-tier suppliers lack long-term commodity hedging against precious metal volatility. Defense contractors show lowest price sensitivity due to mission-critical specifications, while tier-two textile suppliers face acute margin pressure.
Supply Chain Analysis
The United States and Germany anchor conductive polymer R&D and electromagnetic compatibility engineering, while Japan feeds specialized fiber architectures for extreme environmental adaptation. Raw material procurement draws from silver nanowire deposits, Kevlar ballistic substrates, and flame-retardant chemical coatings. Single-source vulnerability concentrates around the Natick certification bottleneck, where sole validation authority creates chokepoints for multi-national suppliers. Distribution runs through prime contractor systems integrators that pre-qualify tier-two textile suppliers against anticipated specification releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soldier-worn network interoperability is shifting procurement toward platform-ecosystem economics, where NATO Standardization Office protocols function as the coordinating layer binding previously siloed textile and electronics suppliers into unified vendor ecosystems.
For Market Incumbents: Consolidate backward integration into conductive fiber production to secure supply continuity against silver nanowire price volatility. Lock in pre-qualification status with Army Futures Command by investing in RF engineering talent pools concentrated around Boston's Route 128 corridor, defending against emerging specialists with alpine-to-tactical technology transfer capabilities.
For New Entrants and Emerging Players: FDA dual-classification fast-tracks for health monitoring fabrics unlock parallel civilian first-responder markets outside defense procurement cycles. Poland's accelerated defense spending under its 2035 technical modernization plan represents the most penetrable geography, with Warsaw's emerging defense industrial zone offering prime contractor pre-qualification pathways. Target entry through photovoltaic-textile convergence for extended reconnaissance power autonomy.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across energy harvesting sub-segments as photovoltaic-textile R&D demands specialized cleanroom fabrication. Long-term viability centers on acquisition targets with captive conductive polymer formulation capabilities and existing NATO electromagnetic compatibility certification infrastructure. Watch for FCC spectrum allocation rule shifts mandating frequency-hopping capabilities as the inflection signal altering R&D prioritization across supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Fiber Production | Captive silver nanowire supply insulates margins from precious metal volatility at mid-tier suppliers. |
| NATO Electromagnetic Compatibility Pre-Certification | Pre-qualification against anticipated specifications compresses vendor validation below 18-month cycles. |
| Photovoltaic-Textile Convergence R&D | Flexible solar harvesting layers address battery dependency in extended special reconnaissance missions. |
| EU Cyber Resilience Act Compliance Investment | Cybersecurity certification for connected military uniforms accelerates textile-electronics integration timelines. |
| RF Engineering Talent Acquisition Programs | Poaching from commercial telecommunications addresses scarcity at the textile-RF engineering intersection. |
Methodological Framework
Cross-validation between primary interviews with defense procurement officers and secondary validation through SEC 10-K filings, NATO Standardization Office protocol documents, and EU regulatory filings anchors the qualitative findings. Stakeholder input from program managers at Army Futures Command, electromagnetic compatibility engineers at prime contractors, textile R&D directors, and Natick Soldier Research Center certification specialists combines with bottom-up and top-down triangulation.
Sensitivity analysis around silver nanowire price volatility and certification timeline compression informs the analytical framework across the analysis window. Segmentation dimensions modeled include product type integration depth, technology electromagnetic compatibility requirements, application certification authorities, and end-user procurement concentration. CAGRs derive from demand-side forecasting validated against defense budget allocation trajectories and supply-side capacity buildout tracking.
Underlying assumptions cover NATO interoperability mandate continuity and REACH amendment implementation timelines, with deviation risk concentrated in FCC spectrum reallocation decisions and Polish defense modernization execution. Recalibration cycles align with material shifts in electromagnetic spectrum warfare requirements and EU Cyber Resilience Act enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Technical Textile Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Agro Textiles Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Construction Textile Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
E-Textile Market