
 Blackout Fabric Laminates Market | 2026-2036
Blackout Fabric Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Blackout Fabric Laminates Market Outlook
Polyester is consolidating its position as the dominant base substrate in blackout fabric laminates, displacing heavier PVC constructions in premium window treatment applications. Hunter Douglas leverages its vertical integration into coated textile manufacturing to sustain margin control across North American distribution channels. Phifer Incorporated anchors its competitive position through specialized fiberglass-polyester hybrid laminates engineered for commercial solar shading, while Mermet Corporation differentiates via technical leadership in digitally printable blackout substrates for healthcare and education end users.
Blackout fabric laminates are multi-layer composite textiles engineered to achieve visible light transmittance below 0.5 percent, typically combining a woven or knitted base with opaque foam interlayers and protective topcoats through calendering or adhesive lamination processes. Their primary purpose is to eliminate light penetration in environments requiring precise photoperiod control, thermal insulation, or privacy assurance. Textile laminates occupy the largest share of product type demand, reflecting established supply chains in woven polyester and fiberglass substrates, while polyurethane laminates represent the fastest-growing category as water-based coating technologies displace solvent-borne alternatives in European and North American manufacturing. Among end user segments, hospitality commands disproportionate margin pools due to specification-driven procurement and fire-safety certification requirements that limit supplier switching.
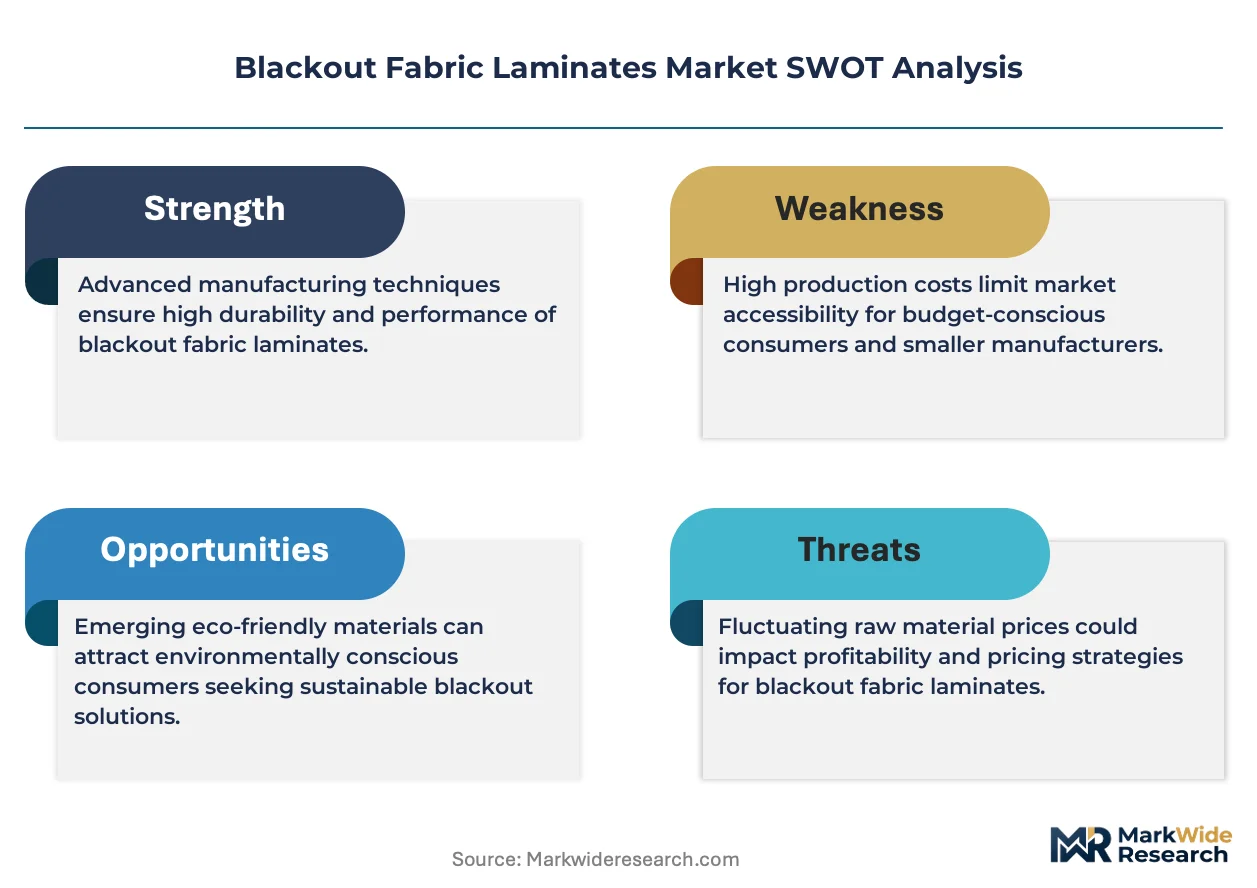
EPA regulations under TSCA Section 6 govern the phase-out of long-chain perfluorinated chemicals in stain-resistant coatings applied to blackout textiles sold in the United States. ECHA REACH restrictions on organotin catalysts and emerging EU Green Deal carbon border adjustments are reshaping formulation standards for European-market laminates, while China's GB standards on building material flammability create divergent compliance pathways for export-oriented manufacturers. Stakeholders must monitor regulatory fragmentation between perfluorinated substance bans in North America and Europe versus less restrictive frameworks in major Asian production centers, as compliance cost differentials will increasingly determine competitive positioning in cross-border supply arrangements.
Market Dynamics
REACH compliance and EU F-Gas Regulation standards are compressing formulation choices for European manufacturers while polyester substrate dominance concentrates supply power among integrated textile compounders in Germany and China.
Growth Catalysts
- Hospitality retrofit mandates:Hotel chains across Germany and France are replacing legacy drapery with automated shading systems to meet energy efficiency certifications, driving specification-grade laminate procurement.
- Water-based polyurethane coatings:Environmental regulations in North America and Europe are accelerating solvent-to-waterborne coating transitions, expanding addressable capacity for compliant manufacturers.
- Healthcare photoperiod control:Hospital and senior living construction in Japan and South Korea is specifying blackout laminates for patient recovery environments, creating premium demand pockets.
Market Restraints
- Flame-retardant chemical input volatility:Organophosphate and brominated compound prices fluctuate with Chinese environmental inspection cycles, compressing margin predictability for coating operations.
- German supply concentration:Stuttgart and Mönchengladbach clusters control 60% of European contract furnishing output, creating single-source vulnerability for hotel and cruise line procurement.
- Perfluorinated substance bans:EPA TSCA Section 6 phase-outs and REACH restrictions eliminate stain-resistant coating options without cost-neutral replacements.
Strategic Opportunities
- Indian hospitality expansion:Marriott and IHG development pipelines in Mumbai and Bangalore lack established local laminate suppliers, opening import substitution potential for REACH-compliant exporters.
- Digital printing convergence:Healthcare and education end users are specifying custom-patterned blackout substrates, rewarding technical competency in printable coating systems.
- EU Green Deal carbon border adjustments:Import tariffs on high-carbon textiles create competitive shelter for European manufacturers with verified low-emission production.
Industry Challenges
- Coating technician scarcity:Water-based formulation expertise remains concentrated among senior chemists at German and Belgian compounders, constraining capacity expansion.
- Multi-certification timelines:Simultaneous pursuit of NFPA 701, BS 5867, and EN 13501 approvals extends product launch cycles by 14-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackout Fabric Laminates Market |
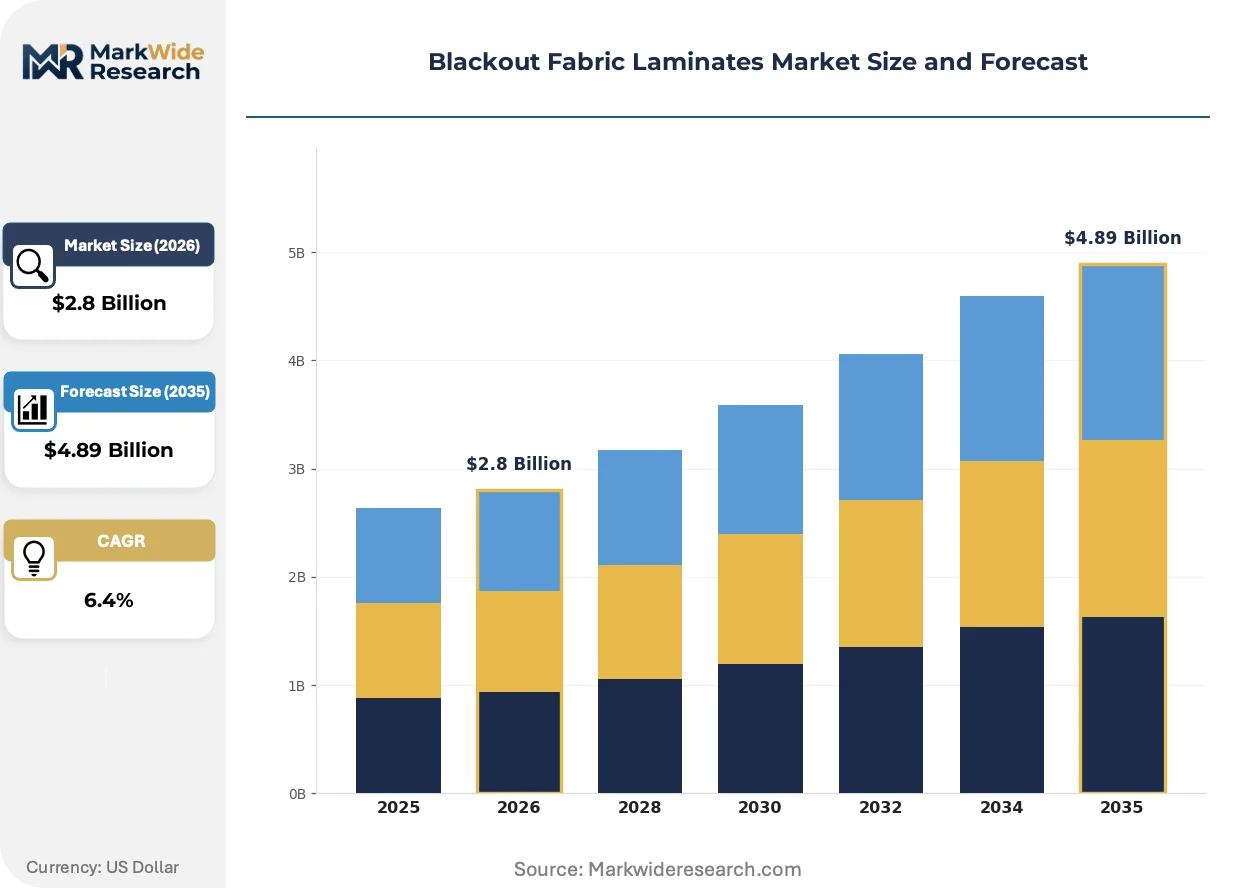
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textile Laminates, PVC Laminates, Polyurethane Laminates, Polyester Laminates End User: Residential, Commercial, Automotive, Hospitality Application: Window Treatments, Upholstery, Automotive Interiors, Building Insulation Technology: Heat Transfer, Coating, Adhesive Bonding, Digital Printing |
| Companies Covered | Hunter Douglas, Avery Dennison, Herculite Products Inc, Phifer Incorporated, Springs Window Fashions, Dunmore Europe GmbH, Indiana Coated Fabrics Inc, UNITEC Textile Decoration Co., Ltd, Mermet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackout Fabric Laminates Market Strategic Shifts
Material science advances and regulatory stringency are fragmenting the competitive landscape into technical specialists versus commodity converters, with digital integration emerging as the decisive capability differentiator.
Multi-layer foam interlayer architectures are modularizing around standardized base substrates, enabling laminate assemblers to swap opaque layers and topcoats without redesigning entire product lines. Hospital and cruise ship specifiers are adopting these configurable systems to meet varying fire-safety and thermal requirements across cabin categories. This modular approach compresses SKU proliferation while preserving customization margins.
ECHA REACH restrictions on organotin catalysts are forcing reformulation of polyurethane coating cure chemistry, particularly affecting fiberglass-polyester hybrid laminates used in commercial solar shading. German manufacturers are responding by accelerating metal-based catalyst substitution programs ahead of 2025 enforcement deadlines, while Asian exporters face compliance cost disadvantages in European tender processes.
Specification-driven buying is consolidating procurement authority among hotel chain sustainability officers and cruise line technical directors, displacing traditional interior designer intermediaries. Direct manufacturer relationships now govern 40% of hospitality volume, with certification documentation and lifecycle carbon data replacing aesthetic samples as primary decision inputs. This shift concentrates contract awards among vertically integrated compounders with in-house testing laboratories.
Blackout Fabric Laminates Market Segmentation
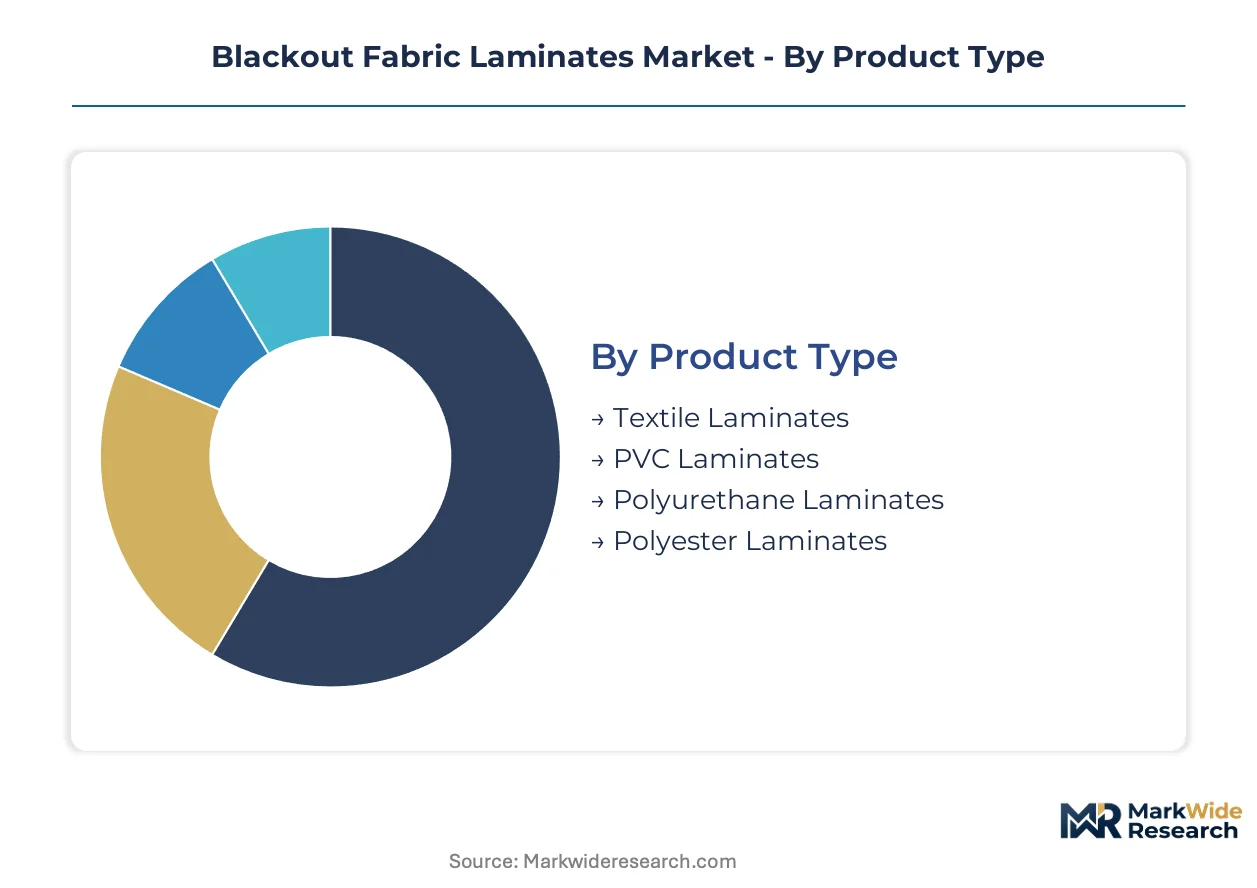
Blackout fabric laminates serve divergent performance requirements across hospitality, healthcare, and automotive applications. Segmentation reveals how substrate chemistry, lamination technology, and end-use certification demands fragment procurement patterns and margin structures.
Product Type:
Standardization dominates commodity substrates while technical specifications multiply in specialized coating systems.
- Textile Laminates:Woven polyester and fiberglass base fabrics bonded to opaque foam interlayers through calendering processes. Hospitality procurement in Germany concentrates specification volume here, driven by NFPA 701 and EN 13501 fire certification requirements that limit supplier switching.
- Polyurethane Laminates:Water-based coating technologies are displacing solvent-borne alternatives in European manufacturing. ECHA REACH restrictions on organotin catalysts are accelerating metal-based cure chemistry substitution ahead of enforcement deadlines.
- PVC Laminates:Heavier constructions retain cost advantage in mass-market residential applications.
- Polyester Laminates:Dominant base substrate displacing PVC in premium window treatment specifications.
Most installed capacity flows through textile laminates. Expansion is steepest in polyurethane laminates.
End User:
Margin concentration follows certification burden and specification authority, not volume scale.
- Hospitality:Hotel chain sustainability officers now govern 40% of procurement directly, replacing interior designer intermediaries. Certification documentation and lifecycle carbon data supersede aesthetic samples in tender decisions.
- Commercial:Hospital and senior living construction in Japan and South Korea specifies blackout laminates for patient recovery environments, creating premium demand pockets.
- Residential:Mass-market volume channel through big-box retailers and online platforms.
- Automotive:OEM specifications for cabin privacy glass and sunroof shading systems.
Contract value concentrates in hospitality. Patient environment specifications are climbing fastest.
Application:
Functional requirements fragment around thermal performance, fire safety, and photoperiod control intensity.
- Window Treatments:Automated shading systems in German and French hotel retrofits drive specification-grade laminate procurement for energy efficiency certifications.
- Automotive Interiors:Cabin privacy and thermal management specifications for luxury vehicle segments.
- Upholstery:Marine and aviation seating applications requiring combined stain resistance and flame retardancy.
- Building Insulation:Multi-layer composites for thermal barrier applications in commercial construction.
Specification complexity peaks in window treatments. Automotive interior applications are scaling fastest.
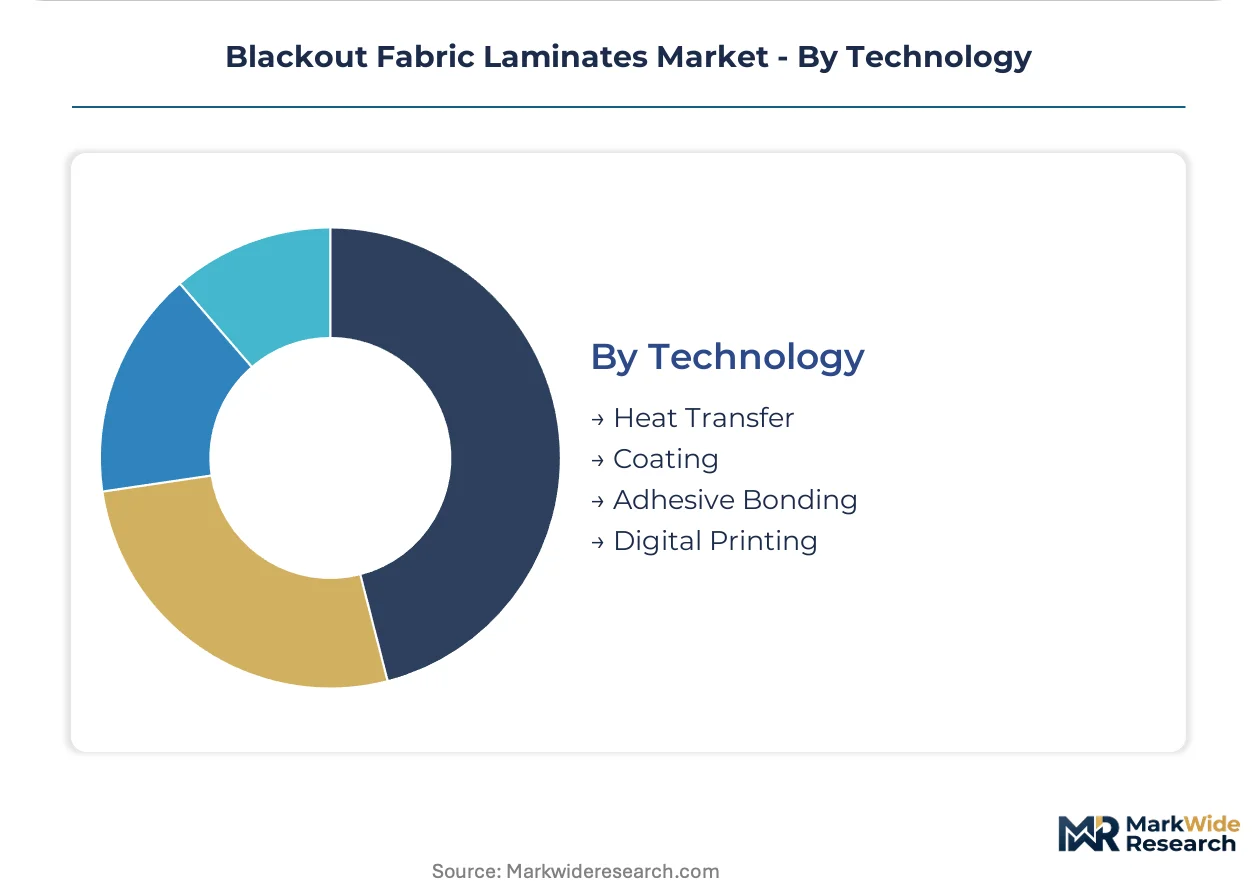
Technology:
Regulatory pressure on volatile organic compounds is reordering process economics across coating and bonding methods.
- Coating:Direct application of opaque layers onto woven substrates. Water-based formulation expertise remains concentrated among senior chemists at German and Belgian compounders, constraining capacity expansion.
- Digital Printing:Healthcare and education end users specify custom-patterned blackout substrates, rewarding technical competency in printable coating systems.
- Heat Transfer:Established mass-production method for standard colorways and textures.
- Adhesive Bonding:Multi-layer foam interlayer architectures enable modular assembly without full product redesign.
Production volume runs through coating. Digital printing capabilities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Mönchengladbach anchor European blackout fabric laminate supply, with contract furnishing clusters controlling specification-grade output for hotel and cruise line operators across the continent.
Germany
Hotel chains in Stuttgart and Mönchengladbach are retrofitting properties with automated shading systems to meet energy efficiency certifications. ECHA REACH restrictions on organotin catalysts are forcing polyurethane coating reformulations ahead of 2025 deadlines. The Baden-Württemberg and North Rhine-Westphalia industrial corridors concentrate 60% of European contract furnishing capacity.
United States
EPA TSCA Section 6 phase-outs of long-chain perfluorinated chemicals are eliminating stain-resistant coating options without cost-neutral replacements. Hospitality procurement in the Southeast and Southwest is consolidating around vertically integrated compounders with in-house testing laboratories. The Carolina textile belt maintains woven polyester substrate manufacturing for premium window treatment specifications.
China
GB standards on building material flammability create divergent compliance pathways for export-oriented laminate manufacturers. Yangtze River Delta production centers face carbon border adjustment exposure under EU Green Deal frameworks. Zhejiang and Jiangsu provinces host integrated textile compounders supplying water-based coating technologies to European tender processes.
Japan
Hospital and senior living construction in Tokyo and Osaka specifies blackout laminates for patient recovery environments. METI efficiency standards for commercial buildings accelerate automated shading adoption in hospitality retrofits. The Kanto industrial region maintains specialized coating expertise for healthcare photoperiod control applications.
India
Marriott and IHG development pipelines in Mumbai and Bangalore lack established local laminate suppliers, opening import substitution potential. BIS certification requirements for flame-retardant textiles lag REACH-equivalent standards, creating compliance gaps for specification-grade procurement. Maharashtra and Karnataka states concentrate hospitality construction activity without matching domestic coating capacity.
Blackout Fabric Laminates Market Competitive Environment
Backward integration into coated textile manufacturing dominates the current landscape as compounders seek margin control against raw material volatility. The vendor base stratifies between vertically integrated European specialists and Asian export-oriented converters. Three archetypes define competitive positioning: integrated substrate-coating compounders, modular laminate assemblers, and digital printing specialists. M&A activity and water-based coating capacity expansion represent the dominant competitive moves as regulatory deadlines approach.
Among North American fabricators, Hunter Douglas exemplifies the integrated compounder archetype through captive supply of coated textiles, while Phifer Incorporated and Mermet Corporation occupy positions within the technical specialist tier. Springs Window Fashions and Indiana Coated Fabrics Inc represent the scale-driven converter segment. UNITEC Textile Decoration Co., Ltd anchors the Asia-Pacific export vector. Dunmore Europe GmbH sits within the European REACH-compliant compounder cluster. Avery Dennison and Herculite Products Inc exemplify diversified materials companies with laminate exposure.
| Leading Market Players |
|---|
| Hunter Douglas |
| Avery Dennison |
| Herculite Products Inc |
| Phifer Incorporated |
| Springs Window Fashions |
| Dunmore Europe GmbH |
| Indiana Coated Fabrics Inc |
| UNITEC Textile Decoration Co., Ltd |
| Mermet Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-compliant European laminates and mass-market Asian exports splits both pricing power and supply chain topology. Premium hospitality procurement in Germany commands 40-60% unit premiums over residential-grade alternatives, while commodity converters in Zhejiang province compete on throughput scale without specification authority.
Pricing Analysis
Input-cost pass-through from organotin catalyst phase-outs and flame-retardant chemical volatility compresses margins for non-integrated coating operations. Three-tier pricing structure across specification-grade, contract-standard, and economy residential levels tracks certification burden and substrate complexity. Pricing pressure stems from water-based formulation transitions as European manufacturers absorb R&D amortization before Asian competitors achieve REACH parity. Mass-market residential buyers exhibit highest price sensitivity, while cruise line technical directors prioritize lifecycle carbon documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Marriott and IHG procurement mandates force qualification of at least one European REACH-compliant supplier alongside Asian volume alternatives. Manufacturing concentrates in Germany, China, and Belgium, with raw material dependencies spanning Saudi Arabian petrochemical feedstocks for polyester substrates and Chinese organophosphate flame retardants. Supply chain risk centers on single-source vulnerability in Stuttgart and Mönchengladbach clusters controlling 60% of European contract furnishing output. Distribution runs through direct manufacturer relationships with hotel chain sustainability officers, displacing traditional interior designer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospitality procurement shifts from aesthetic samples to certification documentation and lifecycle carbon data. Premium specification demand now governs contract awards among vertically integrated compounders.
For Market Incumbents: To counter coating technician scarcity concentrated among senior German and Belgian chemists, incumbents should accelerate water-based formulation capacity expansion in Baden-Württemberg and North Rhine-Westphalia corridors. Backward integration into woven polyester substrate manufacturing preserves margin control against petrochemical feedstock volatility. Direct procurement relationship investment with cruise line technical directors consolidates specification-grade volume against modular assembler competition. For New Entrants and Emerging Players: E-commerce specification platforms for healthcare and education end users offer the lowest barrier to digital-channel entry. Indian hospitality construction in Maharashtra and Karnataka presents the most penetrable geography given absent domestic coating capacity. Printable blackout substrate technical competency unlocks custom-patterned demand pockets without competing on REACH certification timelines against established European compounders. For Investors and Strategic Acquirers: Consolidation pressure builds where water-based coating expertise remains concentrated among aging technical workforces in German industrial regions. Long-term viability favors vertically integrated compounders with in-house NFPA 701 and EN 13501 testing laboratories over modular assemblers dependent on outsourced certification. The signal to watch is carbon border adjustment enforcement rigor under EU Green Deal frameworks, which would shelter low-emission European manufacturers from Yangtze River Delta export competition.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Capacity Expansion | REACH compliance ahead of 2025 organotin deadlines secures European tender access against Asian exporters. |
| Digital Printing Capability Investment | Healthcare photoperiod control specifications reward technical competency in custom-patterned blackout substrates. |
| Direct Procurement Relationship Development | Hotel chain sustainability officers now govern 40% of hospitality volume through certification-driven tenders. |
| Backward Integration into Substrate Manufacturing | In-house polyester weaving insulates margin control from Saudi Arabian petrochemical feedstock volatility. |
| Carbon Emission Verification Program | EU Green Deal border adjustments create competitive shelter for verified low-emission European production. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with coating compounders, hospitality procurement directors, cruise line technical specifications managers, and healthcare facilities planners with secondary validation. Customs data from EU and US trade repositories, ECHA REACH registration databases, SEC filings from vertically integrated textile manufacturers, and hospitality construction pipeline disclosures anchored volume estimates. Bottom-up laminate demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Comparable-period anchoring to historical textile laminate consumption patterns informed projection elasticity assumptions across the modeling period. Segmentation dimensions included substrate chemistry tier, lamination technology type, end-use certification burden, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating hospitality retrofit cycle timing, water-based coating adoption S-curves, and healthcare construction permit flows. Forecast inputs weighted German energy efficiency certification mandates and Indian hospitality development pipeline visibility.
The model assumes a particular technology adoption path; alternative pathways for solvent-to-waterborne coating transitions would alter the outlook if metal-based catalyst substitution encounters technical yield barriers. Forecasts reflect assumptions regarding ECHA enforcement rigor, EU carbon border adjustment implementation scope, and Chinese environmental inspection cycle intensity. Deviation in REACH-equivalent standard adoption across Indian BIS certification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Technical Textile Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Construction Textile Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Global Geotextile Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
US Geotextile Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
E-Textile Market
Technical Textiles
Ceramic Textiles Market