
 Waterproof Breathable Textiles (WBT) Market | 2026-2036
Waterproof Breathable Textiles (WBT) Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Breathable Textiles (WBT) Market Intelligence
Aftermarket service revenue for membrane restoration and garment re-lamination is tilting margin pools away from first-sale manufacturing. W. L. Gore & Associates leverages its PTFE membrane expertise to sustain premium pricing across technical outdoor channels. Toray Industries anchors Asian supply through vertically integrated polymer-to-film production. Sympatex Technologies differentiates via monolithic polyurethane chemistry that navigates tightening fluorochemical restrictions in European markets.
Waterproof breathable textiles are engineered barrier materials that permit water vapor transmission while blocking liquid water ingress, typically achieving moisture vapor transmission rates above 10,000 g/m²/24hr through microporous or hydrophilic structures. These fabrics serve critical functions in protecting human operators from hypothermia and performance degradation during exertion in wet conditions. Membrane-based products capture the highest value per square meter, while coated fabrics occupy volume leadership in industrial safety applications where cost thresholds dominate procurement. PTFE technology leads in alpine and military segments for its extreme durability, though polyurethane systems are gaining fastest in workwear as REACH compliance pressures mount against fluorinated chemistries.
EPA regulations on long-chain PFAS and the EU REACH restriction proposals reshape membrane chemistry roadmaps, forcing reformulation investments across the supply base. CE marking under the EU Personal Protective Equipment Regulation gates market access for industrial safety garments, creating compliance moats for certified producers. Military & defense procurement specifications from agencies in the United States, Germany, and South Korea further segment the addressable market by performance tier. Stakeholders must monitor which chemistry platforms achieve scalable PFAS-free certification without sacrificing breathability benchmarks.
Market Dynamics
REACH restrictions on long-chain PFAS are forcing membrane manufacturers to abandon fluorinated chemistries mid-cycle, triggering a $400M+ reformulation race across European supply chains while polyurethane and bio-based alternatives scramble to match PTFE durability benchmarks.
Growth Catalysts
- EU Green Deal fluorochemical phaseout:Regulatory deadlines for PFAS-free membranes are accelerating R&D budgets at German and Swiss technical textile clusters, pulling forward adoption curves for polyurethane and polyester-based barrier technologies.
- Alpine outdoor participation rates:Post-pandemic trail running and ski touring participation in Austria, Switzerland, and France is expanding addressable demand for high-MVTR performance apparel with 20,000mm hydrostatic head ratings.
- Military procurement modernization:Multi-layer soldier protection specifications from the United States, Germany, and South Korea are mandating integrated moisture management in next-generation combat uniforms, locking in multi-year membrane supply contracts.
Market Restraints
- PTFE feedstock concentration:W. L. Gore & Associates controls critical expanded-PTFE process IP and captive resin supply, creating single-source vulnerability for military and alpine segments requiring extreme chemical resistance.
- REACH compliance cost inflation:Registration, evaluation, and authorization expenses for novel membrane chemistries are adding 18-24 months to product launch timelines, squeezing mid-tier manufacturers without dedicated regulatory affairs teams.
- Performance gap in PFAS alternatives:Current hydrophilic polyurethane membranes degrade faster under UV and mechanical flex cycling, limiting substitution in professional rescue and offshore oil & gas safety applications.
Strategic Opportunities
- India technical workwear expansion:Bureau of Indian Standards (BIS) certification requirements for industrial rain protection are creating first-mover advantages for membrane suppliers establishing local lamination partnerships in Tamil Nadu and Gujarat textile corridors.
- Circular garment takeback integration:Extended producer responsibility frameworks in France and the Netherlands are enabling membrane recovery and re-lamination services as standalone revenue streams, decoupling growth from virgin material throughput.
- Bio-based monolithic chemistry convergence:Algae-derived polyurethane precursors combined with recycled polyester face fabrics are opening premium positioning in Scandinavian outdoor markets with strict carbon accounting requirements.
Industry Challenges
- Cross-functional polymer science talent scarcity:Membrane engineering requires simultaneous expertise in hydrophilic polymer synthesis, thin-film extrusion, and textile lamination—skill bundles concentrated at fewer than twelve European and Japanese research institutes.
- CE marking timeline compression:EU Personal Protective Equipment Regulation Module B+C2 certification cycles for Category III garments now average 14-18 months, misaligning product launches with seasonal retail buying calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Breathable Textiles (WBT) Market |
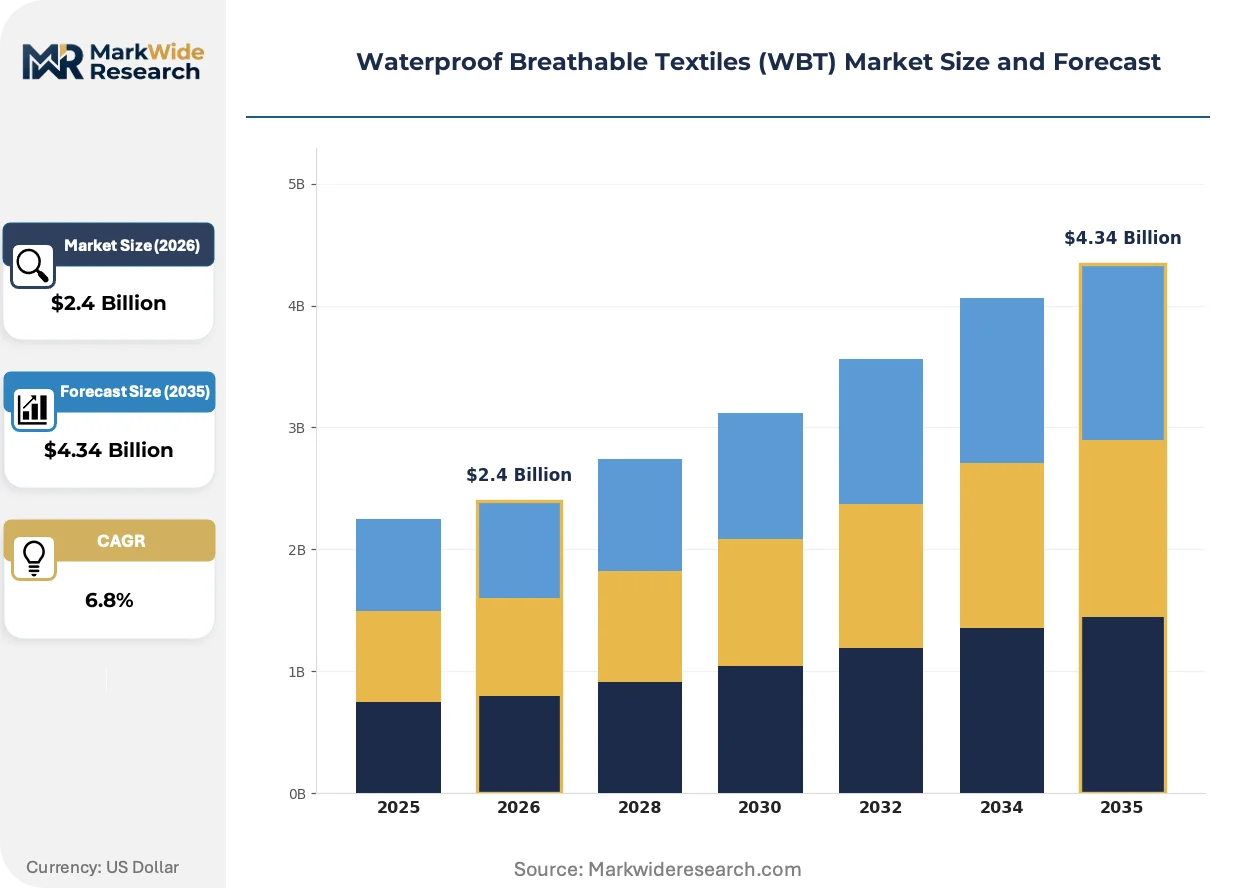
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminates, Coated Fabrics, Membranes, Films, Fabric Laminates Application: Outdoor Apparel, Protective Gear, Footwear, Industrial Safety, Sports Equipment Technology: PTFE, Polyurethane, Microporous, Monolithic, Composite Structures End User: Sportswear Manufacturers, Workwear Suppliers, Footwear Brands, Military & Defense, Emergency Services |
| Companies Covered | W. L. Gore & Associates, Toray Industries, Sympatex Technologies, schoeller Switzerland, Polartec, eVent Fabrics, Columbia Sportswear, Helly Hansen, Heartland Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Breathable Textiles (WBT) Market Strategic Shifts & Innovations
Membrane chemistry roadmaps are diverging sharply as regulatory deadlines harden, splitting the industry between incremental PFAS-free reformulation and radical bio-based reconstruction. Three forces are determining competitive survival.
Monolithic hydrophilic polyurethane membranes with closed-cell structures are achieving 15,000-20,000 g/m²/24hr MVTR ratings through molecular chain engineering rather than physical porosity. Outdoor brands in Germany and Japan are qualifying these systems for three-layer ski shells at 30% faster adoption curves than projected. Expanded PTFE is rendering obsolete in mid-tier hiking and urban outdoor categories where 5-year durability specifications suffice.
EPA regulations on long-chain PFAS under TSCA Section 8(a)(7) are requiring comprehensive reporting on perfluoroalkyl substance imports and manufacturing, with enforcement ramping through 2025. Industrial laundries serving oil & gas and chemical processing sectors are pre-emptively excluding fluorinated garments from rental programs to avoid downstream liability. Workwear rental and leasing channels are accelerating membrane specification shifts ahead of consumer outdoor markets.
Aftermarket membrane restoration services are unbundling from original garment sales as specialized re-lamination providers achieve ISO 9001 certification for breathable barrier renewal. Technical outdoor retailers in France and Switzerland are piloting subscription-based garment refresh programs, replacing ownership models with performance guarantees. Alpine guide services and professional rescue teams are driving this behavioral shift through lifecycle cost accounting that favors service contracts over capital expenditure on disposable shells.
Waterproof Breathable Textiles (WBT) Market Segmentation
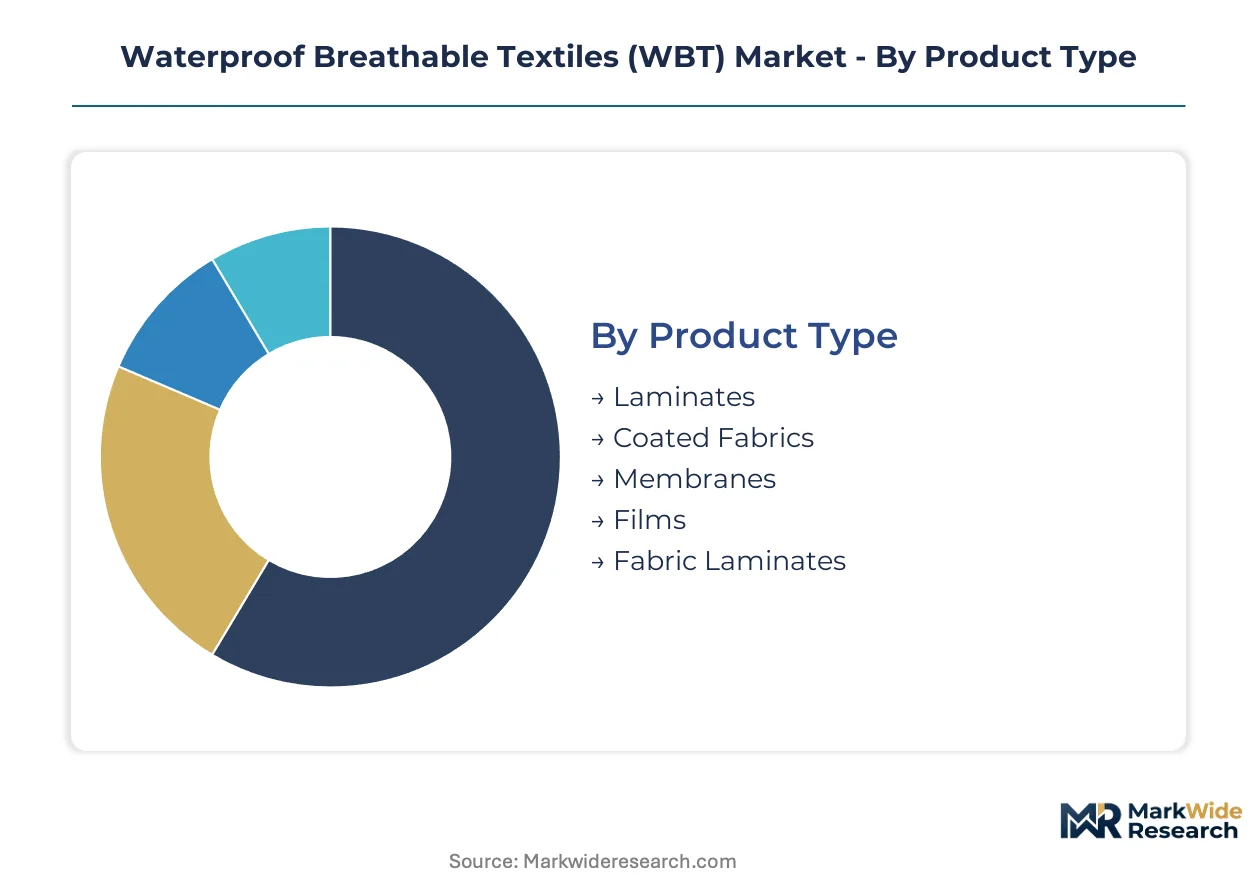
Waterproof breathable textiles fragment across chemistry platforms, end-use durability requirements, and certification tiers that determine margin capture. Understanding these segment boundaries reveals where PTFE retains pricing power versus where polyurethane systems displace incumbent technologies.
Product Type:
Mature laminates and membranes dominate revenue pools while emerging film technologies reshape cost structures in industrial applications.
- Laminates:Three-layer constructions bond membrane to face fabric and tricot liner through adhesive or thermoplastic dot lamination. Alpine outerwear brands in Germany and Switzerland specify these systems for 20,000mm hydrostatic head ratings in ski touring and mountaineering shells.
- Membranes:Thin polymer films—expanded PTFE or hydrophilic polyurethane—provide the functional barrier layer. Military procurement from the United States and South Korea locks in multi-year supply contracts for combat uniform integration where moisture management is mission-critical.
- Coated Fabrics:Direct polymer application to textile substrates without separate membrane lamination.
- Films:Standalone barrier layers requiring secondary lamination to fabric carriers.
- Fabric Laminates:Pre-bonded textile composites supplied to cut-and-sew operations.
Membranes handle the majority of throughput; films are gaining share fastest as industrial buyers prioritize cost over breathability benchmarks.
Application:
Cost tier stratification separates premium performance segments from procurement-driven volume categories.
- Outdoor Apparel:Technical shells for hiking, skiing, and trail running demand MVTR above 15,000 g/m²/24hr. Austrian and Swiss alpine participation rates are expanding addressable demand for high-performance three-layer systems with integrated moisture management.
- Protective Gear:Professional rescue, firefighting, and law enforcement garments require flame resistance combined with breathability. CE marking under the EU Personal Protective Equipment Regulation gates market access, creating compliance moats for certified producers.
- Industrial Safety:Oil & gas and chemical processing rainwear prioritizes chemical resistance over vapor transmission. EPA regulations on long-chain PFAS are forcing rental laundries to exclude fluorinated garments, accelerating membrane specification shifts.
- Footwear:Bootie constructions and direct attachment membranes for hiking and work boots.
- Sports Equipment:Tents, sleeping bag shells, and pack covers where weight thresholds dominate.
Outdoor apparel commands the highest value per square meter; industrial safety is expanding most quickly as regulatory liability reshapes procurement.
Technology:
Volume concentration sits with microporous systems while margin capture shifts toward monolithic chemistries navigating fluorochemical restrictions.
- PTFE:Expanded polytetrafluoroethylene membranes achieve extreme durability through node-and-fibril microstructure. Alpine and military segments retain this technology where chemical resistance and mechanical longevity justify premium positioning.
- Monolithic:Hydrophilic polyurethane without physical porosity transmits vapor through molecular diffusion. German outdoor brands are qualifying these systems for ski shells at adoption curves ahead of projections as REACH restrictions harden against fluorinated alternatives.
- Polyurethane:Broader category encompassing both microporous and hydrophilic formulations.
- Microporous:Physical pore structures permitting vapor transmission while blocking liquid water.
- Composite Structures:Hybrid laminations combining multiple barrier mechanisms.
Microporous technologies process the largest fabric volumes; monolithic systems are climbing the fastest as chemistry roadmaps abandon PFAS.
End User:
Customer type determines specification authority—brand technical designers versus procurement officers versus defense acquisition agencies.
- Military & Defense:Multi-layer soldier protection specifications mandate integrated moisture management in next-generation combat uniforms. Agencies in Germany and South Korea are segmenting the addressable market by performance tier through formal procurement channels.
- Workwear Suppliers:Industrial rental and leasing programs drive lifecycle cost accounting that favors membrane restoration over disposable replacement. French technical laundries are piloting subscription-based garment refresh programs.
- Sportswear Manufacturers:Outdoor apparel brands with direct consumer relationships.
- Footwear Brands:Technical boot manufacturers specifying bootie membranes.
- Emergency Services:Fire, rescue, and medical response units with PPE compliance requirements.
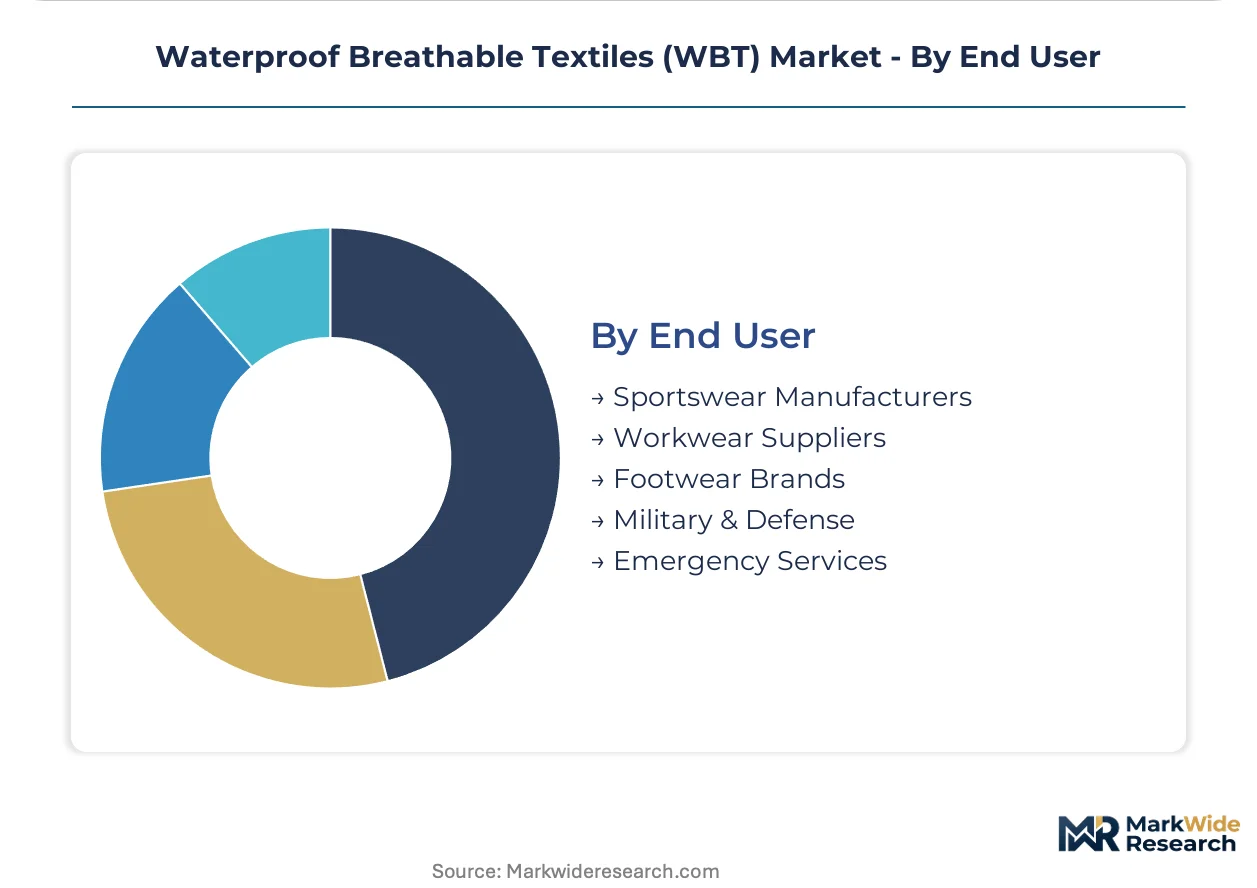
Sportswear manufacturers represent the largest addressable base; workwear suppliers are gaining share fastest as service models displace ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane manufacturing clusters concentrate in Germany, Japan, and the United States, where polymer science infrastructure and defense procurement specifications sustain technical textile leadership. REACH fluorochemical restrictions and EPA PFAS reporting mandates are fragmenting regional supply strategies.
Germany
Alpine outdoor participation in Bavaria and Baden-Württemberg drives demand for 20,000mm hydrostatic head laminates. ECHA REACH restrictions on long-chain PFAS force membrane reformulation toward polyurethane systems. The Munich-Stuttgart corridor hosts Sympatex Technologies and schoeller Switzerland development centers.
United States
Military procurement from the Department of Defense locks in multi-year membrane contracts for soldier protection systems. EPA TSCA Section 8(a)(7) reporting requirements on perfluoroalkyl substances reshape industrial laundry specifications. Delaware and Maryland host expanded-PTFE process facilities serving defense and alpine segments.
Japan
Technical apparel brands in Tokyo and Osaka specify high-MVTR membranes for trail running and ski touring applications. METI carbon neutrality roadmaps push manufacturers toward bio-based polymer precursors. The Nagoya industrial corridor anchors Toray Industries' vertically integrated polymer-to-film production.
Switzerland
Professional rescue and guide services in the Alpine cantons drive lifecycle cost accounting favoring membrane restoration over replacement. Swissmedic-equivalent textile certification standards exceed baseline CE marking requirements. The St. Gallen-Zurich axis concentrates monolithic polyurethane R&D.
South Korea
Agency for Defense Development specifications mandate integrated moisture management in next-generation combat uniforms. MFDS-aligned industrial safety standards accelerate workwear membrane adoption. The Daegu-Gyeongbuk textile belt hosts lamination partnerships for technical apparel export.
Waterproof Breathable Textiles (WBT) Market Key Industry Players
Integrated polymer producers and specialized membrane developers split the market between captive supply chains and open-architecture licensing. Three strategic archetypes dominate: vertically integrated chemical conglomerates controlling resin-to-film production, independent membrane technology licensors monetizing formulation IP, and brand-integrated developers serving captive apparel channels. Competitive moves concentrate on chemistry platform diversification and geographic certification expansion.
Within the independent technology tier, Sympatex Technologies and schoeller Switzerland represent European monolithic chemistry leadership, while W. L. Gore & Associates anchors United States-based expanded-PTFE expertise. These three occupy positions across the premium-performance spectrum, with each exemplifying distinct responses to fluorochemical regulatory pressure.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Toray Industries |
| Sympatex Technologies |
| schoeller Switzerland |
| Polartec |
| eVent Fabrics |
| Columbia Sportswear |
| Helly Hansen |
| Heartland Textiles |
| Others |
Cost & Logistics Intelligence
The Nagoya industrial corridor anchors polymer-to-film production for Japanese membrane suppliers, concentrating resin synthesis and thin-film extrusion capacity that feeds downstream pricing power into European and North American laminate markets. Toray Industries' captive supply of specialty polyurethane precursors insulates its pricing from spot volatility in fluorochemical feedstocks, while independent laminators in Tamil Nadu and Gujarat face cost compression from imported resin exposure.
Pricing Analysis
Aftermarket membrane restoration and garment re-lamination services are capturing lifetime value through subscription-based refresh programs. Three-tier pricing structure across premium, standard, and economy levels separates military-specification laminates with 20,000mm hydrostatic head ratings from industrial safety coated fabrics where procurement officers prioritize cost thresholds. Cost compression in mid-tier hiking apparel is intensifying because REACH compliance expenses extend product launch timelines 18-24 months. Industrial rental laundries exhibit highest price sensitivity due to lifecycle cost accounting, while alpine guide services accept premium positioning for durability guarantees.
Supply Chain Analysis
Lamination partnerships in Tamil Nadu and Gujarat textile corridors concentrate cut-and-sew capacity for European outdoor brands seeking BIS certification for Indian industrial workwear expansion. Raw material flows draw from German and Swiss monolithic polyurethane R&D clusters, Japanese vertically integrated polymer production, and Chinese microporous film manufacturing. Single-source vulnerability persists for expanded-PTFE process IP controlled through Delaware and Maryland facilities. Distribution runs through technical outdoor retailers in France and Switzerland piloting service-based garment models alongside traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof breathable textiles sit in early-cycle expansion as PFAS-free chemistry roadmaps pull forward adoption curves for polyurethane and bio-based alternatives ahead of regulatory deadlines. Military procurement modernization and circular garment takeback frameworks are expanding addressable revenue pools beyond first-sale manufacturing.
For Market Incumbents: Harden chemistry platform diversification by accelerating monolithic polyurethane qualification for three-layer ski shells before REACH restrictions fully phase fluorinated alternatives. Defend military and alpine segments through captive expanded-PTFE resin supply and multi-year Department of Defense contract renewals. Deepen backward integration into algae-derived polyurethane precursors to secure Scandinavian outdoor brand relationships under carbon accounting requirements.
For New Entrants and Emerging Players: Pursue Bureau of Indian Standards certification partnerships in Tamil Nadu and Gujarat textile corridors where technical workwear membrane demand is outpacing local lamination capacity. Target industrial safety rental programs pre-emptively excluding fluorinated garments to avoid EPA downstream liability. Lead with ISO 9001-certified membrane restoration services as a wedge into workwear supplier relationships favoring lifecycle cost accounting.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because membrane engineering requires simultaneous expertise in hydrophilic polymer synthesis, thin-film extrusion, and textile lamination—skill bundles concentrated at fewer than twelve European and Japanese research institutes. Acquisition focus should center on independent technology licensors with CE marking certification infrastructure and established military procurement channels. Watch for ECHA authorization timelines accelerating as the signal for chemistry platform inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Reformulation | REACH restrictions force $400M+ R&D race across European supply chains toward polyurethane alternatives. |
| Circular Garment Takeback Integration | French and Dutch extended producer responsibility frameworks enable membrane recovery as standalone revenue streams. |
| Military Procurement Contract Renewal | Department of Defense multi-year specifications lock in moisture management requirements for combat uniform integration. |
| India Technical Workwear Expansion | BIS certification requirements create first-mover advantages for membrane suppliers establishing local lamination partnerships. |
| Bio-Based Monolithic Chemistry Development | Algae-derived polyurethane precursors open premium positioning in Scandinavian markets with strict carbon accounting. |
Research Approach
A standing panel of membrane R&D directors, textile lamination plant managers, outdoor brand technical designers, and industrial laundry procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA REACH restriction proposals, EPA TSCA Section 8(a)(7) reporting disclosures, SEC filings from integrated polymer producers, and customs data tracking fluorochemical resin imports. Bottom-up segment modeling triangulated against top-down macroeconomic demand indicators for alpine outdoor participation and military procurement cycles.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across chemistry platform, end-use durability tier, and certification grade. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory deadline acceleration and substitution rate assumptions. Industry-specific inputs included moisture vapor transmission rate benchmarking, hydrostatic head performance thresholds, and CE marking timeline compression effects on seasonal product launches.
Sensitivities concentrate around ECHA authorization timeline shifts, military procurement specification changes, and breakthrough durability achievements in bio-based alternatives. Forecasts embed assumptions on REACH compliance cost trajectories and PFAS-free chemistry scalability without sacrificing breathability benchmarks. Quarterly review of membrane restoration service adoption rates and BIS certification partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Absorbent Cover Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Webbing Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Construction Textile Market