
 North America Technical Textiles Market | 2026-2036
North America Technical Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Technical Textiles Market Insights
The US EPA greenhouse gas standards for light-duty vehicles is expanding the addressable market for high-performance reinforcement textiles across automotive platforms. DuPont leverages its aramid fiber heritage to anchor premium ballistic and aerospace applications. Berry Global Inc. competes through scale in polypropylene nonwovens for hygiene and medical end uses. Milliken & Company differentiates via advanced polymer chemistry for military and industrial protective systems.
Technical textiles encompass engineered fiber-based materials designed for functional performance rather than aesthetic appeal, typically manufactured through weaving, knitting, nonwoven bonding, or composite lamination processes with specified tensile strength, thermal stability, and chemical resistance parameters. These materials serve critical load-bearing, filtration, barrier, or reinforcement roles across infrastructure, transportation, healthcare, and defense applications. Industrial textiles lead the product type landscape due to mature demand from construction and manufacturing sectors, while medical textiles represent the fastest-expanding segment driven by infection-control protocols and aging-population care needs. Polyester dominates the material mix by volume owing to cost-performance balance, though aramid commands the deepest margin pools in aerospace and defense niches.
The US EPA, NHTSA, and OSHA collectively shape product standards through emissions rules, flame-resistance mandates, and workplace exposure limits that filter market access for non-compliant suppliers. The Canadian PMRA and Health Canada impose parallel chemical-safety and biocompatibility requirements that create a harmonized but stringent North American regulatory perimeter. Stakeholders must monitor evolving PFAS restrictions and state-level extended-producer-responsibility laws that threaten incumbent chemistries while opening substitution opportunities for bio-based and recycled-fiber innovators.
Market Dynamics
The US EPA and NHTSA fuel-economy mandates are compressing material substitution cycles across automotive platforms. Lightweight composite reinforcements now displace conventional metals at accelerated rates, concentrating procurement leverage among Tier-1 suppliers in the southeastern US manufacturing corridor.
Growth Catalysts
- EPA greenhouse gas standards:Light-duty vehicle emission rules mandate material lightweighting, expanding addressable volume for high-performance reinforcement textiles across automotive OEM platforms.
- Georgia-South Carolina-North Carolina corridor:Dense clustering of composite manufacturing and automotive assembly creates localized demand pull with shortened logistics loops for technical textile suppliers.
- Aramid fiber performance:Superior strength-to-weight ratios enable penetration into ballistic protection and aerospace structural applications where failure tolerance is minimal.
Market Restraints
- Petrochemical feedstock volatility:Polyester and polypropylene resin prices track crude oil and natural gas liquids, compressing margin predictability for nonwoven producers.
- PFAS chemistry restrictions:State-level extended-producer-responsibility laws and EPA action on per- and polyfluoroalkyl substances threaten incumbent water-repellent and flame-retardant textile finishes.
- Aramid supply concentration:Limited qualified producers of para-aramid fiber create single-source risk for aerospace and defense contractors requiring certified material traceability.
Strategic Opportunities
- Mexico automotive expansion:OEM assembly capacity growth south of the US border creates geographic white space for technical textile suppliers with nearshoring logistics advantages.
- Bio-based fiber substitution:Polylactic acid and cellulosic reinforcements qualify for IRA clean energy manufacturing credits, opening procurement doors with sustainability-mandated buyers.
- Medical textile infection control:Antimicrobial nonwoven demand from aging-population care facilities and surgical suite protocols outpaces current North American production capacity.
Industry Challenges
- Composite technician scarcity:Automated fiber placement and resin transfer molding operations require skilled labor pools that regional technical colleges have not scaled to match demand.
- OSHA workplace exposure compliance:Respirable fiber monitoring and ventilation capital expenditures burden smaller weaving and nonwoven operations attempting defense and aerospace certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Technical Textiles Market |
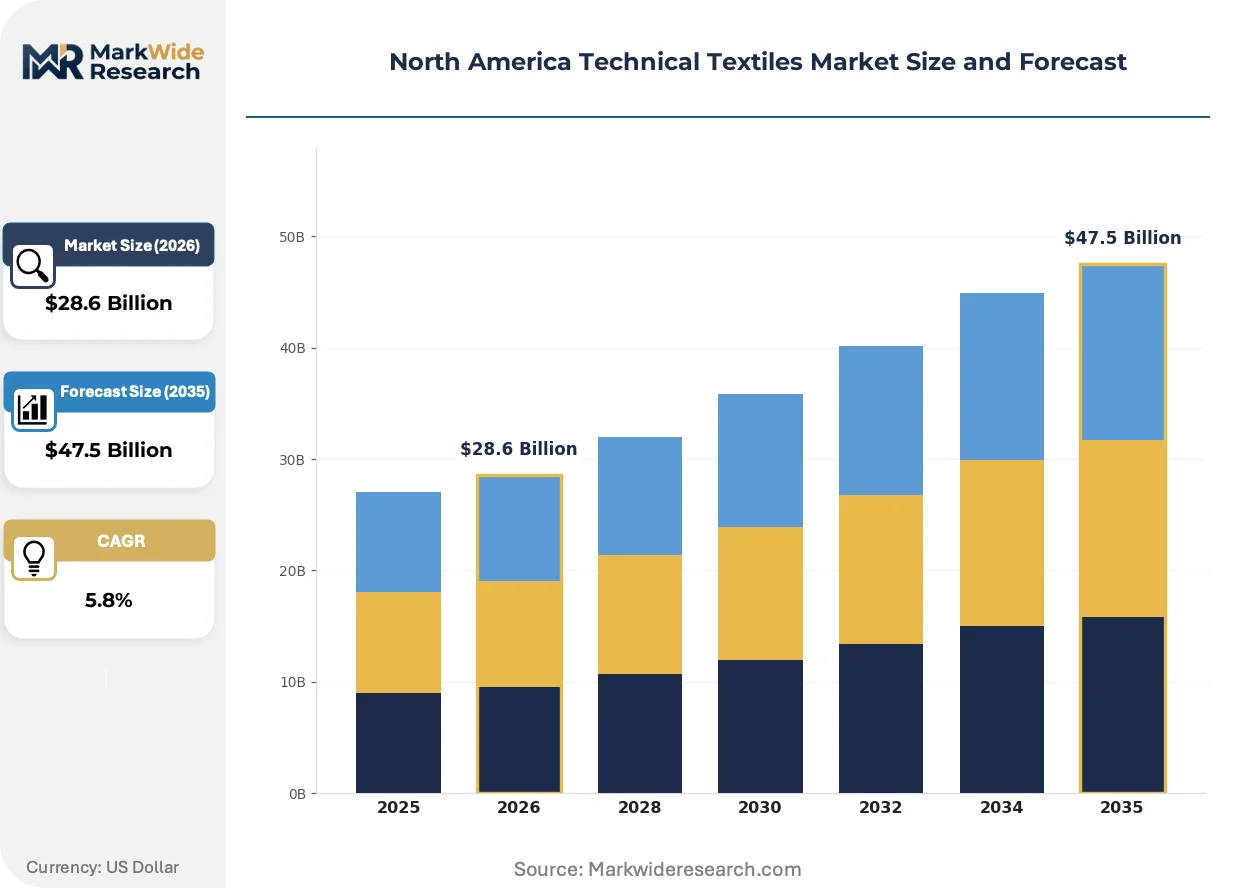
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Agrotextiles, Medical Textiles, Industrial Textiles Application: Construction, Agriculture, Healthcare, Automotive Material: Polyester, Nylon, Aramid, Polypropylene End User: Manufacturers, Contractors, Retailers, Government |
| Companies Covered | Johns Manville, Freudenberg Performance Materials, DuPont, Toray Industries Inc., Asahi Kasei Corporation, Berry Global Inc., Milliken & Company, Ahlstrom, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Technical Textiles Market Trends and Innovations
Material science convergence with digital manufacturing is compressing product development cycles across functional textile categories. Three interconnected developments are restructuring competitive positioning.
Recycled polyethylene terephthalate (rPET) staple fiber is expanding into automotive interior panels and underbody shields. Tier-1 suppliers in Michigan and Ohio have qualified rPET nonwovens for NVH applications previously reserved for virgin polyester. This shift is expanding into structural reinforcements as OEM sustainability scorecards harden procurement specifications.
The US EPA finalized stricter vehicle emission rules through 2032. These standards force material lightweighting at scale, accelerating substitution of glass fiber with carbon and aramid hybrids in electric vehicle battery enclosures. The southeastern US automotive corridor is responding with dedicated composite preforming capacity co-located with final assembly.
Fleet procurement departments now bundle technical textile specifications into multi-year vehicle platform contracts. Direct OEM-supplier relationships are displacing traditional distributor channels for high-performance reinforcements. This concentration is most visible in defense and aerospace verticals where certified supplier status locks out secondary sources.
North America Technical Textiles Market Segmentation
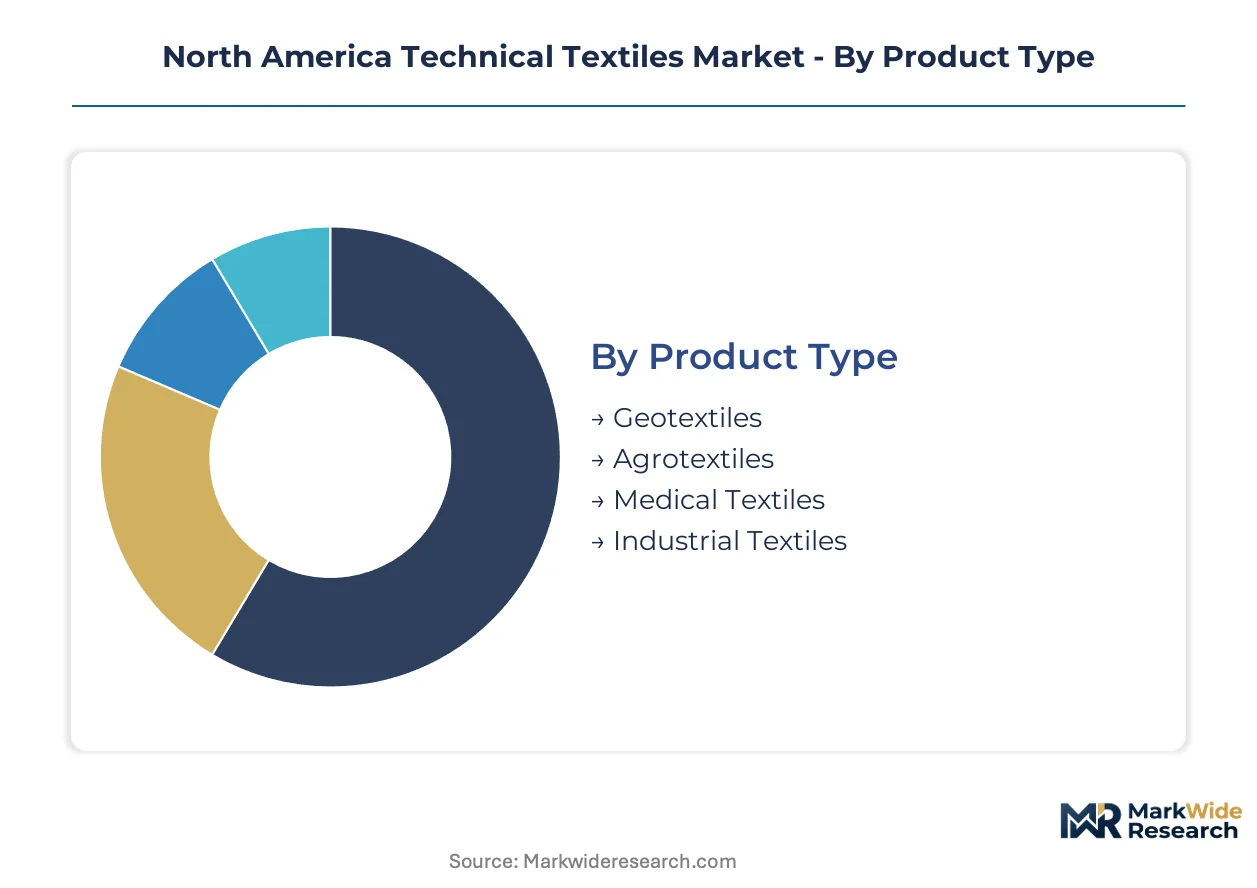
Technical textile procurement decisions hinge on performance specifications that vary sharply across end-use environments. Segmentation reveals where material substitution cycles compress upgrade timelines and where incumbent chemistries retain defensive positions.
Product Type:
Replacement cycles for technical textiles accelerate where infrastructure age and regulatory pressure intersect, forcing specification upgrades that favor engineered fiber solutions over conventional materials.
- Industrial Textiles:Woven and nonwoven reinforcements for conveyor belting, filtration media, and protective barriers dominate current volume. Demand concentrates in the southeastern US manufacturing corridor where OSHA compliance mandates drive specification upgrades in heavy machinery guarding and industrial ventilation systems.
- Medical Textiles:Antimicrobial nonwovens, surgical meshes, and implantable fabrics qualify under FDA biocompatibility protocols. Hospital infection-control budgets and aging-population surgical volumes are expanding procurement of single-use sterile barriers faster than domestic production capacity.
- Geotextiles:Polypropylene and polyester woven stabilization fabrics for soil reinforcement and drainage applications serve DOT infrastructure projects across state transportation departments.
- Agrotextiles:Crop protection nets, mulch mats, and shade fabrics extend growing seasons in California's Central Valley and Florida's specialty crop regions.
Volume placements concentrate in Industrial Textiles; the faster expansion belongs to Medical Textiles.
Application:
Customer procurement authority varies by project scale, with federal infrastructure spending concentrating demand in contractor-led channels while automotive platforms consolidate around OEM direct sourcing.
- Construction:Geosynthetic reinforcement and concrete curing blankets qualify under AASHTO and ASTM specifications for highway and commercial building projects. State DOT procurement offices in Texas, California, and Florida drive specification adherence through qualified-product lists that filter supplier access.
- Automotive:Lightweight composite reinforcements for interior panels, underbody shields, and battery enclosures displace metal at accelerating rates. EPA fuel-economy mandates through 2032 are compressing material qualification timelines as OEMs seek gram-level weight reductions.
- Healthcare:Surgical drapes, gowns, and sterilization wraps demand FDA 510(k) clearance and traceable supply chains for acute-care facilities.
- Agriculture:Erosion control blankets and crop support fabrics serve precision farming operations requiring UV-stabilized durability across seasonal cycles.
Construction absorbs the largest share of current tonnage; Automotive is climbing the fastest as electrification reshapes material requirements.
Material:
Feedstock cost structures and performance ceilings create distinct competitive battlegrounds where polyester scale confronts aramid specialization.
- Polyester:PET staple and filament yarns balance tensile performance with cost efficiency across geotextile, industrial, and medical nonwoven applications. Recycled-content rPET variants are gaining qualification for automotive interior panels as OEM sustainability scorecards harden procurement specifications.
- Aramid:Para-aramid fibers deliver strength-to-weight ratios essential for ballistic protection, aerospace structural components, and high-temperature filtration. Limited qualified producers create supply concentration that defense contractors manage through multi-year offtake agreements.
- Polypropylene:Lightweight, chemically resistant staple fiber dominates agrotextile and hygiene nonwoven segments with favorable moisture management properties.
- Nylon:High-tenacity yarns serve industrial belting, tire cord, and airbag applications requiring abrasion resistance and dimensional stability.
Polyester commands the widest application footprint; Aramid captures the steepest expansion trajectory in defense and aerospace verticals.
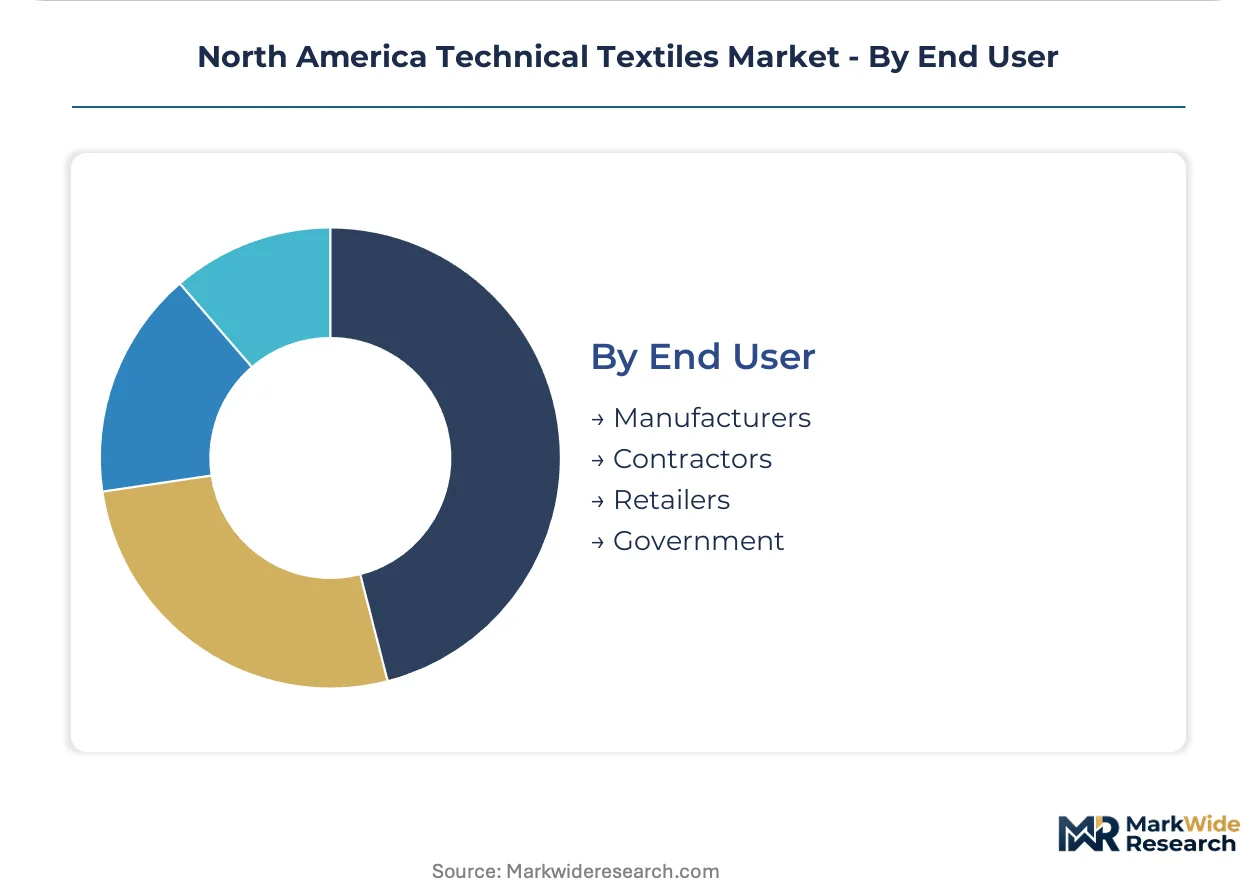
End User:
Procurement sophistication diverges sharply between specification-driven institutional buyers and price-sensitive commercial intermediaries.
- Manufacturers:Tier-1 automotive suppliers and composite fabricators maintain direct technical textile relationships with certified fiber producers. EPA and NHTSA compliance documentation requirements lock in qualified supplier status that secondary sources cannot replicate without 18-24 month qualification cycles.
- Government:Federal defense procurement through DLA and state DOT qualified-product lists impose traceability, domestic-content, and performance-testing standards that filter market access.
- Contractors:Commercial construction and civil engineering firms source geotextiles and industrial fabrics through distributor channels with project-specific specification adherence.
- Retailers:Agricultural supply cooperatives and medical product distributors serve fragmented end-user bases with standardized product ranges.
Manufacturers drive the deepest technical engagement; Government procurement is gaining share fastest as infrastructure and defense spending accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Georgia-South Carolina-North Carolina manufacturing corridor anchors North American technical textile demand, with automotive composite preforming capacity clustering around Spartanburg, Greenville, and Atlanta logistics nodes.
United States
EPA fuel-economy mandates through 2032 compress material qualification timelines for electric vehicle battery enclosures. OSHA workplace exposure rules govern respirable fiber monitoring at weaving and nonwoven operations. The southeastern automotive corridor responds with co-located composite preforming capacity serving BMW, Mercedes-Benz, and Volvo assembly plants.
Canada
Health Canada biocompatibility protocols and PMRA chemical-safety requirements create a harmonized regulatory perimeter with US standards. Federal infrastructure spending through the National Trade Corridors Fund expands geotextile demand for transportation projects. Ontario's Golden Horseshoe hosts filtration media producers supplying Great Lakes manufacturing.
Mexico
OEM assembly capacity expansion in Nuevo León and Bajío Region creates geographic white space for technical textile suppliers. Mexican automotive production growth under USMCA rules of origin pulls composite reinforcement demand southward. Querétaro and Guanajuato industrial parks attract Tier-1 suppliers seeking nearshoring logistics advantages.
North America Technical Textiles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and certification depth, with aramid fiber producers commanding steepest returns while polyester nonwoven fabricators compete on scale. The vendor base stratifies into three tiers: diversified chemical conglomerates with fiber heritage, specialized nonwoven scale producers, and regional composite reinforcement fabricators. Dominant competitive moves include backward integration into polymer resin production and geographic expansion into Mexico's automotive corridor.
Among diversified chemical conglomerates, DuPont exemplifies the premium-tier archetype anchored by aramid fiber heritage. Berry Global Inc. occupies the scale-driven position in polypropylene nonwovens. Milliken & Company represents the specialized industrial segment with advanced polymer chemistry capabilities.
| Leading Market Players |
|---|
| Johns Manville |
| Freudenberg Performance Materials |
| DuPont |
| Toray Industries Inc. |
| Asahi Kasei Corporation |
| Berry Global Inc. |
| Milliken & Company |
| Ahlstrom |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between aerospace-qualified aramid and commodity polyester nonwovens manifests in pricing power anchored to NHTSA and EPA compliance documentation, while supply chain configurations split between southeastern US automotive corridor co-location and Asian resin feedstock dependence. This bifurcation concentrates margin capture among fiber producers with certified supplier status while compressing returns for undifferentiated nonwoven converters.
Pricing Analysis
Outcome-based pricing anchors aramid fiber contracts to ballistic protection performance and aerospace structural yield rates, with DuPont and Toray commanding premiums tied to failure-tolerance specifications. Price differentiation separates FDA-cleared medical textiles from industrial hygiene grades, with ISO 13485 certification adding margin layers. Cost compression in polyester staple fiber intensifies due to petrochemical feedstock volatility, while Tier-1 automotive suppliers exhibit lowest price sensitivity for EPA-mandated lightweighting materials.
Supply Chain Analysis
Post-consumer rPET collection and reprocessing flows now feed automotive interior panel specifications, creating closed-loop material circuits that bypass virgin resin markets. Feedstock dependence centers on US Gulf Coast paraxylene for polyester, Japanese and US para-aramid polymerization, and Canadian propylene for polypropylene nonwovens. Single-source vulnerability concentrates in para-aramid fiber qualification, where defense contractors face 18-month recertification timelines. Distribution runs through Tier-1 automotive suppliers and DLA-qualified channels for defense applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained aramid fiber capacity props pricing across aerospace and defense verticals, with qualified producer scarcity creating defensive moats for incumbent fiber manufacturers.
For Market Incumbents: Cement multi-year offtake agreements with BMW, Mercedes-Benz, and Volvo assembly plants in the Georgia-South Carolina corridor before Mexico automotive expansion accelerates. Backward integration into polymer resin production secures margin against petrochemical volatility, while PFAS chemistry restrictions threaten incumbent water-repellent finishes requiring R&D pivot to bio-based alternatives. For New Entrants and Emerging Players: Enter via antimicrobial nonwoven production for aging-population care facilities, where FDA 510(k) clearance barriers are lower than aerospace certification and domestic capacity lags surgical drape demand. Target Mexico's Nuevo León and Querétaro industrial parks with nearshoring logistics advantages for OEM suppliers seeking USMCA compliance. Lead with sustainability-mandated procurement doors opened by IRA clean energy manufacturing credits for bio-based fiber substitution. For Investors and Strategic Acquirers: Re-rating potential sits with specialized medical textile producers given hospital infection-control budget expansion and single-use sterile barrier demand outstripping North American production capacity. Long-term viability favors acquisition targets with FDA master file documentation and established GPO contracts rather than commodity nonwoven scale. Monitor EPA PFAS regulatory action and state-level extended-producer-responsibility legislation as inflection indicators for chemistry substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive paraxylene supply from US Gulf Coast insulates margin against crude oil volatility. |
| FDA 510(k) Clearance Pathway | Medical textile qualification opens surgical drape procurement at acute-care facilities. |
| Georgia-South Carolina Corridor Expansion | Co-located composite preforming capacity shortens logistics loops for BMW and Mercedes-Benz. |
| rPET Qualification for Automotive Interiors | OEM sustainability scorecards harden procurement specifications favoring recycled content. |
| Joint Venture in Mexico Automotive Belt | USMCA rules of origin pull composite reinforcement demand toward Nuevo León assembly plants. |
Research Methodology
Document review covered EPA emission rulemakings, NHTSA fuel-economy standards, FDA 510(k) clearance databases, and DLA qualified-product lists, complemented by interviews with Tier-1 automotive supplier procurement directors, composite fabricator plant managers, hospital GPO contracts managers, and technical textile R&D directors. Secondary validation drew from SEC 10-K filings, USITC trade data, and AATCC testing standards. Bottom-up fiber volume estimates triangulated against top-down end-use consumption models.
Historical qualification timeline data cross-referenced against panel input from OEM platform engineers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material chemistry, end-use application, and certification tier. CAGRs derived from regression against EPA mandate compliance deadlines and automotive electrification content shifts, with electric vehicle battery enclosure lightweighting treated as a discrete demand driver.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction timelines or aramid supply disruption scenarios. Practitioners should monitor EPA finalized vehicle emission rules and state extended-producer-responsibility legislation for early signals of chemistry substitution cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Technical Textile Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
US Geotextile Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Agri Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Agro Textiles Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Blackout Fabric Market