
 Voice Evacuation Systems Market | 2026-2036
Voice Evacuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Evacuation Systems Market Analytics
IP-to-analog protocol convergence is narrowing the interoperability gap between legacy fire alarm infrastructure and modern building management networks. Bosch Security Systems leverages its global installed base to sustain upgrade revenue across European commercial properties. Honeywell International Inc. anchors its position through backward integration into cloud-connected emergency communication software. Johnson Controls International plc competes on system integration density, bundling voice evacuation with access control and HVAC analytics.
Voice evacuation systems combine loudspeaker arrays, digital signal processors, and automated messaging engines to deliver intelligible emergency instructions with minimum speech transmission index ratings of 0.50 in occupied zones. These systems serve fire safety and mass notification applications where audible clarity determines evacuation speed and occupant survival rates. Integrated systems capture the dominant share of new installations as facility managers prioritize unified command interfaces over standalone alarm panels. IP-based technology leads replacement demand in transportation hubs and healthcare facilities where centralized monitoring reduces response latency.
The National Fire Protection Association's NFPA 72 standard and the EU's Construction Products Regulation collectively enforce intelligibility benchmarks that disqualify legacy analog installations from compliance renewal. Germany's KBA mandates voice evacuation compatibility in rail tunnel refurbishments, while the FAA requires certificated systems for airport terminal expansions. Stakeholders must monitor evolving cyber-resilience standards for networked emergency systems as building IoT attack surfaces expand.
Market Dynamics
IP-enabled voice evacuation platforms are compressing replacement cycles across commercial building portfolios as NFPA 72 intelligibility mandates disqualify legacy analog installations from compliance renewal in the United States and European Union member states.
Growth Catalysts
- NFPA 72 Code Enforcement:United States jurisdictions are rejecting analog system recertifications, forcing building owners into IP-based upgrades that integrate with building management networks.
- Rail Infrastructure Mandates:Germany's KBA requires voice evacuation compatibility in all tunnel refurbishments, creating dedicated procurement pipelines for transportation authorities.
- Healthcare Centralization:Hospital networks are consolidating emergency communication monitoring to reduce response latency, prioritizing IP-based platforms with unified command interfaces.
Market Restraints
- Semiconductor Supply Concentration:Digital signal processor fabrication concentrates in East Asian foundries, exposing European and North American system integrators to extended lead times.
- Copper Loudspeaker Cable Volatility:Raw material price swings for distributed audio infrastructure compress margins on large-scale commercial installations.
- Cyber-Resilience Certification Gaps:Building IoT security standards for networked emergency systems remain under development, delaying procurement approvals for cloud-connected deployments.
Strategic Opportunities
- Airport Terminal Expansions:FAA certification requirements for voice evacuation systems in United States aviation infrastructure create captive demand for compliant platform vendors.
- Smart Building Convergence:Integration between emergency communication software and HVAC analytics platforms enables premium pricing for unified system bundles.
- United Kingdom Retrofit Cycles:Aging commercial stock in London and Manchester coincides with post-Grenfell fire safety mandates, accelerating replacement demand.
Industry Challenges
- Speech Intelligibility Engineering Shortage:Acoustic design expertise for achieving 0.50 minimum speech transmission index ratings in complex architectural geometries remains scarce among systems integrators.
- Legacy Protocol Integration Friction:Bridging IP-enabled voice evacuation platforms with existing fire alarm infrastructure requires specialized gateway hardware that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Evacuation Systems Market |
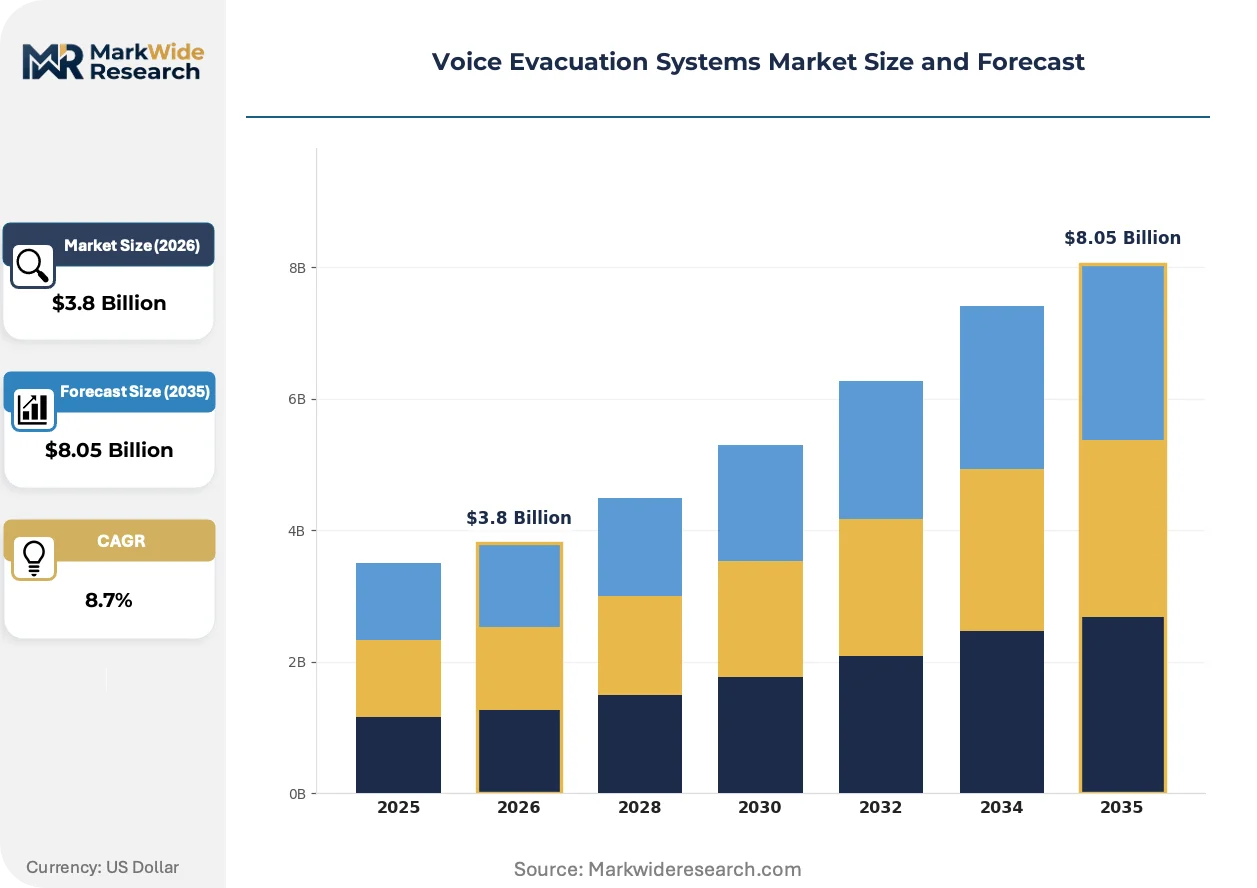
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Digital Solutions, Analog Systems End User: Commercial Buildings, Transportation Hubs, Educational Institutions, Healthcare Facilities Technology: IP-Based Systems, Traditional Systems, Wireless Systems, VoIP Solutions Application: Emergency Management, Public Address, Fire Safety, Security Alerts |
| Companies Covered | Bosch Security Systems, Honeywell International Inc., Johnson Controls International plc, Eaton Corporation plc, Siemens AG, TOA Corporation, Baldwin Boxall Communications Ltd., Kentec Electronics Ltd., ATEÏS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Evacuation Systems Market Evolving Landscape
Emergency communication architecture is undergoing fundamental restructuring as digital signal processing migrates toward edge-computing configurations and regulatory frameworks tighten intelligibility enforcement across jurisdictions.
Networked loudspeaker arrays with embedded DSP chips are migrating from centralized rack-mounted processors to distributed edge nodes. Healthcare facility managers in Germany and the United States are piloting these configurations to reduce cabling infrastructure and enable zone-specific audio processing. This topology is compressing installation labor costs while complicating firmware update management across dispersed device populations.
The European Union's Construction Products Regulation is tightening harmonized standards for emergency communication system intelligibility, compelling manufacturers to submit third-party tested acoustic performance data. Industrial consequence includes disqualification of legacy analog products from CE marking renewal. Transportation hub operators in France and the Netherlands are responding by bundling voice evacuation procurement with integrated fire detection tenders.
Facility management departments are consolidating vendor relationships for emergency systems under single-source service contracts that bundle hardware, software, and acoustic commissioning. This displaces the traditional model of separate fire alarm and public address contractors. The shift is most visible in United States commercial real estate investment trusts managing multi-site portfolios, where standardization reduces training overhead and spare parts inventory duplication.
Voice Evacuation Systems Market Segmentation
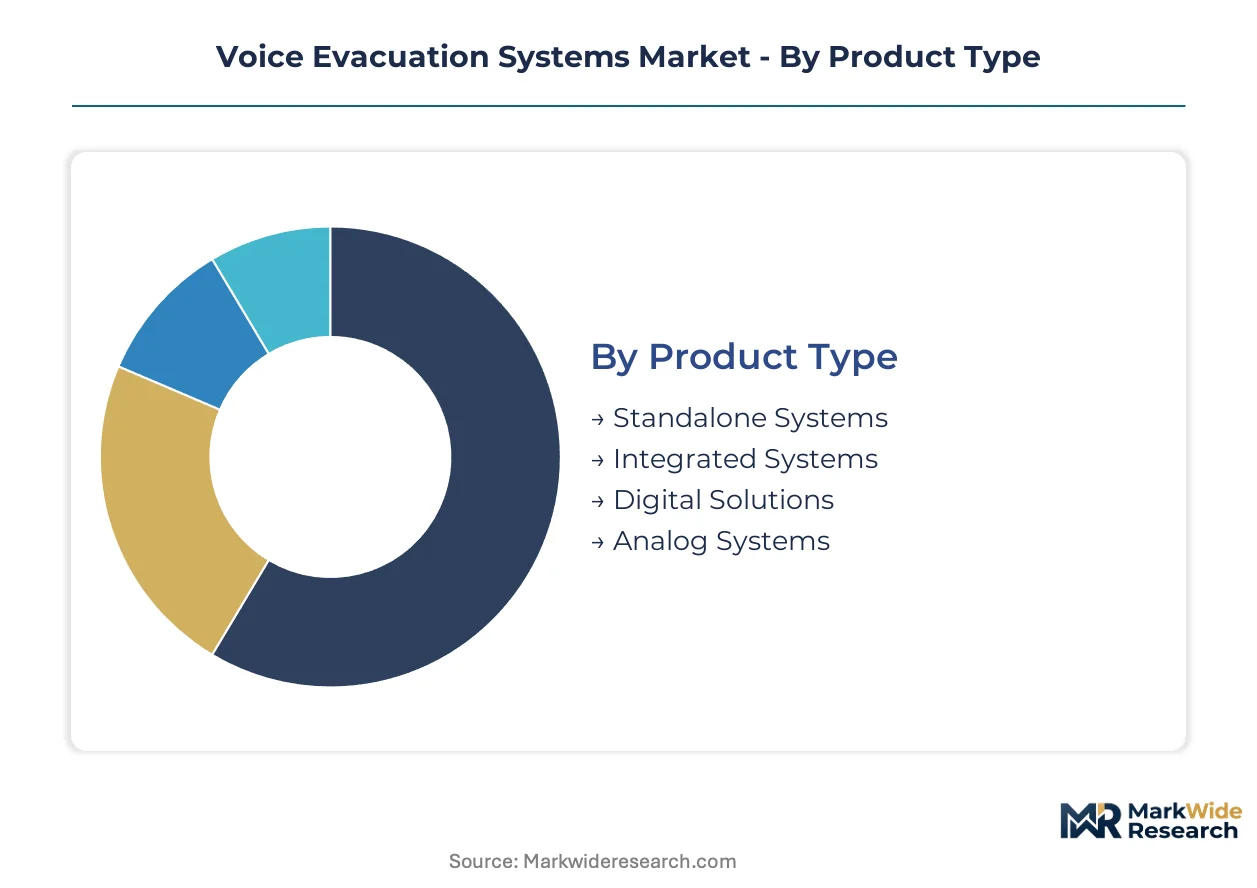
Voice evacuation systems fragment across four critical dimensions that determine procurement patterns and technology roadmaps. Product architecture dictates integration complexity with building management networks. End-use verticals impose divergent acoustic performance standards and regulatory compliance burdens.
Product Type:
Mature analog infrastructure coexists with emerging IP-native platforms as building owners navigate replacement cycles against budget constraints.
- Standalone Systems:Self-contained control panels with dedicated amplifier channels and zone-selective loudspeaker circuits. Demand concentrates in small commercial retrofits across Germany and the United Kingdom where minimal disruption to existing fire alarm infrastructure remains paramount.
- Integrated Systems:Unified platforms merging voice evacuation with access control, HVAC analytics, and video surveillance through single command interfaces. Transportation hubs in the United States prioritize these configurations to reduce operator training overhead and centralize emergency response protocols.
- Digital Solutions:Software-defined audio distribution with networked DSP processing and automated message triggering. Healthcare facilities in the United States deploy these for zone-specific intelligibility tuning and remote diagnostics capability.
- Analog Systems:Legacy centralized amplifier architectures with copper-wired loudspeaker loops. Aging commercial stock in the United Kingdom retains these installations where NFPA 72 compliance deadlines have not yet triggered mandatory replacement.
Integrated systems retain volume leadership; digital solutions hold the steepest expansion curve.
End User:
Cost tiers separate mission-critical infrastructure from standard commercial deployments based on acoustic engineering intensity and certification requirements.
- Commercial Buildings:Office complexes, retail centers, and hospitality properties requiring intelligible coverage across variable occupancy densities. United States commercial real estate investment trusts standardize on IP-enabled platforms to reduce multi-site spare parts inventory.
- Transportation Hubs:Airports, rail terminals, and tunnel networks with stringent FAA and KBA certification mandates. Germany's rail infrastructure refurbishment program creates dedicated procurement pipelines for tunnel-compatible voice evacuation arrays.
- Educational Institutions:Campuses and school districts balancing budget constraints with mass notification requirements. United States K-12 districts favor wireless system extensions to avoid disruptive cabling in aging building stock.
- Healthcare Facilities:Hospitals and medical centers demanding zone-specific messaging and integration with nurse call systems. Centralized monitoring consolidation across hospital networks in Germany and the United States accelerates IP platform adoption.
Commercial buildings dominate installed base volume; transportation hubs command the highest average system values per deployment.
Technology:
Application requirements drive technology selection between proven reliability and advanced connectivity features.
- IP-Based Systems:Ethernet-connected devices with Power over Ethernet loudspeaker arrays and centralized software management. Healthcare and transportation verticals in the United States and Germany prioritize these for reduced cabling infrastructure and remote firmware management.
- Traditional Systems:Hardwired centralized architectures with dedicated control panels and analog audio distribution. Legacy commercial properties retain these where immediate full-system replacement remains capital-constrained.
- Wireless Systems:Radio-frequency linked devices eliminating conduit requirements in retrofit applications. Educational institutions in the United States deploy these for rapid deployment in temporary facilities and modular classroom expansions.
- VoIP Solutions:Session Initiation Protocol-based emergency communication integrating with enterprise telephony infrastructure. Commercial building portfolios with unified communications mandates adopt these for streamlined IT administration.
IP-based systems command the dominant share of new specification activity; wireless configurations are expanding most quickly in education retrofits.
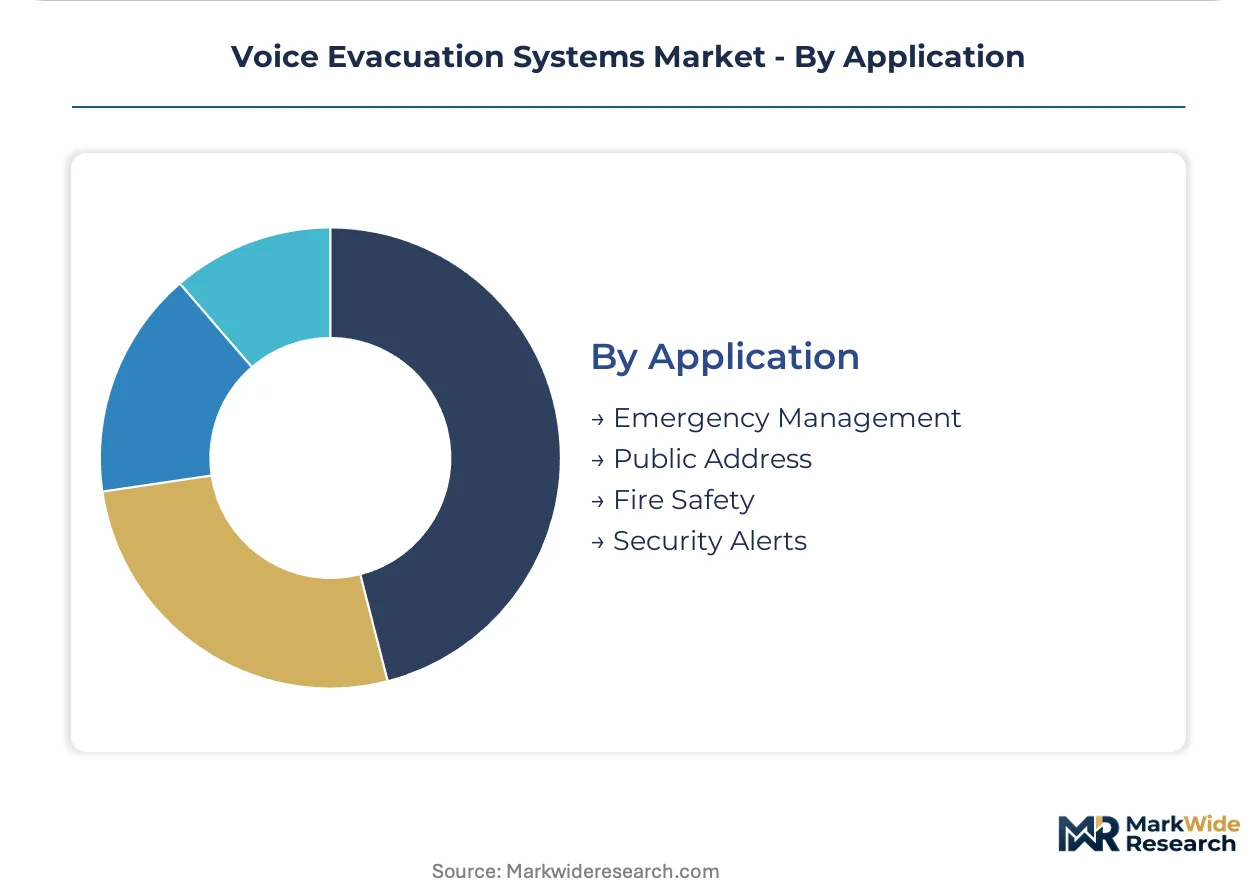
Application:
Customer type segmentation separates life-safety mandates from operational communication functions with distinct procurement authority structures.
- Emergency Management:Coordinated evacuation protocols with automated message sequencing and first responder integration. Transportation hubs and healthcare facilities prioritize these capabilities for regulatory compliance and liability mitigation.
- Public Address:Routine paging and informational broadcasting with emergency override functionality. Commercial buildings and educational institutions deploy these dual-purpose systems to maximize capital efficiency.
- Fire Safety:NFPA 72 and EU Construction Products Regulation-compliant intelligible voice alarm systems. Germany and United Kingdom building codes mandate these for new construction and major renovation permits.
- Security Alerts:Lockdown notifications and threat-specific messaging for active shooter or intrusion scenarios. United States educational institutions drive specification demand following district-wide safety mandate expansions.
Fire safety applications anchor regulatory-driven replacement cycles; security alert functionality is gaining specification share fastest in institutional verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German voice evacuation system manufacturers export heavily into United Kingdom and United States retrofit markets, where NFPA 72 compliance deadlines and post-Grenfell fire safety mandates drive procurement velocity. This transatlantic equipment flow concentrates in transportation hub and healthcare verticals.
United States
Commercial real estate investment trusts standardize IP-enabled platforms across multi-site portfolios to reduce spare parts inventory duplication. FAA certification requirements for airport terminal expansions create captive demand for compliant system vendors. Major metropolitan clusters in Dallas-Fort Worth and Atlanta anchor specification activity for transportation infrastructure.
Germany
Rail tunnel refurbishment programs under KBA mandates generate dedicated procurement pipelines for voice evacuation arrays with tunnel-specific acoustic engineering. The EU Construction Products Regulation tightens harmonized intelligibility standards, compelling manufacturers to submit third-party tested performance data. Industrial concentration in Bavaria and North Rhine-Westphalia hosts systems integration specialists serving Central European transportation authorities.
United Kingdom
Aging commercial stock in London and Manchester coincides with post-Grenfell fire safety mandates, accelerating replacement demand for legacy analog installations. Building control authorities reject recertification applications for non-compliant emergency communication systems. The Southeast England corridor dominates specification activity for integrated fire safety and voice evacuation bundles.
France
Transportation hub operators bundle voice evacuation procurement with integrated fire detection tenders to satisfy tightened EU intelligibility benchmarks. ANSM and national building safety regulators enforce acoustic performance verification for public infrastructure projects. The Île-de-France region concentrates deployment activity for airport and rail terminal modernization programs.
Japan
Healthcare facility networks consolidate emergency communication monitoring to reduce response latency, prioritizing IP-based platforms with unified command interfaces. METI guidelines encourage smart building convergence between emergency systems and building management networks. The Kanto region around Tokyo anchors demand for zone-specific intelligibility tuning in hospital construction.
Voice Evacuation Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with fire safety divisions, dedicated life-safety equipment specialists, and building automation integrators bundling emergency systems with HVAC and access control. Consolidation pressure favors M&A activity among mid-scale specialists, while technology licensing agreements proliferate around IP-to-analog protocol bridging.
Among diversified industrial conglomerates, Bosch Security Systems, Honeywell International Inc., and Johnson Controls International plc exemplify the integrated-systems archetype. These entities occupy positions spanning hardware manufacturing through cloud-connected software layers, leveraging backward integration into emergency communication platforms. Their scale enables unified service contracts that displace traditional separate fire alarm and public address contractor relationships.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Honeywell International Inc. |
| Johnson Controls International plc |
| Eaton Corporation plc |
| Siemens AG |
| TOA Corporation |
| Baldwin Boxall Communications Ltd. |
| Kentec Electronics Ltd. |
| ATEÏS Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in East Asian semiconductor foundries is compressing DSP availability and forcing European system integrators to accept extended lead times or premium spot pricing for voice evacuation control modules. This utilization squeeze cascades into project-based pricing volatility for transportation hub and healthcare deployments, where NFPA 72 compliance deadlines eliminate procurement delay options.
Pricing Analysis
Current-generation IP-enabled platforms command substantial premiums over prior-generation analog architectures, while next-generation edge-computing loudspeaker arrays remain in pilot-phase pricing. Project-based contracting dominates, with price differentiation separating UL-certified systems for FAA-mandated airport deployments from standard CE-marked configurations for commercial retrofits. Cost compression in analog tiers is intensifying because copper loudspeaker cable volatility erodes integrator margins. Educational institutions exhibit highest price sensitivity, prioritizing wireless extensions over full-system replacements.
Supply Chain Analysis
Extended payment terms from German rail authorities and United States healthcare networks are stretching working capital for mid-scale systems integrators dependent on East Asian DSP supply. Manufacturing concentrates in China, South Korea, and Taiwan for digital signal processors, with Germany and the United States hosting final assembly and acoustic commissioning. Raw material dependencies span copper cabling, rare-earth magnet loudspeaker components, and silicon wafers. Single-source vulnerability in DSP fabrication exposes integrators to allocation risk. Distribution runs through authorized systems integrators with NFPA 72 certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The voice evacuation systems market constitutes a defensive moat anchored in regulatory entrenchment. NFPA 72 and EU Construction Products Regulation compliance creates switching costs that lock building owners into certified vendor relationships across multi-decade asset lifecycles.
For Market Incumbents: Harden certification portfolios against emerging cloud-native competitors by deepening backward integration into emergency communication software layers. Invest in KBA-compliant tunnel acoustic engineering capabilities ahead of Germany's rail refurbishment wave. Channel control through unified service contracts displaces fragmented fire alarm and public address contractor relationships. For New Entrants and Emerging Players: Pursue wireless system white space in United States K-12 educational retrofits, where budget constraints and disruptive cabling avoidance create penetrable demand. Target VoIP-integrated configurations for commercial building portfolios with unified communications mandates. Go-to-market leverage rests on IT channel partnerships rather than traditional life-safety distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined audio distribution, reducing barrier thresholds for platform entrants. Mid-scale specialists with IP-to-analog gateway expertise present acquisition targets for diversified conglomerates seeking retrofit market access. Monitor cyber-resilience certification development as inflection signal for cloud-connected deployment approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NFPA 72 Certification Investment | Unlocks FAA-mandated airport terminal procurement pipelines in United States aviation infrastructure. |
| Edge-Computing Loudspeaker Development | Reduces cabling infrastructure costs for German healthcare facility network consolidation programs. |
| Unified Service Contract Expansion | Captures recurring revenue from United States commercial real estate investment trust standardization mandates. |
| IP-to-Analog Protocol Licensing | Enables retrofit compatibility with United Kingdom aging commercial stock ahead of Grenfell-driven replacement deadlines. |
| Cyber-Resilience Certification Program | Accelerates procurement approval for cloud-connected deployments as building IoT security standards mature. |
Research Methodology
Desk research of regulatory filing databases, trade association technical standards, and customs shipment records preceded structured interviews with fire safety systems integrators, hospital facility managers, transportation authority procurement officers, and acoustic engineering consultants. Primary fieldwork combined with secondary validation against NFPA 72 code documentation, EU Construction Products Regulation harmonized standards, and KBA tunnel safety directives. Bottom-up project pipeline enumeration triangulated against top-down building stock replacement cycle estimates.
Assumptions held fixed include current NFPA 72 intelligibility enforcement trajectories and existing EU regulatory harmonization timelines, while semiconductor supply availability and copper commodity pricing were treated as variable inputs across the projection horizon. Segmentation modeling spanned product architecture, end-use vertical, technology generation, and application function. CAGRs derived from replacement cycle velocity analysis and compliance deadline clustering. Industry-specific inputs included rail tunnel refurbishment program schedules and healthcare network centralization trends.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, interest rate environments, or public infrastructure budget allocations would shift the trajectory. Technological disruption from alternative emergency notification modalities or regulatory relaxation of intelligibility mandates would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Europe Public Safety Market
Public Safety
Safe City Market
Public Safety
North America Road Safety Market
Public Safety
Crime Risk Report Market
Public Safety
US Mass Notification Systems Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Global Public Safety Solution Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Public Safety Drones Market
Public Safety
Europe Road Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Global Public Safety and Security Market
Public Safety
Public Safety LTE Market
Public Safety
Crowd Management System Market