
 US Fire Safety Equipment Market | 2026-2036
US Fire Safety Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Fire Safety Equipment Market Insights
Recurring inspection and monitoring subscriptions is rebalancing how fire safety value gets captured across the equipment lifecycle. Johnson Controls International plc leverages its building automation footprint to bundle alarm monitoring with HVAC controls. Honeywell International Inc anchors its position through software-defined detection platforms that reduce false alarm rates. Gentex Corp specializes in advanced notification devices for the residential retrofit channel.
Fire safety equipment encompasses detection, suppression, and alarm systems engineered to NFPA 72 response-time thresholds and UL 268 smoke-sensing performance criteria, designed to interrupt combustion sequences before structural compromise. Sprinkler systems command the largest installed base among product types, though wireless systems within the technology dimension are expanding fastest as legacy buildings seek minimally invasive upgrades. Addressable systems concentrate margin pools in commercial spaces where zone-specific diagnostics justify premium positioning.
NFPA code cycles, OSHA workplace safety directives, and local AHJ enforcement shape product certification requirements and installation compliance across US jurisdictions. The EPA's phasedown of hydrofluorocarbon suppressants is redirecting specification toward fluorine-free alternatives in clean-agent segments. Stakeholders must weigh retrofit timing against pending refrigerant-transition deadlines and evolving smart-building integration standards.
Market Dynamics
Retrofit mandates across aging commercial building stock are compressing replacement cycles while NFPA code tightening forces simultaneous upgrades to detection, suppression, and notification tiers. Property owners face synchronized capital outlays across multiple system categories.
Growth Catalysts
- NFPA 72 Inspection Mandates:Annual testing requirements for alarm and detection systems generate recurring service revenue streams. Commercial property managers must contract certified technicians to maintain code compliance.
- Wireless Retrofit Technology:Minimally invasive installation methods reduce labor costs and tenant disruption in legacy structures. Building owners in dense urban corridors adopt these systems to avoid full rewiring.
- Texas-Florida-California Metropolitan Clusters:High construction velocity and stringent local AHJ enforcement create concentrated demand pockets. These states account for disproportionate new installation volumes.
Market Restraints
- Copper and Steel Input Volatility:Sprinkler system fabrication depends on commodity metal pricing. Manufacturers face margin compression when raw material costs spike without contract escalation clauses.
- EPA HFC Phasedown:Clean-agent suppression system specifications must transition away from hydrofluorocarbon formulations. Inventory obsolescence risk hangs over distributors with legacy product stockpiles.
- Licensed Technician Scarcity:NICET certification requirements limit the available labor pool for system installation and inspection. Project timelines stretch when qualified contractors are overcommitted.
Strategic Opportunities
- Smart Building Integration Convergence:Fire safety systems are unifying with HVAC and access control platforms through BACnet and Modbus protocols. Integrated system vendors capture larger project scopes.
- Residential Retrofit Channel:Aging single-family housing stock lacks modern detection coverage. Home improvement retailers and electrical contractors represent underdeveloped distribution paths.
- Fluorine-Free Clean Agents:EPA regulatory pressure creates specification windows for novel suppression chemistry. Early movers in fluorinated ketone and inert gas blends secure specification lock-in.
Industry Challenges
- Multi-System Integration Complexity:Addressable detection networks must interface with legacy suppression infrastructure. Commissioning delays multiply when protocols mismatch across vintages.
- AHJ Interpretation Variance:Local enforcement authorities apply NFPA codes with jurisdiction-specific stringency. National rollout strategies fragment into market-by-market compliance puzzles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fire Safety Equipment Market |
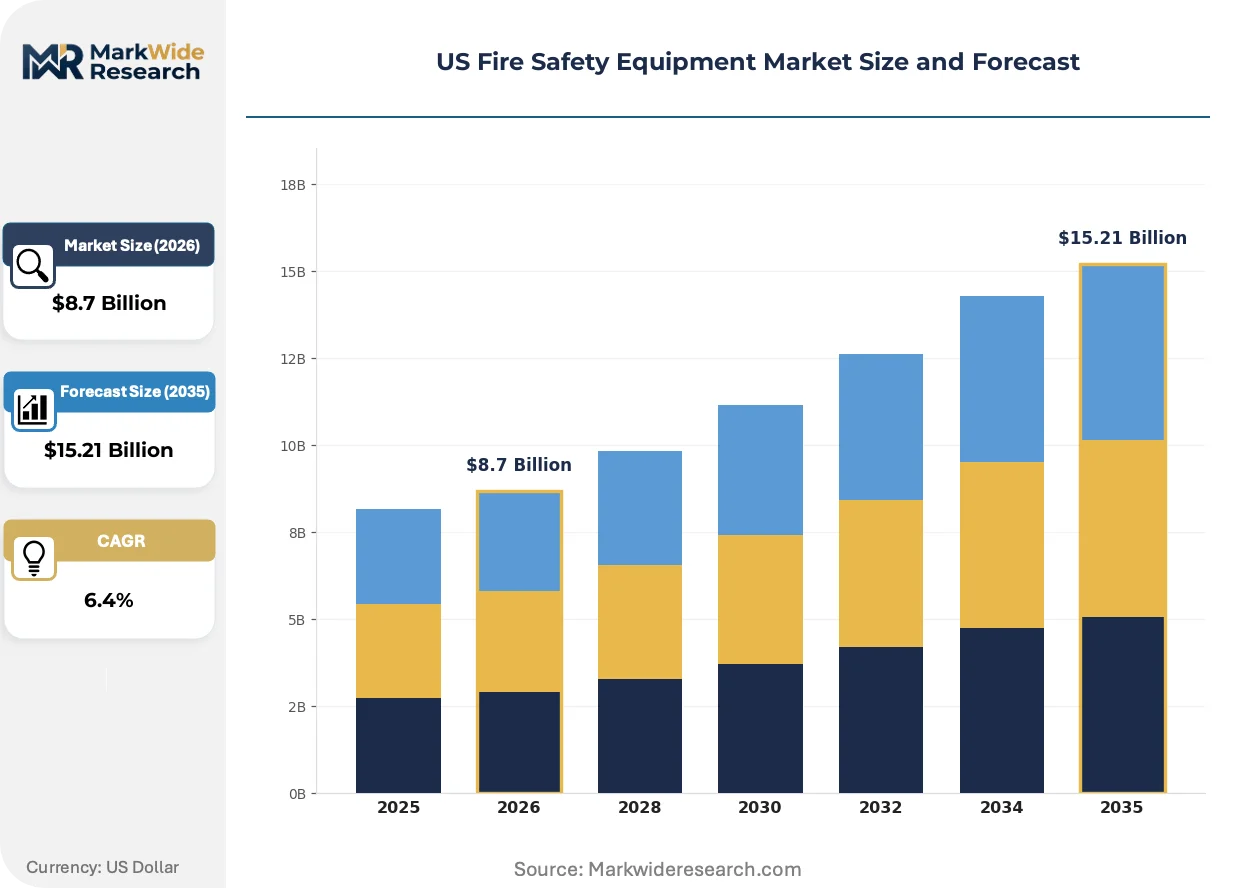
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Extinguishers, Fire Alarms, Sprinkler Systems, Fire Blankets End User: Residential Buildings, Commercial Spaces, Industrial Facilities, Educational Institutions Technology: Conventional Systems, Addressable Systems, Wireless Systems, Hybrid Systems Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | Tyco International Ltd, Siemens Building Technologies Pvt. Ltd., Johnson Controls International plc, Fike Corporation, Hochiki Corporation, Honeywell International Inc, Eaton Corporation Inc, Gentex Corp, Bosch Security System Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fire Safety Equipment Market Trends and Innovations
Detection and suppression architectures are converging around software-defined platforms that reduce hardware redundancy. This shift compresses installation footprints while expanding diagnostic granularity.
Multi-sensor detection units are unifying photoelectric, thermal, and carbon monoxide sensing in single housing. High-rise commercial developers specify these consolidated devices to reduce ceiling penetration counts and wiring runs. The technology is unifying what previously required three separate detector categories into one specification.
OSHA workplace safety directives are tightening emergency notification requirements for multi-employer sites. Industrial facilities must now deploy mass notification systems capable of reaching transient contractor populations. Manufacturing campuses in the Midwest and Gulf Coast petrochemical corridors face the steepest compliance ramps.
Facility managers are bundling inspection, monitoring, and maintenance under single-provider contracts. This consolidation displaces the fragmented vendor relationships common in legacy building operations. Healthcare and education verticals in California and Texas lead this procurement restructuring.
US Fire Safety Equipment Market Segmentation
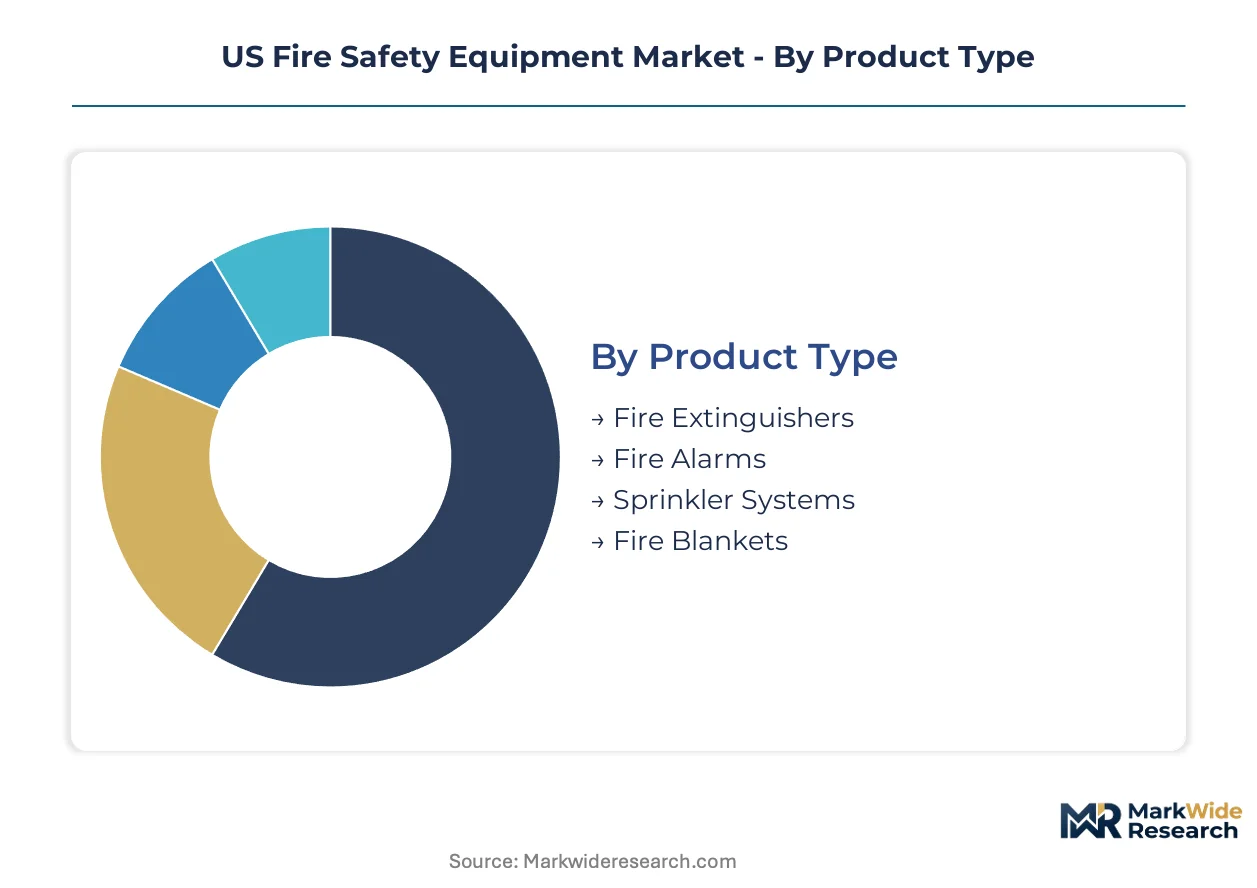
Fire safety equipment segmentation reveals how certification requirements and installation complexity fragment procurement patterns across building types. Each dimension carries distinct approval burdens that shape vendor selection and margin structures.
Product Type:
NFPA 13, NFPA 72, and UL 268 certifications impose tiered testing burdens across product categories, with suppression systems facing the most rigorous hydraulic and discharge validation protocols.
- Fire Extinguishers:Portable units require DOT transport certification and UL 299/711 testing for extinguishing agent discharge. Demand concentrates in industrial corridors across Texas and Louisiana where OSHA workplace safety inspections drive replacement cycles for petrochemical facilities.
- Sprinkler Systems:Wet-pipe, dry-pipe, and pre-action configurations dominate commercial installation specifications. California and Florida metropolitan markets absorb disproportionate volumes as seismic and hurricane-resistant design codes mandate redundant suppression infrastructure in high-rise construction.
- Fire Alarms:Notification appliances and control panels must achieve UL 864 listing for smoke and carbon monoxide detection.
- Fire Blankets:Kitchen and laboratory applications require fiberglass or wool-based heat-resistant materials meeting ASTM F1989 standards.
Sprinkler Systems sits at the top of the volume ranking, with Fire Alarms climbing the fastest.
End User:
Cost tier stratification separates specification-intensive commercial projects from price-sensitive residential retrofit decisions.
- Commercial Spaces:Office towers, retail centers, and hospitality properties demand integrated addressable systems with BACnet connectivity. Texas and California property managers face synchronized capital outlays across detection, suppression, and notification tiers as NFPA code tightening compresses replacement cycles.
- Industrial Facilities:Petrochemical plants and manufacturing campuses require specialized explosion-proof detection and clean-agent suppression. OSHA workplace safety directives in the Gulf Coast corridor mandate mass notification systems capable of reaching transient contractor populations.
- Residential Buildings:Single-family retrofits and multi-family new construction favor wireless smoke detection with minimal installation disruption.
- Educational Institutions:K-12 campuses and university dormitories require voice evacuation systems with strobe notification for ADA compliance.
Commercial Spaces commands the largest project scopes, while Residential Buildings expands most quickly through retail channel penetration.
Technology:
Application complexity determines whether buildings retain legacy conventional wiring or migrate toward addressable diagnostics.
- Addressable Systems:Zone-specific device identification enables pinpoint fault location and reduced maintenance labor. High-rise commercial developers in California and Texas specify these systems to satisfy stringent local AHJ enforcement and minimize ceiling penetration counts.
- Wireless Systems:Battery-powered or mesh-networked devices eliminate conduit runs in heritage structures. Urban corridor building owners adopt these systems to avoid full rewiring during tenant occupancy.
- Conventional Systems:Hardwired zone-based detection remains cost-effective for small-footprint applications.
- Hybrid Systems:Combinations of wired backbone with wireless extensions bridge legacy infrastructure and modern diagnostics.
Conventional Systems retains the largest installed base, with Wireless Systems gaining share fastest through minimally invasive retrofit demand.
Distribution Channel:
Customer type and purchase urgency shape whether procurement flows through stocked retail or engineered direct sales.
- Distributors:Electrical and fire protection wholesalers carry UL-listed inventory for contractor pull-through. Texas and Florida metropolitan markets concentrate distributor branch locations to serve high construction velocity corridors.
- Direct Sales:Manufacturers engage property developers and facility managers for large-scale integrated system specifications. Healthcare and education verticals in California consolidate inspection, monitoring, and maintenance under single-provider direct contracts.
- Retail:Home improvement stores and electrical supply houses serve residential replacement and small commercial retrofit demand.
- Online:E-commerce platforms facilitate standard extinguisher and detector purchases for cost-sensitive buyers.
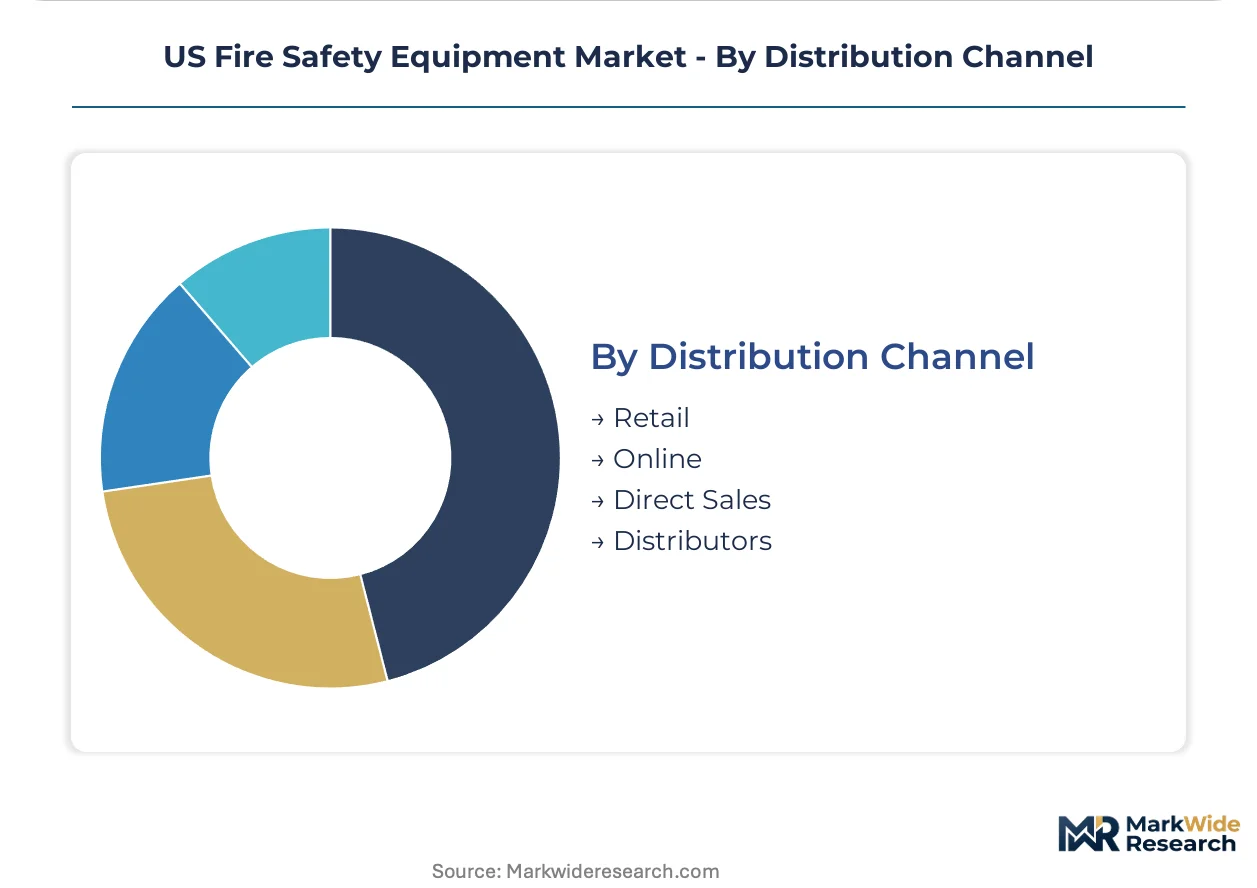
Distributors handles the highest transaction volume, with Direct Sales capturing the steepest expansion trajectory through bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas absorbs more fire safety equipment volume than any other US state, while California's seismic retrofit mandates create distinct specification pressures. Metropolitan construction corridors in Florida, the Northeast, and the Mountain West generate concentrated demand clusters with varying regulatory stringency.
Texas
Houston's petrochemical corridor and Dallas-Fort Worth commercial construction drive concentrated demand for explosion-proof detection and mass notification systems. OSHA workplace safety directives in Gulf Coast industrial zones mandate specialized contractor-alert infrastructure. Austin and San Antonio high-rise developers specify addressable systems to satisfy stringent local AHJ enforcement.
California
Seismic-resistant design codes and wildfire-prone zones accelerate sprinkler and detection system replacement cycles. The California Building Standards Commission tightens installation mandates faster than NFPA national cycles. Los Angeles and San Francisco metropolitan developers bundle fire safety with smart-building integration through BACnet protocols.
Florida
Hurricane-resistant construction codes mandate redundant suppression infrastructure in coastal high-rises. The Florida Building Commission enforces stricter notification system requirements than neighboring southeastern states. Miami and Tampa metropolitan corridors concentrate distributor branch locations to serve rapid commercial development velocity.
Northeast Corridor
Aging commercial building stock in New York and Boston compresses retrofit replacement cycles across multiple system categories. State-level environmental regulations in Massachusetts and Connecticut accelerate HFC clean-agent transitions ahead of EPA deadlines. Philadelphia and Baltimore industrial facilities face synchronized OSHA and local AHJ compliance ramps.
Mountain West
Denver and Phoenix construction booms absorb disproportionate volumes of wireless retrofit systems for minimally invasive tenant upgrades. Colorado and Arizona state fire marshals apply NFPA 72 with jurisdiction-specific inspection frequency requirements. Salt Lake City healthcare and education verticals consolidate inspection and monitoring under single-provider contracts.
US Fire Safety Equipment Market Competitive Landscape
Top-tier vendors anchor integrated system specifications, while mid-tier specialists capture niche certification segments. The vendor base stratifies across three tiers: multinational conglomerates with building automation footprints, dedicated fire safety manufacturers with UL listing depth, and regional contractors with local AHJ relationships. Two strategic archetypes dominate: bundling platforms that unify fire safety with HVAC and access control, and retrofit specialists minimizing installation disruption in heritage structures. Competitive moves concentrate on smart-building protocol integration and fluorine-free clean-agent chemistry transitions.
Within the building automation tier, Johnson Controls International plc and Honeywell International Inc exemplify platform bundling strategies. Siemens Building Technologies Pvt. Ltd. anchors European-origin multinational positioning. Gentex Corp occupies the specialized notification device segment. These three names represent divergent competitive vectors: integrated infrastructure control, software-defined detection, and residential retrofit channel focus.
| Leading Market Players |
|---|
| Tyco International Ltd |
| Siemens Building Technologies Pvt. Ltd. |
| Johnson Controls International plc |
| Fike Corporation |
| Hochiki Corporation |
| Honeywell International Inc |
| Eaton Corporation Inc |
| Gentex Corp |
| Bosch Security System Inc |
| Others |
Pricing and Supply Chain Analysis
Captive vertical integration into copper and steel fabrication anchors pricing power for sprinkler system manufacturers, while outsourced electronics assembly for detection sensors leaves that tier exposed to semiconductor foundry pricing cycles. This split supply architecture concentrates margin control with metal-forming specialists and fragments it among wireless component assemblers.
Pricing Analysis
Capacity additions in Texas and Florida metropolitan corridors are reshaping price floors for sprinkler installation contracts as local contractor density intensifies bid competition. Three-tier pricing structure across premium addressable systems, standard conventional wiring, and economy wireless retrofits separates procurement tiers by certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying because home improvement retailers are consolidating detector SKUs under private-label programs. Residential retrofit buyers exhibit the highest price sensitivity, while healthcare and education verticals accept premium positioning for integrated service contracts.
Supply Chain Analysis
Copper and steel supply rests on domestic foundries in Ohio, Pennsylvania, and Indiana, with specialty alloys for explosion-proof housings drawn from German and Japanese precision metalworkers. Electronic detection modules feed from Taiwanese semiconductor packaging facilities, while clean-agent suppressant chemicals source from Chinese and Indian specialty chemical producers. Single-source vulnerability concentrates in fluorinated ketone formulations where EPA phasedown timelines have compressed alternative qualification windows. Distribution runs through electrical wholesalers and fire protection distributors with NICET-certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US fire safety equipment market functions as a stable compounder where recurring inspection mandates under NFPA 72 generate predictable service revenue streams regardless of new construction cyclicality.
For Market Incumbents: Extend software-defined detection platforms into HVAC integration partnerships to capture smart-building convergence spend before pure-play building automation vendors consolidate the specification. Backward integration into copper fabrication insulates margin from commodity volatility, while captive technician training programs defend against NICET certification scarcity that delays project timelines. For New Entrants and Emerging Players: Launch via home improvement retail partnerships targeting the residential retrofit channel where wireless smoke detection penetration remains underdeveloped relative to commercial addressable systems. Focus initial geographic presence on Mountain West metropolitan corridors where distributor branch density lags construction velocity and local AHJ relationships remain contestable. For Investors and Strategic Acquirers: Roll-up economics work for regional fire protection contractors with deep local AHJ relationships because code interpretation variance fragments national players and rewards jurisdiction-specific expertise. Monitor EPA enforcement intensity on HFC phasedown deadlines as the inflection signal determining inventory obsolescence risk and clean-agent chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Clean-Agent Qualification | Early movers in fluorinated ketone chemistry secure specification lock-in ahead of EPA enforcement deadlines. |
| Wireless Retrofit Platform Development | Battery-powered mesh networks capture heritage building upgrades without tenant-disruptive rewiring. |
| Technician Certification Pipeline Investment | Captive NICET training programs reduce project timeline risk from licensed labor scarcity. |
| Smart Building Protocol Integration | BACnet and Modbus convergence unifies fire safety with HVAC and access control procurement decisions. |
| Residential Retail Channel Penetration | Home improvement store partnerships unlock single-family retrofit volume beyond contractor-driven commercial sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fire protection contractors, facility managers at commercial property portfolios, AHJ enforcement officials, and distributor branch managers with secondary validation against NFPA code documentation, UL certification databases, EPA regulatory filings, and construction permit data. Bottom-up installation volume estimates triangulated against top-down equipment spending flows.
Segment-weighting approaches applied differential growth assumptions across product types, end-user verticals, technology tiers, and distribution channels over the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, code mandate implementation timelines, and construction velocity correlations. Forecast inputs incorporated copper and steel price indices, NICET certification pipeline data, and local AHJ staffing levels.
Several conditions sit outside the modeled scope, including sudden NFPA code cycle acceleration, unanticipated EPA enforcement delays on HFC phasedown, and extreme commodity price spikes beyond historical volatility bands. Forecasts reflect documented assumptions about technician labor supply elasticity and wireless technology adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market