
 Fire Safety Systems Market | 2026-2036
Fire Safety Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Safety Systems Market Analysis
Data center construction is rebalancing demand toward specialized gas suppression and early-warning detection systems. Johnson Controls leverages its building automation integration to capture bundled infrastructure contracts across hyperscale facilities. Honeywell International Inc. sustains technology leadership through addressable sensor networks that reduce false alarm rates in critical environments. Siemens AG anchors European industrial demand with IEC-compliant control panels and centralized monitoring architectures.
Fire safety systems encompass engineered assemblies of detection, alarm, suppression, and evacuation equipment designed to identify ignition events within seconds and execute automated response protocols, typically operating at detection thresholds of 0.01-0.05 optical density per meter for smoke sensors. These systems serve primarily to protect life safety, preserve structural assets, and maintain operational continuity in commercial, industrial, and residential occupancies. Fire detection devices represent the fastest-expanding product category as multi-criteria sensors combining photoelectric, thermal, and carbon monoxide sensing displace single-technology units in high-value installations. Smart technology is displacing conventional wired architectures in retrofit-intensive segments, while wireless technology occupies niche applications in heritage buildings where structural modification is restricted. Commercial buildings remain the dominant application channel, though transportation infrastructure is emerging as a margin-rich segment requiring specialized flame detection and rapid flooding systems.
The National Fire Protection Association (NFPA) 72 and NFPA 13 standards govern system design and installation across North America, mandating minimum coverage densities and response times that directly determine equipment specifications and contractor qualification requirements. The EU's Construction Products Regulation (CPR) and F-Gas Regulation impose material flame-retardancy benchmarks and restrict high-global-warming-potential extinguishing agents, forcing reformulation of clean agent suppressants and recertification of existing installed bases. Stakeholders must monitor evolving refrigerant-phaseout schedules and building electrification codes that are rewriting suppression requirements for battery energy storage systems and electric vehicle charging infrastructure.
Market Dynamics
The EU F-Gas Regulation is forcing rapid reformulation of clean agent suppressants while data center construction concentrates demand for specialized gas suppression technologies in hyperscale facilities.
Growth Catalysts
- Industrial Retrofit Mandates:Germany's building code enforcement triggers replacement cycles across manufacturing facilities and logistics hubs, accelerating equipment turnover.
- Battery Energy Storage Proliferation:Electrification codes for lithium-ion installations mandate specialized detection and suppression architectures in utility-scale storage projects.
- Multi-Criteria Sensor Adoption:Photoelectric-thermal-CO2 sensor fusion reduces false alarm rates in critical environments, driving premium equipment specification.
Market Restraints
- Clean Agent Supply Concentration:Three chemical manufacturers control fluorinated ketone and HFC-227ea production, creating price volatility and allocation risk.
- Copper and Rare Earth Input Costs:Sensor assemblies and control panel wiring face commodity price swings that compress installer margins.
- Certification Timeline Friction:UL and FM Global testing protocols extend product launch cycles by 18-24 months for novel suppression agents.
Strategic Opportunities
- Wireless Retrofit Penetration:Heritage building restrictions on structural modification create demand for battery-powered detection networks in European historic districts.
- Transportation Infrastructure:Tunnel and rail systems require specialized flame detection and rapid flooding systems with shorter replacement cycles than commercial buildings.
- Service Contract Unbundling:After-sales maintenance and monitoring subscriptions separate from equipment sales, generating recurring revenue streams.
Industry Challenges
- Addressable System Integration:Legacy hardwired installations resist migration to networked architectures without full building rewiring.
- Cross-Discipline Technician Scarcity:Installation crews must combine electrical, networking, and suppression expertise that training pipelines fail to produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Safety Systems Market |
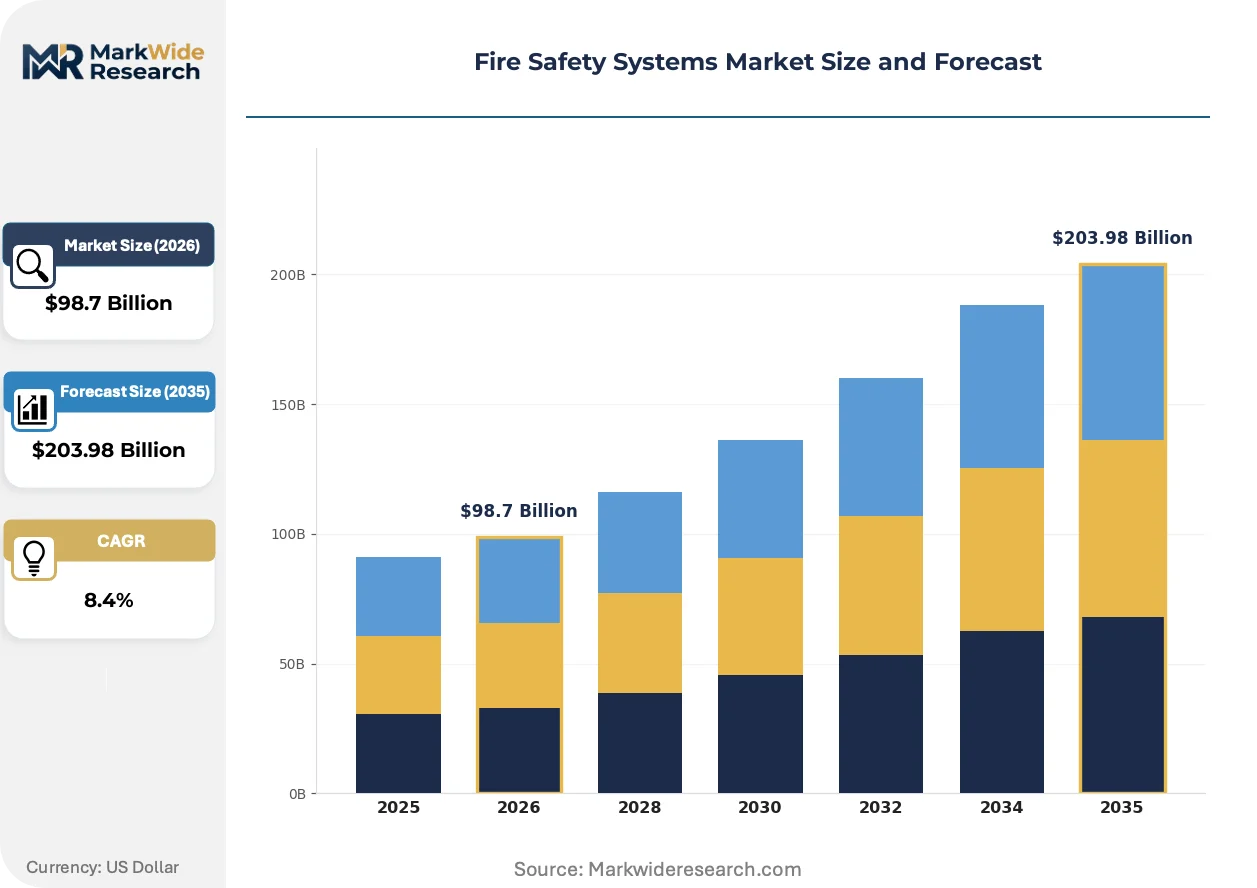
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Alarm Systems, Fire Sprinkler Systems, Extinguishing Systems, Fire Detection Devices Technology: Conventional Technology, Addressable Technology, Wireless Technology, Smart Technology Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Transportation End User: Government, Education, Healthcare, Retail |
| Companies Covered | Johnson Controls, Honeywell International Inc., Siemens AG, Robert Bosch GmbH, Gentex Corporation, Halma plc, Eaton, Carrier Global Corporation, Hochiki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Safety Systems Market Emerging Trajectories
Detection architectures are converging with building management systems while suppression chemistry undergoes forced transition away from high-global-warming-potential formulations.
Artificial intelligence inference at the edge is electrifying smoke detection by enabling pattern recognition that distinguishes between actual combustion and nuisance sources like steam or dust. Data center operators deploy these sensors most aggressively, accepting 40% unit cost premiums for 90% false alarm reduction. The technology is compressing maintenance dispatch frequency and insurance premium structures for critical facilities.
REACH and the EU F-Gas Regulation are accelerating phaseout schedules for HFC-based clean agents, compelling suppressant manufacturers to commercialize fluorinated ketone and inert gas alternatives. Industrial users face recertification costs for installed bases while new construction specifications pivot toward lower-global-warming-potential formulations. German chemical registrants under ECHA oversight lead alternative formulation development.
Integrated service agreements now bundle detection hardware, cloud monitoring, and response dispatch into single contracts that displace traditional equipment-plus-installation procurement. Facility management outsourcing firms in the United States and United Kingdom adopt these arrangements most rapidly, transferring operational risk to system vendors. The model concentrates vendor selection authority with national account teams rather than local contractors.
Fire Safety Systems Market Segmentation
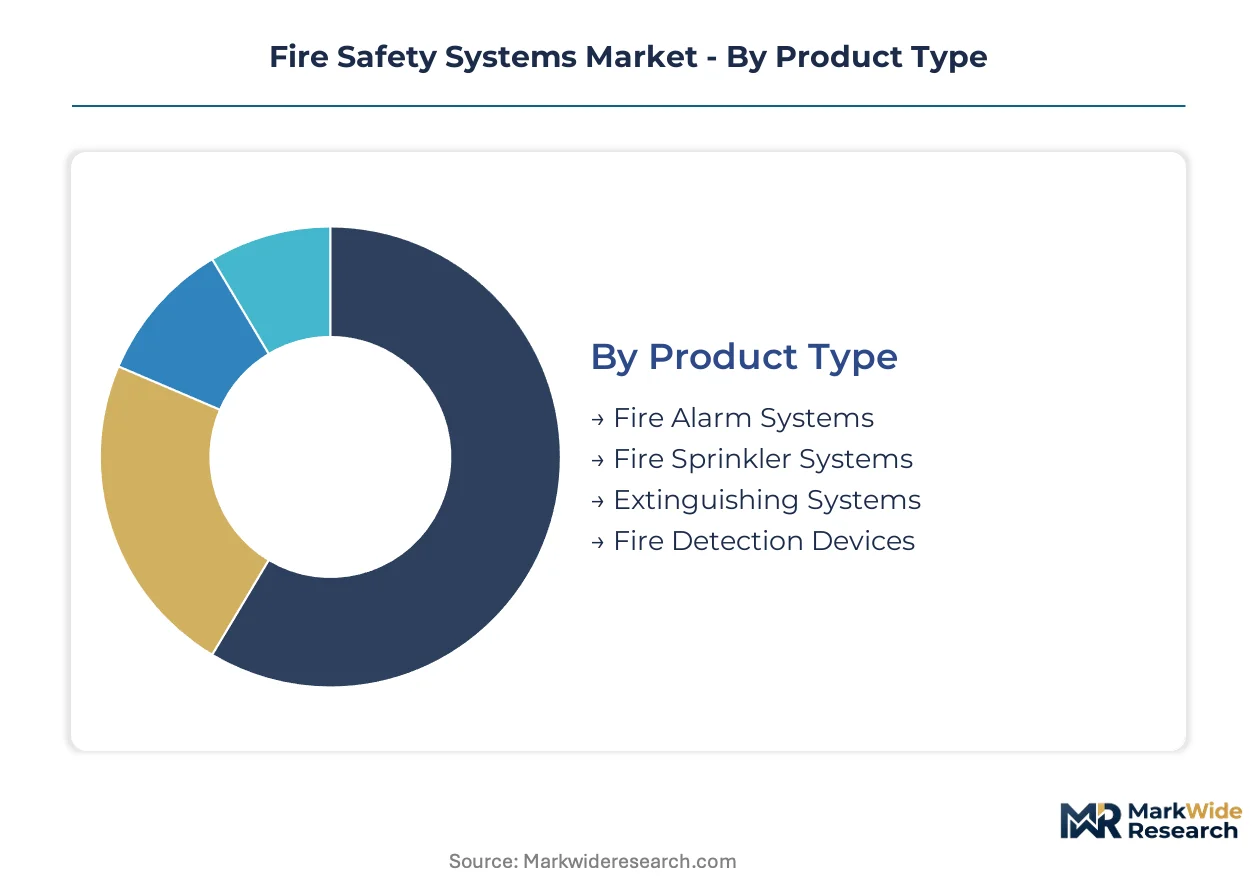
Fire safety procurement splits sharply between retrofit infrastructure and new construction specifications. Equipment selection hinges on detection sensitivity requirements, suppression chemistry constraints, and integration depth with building automation platforms.
Product Type:
Supply concentration in clean agent chemistry and sensor manufacturing concentrates margin capture among integrated system vendors rather than component specialists.
- Fire Alarm Systems:Audible and visual notification appliances integrated with control panels and manual pull stations. Demand clusters in Germany's industrial retrofit mandates and hyperscale data center construction across Ireland and the Netherlands, driven by NFPA 72 compliance timelines and EU CPR flame-retardancy certification.
- Fire Sprinkler Systems:Wet pipe, dry pipe, and pre-action configurations using steel or CPVC piping with fusible element or glass bulb activation. Commercial high-rise construction in Frankfurt and Munich sustains specification volume despite slower growth in residential applications.
- Extinguishing Systems:Gaseous, foam, and water mist suppression architectures. REACH and EU F-Gas Regulation phaseouts are forcing reformulation toward fluorinated ketone and inert gas alternatives.
- Fire Detection Devices:Smoke, heat, flame, and gas sensors operating at 0.01-0.05 optical density thresholds. Multi-criteria sensor fusion is gaining share fastest in critical environments accepting 40% unit cost premiums for false alarm reduction.
Today's leader: Fire Sprinkler Systems. Tomorrow's challenger: Fire Detection Devices.
Technology:
Cost tier stratification separates premium addressable architectures from economy conventional installations, with wireless occupying a narrow mid-tier niche constrained by battery maintenance burdens.
- Conventional Technology:Hardwired zone-based detection with limited individual device identification. Legacy manufacturing facilities in eastern Germany retain these systems where full rewiring costs exceed replacement benefits.
- Addressable Technology:Digital communication protocols enabling individual device polling and precise fault location. Data center operators in Frankfurt, Amsterdam, and Dublin specify these networks for reduced maintenance dispatch frequency and insurance premium compression.
- Wireless Technology:Battery-powered detection networks using mesh or star topologies. Heritage building restrictions in Prague, Vienna, and Florence sustain demand where structural modification is prohibited.
- Smart Technology:Edge AI inference enabling pattern recognition between combustion and nuisance sources. This segment climbs the fastest as facility management outsourcing firms in the United Kingdom and United States adopt integrated service agreements bundling hardware, cloud monitoring, and response dispatch.
Conventional Technology still dominates installed base volume. Smart Technology commands the steepest expansion trajectory through bundled service contracts.
Application:
Volume concentration in commercial construction masks margin superiority in specialized transportation and industrial segments requiring rapid flooding and flame detection capabilities.
- Residential Buildings:Single and multi-family dwellings with basic smoke alarm and sprinkler requirements. Germany's building code enforcement accelerates replacement cycles in older housing stock.
- Commercial Buildings:Offices, retail, hospitality, and institutional facilities with integrated detection and suppression. This application captures the largest revenue share through high-rise construction density in Frankfurt, Munich, and Hamburg.
- Industrial Facilities:Manufacturing plants, warehouses, and energy infrastructure with specialized hazard protection. Battery energy storage proliferation is mandating new detection architectures for lithium-ion installations.
- Transportation:Tunnels, rail systems, airports, and maritime vessels requiring rapid response and harsh environment durability. Shorter replacement cycles and specialized flame detection specifications generate premium margins.
Commercial Buildings anchor current procurement volume. Transportation infrastructure presents the most attractive margin expansion opportunity.
End User:
Customer type determines procurement authority concentration, with government and healthcare centralizing vendor selection through national account frameworks while retail fragments across local contractor relationships.
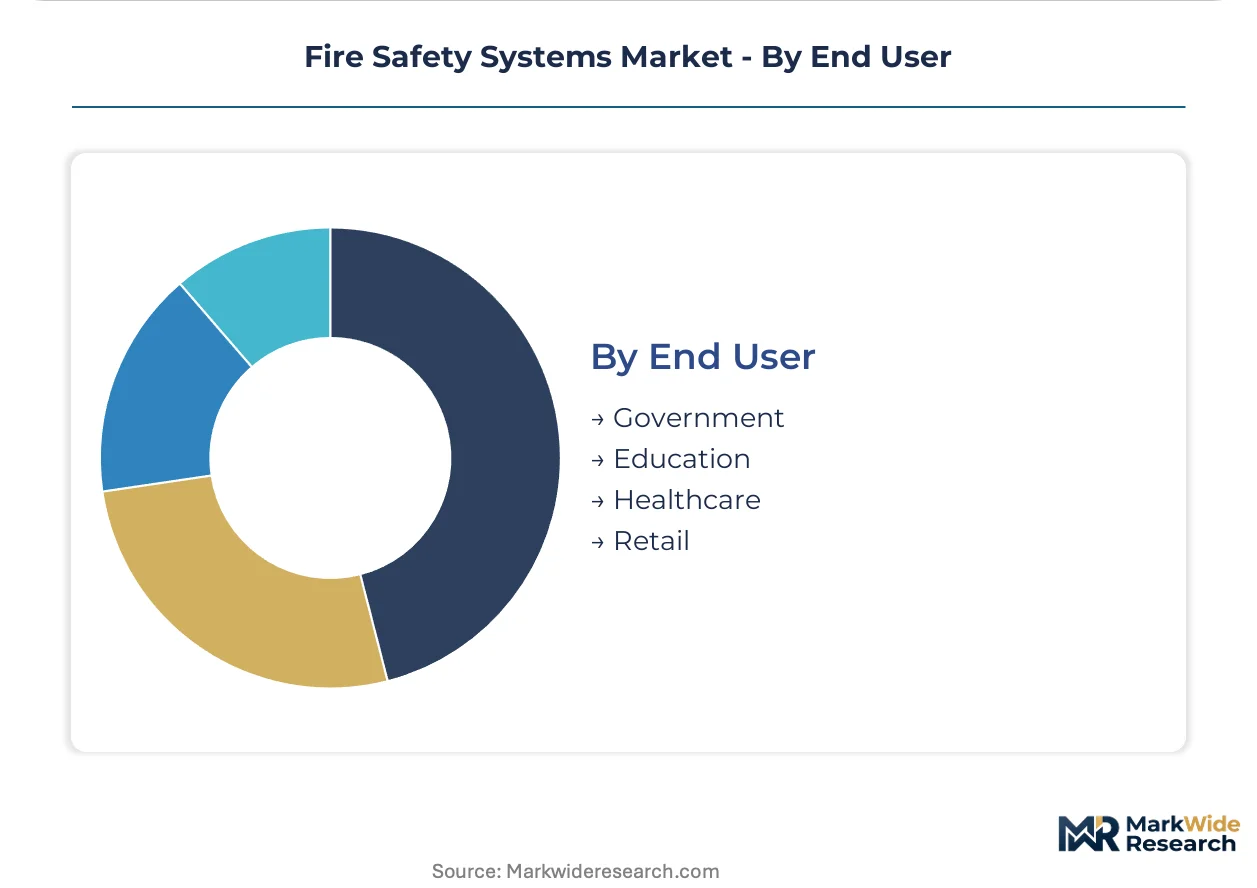
- Government:Federal, state, and municipal facilities with mandated compliance schedules. German federal building renovation programs concentrate specification authority with integrated system vendors.
- Education:K-12 and university campuses with dormitory and laboratory hazard profiles. Campus consolidation in the United Kingdom is shifting procurement toward regional framework agreements.
- Healthcare:Hospitals and long-term care facilities requiring uninterrupted operations and patient evacuation protocols. Infection control requirements intersect with fire safety in German and French hospital construction.
- Retail:Big-box stores, shopping centers, and hospitality venues with high occupancy turnover. Franchise operators in Spain and Italy favor standardized specifications across property portfolios.
Government procurement commands the largest contract values. Healthcare facilities offer the most defensible margins through operational continuity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping procurement patterns as manufacturers migrate production to jurisdictions with lower compliance burdens while specification authority concentrates in high-standard markets. The EU F-Gas Regulation and REACH impose steep reformulation costs that advantage domestic European producers with established ECHA registration pathways.
Germany
Industrial retrofit mandates under the federal building code trigger replacement cycles across manufacturing facilities and logistics hubs. ECHA oversight of chemical registrants accelerates alternative suppressant formulation development. Frankfurt, Munich, and Hamburg anchor specification volume through high-rise construction density and hyperscale data center clusters.
United States
NFPA 72 and NFPA 13 compliance timelines drive equipment turnover in commercial and institutional stock. Facility management outsourcing firms in the United States adopt integrated service agreements bundling hardware, cloud monitoring, and response dispatch. Data center construction in Northern Virginia and Dallas-Fort Worth concentrates demand for specialized gas suppression technologies.
China
GB standards for fire safety equipment tighten detection sensitivity and response time requirements in high-occupancy buildings. MIIT industrial policy supports domestic sensor manufacturing capacity expansion. Yangtze River Delta manufacturing clusters supply photoelectric and thermal sensor assemblies to regional system integrators.
United Kingdom
Campus consolidation in higher education shifts procurement toward regional framework agreements with standardized specifications. The UK's building safety regulator enforces enhanced evacuation protocol requirements in high-rise residential construction. London and Southeast England concentrate healthcare facility renovation programs with infection control intersecting fire safety specifications.
Japan
METI building energy codes intersect with fire safety requirements in dense urban construction. JIS standards govern sensor performance thresholds in commercial and transportation applications. Kanto and Kansai metropolitan areas sustain demand for addressable detection networks in retrofit-intensive commercial districts.
Fire Safety Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors capturing margin in bundled infrastructure contracts while component specialists face commoditization pressure. The vendor base organizes into three tiers: multinational conglomerates with building automation platforms, regional specialists with certification depth in local codes, and OEM fabricators supplying private-label detection hardware. Tier-one players defend position through M&A to acquire sensor technology assets and cloud monitoring capabilities. Geographic expansion into data center construction clusters represents the second dominant competitive vector.
Within the multinational conglomerate tier, Johnson Controls, Honeywell International Inc., and Siemens AG exemplify the integrated platform model that bundles detection, suppression, and building automation across hyperscale facilities. These entities anchor specification authority through national account frameworks with facility management outsourcing firms and government procurement programs. Regional specialists occupy positions defined by IEC and NFPA certification depth in European and North American industrial retrofit cycles.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International Inc. |
| Siemens AG |
| Robert Bosch GmbH |
| Gentex Corporation |
| Halma plc |
| Eaton |
| Carrier Global Corporation |
| Hochiki Corporation |
| Others |
Supply Flow & Price Mechanics
Edge AI inference migration in detection hardware simultaneously compresses unit economics and concentrates component sourcing among semiconductor foundries with mature automotive-grade certification. This technology shift rewards integrated vendors bundling cloud monitoring with sensor hardware while squeezing standalone equipment margins.
Pricing Analysis
Distributor margins in fire safety equipment typically span fifteen to twenty-five percent, with direct-to-OEM contracts commanding steeper discounts for hyperscale data center bundles. Three-tier pricing structure across premium, standard, and economy levels separates addressable smart systems from conventional wired architectures, with certification grade serving as the primary price differentiation driver. Cost compression in conventional technology tiers is intensifying because copper and rare earth input volatility compresses installer margins. Municipal government procurement exhibits the highest price sensitivity, while healthcare facilities accepting operational continuity premiums show the least.
Supply Chain Analysis
Dual-sourcing requirements for critical sensor assemblies and clean agent suppressants mandate multi-supplier qualification across German chemical registrants, Chinese photoelectric component manufacturers, and Japanese thermal sensor specialists. Raw material dependencies center on copper wiring, rare earth elements for magnetic components, and fluorinated ketone precursor chemicals. Single-source vulnerability in HFC-227ea and fluorinated ketone production creates allocation risk during regulatory transition periods. Distribution runs through specialized fire protection distributors and direct national account channels with facility management outsourcing firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire safety systems procurement operates as a geographic-arbitrage play where ECHA-registered European suppressant suppliers capture premium pricing against Asian competitors facing REACH compliance cost disadvantages.
For Market Incumbents: Cement specification authority through backward integration into sensor semiconductor sourcing and captive cloud monitoring platform development. Emerging wireless retrofit specialists threaten regional market share in heritage building segments. Certification investment in IEC-compliant control panels anchors European industrial retrofit cycles.
For New Entrants and Emerging Players: Battery-powered mesh detection networks offer a technology-first wedge into European historic districts where structural modification restrictions block incumbent wired solutions. The most penetrable segment clusters in Prague, Vienna, and Florence heritage building authorities. A direct municipal sales model bypasses established distributor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with deep NFPA and IEC certification portfolios but limited cloud monitoring capabilities. Long-term viability favors vendors controlling both detection hardware and integrated service agreement revenue streams. The signal to watch is consolidation activity among facility management outsourcing firms centralizing vendor selection authority.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Sensor Technology Assets | Edge AI inference capabilities differentiate premium detection hardware in data center specifications. |
| Cloud Monitoring Platform Integration | Recurring service revenue streams displace transactional equipment sales in facility management outsourcing contracts. |
| ECHA-Compliant Suppressant Formulation | REACH and F-Gas Regulation phaseouts mandate alternative chemistry registration for European market access. |
| National Account Framework Expansion | Direct relationships with hyperscale data center operators concentrate procurement authority with integrated system vendors. |
| Wireless Retrofit Certification Investment | Battery-powered mesh networks unlock heritage building segments where structural modification is prohibited. |
Methodological Framework
Direct dialogue with fire protection system integrators, facility management outsourcing executives, ECHA regulatory affairs specialists, and industrial plant safety officers grounded qualitative findings. Secondary validation drew from NFPA technical standards documentation, EU Construction Products Regulation filings, SEC 10-K disclosures of listed equipment manufacturers, and customs trade data for suppressant chemical flows. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchored market sizing.
Segment-level projections across product type, technology architecture, application vertical, and end-user category fed into the analytical framework over the projection horizon. CAGRs were derived from regression analysis against construction spending indices and regulatory compliance timeline modeling. Battery energy storage system penetration rates and data center capex trajectories served as industry-specific forecast inputs.
The model holds under stable regulatory phaseout schedules and continued data center construction momentum; deviation in F-Gas Regulation enforcement timing or lithium-ion incident frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Global Fire Barrier Sealant Market