
 Fire Protection Systems for Industrial Cooking Market | 2026-2036
Fire Protection Systems for Industrial Cooking Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Protection Systems for Industrial Cooking Market Analysis
UL 300 certification for wet chemical suppression systems is redrawing competitive boundaries in commercial kitchen fire protection. Ansul Incorporated leverages its captive distribution network to dominate replacement parts and service contracts. Hochiki Corporation specializes in multi-sensor detection arrays that integrate heat and flame sensing for high-volume frying operations. Johnson Controls International plc anchors its position through backward integration into control panel manufacturing and in-house production of actuation hardware.
Fire protection systems for industrial cooking encompass fixed suppression, detection, and alarm assemblies engineered to extinguish Class K and grease-fueled fires in commercial food preparation environments, typically employing wet chemical agents with saponification temperatures below 500°F to form oxygen-barrier foam blankets over burning lipids. Chemical suppression systems command the dominant share of installed value due to mandatory UL 300 compliance in North American commercial kitchens, while multi-sensor detectors represent the fastest-expanding detection category as operators seek to reduce false alarms in high-particulate cooking atmospheres. Food processing plants generate the most concentrated demand by end user segment because continuous-batch frying lines carry catastrophic fire exposure and insurers require redundant suppression zones.
NFPA standards, UL listing requirements, and EN 54 fire detection norms collectively shape product design cycles and market access conditions across major jurisdictions. The EPA regulates discharge of perfluorinated suppression chemistries, forcing reformulation toward fluorine-free alternatives in systems bound for US installations. Stakeholders must monitor evolving state-level amendments to NFPA 96 that shorten mandatory inspection windows, as these intervals directly determine recurring service revenue pools and retrofit timing.
Market Dynamics
UL 300 certification mandates are compressing replacement cycles for wet chemical suppression systems across commercial kitchen portfolios, forcing operators to accelerate capital deployment or face insurance cancellation.
Growth Catalysts
- NFPA 96 Inspection Compression:North American jurisdictions are shortening mandatory grease duct inspection intervals from annual to semi-annual cycles, directly expanding recurring service revenue pools.
- Quick-Service Restaurant Automation:Chain operators retrofitting legacy kitchens with automated suppression triggers are driving replacement demand for non-compliant legacy systems.
- Class K Saponification Chemistry:Wet chemical agents with sub-500°F foam-forming temperatures are becoming mandatory for high-volume frying operations, eliminating dry chemical alternatives.
Market Restraints
- Fluorine-Free Reformulation Costs:EPA discharge restrictions on perfluorinated suppression chemistries are forcing costly agent reformulation without performance guarantees.
- Specialized Installation Labor Scarcity:Certified kitchen suppression technicians concentrate in metropolitan corridors, extending project timelines in secondary markets.
- Legacy Hood Integration Friction:Retrofit installations face structural incompatibility with pre-2000 exhaust hood configurations, requiring complete duct replacement.
Strategic Opportunities
- Multi-Sensor Detection Convergence:Heat-flame-particulate sensor arrays are penetrating high-volume frying environments where false alarm rates previously blocked adoption.
- Food Processing Plant Redundancy Mandates:Insurers are requiring dual-zone suppression for continuous-batch frying lines, doubling installed value per production site.
- Service Contract Unbundling:Third-party service providers are capturing inspection and recharge work previously captive to original equipment manufacturers.
Industry Challenges
- UL 300 Recertification Timelines:Wet chemical system redesigns face extended listing approval periods, delaying product launches by 12-18 months.
- Cross-System Integration Complexity:Kitchen suppression networks must interface with building-wide alarm panels, creating protocol translation failures during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Protection Systems for Industrial Cooking Market |
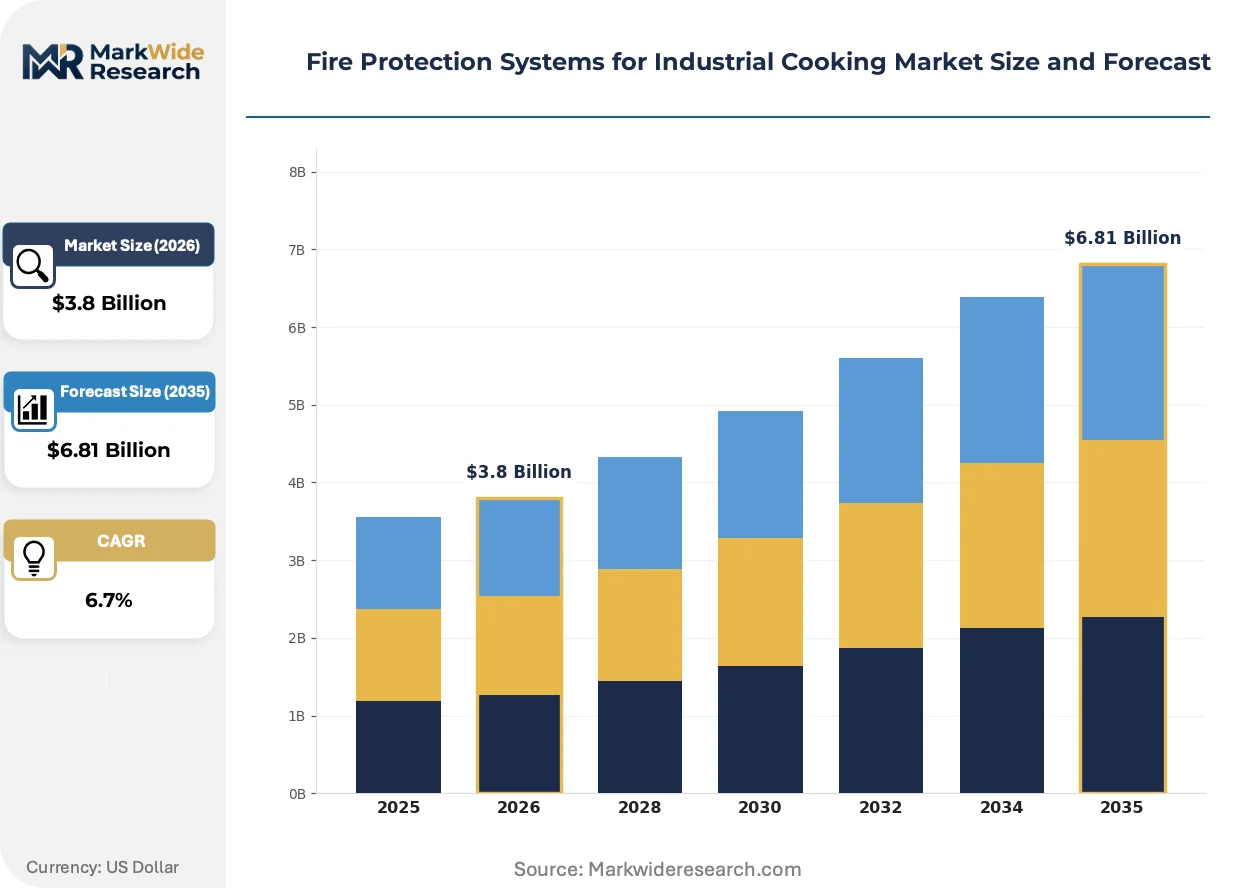
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Water Sprinkler, Foam System, Chemical Suppression, Dry Powder System Fire Detection Technology: Heat Sensors, Smoke Detectors, Flame Detectors, Multi-Sensor Detectors End User Segment: Restaurants, Catering Services, Food Processing Plants, Industrial Bakeries Compliance Standards: NFPA, UL Listed, EN Standards, Local Fire Codes |
| Companies Covered | Johnson Controls International plc, Honeywell International Inc., Ansul Incorporated, Siemens AG, Halma plc, Emerson Electric Company, API Group Inc., Hochiki Corporation, Amerex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Protection Systems for Industrial Cooking Market Emerging Trajectories
Detection and suppression architectures are converging around sensor fusion and predictive activation, replacing single-point trigger systems with networked response protocols that anticipate fire events before visible flame emergence.
Fluorine-free wet chemical formulations are decomposing the established agent supply structure by eliminating perfluorinated compound dependencies that dominated UL 300-compliant systems for two decades. Major quick-service chains in California and New York are piloting these reformulations under accelerated insurer review timelines. The shift is compressing margins for incumbent chemical suppliers while opening formulation partnerships with specialty surfactant producers.
REACH restrictions on persistent organic pollutants are extending to imported suppression equipment bound for European commercial kitchens, requiring substance disclosure documentation across entire agent supply chains. German and French regulators are enforcing these provisions through customs inspection protocols that delay non-compliant shipments. Kitchen equipment distributors are responding by dual-sourcing UL-listed and CE-marked suppression systems from separate manufacturing lines.
After-sales service unbundling is fragmenting the traditional manufacturer-captive model as independent inspection contractors capture grease duct cleaning and agent recharge work. Restaurant franchisees in Texas and Florida are sourcing these services through facility management platforms rather than original system vendors. The pattern is most pronounced in multi-site operators with centralized procurement functions that treat suppression maintenance as commodity spend.
Fire Protection Systems for Industrial Cooking Market Segmentation
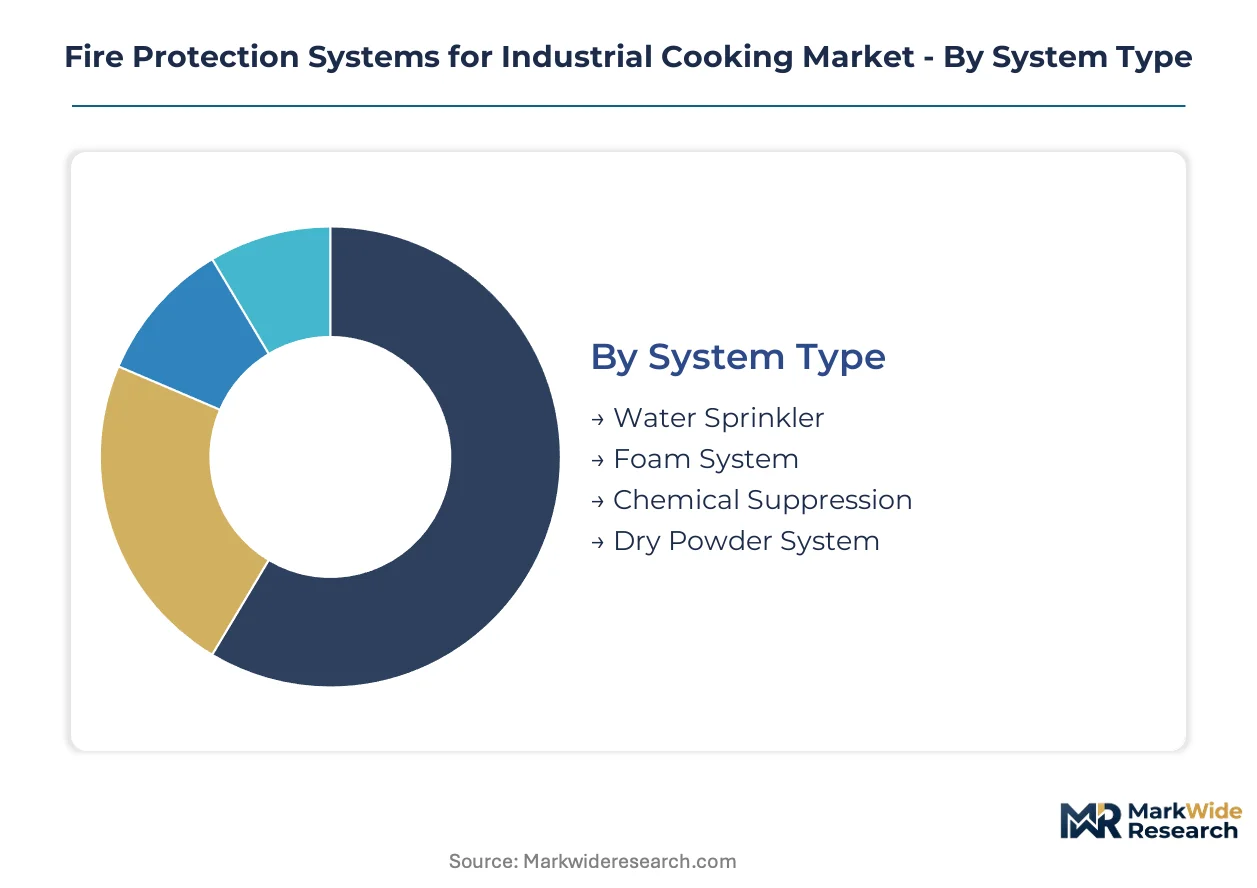
Segmentation in fire protection for industrial cooking reveals how UL 300 mandates and NFPA 96 inspection cycles concentrate value in specific system configurations. Channel flows differ sharply between replacement parts for existing kitchens and new installations in greenfield food processing facilities.
System Type:
Distribution channels bifurcate between OEM-captive service networks for chemical systems and open procurement for water-based alternatives.
- Chemical Suppression:Wet chemical agents engineered for saponification temperatures below 500°F form oxygen-barrier foam blankets over burning lipids. Quick-service restaurant chains in the United States drive replacement volume as insurers mandate UL 300 compliance for policy renewal.
- Water Sprinkler:Conventional sprinkler heads deliver deluge flow rates unsuited for grease-fueled Class K fires, limiting deployment to auxiliary protection zones rather than cooking line primary suppression. Secondary market positioning restricts pricing power.
- Foam System:Aqueous film-forming foam variants serve aircraft galley and marine galley niches where space constraints override chemical system footprint requirements.
- Dry Powder System:Sodium bicarbonate-based dry chemical installations persist in legacy industrial bakeries with pre-2000 equipment grandfathered under older fire codes.
By volume, chemical suppression leads. By growth pace, foam systems are climbing the fastest in specialized transport catering applications.
Fire Detection Technology:
Cost tiers separate premium multi-sensor arrays from commodity heat detection in high-particulate cooking atmospheres.
- Multi-Sensor Detectors:Integrated heat-flame-particulate arrays reduce false alarm rates that previously blocked adoption in high-volume frying environments. Food processing plants with continuous-batch lines generate concentrated demand as insurers require redundant detection zones.
- Heat Sensors:Fixed-temperature and rate-of-rise thermocouples dominate budget retrofit installations where legacy control panel compatibility constrains technology selection.
- Flame Detectors:Ultraviolet and infrared optical sensors serve open-flame cooking applications in ethnic cuisine restaurants with visible flame exposure.
- Smoke Detectors:Photoelectric and ionization technologies face particulate interference in grease-laden atmospheres, restricting deployment to non-cooking ancillary spaces.
By installed base, heat sensors dominate. By expansion trajectory, multi-sensor configurations are gaining share fastest.
End User Segment:
Application severity determines specification grade, with catastrophic exposure sites commanding premium system configurations.
- Food Processing Plants:Continuous-batch frying lines carry catastrophic fire exposure with lipid volumes exceeding 10,000 gallons in single production zones. Insurers mandate dual-zone suppression redundancy, doubling installed value per site.
- Restaurants:Quick-service chains accelerate automated suppression retrofits while independent operators delay replacement until insurance cancellation threats force compliance.
- Catering Services:Mobile and temporary kitchen configurations drive demand for portable suppression modules with rapid deployment capabilities.
- Industrial Bakeries:Oven fire risks from accumulated flour dust and lubricating oils sustain steady replacement demand for dry chemical legacy systems.
By revenue concentration, food processing plants lead. By retrofit velocity, restaurants are expanding most quickly.
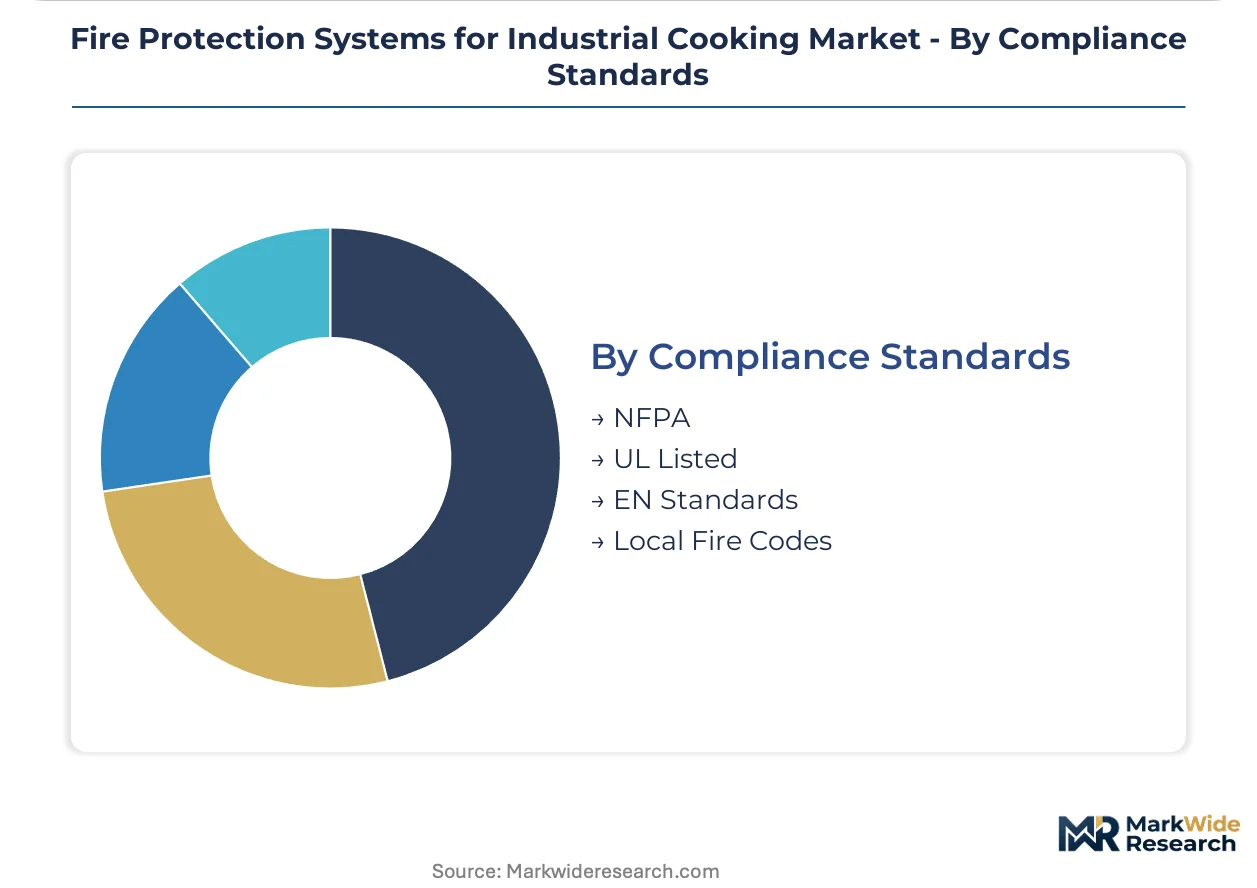
Compliance Standards:
Geographic scope of certification determines market access, with multi-standard products commanding procurement preference from multinational operators.
- UL Listed:Underwriters Laboratories certification for wet chemical suppression systems constitutes mandatory market entry for North American commercial kitchen sales. UL 300 recertification timelines extend product launch windows.
- NFPA:National Fire Protection Association grease duct standards govern inspection intervals that directly determine recurring service revenue pools across United States jurisdictions.
- EN Standards:European Norm fire detection and suppression provisions apply to commercial kitchens across EU member states, with REACH substance disclosure requirements extending to imported agent supply chains.
- Local Fire Codes:Municipal amendments to national standards create fragmentation in inspection intervals and agent discharge regulations.
By enforcement weight, UL Listed dominates North American procurement. By regulatory expansion, EN Standards are broadening fastest across European commercial kitchen mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance underwriters in the United States are mandating UL 300-compliant suppression retrofits, compressing replacement cycles for commercial kitchen operators. Germany's REACH enforcement on perfluorinated chemistries is accelerating fluorine-free agent reformulation timelines. Japan's METI fire safety guidelines are tightening detection standards for high-volume frying environments.
United States
Quick-service restaurant chains in Texas and Florida are expanding automated suppression retrofits to avoid policy cancellations. NFPA 96 grease duct standards now drive semi-annual inspection cycles in California and New York. The Dallas-Fort Worth metroplex concentrates demand for certified kitchen suppression technicians as chain operators centralize procurement.
Germany
Industrial bakeries in Bavaria sustain replacement demand for legacy dry chemical systems under grandfathered fire codes. ECHA substance disclosure requirements are extending to imported suppression equipment through customs inspection protocols. The Stuttgart industrial corridor hosts dual-sourcing distributors managing separate UL-listed and CE-marked manufacturing lines.
Japan
Food processing plants in Osaka Prefecture require redundant suppression zones for continuous-batch frying lines under insurer mandates. METI fire detection guidelines are converging with JIS standards for multi-sensor arrays in high-particulate environments. The Nagoya manufacturing belt concentrates OEM-captive service networks for wet chemical system maintenance.
United Kingdom
Independent restaurant operators in Greater London delay suppression system replacement until enforcement threats force compliance. Local fire authority amendments to national standards create inspection interval fragmentation across municipal jurisdictions. The Midlands industrial zone generates concentrated demand for food processing plant dual-zone suppression configurations.
China
Export-oriented kitchen equipment manufacturers in Guangdong Province are adapting product lines for REACH-compliant European shipments. GB standards for commercial kitchen fire safety are tightening alignment with IEC detection norms. The Yangtze River Delta hosts formulation partnerships between suppression system assemblers and specialty surfactant producers.
Fire Protection Systems for Industrial Cooking Market Vendor Landscape
Player mix skews toward diversified fire safety conglomerates with captive distribution networks and specialized detection technology developers. Market structure concentrates around three archetypes: integrated building systems providers controlling actuation hardware manufacturing, wet chemical specialists dominating replacement parts and service contracts, and multi-sensor detection array developers serving high-volume frying operations. Competitive moves center on backward integration into control panel production and geographic expansion through facility management platform partnerships.
Within the integrated systems tier, Johnson Controls International plc and Honeywell International Inc. exemplify the archetype of building technology conglomerates with in-house manufacturing capabilities. Ansul Incorporated anchors the wet chemical specialization vector. Hochiki Corporation occupies a position among detection technology developers. Siemens AG and Halma plc represent European-headquartered competitors with multi-jurisdictional certification portfolios.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Honeywell International Inc. |
| Ansul Incorporated |
| Siemens AG |
| Halma plc |
| Emerson Electric Company |
| API Group Inc. |
| Hochiki Corporation |
| Amerex Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with take-or-pay clauses lock in recurring revenue streams for wet chemical system providers while insulating buyers from spot-price volatility in fluorine-free agent markets. These arrangements concentrate pricing power with OEM-captive networks in the United States, where NFPA 96 inspection mandates guarantee demand visibility across multi-year horizons.
Pricing Analysis
Certification level creates the primary spread between UL 300-listed wet chemical systems and non-compliant legacy alternatives. Project-based pricing dominates system installations, with premium tiers commanded by dual-zone suppression configurations for food processing plants. Price compression runs through standard-tier chemical agents as EPA discharge restrictions force costly reformulation without performance guarantees. Quick-service restaurant chains exhibit highest price sensitivity due to centralized procurement treating suppression maintenance as commodity spend, while food processing plants prioritize redundancy over unit cost.
Supply Chain Analysis
Strategic stockpiling of wet chemical agents prevails among US distributors facing extended UL 300 recertification timelines that stretch 12-18 months. Manufacturing concentrates in the United States, Germany, and Japan, with control panel assembly anchored in the Nagoya manufacturing belt and agent formulation centered on specialty surfactant producers in the Yangtze River Delta. Supply chain risk hinges on single-source vulnerability for perfluorinated compound alternatives as REACH enforcement tightens substance disclosure requirements. Distribution runs through OEM-captive service networks for chemical systems and open procurement channels for detection hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is entering a cyclical recovery phase driven by compressed replacement cycles as NFPA 96 inspection intervals tighten across North American jurisdictions.
For Market Incumbents: Shield service contract revenue pools from third-party unbundling by deepening backward integration into control panel manufacturing and actuation hardware production. Capture inspection and recharge work through facility management platform partnerships rather than ceding ground to independent contractors. Prioritize certification investment in multi-sensor detection arrays to defend against specialty technology developers penetrating high-volume frying environments. For New Entrants and Emerging Players: Anchor in secondary US metropolitan corridors where certified kitchen suppression technician scarcity extends project timelines and creates service gaps for agile regional providers. Target fluorine-free agent formulation partnerships with quick-service chains in California and New York piloting accelerated insurer review timelines. Pursue white-label supply agreements with export-oriented kitchen equipment manufacturers in Guangdong Province adapting product lines for REACH-compliant European shipments. For Investors and Strategic Acquirers: Capital is best deployed toward detection technology developers with multi-sensor fusion capabilities and established JIS or EN 54 certification pathways. Long-term viability over a 5-10 year horizon rests on convergence between suppression and building management systems integration. The signal to watch is state-level amendment velocity to NFPA 96 shortening inspection windows, which directly expands recurring service revenue pools and accelerates retrofit timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Agent Reformulation | EPA discharge restrictions on perfluorinated chemistries force costly reformulation partnerships with specialty surfactant producers. |
| Multi-Sensor Detection Convergence | Heat-flame-particulate arrays reduce false alarm rates in high-particulate cooking atmospheres previously blocking adoption. |
| Backward Integration into Control Panels | Johnson Controls and Honeywell anchor competitive position through in-house production of actuation hardware and panel manufacturing. |
| Service Contract Unbundling Defense | Third-party inspection contractors capture grease duct cleaning and agent recharge work previously captive to OEM networks. |
| Dual-Zone Suppression Redundancy | Insurer mandates for continuous-batch frying lines double installed value per food processing plant production site. |
Methodological Framework
Desk research of NFPA technical standards documentation, UL listing databases, and ECHA substance restriction filings preceded structured interviews with fire protection system specification engineers, commercial kitchen facility managers, insurance underwriters, and aftermarket service technicians. Primary fieldwork combined telephone and video interviews with stakeholders across the United States, Germany, and Japan. Secondary validation drew from customs trade records, SEC 10-K disclosures of listed fire safety conglomerates, and regulatory filing repositories. Bottom-up unit economics triangulated against top-down market sizing from national fire code adoption timelines.
Variance decomposition across system type, fire detection technology, end user segment, and compliance standard dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression analysis and inspection interval regulatory amendments. Modeled inputs included quick-service restaurant chain capital expenditure disclosures, food processing plant insurance mandate documentation, and REACH substance restriction implementation schedules.
Material uncertainties — regulatory amendment velocity, fluorine-free agent performance validation, and certified technician labor pool expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding NFPA 96 adoption consistency across US state jurisdictions and insurer mandate enforcement intensity. Revision becomes warranted when state-level inspection interval compression accelerates beyond current amendment trajectories or when EPA discharge restrictions expand to additional suppression chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Passive Fire Proofing System Market