
 Finland POS Terminals Market | 2026-2036
Finland POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Finland POS Terminals Market Foresight
Aftermarket service revenue is rewriting profitability logic across the Finland POS Terminals Market. Finnpos Systems Oy leverages its domestic installation base to sustain recurring software maintenance contracts. Worldline, operating through its Ingenico heritage, anchors European payment compliance expertise to control large-format retail deployments. PAX Technology competes on manufacturing scale, extending cost advantages into Nordic distribution channels.
POS terminals are electronic devices that process card and digital payments through integrated hardware comprising secure PIN entry modules, EMV chip readers, and NFC antennas for contactless communication. These systems authenticate transactions via encrypted data exchange with acquiring banks, serving as the terminal node in retail and service-sector payment infrastructure. Mobile POS solutions lead Finnish merchant adoption where tablet-based flexibility displaces fixed-counter installations, while smart POS terminals with integrated business apps capture expanding margin pools from software subscription layering. Contactless technology dominates transaction volume growth as NFC-enabled terminals displace magnetic stripe legacy hardware across hospitality and transit endpoints.
Finland's national financial regulator, Finanssivalvonta, enforces PSD2 compliance timelines that mandate Strong Customer Authentication for card-present transactions, directly accelerating terminal replacement cycles. The Finnish Standards Association (SFS) coordinates with EBA and PCI SSC frameworks to certify EMV and data security standards, restricting market access for non-compliant hardware imports. Stakeholders must monitor whether open banking API integration shifts terminal value from hardware toward embedded software platforms.
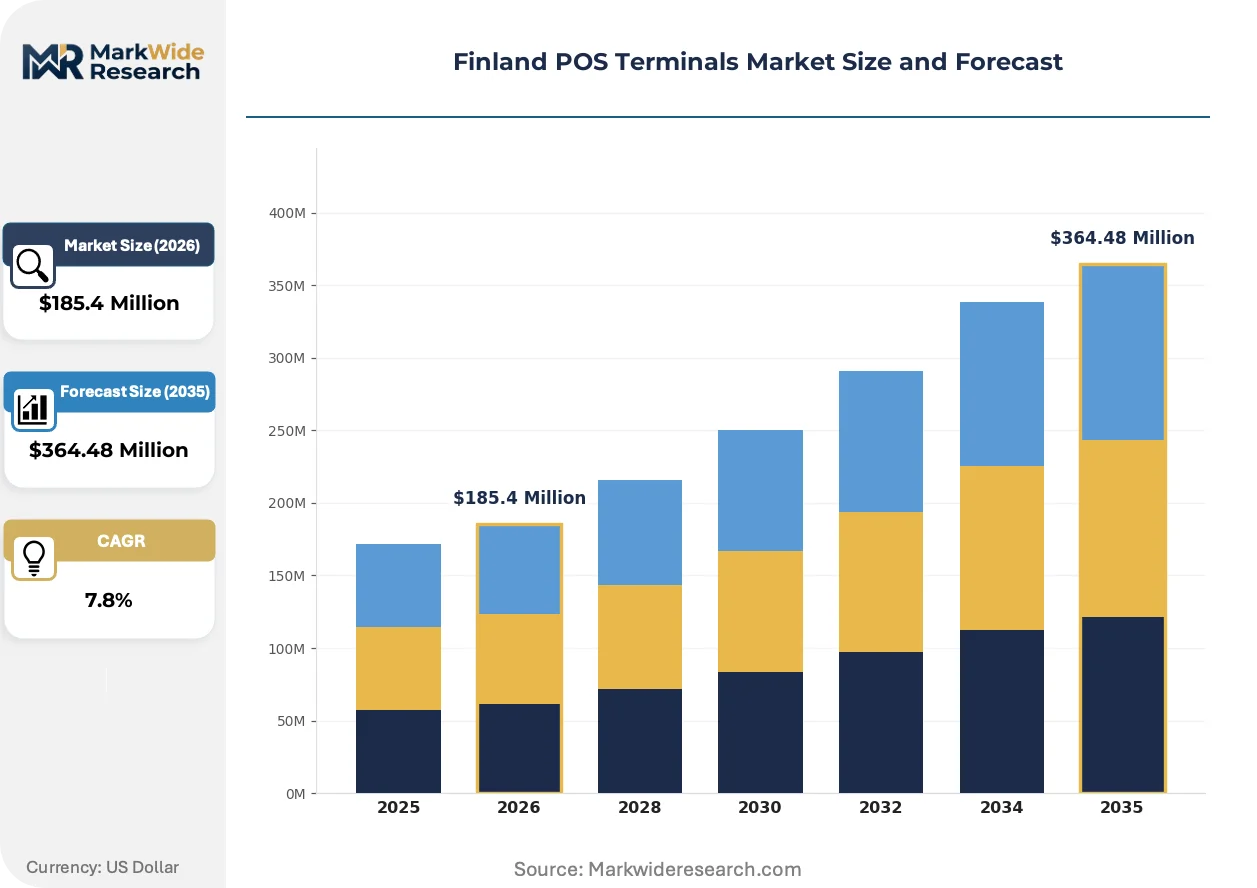
Market Dynamics
Finnish merchants face compressed terminal replacement cycles as Finanssivalvonta's PSD2 Strong Customer Authentication mandates force hardware upgrades across hospitality and transit infrastructure. This regulatory pressure layer atop contactless transaction volume growth creates simultaneous pull-and-push market mechanics.
Growth Catalysts
- Transit Authority Modernization:Helsinki Regional Transport's open-loop payment integration demands NFC-enabled terminal density at every station gate and onboard vehicle.
- Hospitality Digitalization:Finnish restaurant chains deploy tablet-based mobile POS to enable tableside ordering and split-bill flexibility for tourists.
- PSD2 SCA Compliance:Finanssivalvonta's authentication deadlines force magnetic stripe terminal obsolescence regardless of functional condition.
Market Restraints
- Semiconductor Supply Concentration:Secure element chip fabrication concentrates in East Asian foundries, exposing Finnish distributors to allocation volatility.
- EMV Certification Bottlenecks:Finnish Standards Association coordination with PCI SSC creates six-to-nine month hardware approval timelines.
- Smartphone Tap-to-Pay Substitution:Apple Pay and Google Wallet adoption reduces merchant urgency for dedicated terminal investment.
Strategic Opportunities
- Tampere Transit Expansion:Finland's second city is extending tram networks with integrated payment infrastructure requiring 400+ new terminal installations.
- Software Subscription Layering:Smart POS platforms embed inventory management and loyalty apps, capturing recurring revenue beyond hardware margins.
- Open Banking API Convergence:Account-to-account payment rails threaten card network dominance, creating white space for terminal-agnostic software vendors.
Industry Challenges
- EMV Kernel Integration Complexity:Finnish ISVs struggle to port certified payment applications across fragmented Android-based hardware ecosystems.
- PCI DSS 4.0 Transition Burden:Merchants operating legacy Windows Embedded terminals face complete stack replacement to meet March compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland POS Terminals Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $364.48 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Smart POS, Self-Service Kiosk Technology: Contactless, Chip & PIN, Magnetic Stripe, NFC End User: Retail, Hospitality, Transportation, Healthcare Payment Method: Credit Card, Debit Card, Digital Wallets, Bank Transfer |
| Companies Covered | PayXpert LTD, Finnpos Systems Oy, Ingenico Group (Worldline), Kassamagneetti Oy, Seita Technologies Oy, VeriFone System Inc, Erply, Nayax, PAX Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland POS Terminals Market Shifts & Advancements
Payment terminal architecture is bifurcating between stripped-down contactless readers for transit and full-stack smart devices for retail. Finnish adoption patterns favor the latter, where software ecosystems determine hardware selection.
Android-based smart POS terminals are collapsing the traditional separation between payment acceptance and business management software. Finnish hospitality operators adopt these devices to consolidate reservation systems, kitchen display integration, and staff scheduling onto single tablets. The convergence compresses vendor count from three separate suppliers to one platform provider.
Finanssivalvonta's phased SCA enforcement timeline creates predictable replacement waves across merchant tiers. Large-format retailers completed upgrades first; mid-market hospitality and independent retail now face 2025 deadlines. Terminal distributors front-load inventory to capture this concentrated demand window.
Merchant acquisition is fragmenting beyond traditional bank channels. Finnish fintechs and ISOs deploy direct sales teams with zero-hardware-cost leasing models. Independent restaurants in Helsinki and Turku increasingly source terminals through software vendors rather than financial institutions, decoupling hardware procurement from banking relationships.
Finland POS Terminals Market Segmentation
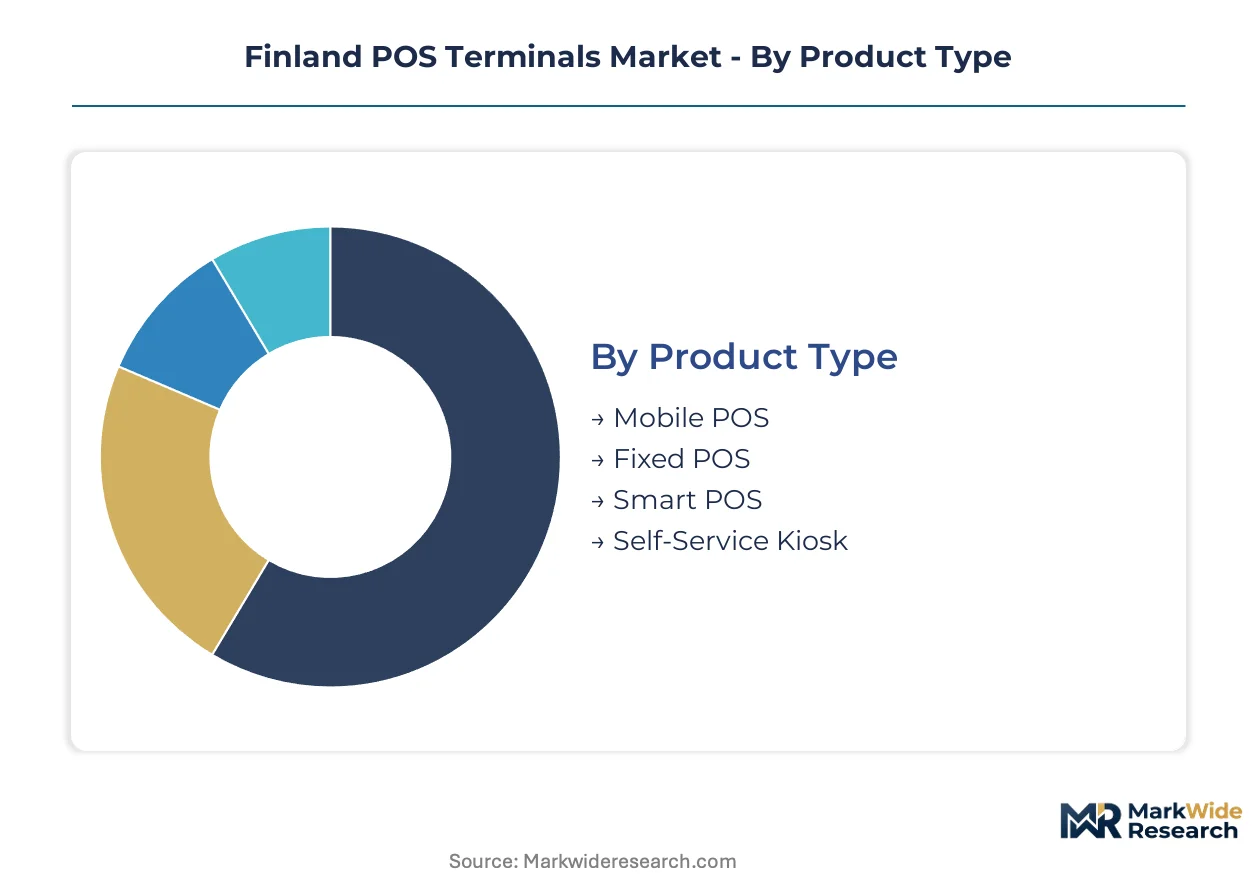
Finnish merchants select terminal configurations based on transaction velocity, software integration requirements, and Finanssivalvonta compliance timelines. Segmentation reveals divergent hardware replacement cycles across merchant tiers, with aftermarket service contracts increasingly determining vendor selection.
Product Type:
After-sales service intensity varies sharply across form factors, with mobile deployments demanding field support networks that fixed-counter installations rarely require.
- Mobile POS:Tablet-based terminals with Bluetooth-connected card readers enable tableside payment acceptance in Helsinki restaurants. Finnish hospitality chains in Tampere and Turku prioritize these for split-bill flexibility and reduced counter congestion during peak tourist seasons.
- Smart POS:Android-based devices integrate payment acceptance with inventory management, kitchen display systems, and staff scheduling applications. Helsinki retailers adopt these to consolidate vendor relationships from three separate suppliers onto single platforms.
- Fixed POS:Traditional countertop terminals with integrated receipt printers serve high-volume grocery and department store environments.
- Self-Service Kiosk:Unattended payment stations at transit gates and quick-service restaurants require ruggedized enclosures and remote monitoring capabilities.
By volume, Fixed POS leads. By growth pace, Smart POS is ahead.
Technology:
Hardware cost tiers stratify sharply by authentication complexity, with contactless readers commanding premium pricing over legacy magnetic stripe terminals facing obsolescence.
- Contactless:NFC-enabled terminals process tap-to-pay transactions without PIN entry for amounts below PSD2 Strong Customer Authentication thresholds. Helsinki Regional Transport mandates these at every station gate and onboard vehicle.
- NFC:Near-field communication hardware supports both card-present and smartphone wallet acceptance. Finnish merchants in tourist-heavy districts prioritize these for Apple Pay and Google Wallet compatibility.
- Chip & PIN:EMV-compliant terminals with secure PIN entry modules remain mandatory for transactions exceeding SCA limits.
- Magnetic Stripe:Legacy swipe readers face accelerated replacement as Finanssivalvonta deadlines render non-compliant hardware unusable.
By installed base, Chip & PIN dominates. By replacement urgency, Contactless is climbing the fastest.
End User:
Application-specific durability requirements and software integration needs create distinct procurement patterns across Finnish merchant verticals.
- Retail:Department stores and grocery chains deploy fixed-counter terminals with high-speed thermal printers. Inventory system integration drives smart POS adoption in Helsinki and Tampere.
- Hospitality:Restaurants and hotels favor mobile and smart POS for tableside ordering and property management system connectivity.
- Transportation:Transit authorities require ruggedized contactless readers with offline transaction storage for tunnel and rural coverage gaps.
- Healthcare:Clinics and pharmacies prioritize PCI DSS-compliant terminals with patient billing system integration.
By terminal count, Retail leads. By expansion rate, Transportation is gaining share fastest.
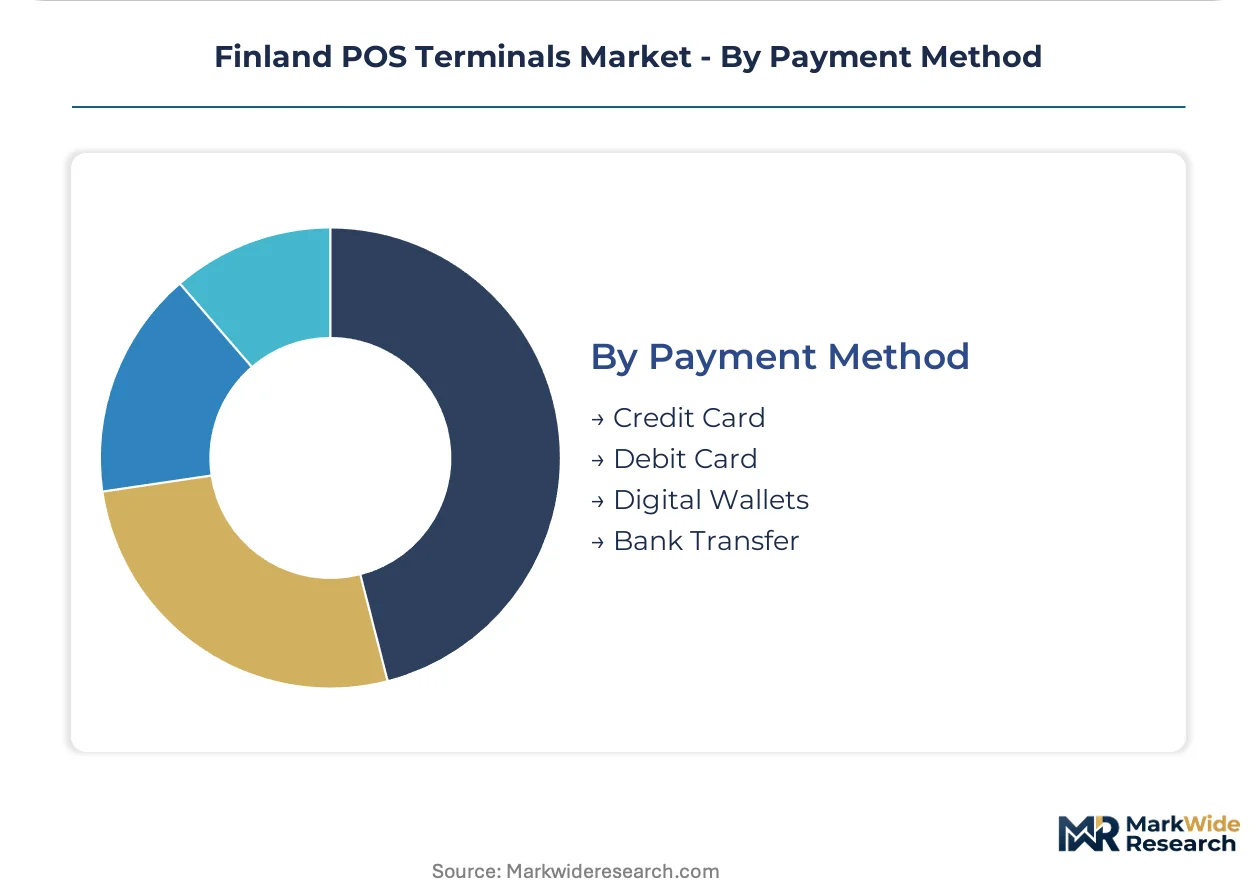
Payment Method:
Customer type segmentation reflects divergent merchant acquisition strategies, with card network dependence under pressure from account-to-account alternatives.
- Credit Card:Premium interchange rates support hardware leasing models for independent restaurants and boutique retailers.
- Debit Card:Domestic bank network dominance in Finland ensures continued terminal demand for PIN-authenticated transactions.
- Digital Wallets:Smartphone-based acceptance reduces merchant urgency for dedicated terminal investment in low-volume settings.
- Bank Transfer:Open banking API integration threatens traditional terminal value as account-to-account rails bypass card networks entirely.
By transaction volume, Debit Card leads. By disruption potential, Bank Transfer shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish merchants exhibit the widest demand-elasticity spread across Nordic markets, with Helsinki hospitality operators accepting premium pricing for integrated software platforms while rural independent retailers resist hardware costs above replacement thresholds.
Helsinki Capital Region
Transit modernization and tourism density drive terminal deployment intensity. Finanssivalvonta's SCA deadlines concentrate replacement demand among waterfront restaurants and hotel chains. The Kamppi and Kallio districts host dense clusters of tablet-based mobile POS installations serving international visitors.
Tampere
Tram network expansion creates systematic procurement opportunities across 23 planned stops. Pirkanmaa regional transit authority mandates open-loop payment compatibility for all new infrastructure. Hatanpää and Tammela commercial zones anchor smart POS adoption among mid-market hospitality operators.
Turku
Archipelago tourism routes require ruggedized terminals with offline transaction storage for ferry and island service endpoints. The Turku Science Park mediates between hardware vendors and software developers for integrated payment solutions. Port district restaurants prioritize contactless readers for cruise passenger throughput.
Oulu
Technology sector employment sustains above-average merchant digitalization rates. The Linnanmaa campus district drives demand for Android-based smart terminals with business application integration. Winter reliability requirements favor fixed-counter installations over mobile alternatives in retail environments.
Lahti
Ski resort proximity creates seasonal demand spikes for rental equipment and hospitality terminals. The Sibelius Hall event venue cluster requires high-velocity contactless readers for concert and conference traffic. Independent retailers in the city center lag replacement cycles due to compressed margins.
Finland POS Terminals Market Competitive Landscape
Domestic system integrators and international hardware manufacturers split the market along service-depth versus scale axes. Three strategic archetypes dominate: Nordic-focused software-hardware bundlers, pan-European payment compliance specialists, and East Asian manufacturing-scale exporters. Consolidation pressure intensifies as recurring revenue models displace transactional hardware margins. Vertical integration into secure element supply chains and API platform development represent the primary competitive vectors.
Among Finland-anchored specialists, Finnpos Systems Oy and Seita Technologies Oy occupy positions emphasizing domestic installation density and regulatory navigation. Ingenico Group, operating through its Worldline parent structure, exemplifies the European compliance-specialist archetype with certification leverage across EMV and PCI frameworks. PAX Technology represents manufacturing-scale competition extending cost advantages through Nordic distribution partnerships.
| Leading Market Players |
|---|
| PayXpert LTD |
| Finnpos Systems Oy |
| Ingenico Group (Worldline) |
| Kassamagneetti Oy |
| Seita Technologies Oy |
| VeriFone System Inc |
| Erply |
| Nayax |
| PAX Technology |
| Others |
Supply & Pricing Matrix
Secure element chip fabrication concentrates in Taiwan and South Korea, anchoring upstream margin capture while Finnish distributors compete on software subscription attach rates and field service density. Terminal hardware margins compress under manufacturing scale competition, yet recurring maintenance contracts and PCI compliance consulting sustain profitability downstream.
Pricing Analysis
Software maintenance and certification renewal revenue drives lifetime customer value beyond initial hardware deployment. Three-tier pricing structure across premium smart POS platforms, standard fixed-counter terminals, and economy mobile readers stratifies by EMV certification tier and after-sales bundling depth. Pricing pressure stems from East Asian manufacturing scale extending into Nordic distribution channels. Independent retailers in Lahti and Turku exhibit highest price sensitivity, while Helsinki hospitality chains accept premium positioning for integrated platform solutions.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor foundries and European terminal assemblers dominates supply chain risk calculus. Secure element chips draw from Taiwan, South Korea, and China; NFC antenna modules and EMV kernel software originate from Chinese and Japanese suppliers. Single-source vulnerability in secure microcontroller fabrication creates allocation volatility during demand surges. Distribution runs through Helsinki-based system integrators with direct relationships to transit authorities and hospitality chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finnish POS terminal demand is restructuring around service-attach economics, with software subscription layering expanding faster than hardware shipment growth across hospitality and transit verticals.
For Market Incumbents: Pre-empt smartphone tap-to-pay substitution by embedding inventory management and loyalty applications into smart POS platforms. Secure exclusive distribution agreements with Helsinki Regional Transport and Pirkanmaa transit authority before tender windows close. Deepen backward integration into EMV kernel certification to compress six-to-nine month Finnish Standards Association approval timelines. For New Entrants and Emerging Players: Build out field service networks in Tampere and Oulu where domestic installation density remains below Helsinki saturation. Target archipelago ferry operators and ski resort equipment rental operators with ruggedized offline-capable terminals bundled with seasonal maintenance contracts. Pursue software vendor channel partnerships rather than direct merchant acquisition to bypass entrenched banking relationships. For Investors and Strategic Acquirers: Capital is best deployed toward Nordic-focused system integrators with captive transit authority relationships and recurring software revenue bases exceeding hardware shipment value. Five-to-ten year viability hinges on open banking API convergence shifting terminal value toward platform-agnostic software layers. Monitor Finanssivalvonta SCA deadline enforcement intensity as inflection indicator for replacement cycle concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Consolidates restaurant reservation, kitchen display, and payment systems onto single Android terminals. |
| Transit Authority Partnership | Secures multi-year terminal deployment contracts with open-loop payment mandate compliance. |
| EMV Certification Investment | Accelerates Finnish Standards Association approval timelines from nine months toward six months. |
| Field Service Network Expansion | Captures aftermarket maintenance contracts in Tampere and Oulu merchant corridors. |
| Channel Partnership with Fintechs | Bypasses traditional bank merchant acquisition through direct software vendor distribution. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with payment hardware procurement managers, transit authority technology officers, hospitality chain operations directors, and Finnish Standards Association certification leads; and secondary validation against EMVCo compliance databases, Finanssivalvonta regulatory filings, PCI SSC certification registries, and Nordic customs import records. Bottom-up terminal shipment estimates triangulated against top-down payment transaction volume projections.
Forecast inputs span product type segmentation across mobile, smart, fixed, and self-service kiosk configurations; technology tiers from magnetic stripe through contactless NFC; and end-user verticals including retail, hospitality, transportation, and healthcare. CAGRs derive from replacement cycle modeling against Finanssivalvonta SCA compliance deadlines and transit infrastructure expansion timelines. Open banking API adoption rates and smartphone wallet penetration curves inform terminal demand elasticity assumptions.
Practitioners should monitor Finanssivalvonta enforcement intensity, East Asian semiconductor allocation volatility, and merchant acquisition channel fragmentation for early signals of forecast revision. Forecasts reflect assumptions about regulatory deadline adherence, supply chain stability, and payment method substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Digital Wallets Market
Payments
North America Payment Analytics Software Market
Payments
India POS Terminals Market
Payments
Bulgaria POS Terminals Market
Payments
Payment Security Market
Payments
Canada Real Time Payments Market
Payments
Global Utility Billing Software Market
Payments
South Korea Digital Payments Market
Payments
France Virtual Cards Market
Payments
Germany Payments Market
Payments
South Korea Real Time Payments Market
Payments
Kenya Mobile Money Market
Payments
Italy POS Terminals Market
Payments
Hong Kong Payments Market
Payments
United States POS Terminals Market
Payments
Asia Pacific Mobile Wallet Market