
 Global Digital Wallets Market | 2026-2036
Global Digital Wallets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Wallets Market Foresight
India's UPI infrastructure expansion is fragmenting legacy payment rails as real-time settlement protocols displace card-based workflows. PayPal leverages its cross-border remittance network to sustain merchant acquisition costs in competitive corridors. WeChat Pay anchors super-app commerce through embedded mini-programs that lock in user engagement across verticals.
Digital wallets are software-based payment systems that store encrypted credential tokens on devices or cloud servers, enabling authentication through biometrics, PINs, or device-bound cryptography for transaction authorization. Their primary commercial purpose is reducing friction in consumer-to-business and peer-to-peer fund transfers while capturing behavioral data for financial services cross-sell. Mobile platforms dominate transaction volumes due to persistent device proximity and native biometric security integration, while QR code payments capture micro-merchant segments where terminal costs exclude traditional point-of-sale hardware. E-commerce applications concentrate value per transaction, whereas peer-to-peer transfers drive account acquisition velocity with thinner margin profiles.
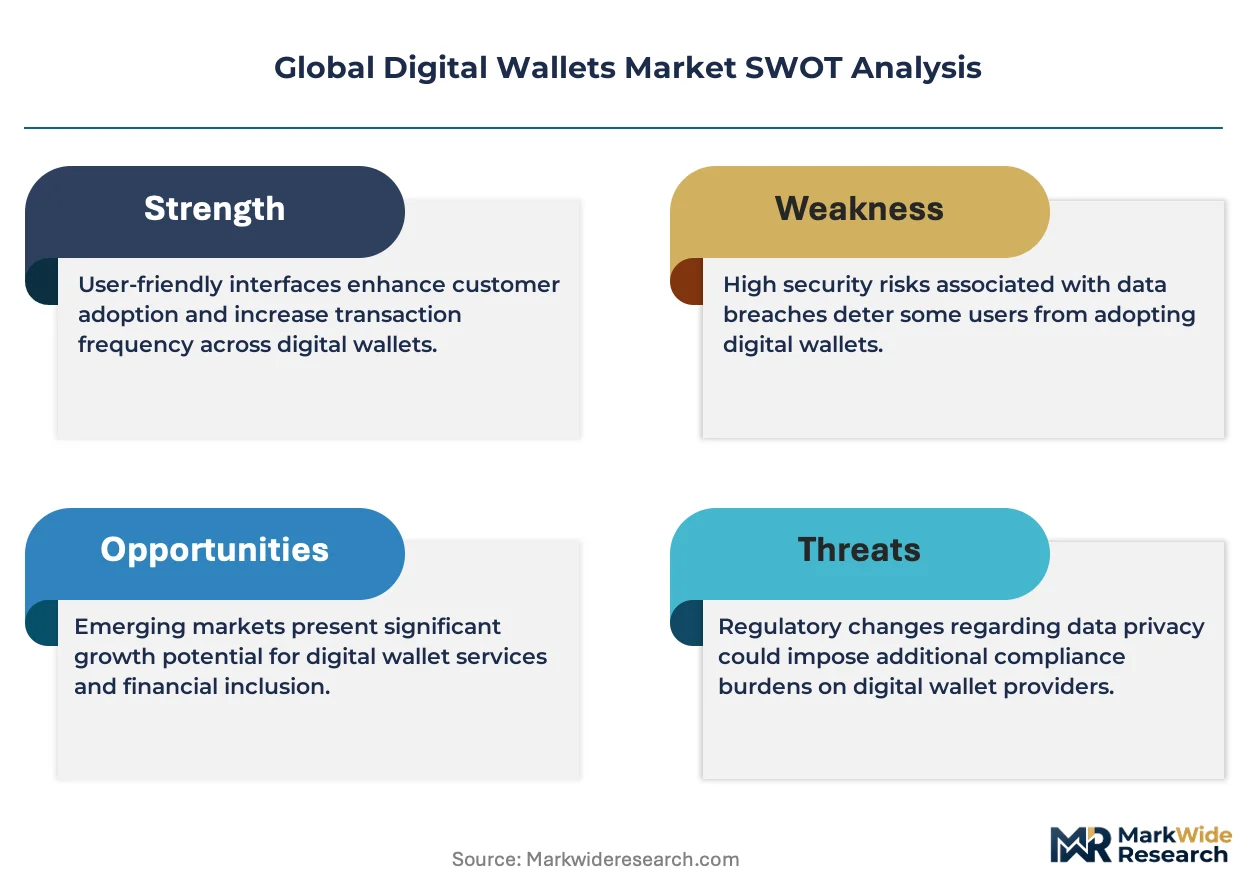
India's RBI mandates tokenization standards for card-on-file storage, while the EU's PSD2 strong customer authentication framework shapes product design for wallet providers operating across European markets. China's SAMR enforces antitrust scrutiny on platform exclusivity arrangements that tie wallet services to e-commerce marketplaces. Stakeholders must monitor whether open banking APIs in Brazil and Nigeria fragment wallet incumbents by enabling bank-direct payment initiation that bypasses stored-value architectures.
Market Dynamics
Real-time settlement protocols are collapsing the latency advantage that card networks held for decades, forcing infrastructure reinvestment across every node of the payment value chain.
Growth Catalysts
- Interoperability Mandates:Brazil's central bank has enforced open banking APIs that force wallet providers to enable direct bank-account initiation, expanding addressable transaction volumes beyond stored-value limits.
- Biometric Authentication:Fingerprint and facial recognition integration into mobile operating systems has reduced authentication friction below the threshold where cash remains competitive for micro-transactions.
- QR Code Infrastructure:India's merchant acquisition strategy through interoperable QR standards has penetrated informal retail segments previously excluded from electronic payment acceptance.
Market Restraints
- Data Localization Requirements:India's RBI mandates domestic server storage for payment data, elevating compliance costs for foreign wallet providers and fragmenting cloud architecture strategies.
- Interchange Compression:Regulatory caps on merchant discount rates in Brazil and India have thinned revenue per transaction, compressing unit economics for providers dependent on payment float.
- Platform Exclusivity Enforcement:China's SAMR has prohibited wallet services from tying payment functionality to e-commerce marketplace access, severing a primary customer acquisition channel.
Strategic Opportunities
- Embedded Finance Convergence:The integration of wallet functionality with wealth management and insurance distribution within super-app architectures is capturing lifetime value beyond payment margins.
- Cross-Border Remittance Rails:Southeast Asian corridors between Indonesia, Philippines, and Vietnam remain underpenetrated by integrated wallet solutions, presenting white space for corridor-specific product builds.
- Offline QR Acceptance:Nigeria's central bank has mandated merchant acceptance infrastructure for tier-1 banks, creating regulatory tailwind for wallet providers with agent network density.
Industry Challenges
- Tokenization Certification Timelines:India's RBI card-on-file storage standards require recertification cycles that delay product launches by 6-12 months for providers with legacy vault architectures.
- Legacy Core Integration:Bank-direct payment initiation through open APIs is forcing wallet incumbents to reengineer settlement flows that assumed stored-value float as a core revenue pillar.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Wallets Market |
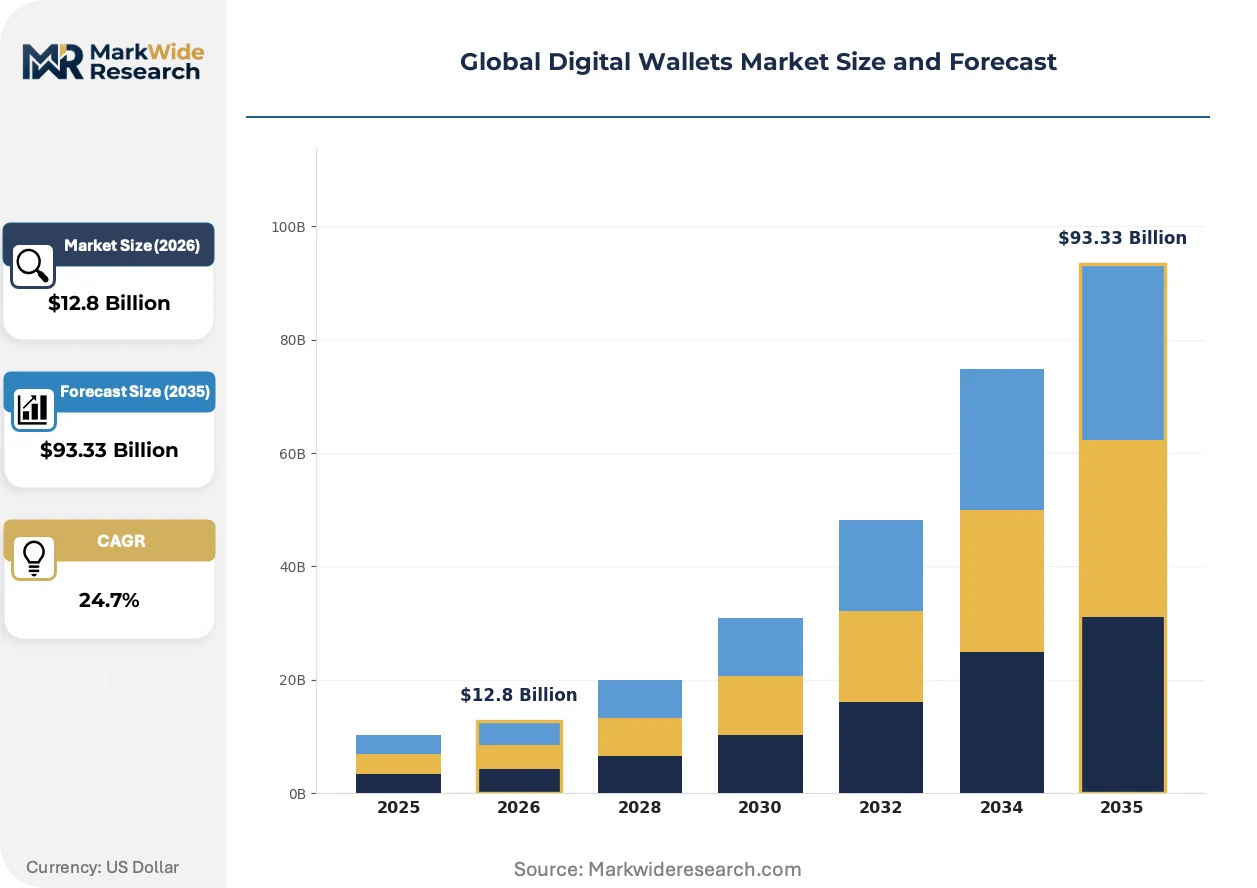
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $93.33 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: Mobile, Web, Wearable Devices, Desktop Applications Payment Method: Credit Cards, Debit Cards, Bank Transfers, Mobile Payments, QR Code Payments End User: Consumers, Small Enterprises, Freelancers, Non-Profit Organizations Application: E-Commerce, Peer-to-Peer Transfers, Bill Payments, Event Ticketing, Loyalty Programs |
| Companies Covered | Alipay, Apple Pay, Google Pay, PayPal, WeChat Pay, Cash App, Samsung Pay, Amazon Pay, Venmo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Wallets Market Shifts & Advancements
Payment authentication is migrating from credential-based verification toward continuous behavioral signals, compressing the security-per-convenience tradeoff that previously constrained adoption curves.
Biometric payment authorization is collapsing the step-up authentication requirements that previously interrupted high-value transactions. Large-format retail chains in Brazil and Mexico are deploying palm-vein and facial recognition terminals at self-checkout lanes, eliminating PIN entry friction for transactions above contactless limits. This compression of authentication steps is enabling wallet providers to capture grocery and electronics verticals where cart abandonment had historically favored card-present workflows.
Europe's PSD2 strong customer authentication framework has mandated two-factor verification for electronic payments, forcing wallet providers to implement dynamic linking between transaction amount and authentication credentials. The regulation has elevated technical barriers for entrants lacking certificate authority relationships, concentrating compliance capability among established providers. Fintech challengers in Germany and France are responding by acquiring electronic money institution licenses that grandfather certain authentication flexibility.
Merchant acquisition models are pivoting from hardware-terminal distribution toward software-only onboarding through existing smartphone infrastructure. Micro-merchants in Indonesia and Vietnam are adopting wallet-based acceptance without dedicated POS devices, using personal phones to generate dynamic QR codes for each transaction. This behavioral shift is most visible in wet-market and street-vendor segments where terminal deployment economics had previously excluded electronic payment participation.
Global Digital Wallets Market Segmentation
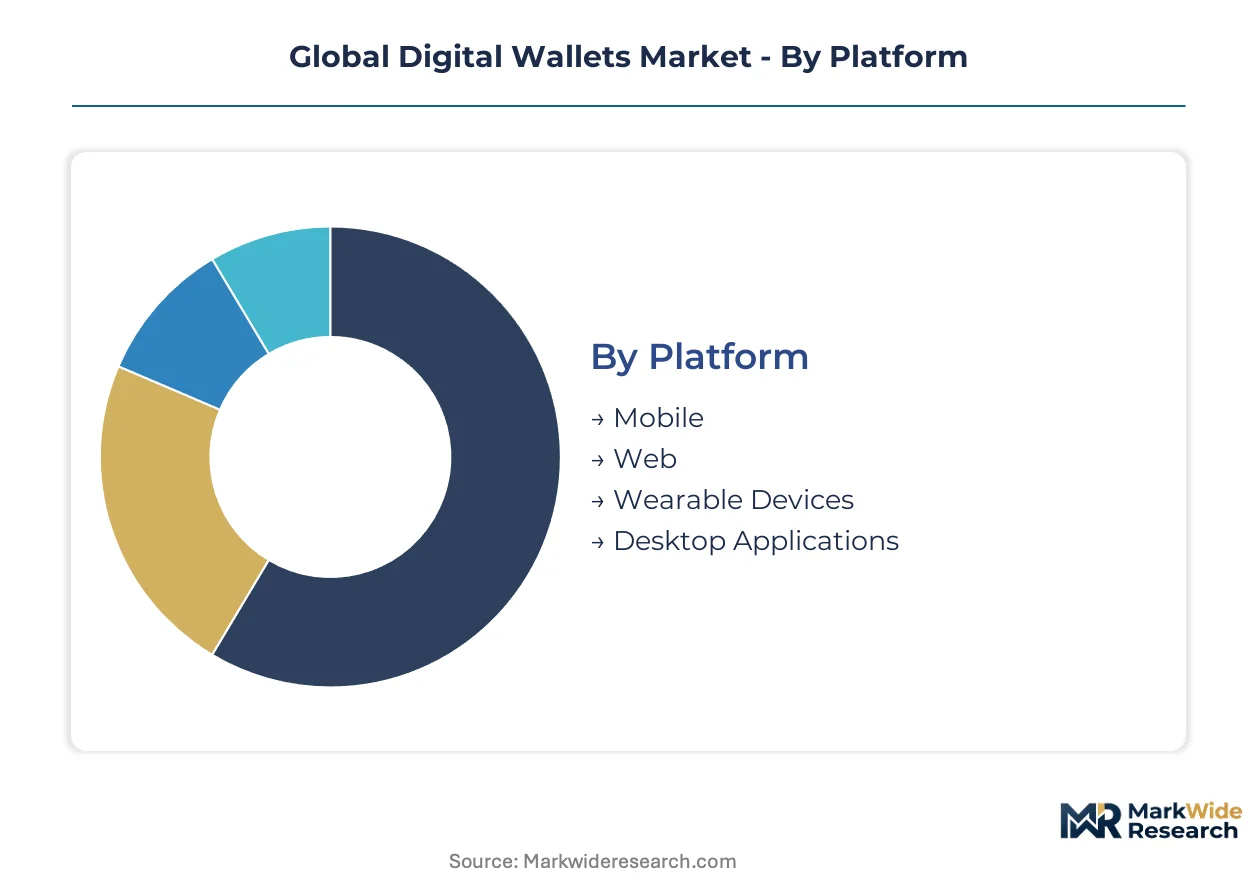
Digital wallet segmentation reveals divergent monetization velocities across platform architectures and payment modalities. Transaction frequency, credential storage methods, and settlement latency vary substantially by segment, reshaping provider resource allocation and infrastructure investment priorities.
Platform:
Mobile platforms turn over transaction volumes fastest with sub-second authentication cycles, while desktop applications exhibit slower session-based engagement patterns with higher per-transaction values.
- Mobile:Native biometric integration on iOS and Android enables seamless fingerprint and facial recognition authentication. India's UPI rail processes billions of monthly transactions through mobile-first architectures, compressing settlement latency to real-time speeds.
- Wearable Devices:NFC-enabled smartwatches and fitness bands support contactless tap-to-pay without phone retrieval. Brazil's central bank mandates interoperability standards that extend tokenized credentials to wrist-worn form factors, accelerating merchant acceptance.
- Web:Browser-based wallets rely on encrypted cloud credential storage with step-up authentication for high-value transfers.
- Desktop Applications:Native software installations persist in enterprise treasury and cross-border remittance workflows where screen real estate supports complex multi-currency operations.
Mobile anchors the volume base while wearable devices gain share at the steepest rate.
Payment Method:
Cost tier differentiation separates high-interchange credit instruments from low-margin bank-direct initiation, with QR codes occupying the micro-transaction economy.
- QR Code Payments:Static and dynamic barcode generation enables merchant acceptance without terminal hardware. Indonesia's street vendors and wet-market operators have adopted smartphone-generated QR codes at scale, bypassing traditional POS infrastructure costs entirely.
- Mobile Payments:NFC and tokenized credential transmission through device proximity dominate transit and quick-service retail. China's super-app ecosystem embeds payment functionality within messaging and commerce interfaces, locking users into vertically integrated environments.
- Credit Cards:Tokenized card-on-file storage supports e-commerce checkout with liability shift protections.
- Debit Cards:Direct account linking reduces interchange costs for merchants compared to credit rails.
- Bank Transfers:Open banking APIs enable account-to-account initiation that bypasses card network fees entirely.
QR code payments anchor the volume base while mobile payments gain share at the steepest rate.
End User:
Customer type determines feature complexity requirements, from simplified consumer interfaces to multi-user enterprise treasury controls with approval hierarchies.
- Consumers:Individual users demand frictionless peer-to-peer transfers and merchant checkout with minimal authentication steps. India's UPI adoption has concentrated demand among retail consumers seeking alternatives to cash for everyday transactions.
- Small Enterprises:Micro-merchants require lightweight acceptance tools without dedicated hardware or complex onboarding. Brazil's central bank mandates have expanded access to electronic payment acceptance for previously excluded commercial segments.
- Freelancers:Cross-border invoicing and multi-currency receipt capabilities support gig economy workers serving international clients.
- Non-Profit Organizations:Donation-specific features include recurring contribution management and tax receipt generation.
Consumers anchor the volume base while small enterprises gain share at the steepest rate.
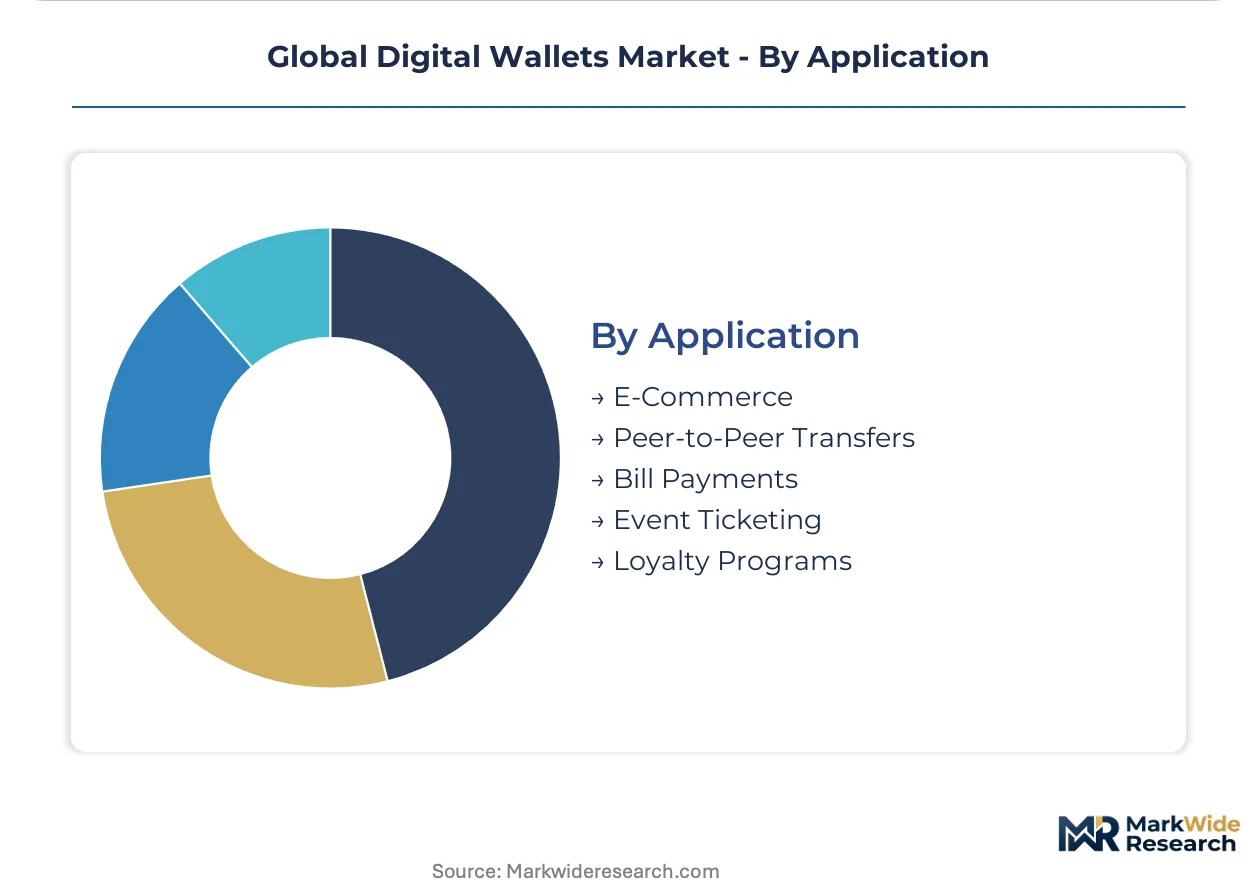
Application:
Geographic concentration varies by use case, with e-commerce clustering in urban digital commerce corridors and peer-to-peer transfers penetrating rural financial inclusion zones.
- E-Commerce:Checkout integration with merchant platforms captures high-value transactions with embedded loyalty and financing options. Southeast Asian marketplaces have consolidated wallet functionality with shopping interfaces, reducing cart abandonment through one-tap payment completion.
- Peer-to-Peer Transfers:Instant fund movement between individuals drives account acquisition with minimal marginal cost. Nigeria's central bank mandates for tier-1 bank infrastructure have expanded P2P accessibility across previously underbanked populations.
- Bill Payments:Recurring utility and subscription management automates household financial obligations.
- Event Ticketing:Wallet-integrated admission credentials reduce fraud and enable dynamic pricing.
- Loyalty Programs:Points aggregation and redemption within payment interfaces increase transaction stickiness.
E-commerce anchors the volume base while peer-to-peer transfers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's super-app ecosystem treats wallet functionality as embedded infrastructure rather than standalone product, while India and Brazil deploy wallet rails primarily for financial inclusion and merchant digitization respectively.
China
WeChat Pay and Alipay process the vast majority of transactions through mini-program commerce embedded within messaging and social interfaces. SAMR enforces antitrust prohibitions on platform exclusivity arrangements that tie payment services to marketplace access. Shenzhen and Hangzhou anchor development clusters where wallet providers integrate wealth management and insurance distribution into super-app architectures.
India
UPI real-time settlement has displaced card-based workflows for peer-to-peer transfers and micro-merchant payments across urban and rural segments. RBI mandates tokenization standards for card-on-file storage and domestic data localization for payment information. Mumbai and Bangalore concentrate fintech development where wallet providers engineer compliance architectures around recertification timelines.
Brazil
Central bank open banking APIs force wallet providers to enable direct bank-account initiation, expanding transaction volumes beyond stored-value float limits. ANVISA and central bank interoperability mandates accelerate merchant acceptance infrastructure deployment. São Paulo anchors the financial services corridor where providers compete for agent network density in informal retail segments.
Indonesia
Street vendors and wet-market operators have adopted smartphone-generated QR codes at scale, bypassing traditional POS terminal economics entirely. Bank Indonesia interoperability standards enable cross-wallet transaction routing. Jakarta and Surabaya concentrate merchant acquisition activity where providers deploy software-only onboarding through existing smartphone infrastructure.
Nigeria
Central bank mandates for tier-1 bank infrastructure have expanded peer-to-peer accessibility across previously underbanked populations. Regulatory requirements for merchant acceptance infrastructure create tailwinds for wallet providers with established agent networks. Lagos anchors fintech development where providers engineer offline QR solutions for connectivity-constrained environments.
Global Digital Wallets Market Competitive Landscape
Capability concentration sits with technology platform owners who control mobile operating systems and biometric authentication frameworks; scale advantage sits with super-app operators who command integrated commerce ecosystems. The market structures around three tiers: mobile OS-embedded wallets, standalone payment applications, and commerce-platform-integrated solutions. Dominant competitive moves include geographic corridor expansion for cross-border remittance and embedded finance convergence that captures lifetime value beyond transaction margins.
Among Asia-Pacific-based super-app operators, Alipay and WeChat Pay exemplify the vertically integrated archetype that locks users into messaging, commerce, and wealth management interfaces. Google Pay and Apple Pay occupy positions anchored to mobile operating system distribution, representing the platform-native tier that leverages device-level biometric security integration. PayPal sits within the cross-border specialist archetype, sustaining merchant relationships through remittance corridor density rather than domestic super-app engagement.
| Leading Market Players |
|---|
| Alipay |
| Apple Pay |
| Google Pay |
| PayPal |
| WeChat Pay |
| Cash App |
| Samsung Pay |
| Amazon Pay |
| Venmo |
| Others |
Supply & Pricing Matrix
Asia-Pacific submarine cable routes connecting Singapore to Mumbai carry the bulk of cross-border payment data traffic, with bandwidth cost differentials between these corridors directly shaping how wallet providers tier service pricing across Southeast Asian markets versus Indian subcontinent deployments.
Pricing Analysis
Geographic price spreads between Brazil and India exceed threefold for equivalent transaction processing services, driven by divergent regulatory cost burdens. The dominant pricing model runs on per-unit transactional fees scaled to transaction value bands, with interchange compression in Brazil and India thinning revenue per transaction. Price differentiation rests on certification tier under RBI tokenization standards versus Brazil's open banking compliance grade, alongside volume scale thresholds. Pricing pressure stems from central bank mandates capping merchant discount rates. Small enterprises exhibit highest price sensitivity, while large e-commerce platforms negotiate least.
Supply Chain Analysis
Tariff exposure between US and China semiconductor supply chains dominates infrastructure cost volatility for wallet providers dependent on secure element manufacturing. Hardware security module production concentrates in China, Taiwan, and South Korea, while cloud infrastructure draws from US, Ireland, and Singapore data center clusters. Raw material dependencies span silicon wafers, cryptographic processors, and biometric sensor components. Single-source vulnerability persists in EMVCo-certified secure chip fabrication. Distribution runs through hyperscaler partnerships and direct enterprise API integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as real-time settlement protocols displace legacy card rails across Brazil, India, and Nigeria, with biometric authentication penetration still below saturation thresholds in Southeast Asian corridors.
For Market Incumbents: Build network effects moats through merchant acquisition density in informal retail segments before open banking APIs fragment stored-value architectures. Deepen agent network coverage in Nigeria's tier-2 cities to preempt bank-direct payment initiation. Invest in RBI tokenization recertification cycles to maintain card-on-file compliance advantage against fintech challengers.
For New Entrants and Emerging Players: Pursue corridor-specific remittance builds between Indonesia, Philippines, and Vietnam where integrated wallet solutions remain underpenetrated. Target micro-merchant segments in wet-market economies with software-only QR onboarding that bypasses terminal deployment economics. Lead with embedded wealth management features to capture lifetime value beyond thin payment margins.
For Investors and Strategic Acquirers: Carve-out targets emerge from bank-owned wallet subsidiaries lacking super-app commerce integration. Long-term viability favors providers with biometric authentication certification and cross-border corridor density. Watch for inflection signals in central bank open banking API maturity that enables bank-direct initiation bypassing stored-value float models.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Certification | RBI and Brazil's central bank mandates elevate technical barriers for uncertified providers. |
| Cross-Border Corridor Expansion | Southeast Asian remittance rails between Indonesia, Philippines, and Vietnam present white space. |
| Embedded Finance Convergence | Super-app architectures in China demonstrate wealth management integration capturing lifetime value. |
| Merchant Acquisition Density | Nigeria's central bank mandates for tier-1 infrastructure create tailwinds for agent networks. |
| Open Banking API Integration | Brazil's central bank interoperability standards force reengineering of settlement flows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and hyperscaler infrastructure disclosures. Primary interviews engaged payment platform CTOs, central bank policy officers, merchant acquisition heads, and biometric authentication specialists. Secondary validation drew from RBI circulars, Brazil's central bank open banking documentation, EU PSD2 implementation reports, and SEC filings of listed payment providers. Bottom-up transaction volume modeling triangulated against top-down addressable market sizing.
Forecast inputs span platform architecture segmentation, payment modality mix, and end-user adoption curves across consumer, small enterprise, and freelancer categories. The analytical framework projects volumes across the modeling period by corridor-specific penetration rates, biometric authentication deployment timelines, and regulatory compliance cost burdens. CAGRs derive from segment-level growth rate reconciliation against macroeconomic payment digitization indices.
Sensitivities concentrate around central bank mandate timing, tokenization recertification delays, and open banking API fragmentation risks. Forecasts reflect assumptions on interoperability standard adoption and merchant infrastructure deployment pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Electronic Payment Processing Software Market
Payments
Retail Point of Sale (POS) Market
Payments
Europe Fuel Cards Market
Payments
Europe Credit Cards Market
Payments
Credit Card Issuance Services Market
Payments
Retail POS Terminals Market
Payments
Global Telecom Billing Market
Payments
Denmark POS Terminals Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Europe Virtual Cards Market
Payments
Europe POS Terminal Market
Payments
Europe Payments Market
Payments
India Forex Cards Market
Payments
Global Real-Time Payments Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Brazil Real Time Payments Market