
 Bulgaria POS Terminals Market | 2026-2036
Bulgaria POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria POS Terminals Market Outlook
Hospitality is pivoting toward cloud-connected terminal fleets as Bulgarian restaurants and hotels modernize guest payment journeys. PAX Technology leverages its manufacturing scale to supply EMV-certified hardware across Balkan distribution channels. Datecs Ltd. anchors its position through deep integration with local fiscal memory requirements and Bulgarian National Revenue Agency compliance protocols. myPOS competes aggressively on merchant onboarding speed, targeting small hospitality operators with bundled acquiring services.
POS terminals are electronic devices that capture payment card data, authenticate transactions through embedded encryption modules, and transmit authorization requests to banking networks via secure IP or cellular connectivity. Their primary commercial purpose is to enable regulated, auditable payment acceptance while reducing cash handling costs for merchants. Mobile POS terminals are capturing the fastest expansion as Bulgarian sole traders and pop-up vendors prioritize low-cost, smartphone-integrated hardware over traditional fixed-counter installations. Cloud-based deployment models concentrate margin pools in recurring software subscription revenue rather than one-time hardware sales, while NFC technology is displacing magstripe dominance as contactless transaction limits rise across EU member states.
Bulgaria's POS terminal market operates under the EU Payment Services Directive, the Bulgarian National Revenue Agency's fiscal device certification regime, and BIS interoperability standards for payment infrastructure. These frameworks mandate encrypted transaction logging, certified fiscal memory modules, and periodic software audits that shape vendor product roadmaps and create barriers for uncertified imports. Stakeholders must monitor how forthcoming EU digital identity wallet integration and real-time payment scheme rollouts alter terminal firmware requirements and merchant upgrade cycles.
Market Dynamics
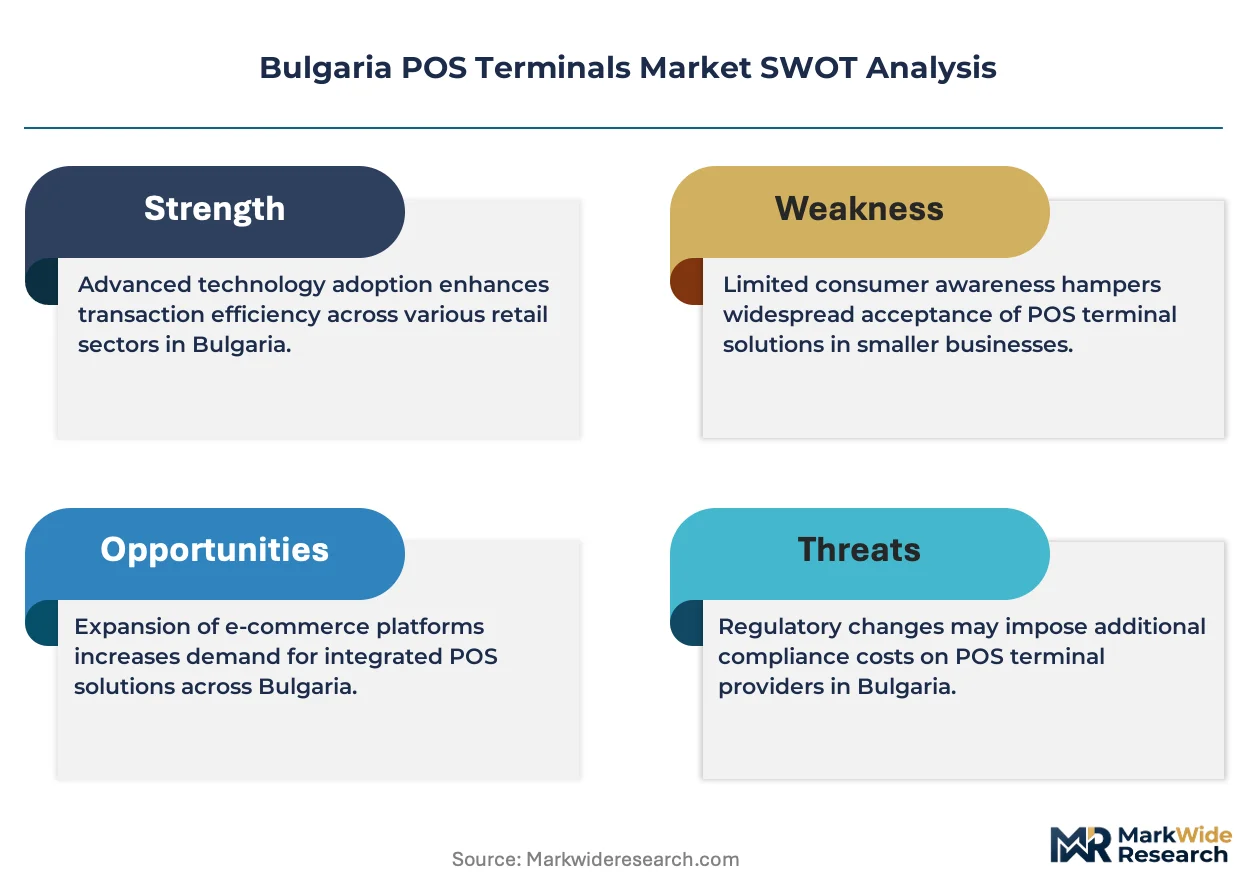
EU Payment Services Directive mandates for contactless transaction infrastructure are forcing Bulgarian merchants into accelerated hardware refresh cycles, compressing terminal replacement timelines from seven years to under four.
Growth Catalysts
- PSD2 Strong Customer Authentication:Bulgarian banks must upgrade terminal fleets to support dual-factor authentication protocols, creating mandatory demand for EMV-compliant hardware across retail networks.
- Sofia hospitality cluster:Restaurant and hotel chains in the capital are deploying cloud-connected terminal fleets to unify payment data across properties and streamline reconciliation.
- NFC reader modules:Contactless payment limits across EU member states are driving merchant adoption of tap-to-pay hardware, particularly among food service operators seeking faster table turnover.
Market Restraints
- Certified fiscal memory modules:Bulgarian National Revenue Agency mandates for tamper-proof transaction logging add 15-20% hardware cost premiums versus uncertified imports from non-EU suppliers.
- Semiconductor supply concentration:Payment processor chip fabrication concentrates in Taiwan and South Korea, exposing Bulgarian distributors to allocation delays and order volatility.
- Magstripe infrastructure:Legacy magnetic stripe terminals in rural Bulgarian retail create technical debt that slows unified payment system rollouts.
Strategic Opportunities
- Plovdiv and Varna merchant corridors:Secondary Bulgarian cities show 40% lower terminal penetration than Sofia, creating whitespace for mobile POS solutions targeting sole traders.
- EU Digital Identity Wallet integration:Forthcoming eIDAS 2.0 mandates will require firmware upgrades enabling government-issued digital ID verification at point of sale.
- SoftPOS smartphone acceptance:Software-based card acceptance eliminates dedicated hardware costs, opening micro-merchant segments previously priced out of electronic payments.
Industry Challenges
- Firmware certification timelines:Bulgarian National Revenue Agency approval processes for terminal software updates extend 8-14 weeks, delaying security patch deployment.
- EMV kernel integration complexity:Legacy payment systems in family-owned Bulgarian retail require costly middleware development to connect modern terminals with back-office accounting software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria POS Terminals Market |
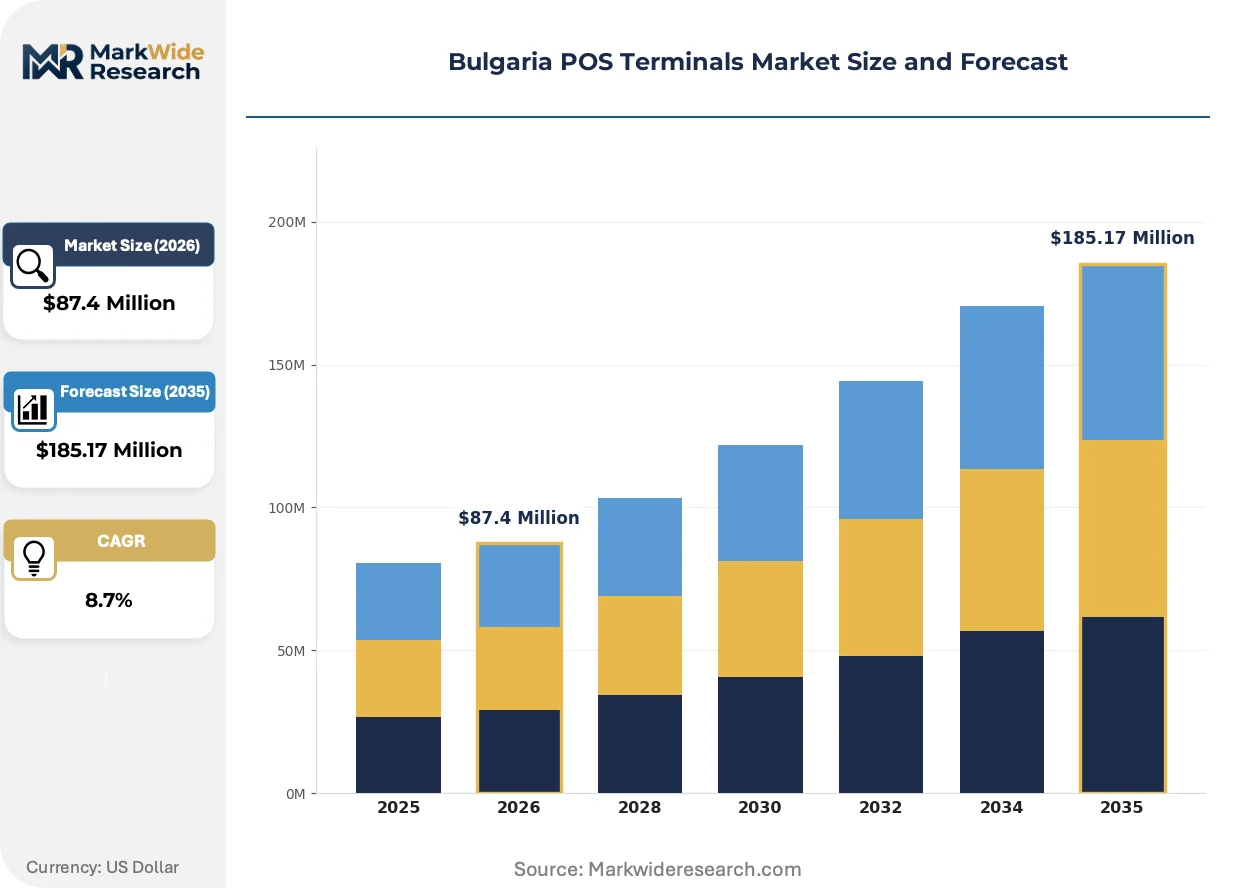
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Self-Service Kiosks, Wireless Terminals Technology: Magstripe, EMV, NFC, QR Code End User: Retail, Hospitality, Healthcare, Transportation Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Selmatic Ltd., PAX Technology, VeriFone Systems, Inc., Datecs Ltd., myPOS, SIS Technology, Eltrade Ltd., SumUp, Toshiba Tec Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria POS Terminals Market Strategic Shifts
Payment terminal architecture is pivoting from fixed-counter hardware toward software-defined acceptance platforms. Bulgarian merchants now prioritize smartphone-integrated solutions and cloud-native transaction processing over traditional proprietary systems.
Android-based open-platform terminals are overtaking proprietary closed-system hardware across Bulgarian retail. These devices run merchant apps alongside payment software, enabling inventory management and loyalty program integration. Mid-sized grocery chains in Sofia and Burgas are deploying these systems fastest. The shift is compressing margins for single-function terminal vendors while opening subscription revenue streams for platform providers.
EU AI Act transparency requirements are reshaping fraud detection module development for payment terminals deployed in Bulgaria. Vendors must document algorithmic decision-making processes used in transaction risk scoring. Hardware manufacturers serving the Bulgarian market are restructuring firmware architectures to isolate AI components for auditability. This regulatory pressure is delaying product launches by 3-6 months for vendors lacking pre-existing compliance frameworks.
Merchant acquisition is fragmenting away from bank-controlled distribution toward independent sales organizations and direct-to-merchant digital onboarding. Bulgarian hospitality operators now compare terminal-plus-acquiring bundles from fintech platforms against traditional bank offerings. This disintermediation is most visible among seasonal tourism businesses in Black Sea resort towns, where flexible contract terms outweigh brand loyalty to established financial institutions.
Bulgaria POS Terminals Market Segmentation
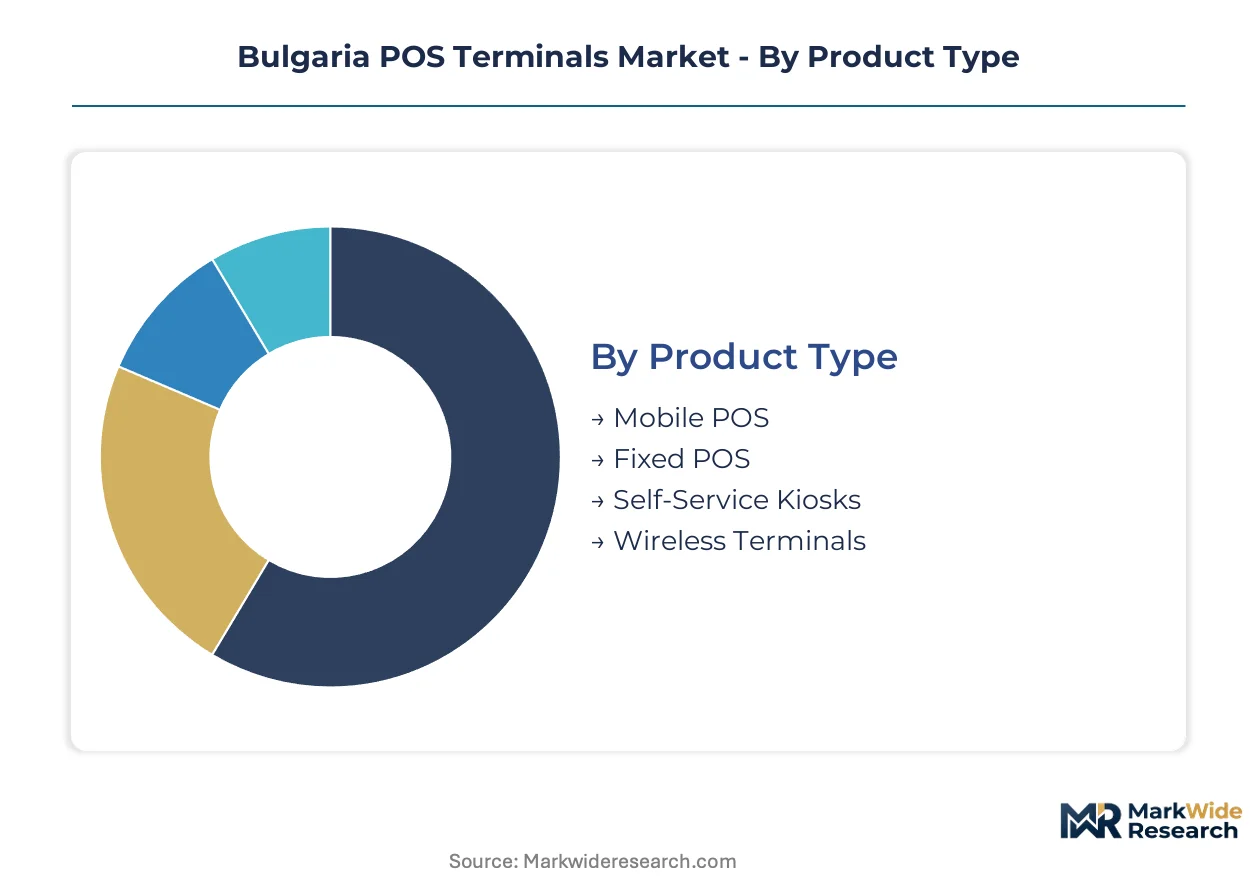
Bulgarian merchants select POS terminals through layered trade-offs between upfront hardware investment, recurring software costs, and compliance complexity. Each segmentation dimension reveals distinct buyer priorities across Sofia's hospitality clusters versus provincial retail networks.
Product Type:
Merchants weigh mobility requirements against transaction volume density and fiscal memory certification constraints.
- Mobile POS:Smartphone-connected card readers with Bluetooth pairing and lightweight fiscal module integration. Sofia's pop-up vendors and Black Sea seasonal operators favor these for rapid deployment without fixed infrastructure commitments.
- Fixed POS:Counter-mounted terminals with embedded printers and certified fiscal memory meeting Bulgarian National Revenue Agency tamper-proof standards. Full-service restaurants in Sofia and Plovdiv anchor demand for reliable high-volume transaction processing.
- Self-Service Kiosks:Standalone ordering and payment stations with integrated touchscreen interfaces.
- Wireless Terminals:Battery-powered devices with cellular or Wi-Fi connectivity for tableside service.
Volume sits with Fixed POS; growth tilts toward Mobile POS.
Technology:
Hardware certification timelines and EU mandate compliance reshape technology migration patterns across merchant tiers.
- NFC:Contactless-enabled readers supporting tap-to-pay cards and mobile wallets through 13.56 MHz radio frequency modules. Bulgarian food service operators prioritize NFC for faster table turnover during peak Sofia dining hours.
- EMV:Chip-card authentication systems with embedded secure microprocessors and dynamic data encryption. Bulgarian banks mandate EMV compliance under PSD2 Strong Customer Authentication protocols, forcing terminal refresh cycles.
- Magstripe:Legacy magnetic stripe readers with static data capture.
- QR Code:Optical scan-based payment acceptance using merchant-presented or customer-presented codes.
EMV commands current installed base; NFC is climbing the fastest as contactless limits rise.
End User:
Sector-specific transaction patterns and reconciliation workflows drive divergent terminal feature requirements.
- Hospitality:Restaurants, hotels, and cafes requiring split-bill functionality, tip adjustment workflows, and cloud-connected fleet management. Sofia's concentration of international hotel chains and fine-dining establishments generates concentrated demand for multi-property reporting integration.
- Retail:Grocery, apparel, and convenience stores prioritizing barcode scanning integration and inventory synchronization. Mid-sized Bulgarian grocery chains in Burgas and Varna deploy Android-based open-platform terminals fastest.
- Healthcare:Clinics and pharmacies with insurance integration and patient billing requirements.
- Transportation:Transit operators and fuel stations needing ruggedized hardware and offline transaction capability.
Hospitality leads current procurement; retail shows steepest expansion trajectory as provincial merchants modernize.
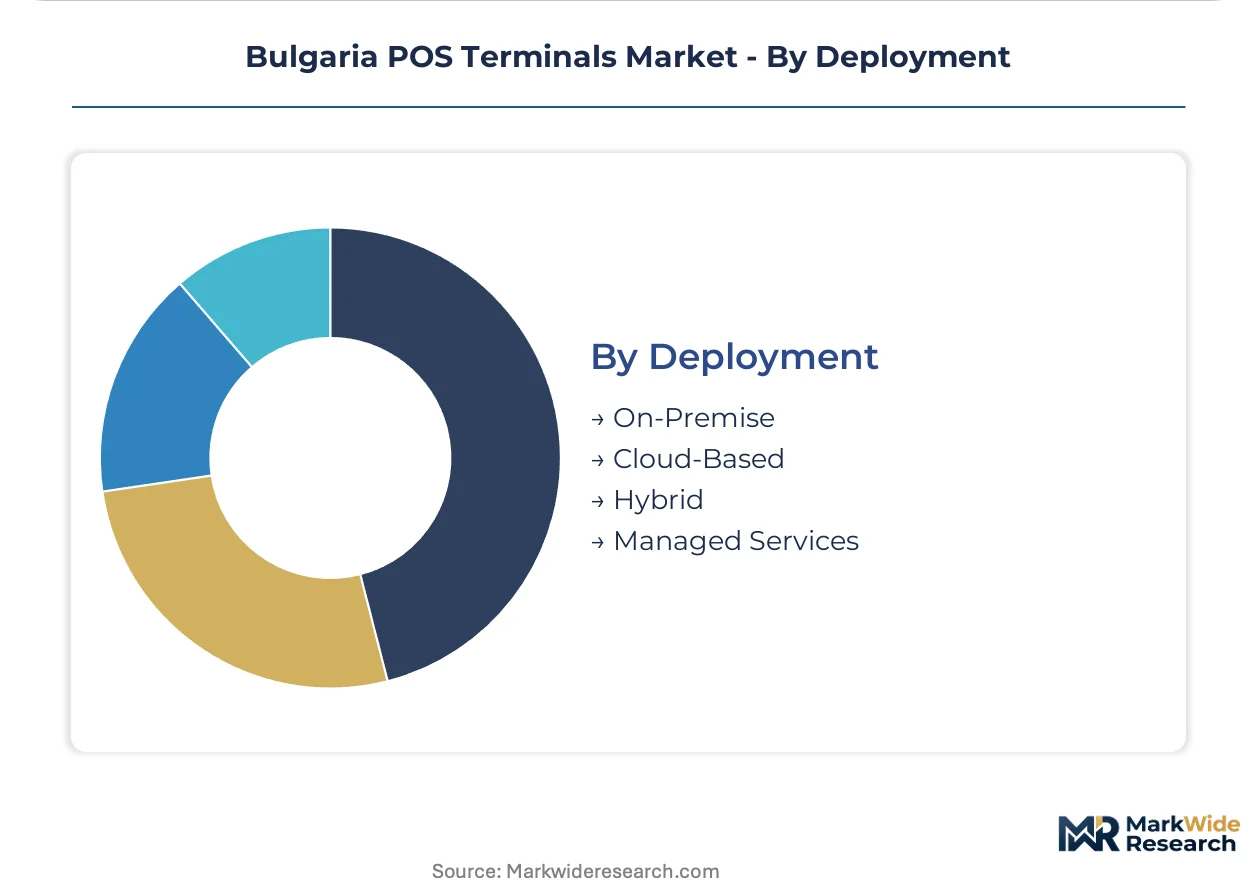
Deployment:
Total cost of ownership calculations separate merchants optimizing for capital expenditure control versus operational flexibility.
- Cloud-Based:Terminals with real-time data synchronization to remote servers, automatic software updates, and subscription-based pricing. Bulgarian hospitality chains favor cloud deployment for unified reconciliation across multiple Sofia properties.
- Hybrid:Systems combining local transaction processing with periodic cloud synchronization for compliance reporting.
- On-Premise:Locally hosted infrastructure with dedicated server maintenance.
- Managed Services:Fully outsourced terminal provisioning, maintenance, and support bundles.
Hybrid retains largest installed base; cloud-based solutions are gaining share fastest among multi-location operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sofia Tech Park anchors Bulgaria's POS terminal demand concentration, drawing hospitality and fintech clusters through tax incentives and EU-funded digital infrastructure programs.
Sofia Capital Region
International hotel chains and fine-dining clusters drive cloud-connected terminal procurement. The Bulgarian National Revenue Agency enforces fiscal memory certification for all payment devices. Central Sofia's hospitality corridor generates concentrated demand for multi-property fleet management systems.
Plovdiv
Manufacturing logistics and retail modernization accelerate terminal deployment. EU cohesion funds support SME digitalization programs requiring compliant payment infrastructure. The Plovdiv industrial zone anchors wholesale and distribution merchant adoption.
Varna
Black Sea tourism seasonality creates demand for flexible, mobile-first payment solutions. The Bulgarian National Bank supervises acquiring license frameworks affecting terminal distribution. Coastal resort operators prioritize rapid-deployment hardware for summer revenue peaks.
Burgas
Port logistics and mid-sized grocery chains drive Android-based open-platform adoption. EU Payment Services Directive mandates force EMV compliance upgrades across merchant tiers. The Burgas retail corridor shows steepest provincial growth in cloud-based terminal subscriptions.
Bulgaria POS Terminals Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fiscal compliance expertise creating stickier relationships than hardware differentiation alone. The vendor base concentrates around three strategic archetypes: multinational platform providers with manufacturing scale, regional specialists with deep local certification knowledge, and fintech-integrated challengers bundling acquiring services. Competitive moves center on firmware certification speed and merchant onboarding automation rather than pure hardware cost reduction.
Within the local certification specialist tier, Datecs Ltd. and Eltrade Ltd. exemplify players whose market position derives from Bulgarian National Revenue Agency protocol mastery rather than manufacturing scale. PAX Technology represents the manufacturing-scale archetype, leveraging production capacity to supply standardized EMV hardware across Balkan distribution channels. myPOS occupies a position bridging fintech integration with rapid merchant acquisition, targeting hospitality operators through bundled terminal-plus-acquiring packages.
| Leading Market Players |
|---|
| Selmatic Ltd. |
| PAX Technology |
| VeriFone Systems, Inc. |
| Datecs Ltd. |
| myPOS |
| SIS Technology |
| Eltrade Ltd. |
| SumUp |
| Toshiba Tec Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Payment Services Directive mandates for contactless infrastructure are compressing terminal replacement cycles and forcing Bulgarian merchants to absorb certified hardware premiums. Supply response concentrates in EMV-certified manufacturing hubs, with fiscal memory compliance requirements adding structural cost layers that uncertified competitors cannot bypass.
Pricing Analysis
Lead-time-driven pricing stratification separates Bulgarian terminal procurement, with certified fiscal memory modules commanding premiums for immediate availability versus extended-delivery alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Price erosion runs through economy-tier imports as non-compliant hardware faces National Revenue Agency exclusion. Small hospitality operators in Sofia show highest price sensitivity, while international hotel chains prioritize compliance assurance over unit cost.
Supply Chain Analysis
Payment processor chip fabrication rests on Taiwanese and South Korean specialty foundries, with secure element production concentrated in German and French semiconductor facilities. Raw material dependencies span rare earth substrates for magnetic components, lithium-ion cells for wireless terminals, and tamper-evident plastics for fiscal memory enclosures. Single-source vulnerability in EMV kernel licensing exposes Bulgarian distributors to allocation delays. Distribution runs through Balkan regional hubs with direct-to-merchant digital channels gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bulgaria POS terminals market functions as a vertical-integration race where firmware certification speed and acquiring service bundling determine competitive position. Players are pursuing backward integration into fiscal memory module production to capture compliance premiums and reduce certification timeline risk.
For Market Incumbents: Deploy firmware certification acceleration as the primary defensive lever against fintech-integrated challengers. Invest in captive fiscal memory production capacity to defend margin position from 15-20% hardware cost premiums mandated by National Revenue Agency protocols. Strengthen channel control through exclusive distribution agreements with Bulgarian National Bank-licensed acquirers to counter myPOS merchant onboarding automation. For New Entrants and Emerging Players: Capture the Plovdiv and Varna merchant corridors where terminal penetration trails Sofia by 40%, targeting sole traders with smartphone-integrated SoftPOS solutions. Exploit underpenetrated provincial retail networks through rapid digital onboarding and flexible seasonal contract terms tailored to Black Sea tourism operators. Lead with bundled acquiring services rather than hardware differentiation to bypass incumbent certification advantages. For Investors and Strategic Acquirers: Re-rating potential sits with local certification specialists given EU Digital Identity Wallet integration mandates requiring firmware upgrade capabilities. Long-term viability favors vendors with established National Revenue Agency audit relationships and recurring software subscription revenue streams. Watch Bulgarian National Bank acquiring license issuance velocity as the inflection indicator for market entry opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Acceleration | Reduces National Revenue Agency approval timelines from 14 weeks to capture mandatory PSD2 upgrade demand. |
| Backward Integration into Fiscal Memory | Captures 15-20% hardware cost premiums through in-house production of tamper-proof transaction logging modules. |
| SoftPOS Platform Launch | Eliminates dedicated hardware costs to penetrate micro-merchant segments previously excluded from electronic payments. |
| Cloud-Native Fleet Management | Enables multi-property reconciliation for Sofia hospitality chains through subscription-based terminal orchestration. |
| EU Digital Identity Wallet Integration | Positions vendors for eIDAS 2.0 mandates requiring government-issued digital ID verification at point of sale. |
Study Parameters
Multi-period observation of terminal deployment rates, certification timeline patterns, and merchant acquisition flows anchored the trend analysis, supplemented by interviews with payment hardware procurement managers at Bulgarian retail chains, fiscal compliance officers at National Revenue Agency-certified vendors, hospitality operations directors, and independent sales organization principals. Secondary validation drew from EU Payment Services Directive implementation reports, Bulgarian National Bank acquiring license registers, customs import data for payment devices, and SEC filings of listed terminal manufacturers. Bottom-up merchant demand modeling triangulated against top-down banking network infrastructure forecasts.
Segment-weighting across product type, technology tier, end-use sector, and deployment model shaped volume and value projections throughout the forecast period. CAGR derivation incorporated hardware replacement cycle compression under PSD2 mandates, cloud subscription revenue recognition patterns, and provincial penetration gap closure rates. Industry-specific inputs included National Revenue Agency certification queue data and EU contactless transaction limit escalation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor allocation volatility and forthcoming eIDAS 2.0 firmware requirements. Forecasts reflect documented assumptions regarding regulatory timeline adherence and merchant digitalization adoption curves. A small set of triggers—Taiwanese foundry capacity constraints, Bulgarian National Revenue Agency audit backlog expansion, and EU real-time payment scheme acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Belgium POS Terminals Market
Payments
Global Gift Card Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
China Payments Market
Payments
Singapore Payments Market
Payments
Bill Splitting Apps Market
Payments
Wearable Payments Market
Payments
Africa Mobile Money Market
Payments
India Real Time Payments Market
Payments
Mobile Point of Sale (POS) Market
Payments
United States Mobile Payment Market
Payments
B2C Payment Market
Payments
Spain Payments Market
Payments
Fuel and Convenience Store POS Market
Payments
Luxembourg POS Terminals Market
Payments
Point-To-Point Encryption (P2PE) Payment Market