
 South Korea Real Time Payments Market | 2026-2036
South Korea Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Real Time Payments Market Analytics
Fintech developers and payment engineers are redrawing competitive boundaries across South Korea's financial infrastructure. Kakao Pay Corp. leverages its messaging ecosystem to dominate P2P transfer volumes, while Toss anchors its position among millennial and Gen Z user segments through specialized savings and investment interfaces. Naver Financial Corp. competes by integrating commerce, content, and payment rails within a single super-app architecture.
Real time payments denote electronic fund transfers that clear and settle within seconds through continuous availability processing networks, typically operating on ISO 20022 messaging standards with 24/7/365 uptime requirements. These systems serve commercial and retail users by eliminating settlement risk and enabling immediate liquidity access for merchants and consumers. Mobile wallet and QR code channels command the largest transaction volumes, while banking API platforms represent the fastest-growing infrastructure layer as institutions open core systems to third-party developers. Merchant payment and e-commerce transaction types concentrate margin pools, whereas standalone apps face consolidation pressure from integrated service models.
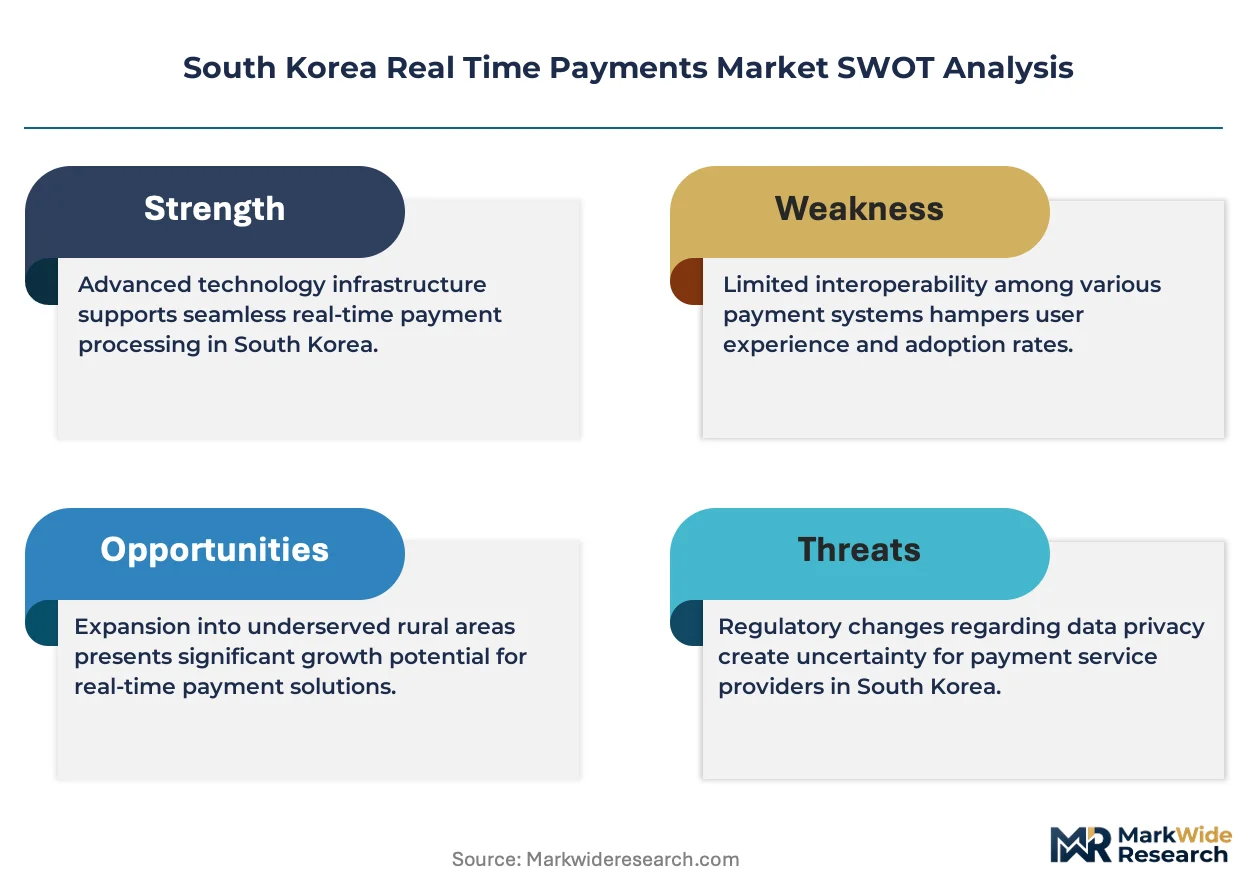
The Financial Services Commission enforces open banking standards that mandate fee transparency and interoperability, while the Bank of Korea supervises systemic risk in retail payment networks. MFDS guidelines on data security in financial services and the Personal Information Protection Commission's consent frameworks shape product design and market access protocols. Stakeholders must monitor how central bank digital currency pilots alter clearing hierarchies and whether API governance standards fragment across competing platform consortia.
Market Dynamics
The Financial Services Commission's open banking mandates are forcing incumbent banks to dismantle proprietary payment silos and expose core infrastructure through standardized APIs, redrawing competitive boundaries between traditional institutions and fintech challengers across Seoul's retail corridors.
Growth Catalysts
- Financial Services Commission Open Banking Mandates:The regulator's interoperability requirements accelerate third-party developer access to core banking systems, expanding API-based payment rails.
- QR Code Merchant Adoption:Small and medium enterprises in Busan's commercial districts integrate low-cost acceptance infrastructure, reducing cash-handling overhead and settlement delays.
- Bank of Korea Digital Currency Pilots:Central bank experiments with retail CBDC architectures test programmable payment capabilities and real-time settlement finality.
Market Restraints
- Data Localization Requirements:The Personal Information Protection Commission's consent frameworks impose infrastructure redundancy costs and cross-border data friction.
- Legacy Core Banking Dependencies:Tier-1 institutions maintain mainframe architectures that resist real-time processing modifications without substantial capital expenditure.
- Interchange Fee Compression:Regulatory caps on merchant discount rates constrain revenue pools available for network infrastructure investment.
Strategic Opportunities
- Gyeonggi Province Logistics Corridors:Underpenetrated B2B payment automation in warehousing and freight settlement offers white-space expansion for invoice financing integration.
- Cross-Border Remittance Rails:ASEAN corridor demand from migrant worker populations creates anchor use cases for blockchain-based settlement layers.
- Embedded Finance Convergence:Transportation and utility platforms integrate payment functionality directly into service applications, bypassing standalone wallet interfaces.
Industry Challenges
- ISO 20022 Migration Complexity:Financial institutions face message format conversion timelines that risk interoperability gaps during parallel system operation.
- Cloud Infrastructure Certification:MFDS guidelines on data security in financial services delay public cloud adoption for transaction processing workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Real Time Payments Market |
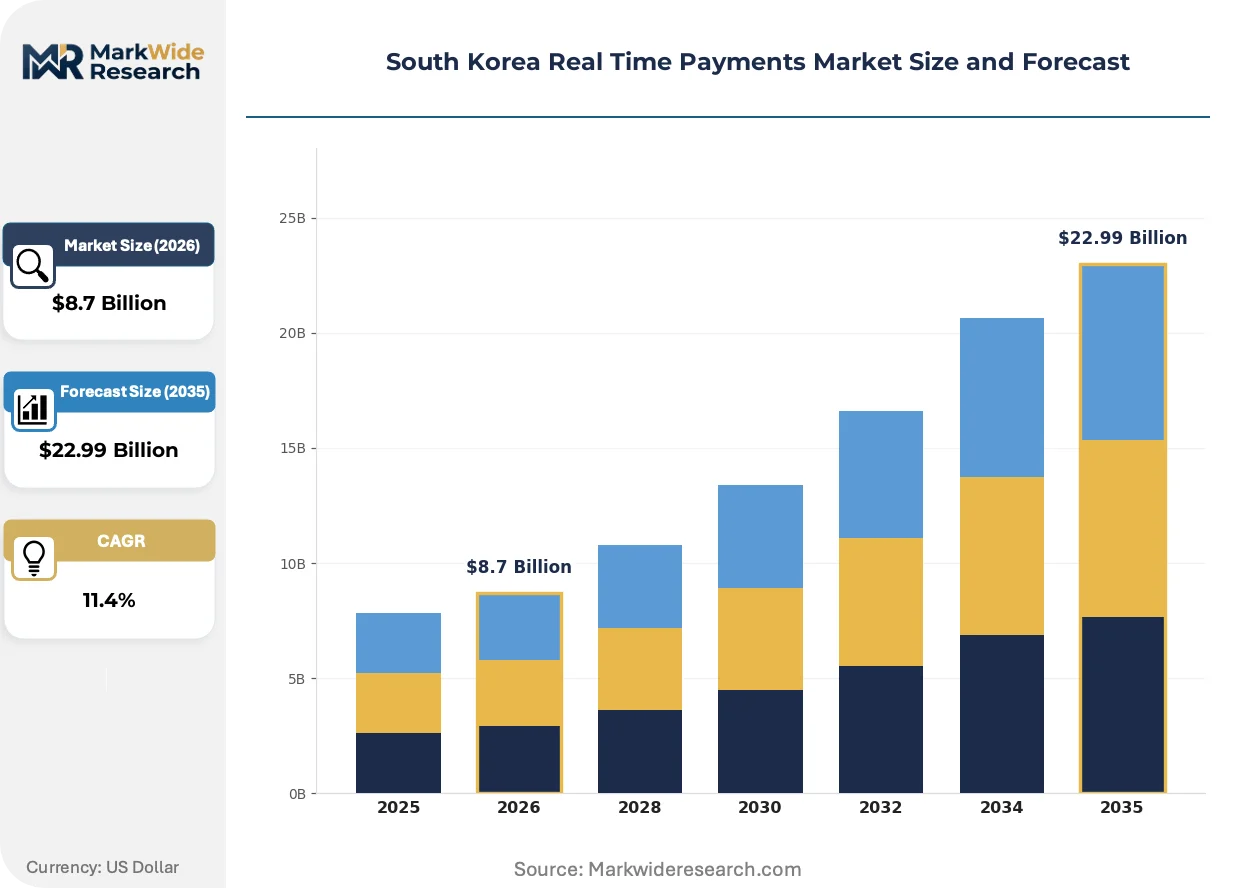
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Wallet, Credit Card, Bank Transfer, QR Code Transaction Type: P2P, Bill Payment, E-commerce, Merchant Payment Platform Type: Standalone App, Integrated Service, Banking API, Digital Banking User Segment: Consumers, Small Businesses, Corporates, Freelancers |
| Companies Covered | VISA Inc., EMQ, Toss (Viva Republica Inc.), PayCo (NHN Corp.), Fiserv Inc., Kakao Pay Corp., Mastercard Inc., ACI Worldwide Inc., Naver Financial Corp. (Naver Pay), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Real Time Payments Market Evolving Landscape
Distributed ledger architectures and programmable money experiments are compressing settlement finality from hours to seconds, while regulatory sandboxes accelerate novel payment instrument testing outside traditional licensing frameworks.
Blockchain-based settlement infrastructure is fragmenting correspondent banking relationships by enabling direct peer-to-peer value transfer without intermediary nostro-vostro accounts. Asset managers and securities depositories in Seoul's Yeouido financial district pilot atomic settlement for repurchase agreements. The structural consequence is disintermediation of traditional clearinghouses from certain instrument categories.
The Financial Services Commission's API governance standards mandate standardized authentication protocols and fee disclosure mechanisms across all participating institutions. Payment service providers must reengineer customer onboarding flows to accommodate multi-bank consent management. Retail banking divisions absorb compliance costs while fintech challengers gain normalized access to account information services.
Merchant acquisition patterns are rotating from hardware-dependent POS terminals toward software-only QR acceptance. Convenience store chains and quick-service restaurants in the greater Seoul metropolitan area eliminate dedicated payment device procurement in favor of smartphone-based merchant interfaces. This compression of acceptance infrastructure alters distributor economics and after-sales service revenue pools for terminal manufacturers.
South Korea Real Time Payments Market Segmentation
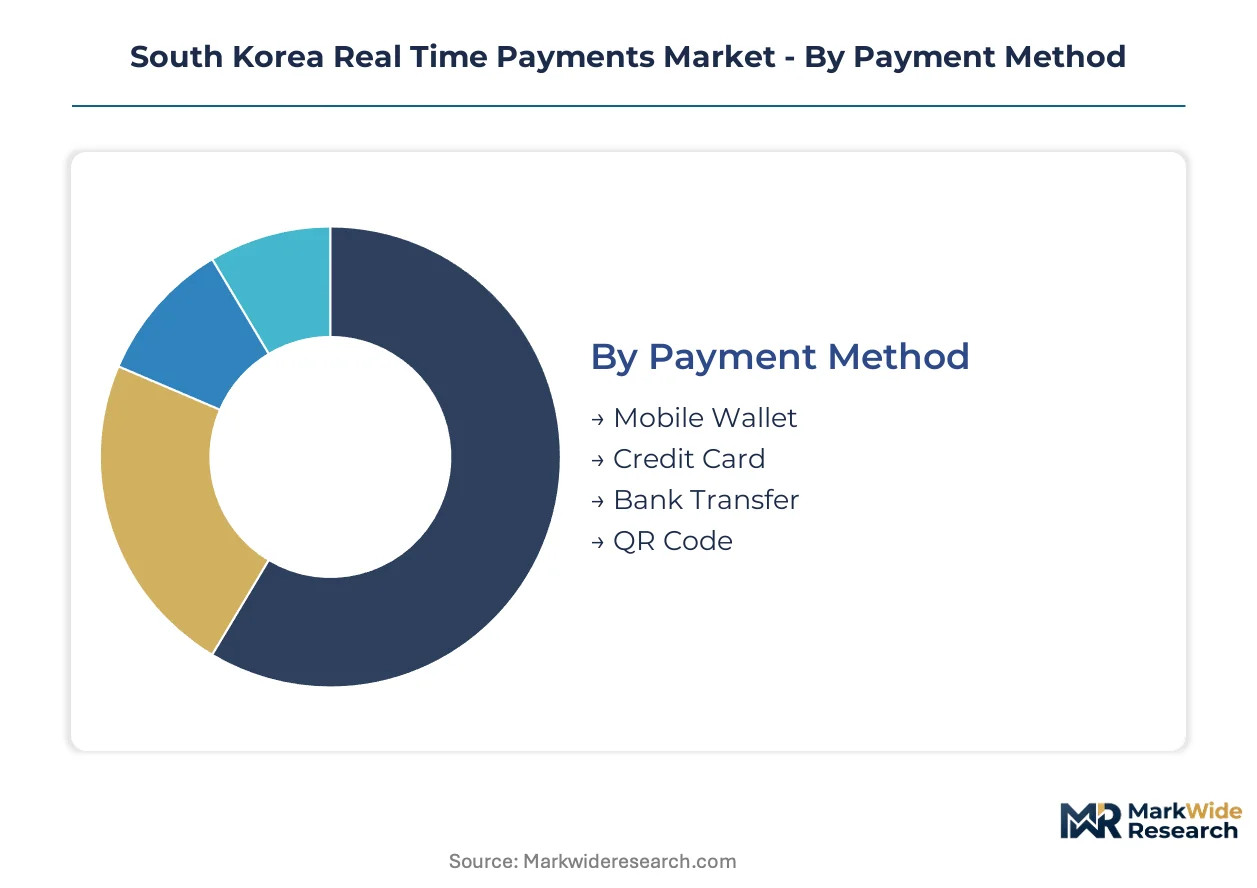
Payment method diversity across South Korea's real time infrastructure determines where transaction economics concentrate. Platform architecture choices reshape developer access and merchant onboarding costs across Seoul's retail corridors and Busan's SME clusters.
Payment Method:
Mobile wallet and QR code channels capture the densest margin pools through merchant discount rates and interchange economics, while credit card rails face regulatory compression on fee structures.
- Mobile Wallet:Smartphone-native payment interfaces store tokenized credentials and execute biometric-authenticated transfers through NFC or QR protocols. Demand concentrates among millennial and Gen Z demographics in Seoul's convenience store chains and quick-service restaurants, driven by Kakao Pay and Toss ecosystem lock-in effects.
- QR Code:Static and dynamic matrix codes enable software-only merchant acceptance without dedicated terminal hardware. Busan's SME commercial districts and Gyeonggi Province logistics hubs show accelerating adoption, propelled by zero upfront procurement costs and immediate settlement finality.
- Credit Card:Traditional card networks process real time authorization through tokenized credentials linked to mobile interfaces.
- Bank Transfer:Direct account-to-account rails leverage open banking APIs for immediate clearing without card network intermediation.
Mobile wallet holds installed capacity. QR Code is rotating up the share rankings.
Transaction Type:
Merchant payment and e-commerce transaction types command premium economics through volume scale and value-added service attach rates, whereas P2P transfers operate on thin or zero-fee models.
- Merchant Payment:Retail and service sector transactions settle immediately to merchant accounts with integrated reconciliation and inventory management hooks. Seoul's greater metropolitan area retail corridors generate concentrated demand, reinforced by Financial Services Commission mandates for interoperable acceptance infrastructure.
- E-commerce:Online checkout flows integrate real time confirmation with escrow and buyer protection mechanisms. Gyeonggi Province's warehousing and fulfillment clusters drive B2C volume expansion, supported by embedded finance convergence in marketplace platforms.
- P2P:Person-to-person transfers split bills and remit funds through messaging-integrated interfaces.
- Bill Payment:Utility and subscription settlements execute on scheduled or trigger-based automation.
Merchant payment dominates transaction value. E-commerce is climbing the fastest in share rankings.
Platform Type:
Banking API platforms represent the steepest expansion trajectory as institutions dismantle proprietary silos, while standalone apps face consolidation pressure from integrated service economics.
- Banking API:Standardized interfaces expose core account services to third-party developers under Financial Services Commission governance protocols. Seoul's fintech developer community concentrates demand generation, compelled by open banking interoperability mandates and normalized access to account information services.
- Integrated Service:Super-app architectures embed payment rails within messaging, commerce, and content ecosystems. Naver Financial and Kakao Pay anchor user retention through unified interface density, displacing standalone wallet switching costs.
- Standalone App:Dedicated payment applications without ecosystem integration face user acquisition headwinds.
- Digital Banking:Neobank-native platforms build real time infrastructure from cloud-first architectures without legacy mainframe dependencies.
Banking API holds developer mindshare. Integrated service is rotating up the share rankings.
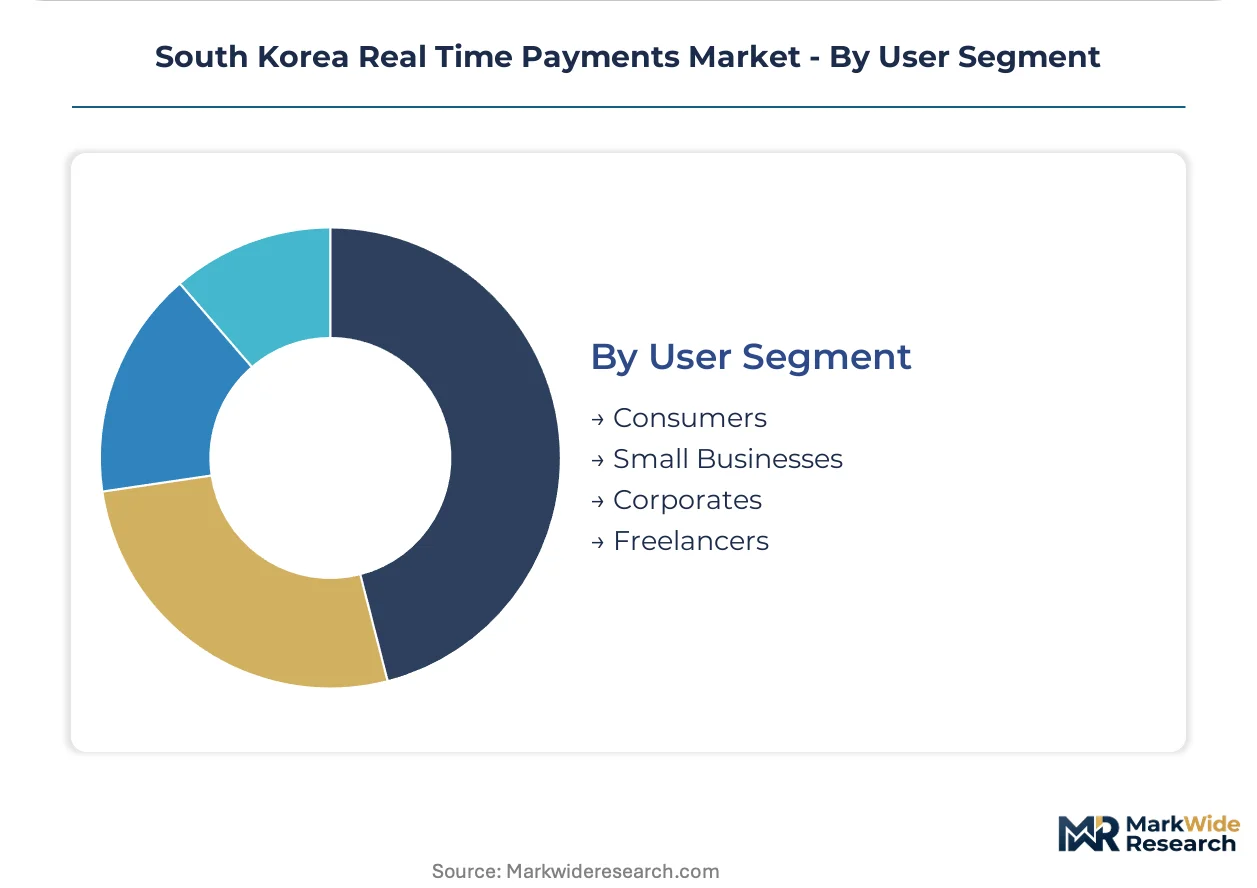
User Segment:
Corporate and small business segments generate recurring revenue through treasury automation and working capital optimization, while consumer volumes rely on monetization through adjacent financial services.
- Small Businesses:Merchants and professional services firms automate invoice collection and supplier settlements through mobile-first interfaces. Busan's commercial districts and Gyeonggi Province logistics corridors show underpenetrated B2B automation demand, catalyzed by QR code adoption and reduced cash-handling overhead.
- Corporates:Enterprise treasury operations require multi-bank connectivity and programmable payment scheduling with ERP integration. Seoul's Yeouido financial district institutions pilot atomic settlement for repurchase agreements, driven by distributed ledger compression of settlement finality.
- Consumers:Retail users execute P2P splits, merchant purchases, and bill payments through smartphone interfaces.
- Freelancers:Independent contractors manage irregular income flows and tax withholding through simplified onboarding protocols.
Small businesses hold activation density. Corporates are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area commands premium merchant discount rates that subsidize thinner margins in Busan-Ulsan's SME corridors, creating a pricing-power asymmetry that shapes infrastructure investment flows across South Korea's payment networks.
Seoul Capital Area
Kakao Pay and Toss drive P2P transfer volumes through messaging-integrated interfaces, while the Financial Services Commission enforces open banking interoperability mandates. Yeouido's financial district institutions pilot atomic settlement for repurchase agreements using distributed ledger architectures.
Busan-Ulsan
QR code merchant adoption accelerates among SME clusters seeking zero upfront procurement costs, supported by the Bank of Korea's retail CBDC experiments testing programmable payment capabilities. Busan's commercial districts eliminate cash-handling overhead through smartphone-based acceptance infrastructure.
Gyeonggi Province
Logistics corridors generate underpenetrated B2B payment automation demand for invoice financing integration, with warehousing and freight settlement operations concentrated in Suwon and Incheon satellite cities. The Personal Information Protection Commission's consent frameworks shape cross-border data protocols for fulfillment platforms.
Daegu-Gyeongbuk
Manufacturing supply chains anchor corporate treasury automation requirements, driven by automotive and electronics component suppliers seeking multi-bank ERP connectivity. The MFDS guidelines on data security in financial services delay public cloud adoption for transaction processing workloads in regional banking operations.
Daejeon-Sejong
Government administrative functions concentrate demand for bill payment automation and scheduled settlement protocols, with Sejong City's planned administrative capital status driving embedded finance convergence in public service platforms. The Bank of Korea supervises systemic risk oversight from its Daejeon operational hub.
South Korea Real Time Payments Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Korea's real time payments infrastructure. The market structure concentrates around messaging-ecosystem incumbents with super-app architectures, challenger fintechs with specialized vertical interfaces, and global network operators with cross-border settlement rails. Three strategic archetypes dominate: platform-integrated payment rails, standalone wallet specialists, and infrastructure-technology vendors. Competitive moves center on API governance standardization and embedded finance convergence through transportation and utility platform partnerships.
Within the platform-integrated tier, Kakao Pay Corp. and Naver Financial Corp. anchor user retention through unified interface density that displaces standalone wallet switching costs. Toss exemplifies the challenger fintech archetype through millennial and Gen Z segment specialization. Global network operators including VISA Inc. and Mastercard Inc. occupy positions as cross-border settlement infrastructure providers, though their domestic merchant acquiring presence faces compression from QR code and open banking alternatives.
| Leading Market Players |
|---|
| VISA Inc. |
| EMQ |
| Toss (Viva Republica Inc.) |
| PayCo (NHN Corp.) |
| Fiserv Inc. |
| Kakao Pay Corp. |
| Mastercard Inc. |
| ACI Worldwide Inc. |
| Naver Financial Corp. (Naver Pay) |
| Others |
Value Network & Pricing Analysis
Platform scale economies in Seoul's super-app ecosystems compress transaction processing costs below standalone wallet thresholds, concentrating pricing power among messaging-integrated incumbents while forcing specialized challengers toward thinner margin structures. This dynamic anchors price floors through volume-dependent unit economics and reshapes supplier bargaining positions across infrastructure layers.
Pricing Analysis
The customization-premium spread between configured enterprise treasury solutions and standardized retail interfaces widens as corporate clients demand ERP integration and programmable scheduling capabilities. Merchant discount rates stratify across premium white-label deployments, standard API-accessed rails, and economy QR-code acceptance tiers, with the Financial Services Commission's interchange caps intensifying compression on middle-tier offerings. Small businesses in Busan's SME corridors exhibit highest price sensitivity, while Seoul's corporate treasury divisions absorb premium pricing for atomic settlement and multi-bank connectivity.
Supply Chain Analysis
Inbound logistics costs through Busan Port and Incheon container terminals influence hardware terminal distribution economics, though software-only QR acceptance is displacing physical device procurement. Core processing infrastructure draws from domestic cloud service providers and certified data centers in Seoul and Gyeonggi Province, with legacy mainframe dependencies creating single-source vulnerability for Tier-1 institutions. Distribution runs through API gateway providers and embedded finance partnerships rather than traditional hardware distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around super-app ecosystems that internalize payment switching costs, fragmenting demand access for standalone wallet specialists and compressing their margin recovery options.
For Market Incumbents: Fortify API governance control by deepening certification investment in Financial Services Commission interoperability standards, while anchoring user retention through transportation and utility platform exclusivity arrangements that block challenger fintech onboarding channels. For New Entrants and Emerging Players: Differentiate on B2B invoice financing integration in Gyeonggi Province's underpenetrated logistics corridors, targeting freight settlement automation as the most penetrable white-space segment with direct sales to warehousing operators bypassing incumbent banking relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among banking API platform operators with embedded ERP connectivity and multi-tenant architectures; long-term viability favors cloud-native infrastructure vendors over legacy mainframe-dependent service providers, with the signal to watch being central bank digital currency pilot commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| API Governance Certification | Financial Services Commission interoperability mandates normalize third-party access across Seoul's banking infrastructure. |
| Embedded Finance Partnership | Transportation and utility platforms in Busan integrate payment rails directly into service applications. |
| QR Infrastructure Deployment | Software-only merchant acceptance eliminates hardware procurement costs in Gyeonggi Province logistics hubs. |
| Atomic Settlement Pilot | Yeouido financial institutions test distributed ledger compression for repurchase agreement finality. |
| Cross-Border Rail Development | ASEAN corridor demand from migrant worker populations anchors blockchain-based remittance infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment engineers at fintech developers, platform architects at super-app operators, treasury automation leads at logistics enterprises, and merchant acquisition heads at retail chains. Secondary validation drew from Financial Services Commission regulatory filings, Bank of Korea payment system statistics, open banking API documentation, and hyperscaler cloud service disclosures. Bottom-up transaction volume modeling triangulated against top-down infrastructure capacity assessments.
Across the projection horizon, the analytical framework segmented volume and value outputs by payment method, transaction type, platform architecture, and user segment, with CAGRs derived from trend extrapolation of open banking adoption curves and mobile wallet penetration rates. Forecast inputs incorporated ISO 20022 migration timelines and central bank digital currency pilot expansion scenarios without assuming specific commercialization dates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory support for open banking interoperability or accelerated legacy system modernization would require recalibration. Practitioners should keep alternative scenarios live as Financial Services Commission API governance standards and Personal Information Protection Commission consent frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Digital Transaction Management Market
Payments
Denmark Mobile Payments Market
Payments
Mobile Payment Security Software Market
Payments
New Zealand Payments Market
Payments
3D Secure Payment Authentication Market
Payments
France POS Terminal Market
Payments
Australia Payments Market
Payments
E-Commerce Payments Market
Payments
France Buy Now Pay Later Services Market
Payments
Direct Carrier Billing Market
Payments
United States POS Terminals Market
Payments
Mobile Payment Security Market
Payments
Global Telecom Billing Market
Payments
Cyprus POS Terminals Market
Payments
Finland Payments Market