
 Asia Pacific Mobile Wallet Market | 2026-2036
Asia Pacific Mobile Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Mobile Wallet Market Analysis
Multi-source technology partnerships is pivoting how platform providers assemble their payment stacks across the Asia Pacific Mobile Wallet Market. Ant Group leverages its merchant ecosystem dominance to lock in small-business transaction flows. Samsung Electronics anchors its position through hardware-software integration across its device installed base. Tencent competes by weaving wallet functionality into super-app architectures that capture user attention across messaging, gaming, and commerce.
A mobile wallet constitutes a software-based payment system that stores encrypted credential tokens on portable devices, executing transactions through near-field communication chips, QR code optical scanning, or biometric authentication modules to transfer monetary value between parties. Its primary commercial purpose is to displace physical currency and card-present infrastructure with real-time, account-agnostic settlement rails. Peer-to-Peer usage generates the highest transaction frequency but the thinnest margin pools, while Bill Payments commands superior unit economics through recurring revenue structures and enterprise integration fees. QR Code technology leads deployment in cost-sensitive markets where merchant hardware investment is constrained, though NFC infrastructure is deepening in South Korea and Japan where contactless terminal density is highest.
India's Reserve Bank of India mandates full-KYC compliance for wallet balance limits, while China's SAMR enforces anti-monopoly scrutiny on platform payment routing. Australia's ASIC and Japan's FSA both impose operational risk frameworks that elevate capital requirements for licensed e-money issuers. South Korea's Financial Services Commission has introduced open-banking APIs that force incumbent wallets to interoperate with challenger platforms. Stakeholders must monitor whether India's central bank digital currency pilot expands to displace private wallet float, and whether ASEAN mutual recognition agreements harmonize cross-border licensing before regional consolidation accelerates.
Market Dynamics
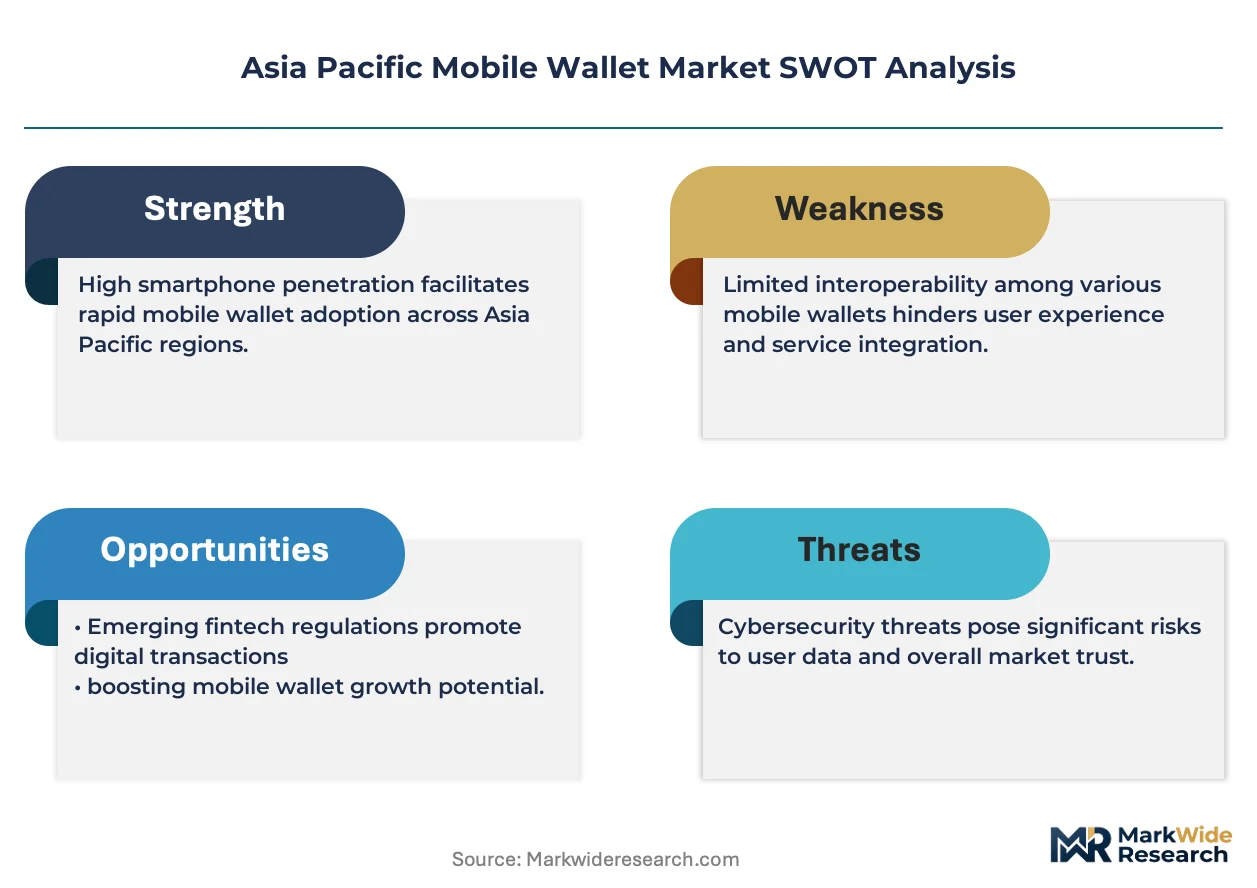
Super-app convergence is compressing standalone wallet margins across Asia Pacific as platforms bundle payments with messaging, commerce, and transport. India's RBI mandates and China's SAMR enforcement are forcing providers to rebuild core infrastructure around compliance-first architectures rather than growth-first scaling.
Growth Catalysts
- Indonesia's unbanked corridor:Urban populations from Jakarta to Surabaya bypass traditional banking entirely, creating first-mover adoption velocity for mobile-native financial services.
- South Korea's open-banking APIs:The Financial Services Commission mandates interoperability, forcing incumbent wallets to open rails that challenger platforms exploit for market entry.
- QR code merchant economics:Optical scanning eliminates hardware investment barriers for micro-merchants, expanding addressable merchant bases beyond NFC terminal density constraints.
Market Restraints
- Full-KYC compliance costs:India's RBI balance-limit rules impose identity-verification infrastructure burdens that raise customer acquisition expenses for tier-2 and tier-3 city expansion.
- Platform concentration risk:China's real-name verification mandates and anti-monopoly scrutiny on payment routing create operational uncertainty for dominant wallet providers.
- Biometric hardware dependency:Fingerprint and facial recognition modules require secure element chipsets that face supply constraints from Taiwan-based semiconductor foundries.
Strategic Opportunities
- ASEAN cross-border harmonization:Mutual recognition agreements on digital payment licensing would enable wallet portability across Indonesia, Malaysia, Thailand, and Vietnam.
- Bill payment enterprise integration:Recurring revenue structures and B2B API fees offer superior unit economics compared to thin-margin peer-to-peer transfers.
- Biometric-NFC convergence:South Korea and Japan's contactless terminal density enables next-generation authentication protocols that reduce transaction friction.
Industry Challenges
- Compliance engineering talent scarcity:Full-stack developers with central bank regulatory interface experience command premium compensation that strains challenger platform burn rates.
- Legacy core banking integration:State-owned banks across India and Indonesia maintain batch-processing architectures that create settlement latency incompatible with real-time wallet expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Mobile Wallet Market |
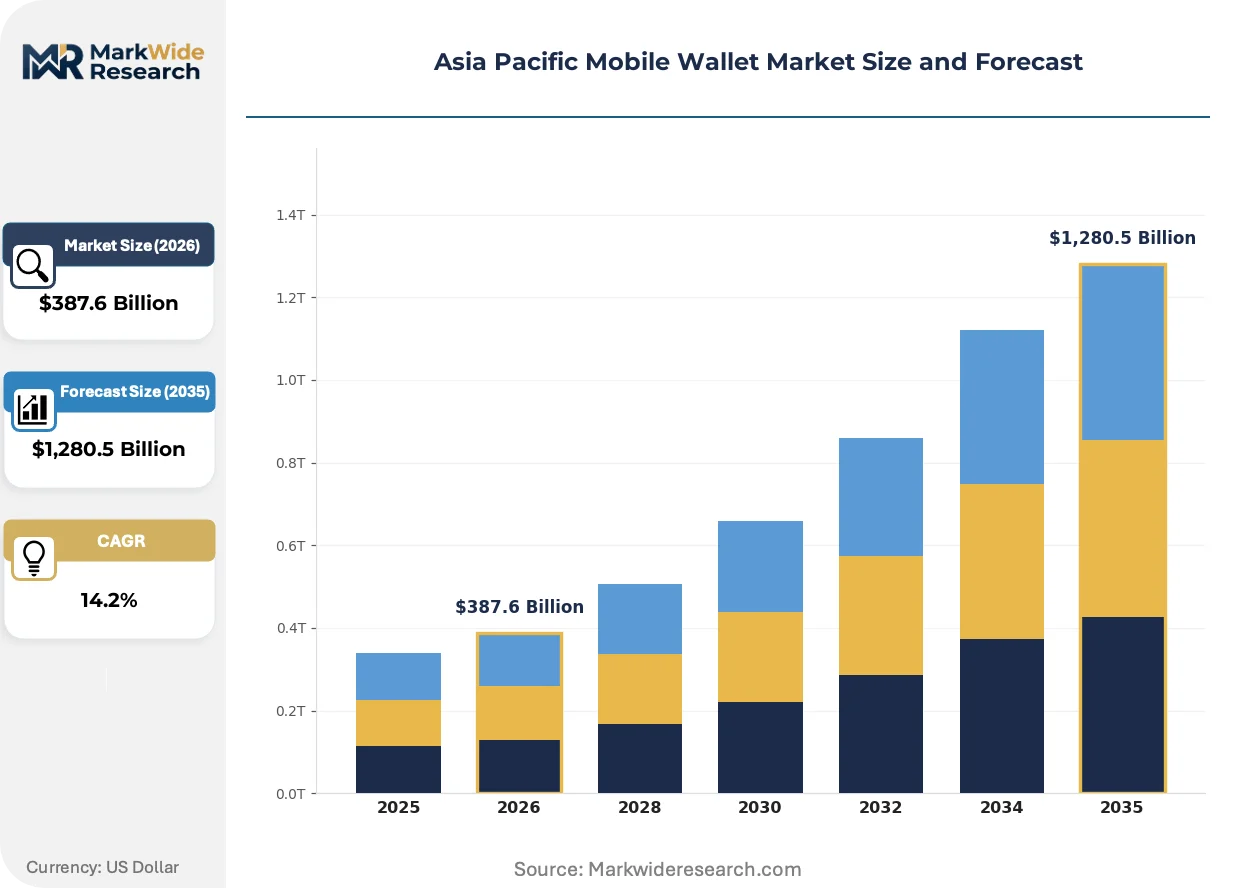
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Usage Type: Peer-to-Peer, Online Shopping, Bill Payments, In-Store Purchases Device Type: Smartphones, Tablets, Wearables, Laptops Technology: NFC, QR Code, Biometrics, Magnetic Stripe Customer Segment: Consumers, Small Businesses, Large Enterprises, Corporates |
| Companies Covered | Apple, Samsung Electronics, Ant Group, PayPal, Kakao Corp, Tencent, Google, Amazon.com, Alibaba Group Holding, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Mobile Wallet Market Emerging Trajectories
Embedded finance architectures are dissolving boundaries between wallet functionality and non-financial super-apps across Southeast Asian markets. Providers now compete on context-aware transaction triggers rather than standalone payment utility.
Biometric authentication modules are integrating secure element processors directly into mid-range smartphone chipsets, enabling facial recognition and fingerprint verification without dedicated hardware peripherals. Indonesian and Vietnamese handset assemblers are adopting these system-on-chip designs fastest, compressing the price threshold for biometric-enabled wallets. The technology is integrating payment rails with device identity layers that reduce fraud liability for issuing banks.
India's central bank digital currency pilot is forcing private wallet providers to architect float-compatible settlement layers that coexist with sovereign digital rupee infrastructure. The RBI's phased expansion mandates interoperability protocols that erode proprietary closed-loop advantages. Wallet operators in Mumbai, Bangalore, and Delhi NCR are rebuilding core ledgers to accommodate CBDC rails alongside existing UPI transaction flows.
Merchant acquisition models are pivoting from hardware subsidies toward revenue-share arrangements tied to transaction volume. Indonesian retail cooperatives and Malaysian convenience store chains now prefer zero-upfront terminal deployments with percentage-based fee structures. This shift concentrates bargaining power with platform providers who can aggregate micro-merchant density into enterprise-grade settlement pools.
Asia Pacific Mobile Wallet Market Segmentation
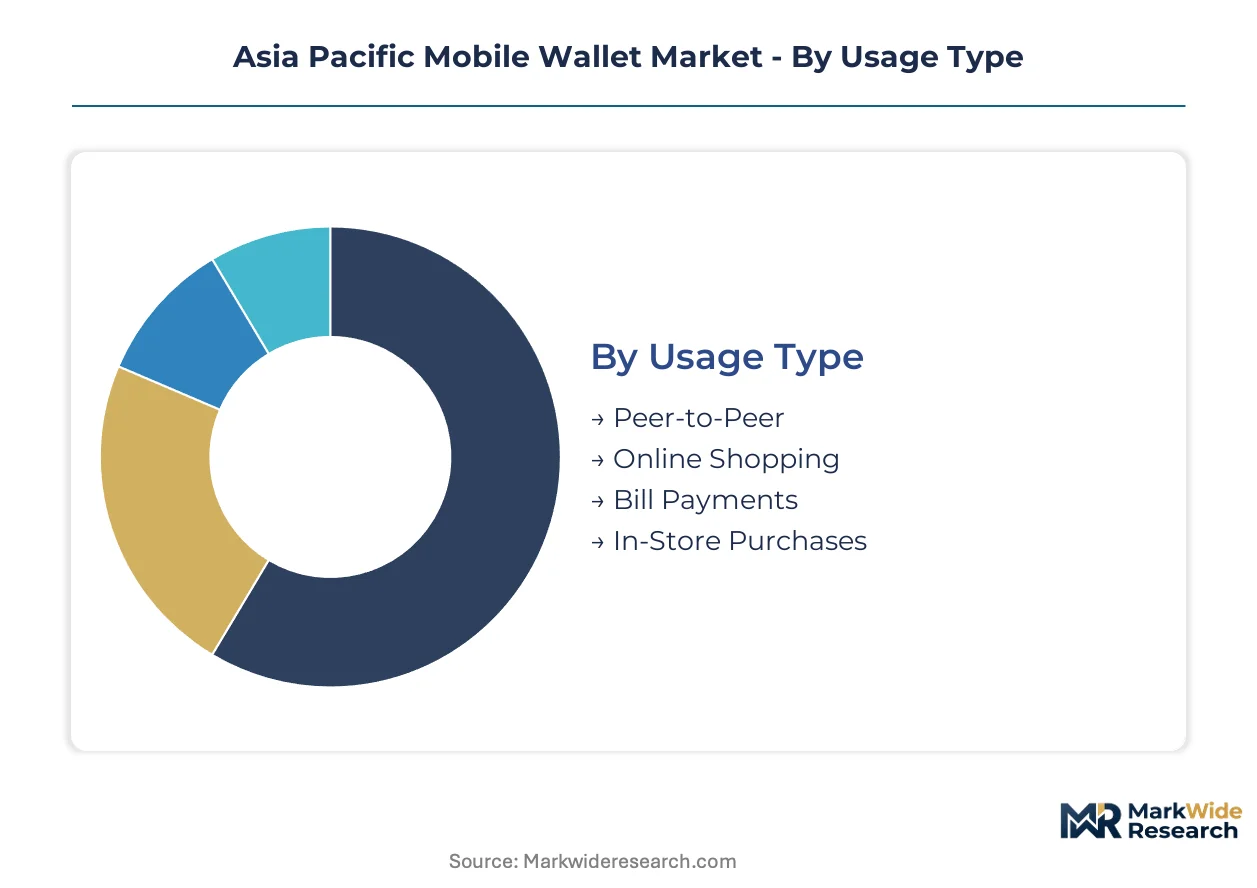
Mobile wallet providers across Asia Pacific architect their product roadmaps around distinct usage patterns, hardware ecosystems, and compliance tiers. Segmentation discipline separates thin-margin peer-to-peer plays from enterprise-grade recurring revenue streams.
Usage Type:
Standardized transaction rails dominate high-frequency use cases, while customized enterprise integrations capture premium positioning across this category.
- Peer-to-Peer:Transfers between individual wallet accounts execute through encrypted token exchange with minimal settlement infrastructure. Demand concentrates in Indonesia's urban corridor from Jakarta to Surabaya, where unbanked populations rely on person-to-person remittance flows as primary financial infrastructure.
- Bill Payments:Recurring settlement protocols integrate with utility, telecom, and subscription billing systems through API-connected enterprise backends. This segment commands superior unit economics through recurring revenue structures and B2B integration fees across India's tier-1 metropolitan clusters.
- Online Shopping:E-commerce checkout flows embed wallet authentication through one-click token validation. Merchant adoption accelerates fastest in Vietnam and Philippines digital retail corridors.
- In-Store Purchases:Physical retail acceptance relies on QR code scanning or NFC tap protocols at merchant terminals. Micro-merchant density in Malaysian convenience store chains drives addressable market expansion.
Leading the category by volume: Peer-to-Peer. Growing fastest: Bill Payments.
Device Type:
Hardware-software integration depth varies sharply by form factor, with premium biometric capabilities concentrated in flagship-tier smartphones while cost-optimized tablets serve merchant-facing deployments.
- Smartphones:Primary wallet interface combining secure element chipsets, biometric sensors, and cellular connectivity for real-time transaction authorization. Samsung Electronics anchors market positioning through hardware-software integration across its device installed base in South Korea and broader Southeast Asia.
- Wearables:Wrist-worn devices with NFC coils and tokenized payment credentials enable contactless transactions without phone retrieval. South Korea's contactless terminal density supports fastest adoption velocity for watch and band form factors.
- Tablets:Larger-screen merchant-facing terminals for order management and customer checkout in retail environments. Indonesian retail cooperatives deploy these for cooperative member transactions.
- Laptops:Browser-based wallet interfaces with hardware security key integration for high-value B2B settlements. Corporate procurement workflows in Japan's enterprise sector favor this authentication tier.
Smartphones dominate absolute transaction volume. Wearables expand most quickly as biometric-NFC convergence matures.
Technology:
Deployment cost structures and fraud liability profiles diverge fundamentally across authentication modalities, with optical scanning eliminating hardware barriers while chip-based protocols command premium security positioning.
- QR Code:Two-dimensional barcode scanning enables payment initiation through smartphone cameras without dedicated merchant terminal investment. Optical scanning eliminates hardware investment barriers for micro-merchants across Indonesia and Vietnam, expanding addressable bases beyond NFC terminal density constraints.
- NFC:Near-field communication chipsets establish encrypted radio links between devices and contactless terminals for sub-second transaction completion. South Korea and Japan's contactless terminal density enables next-generation authentication protocols that reduce transaction friction.
- Biometrics:Fingerprint and facial recognition modules authenticate transactions through secure element processors integrated into smartphone chipsets. Indonesian and Vietnamese handset assemblers adopt these system-on-chip designs fastest, compressing price thresholds for biometric-enabled wallets.
- Magnetic Stripe:Legacy card emulation through magnetic field generation supports backward compatibility with older point-of-sale infrastructure. Australia's remaining mag-stripe terminal base sustues residual demand for this transitional technology.
QR Code leads merchant acquisition by volume. Biometrics gains share fastest as mid-range chipsets integrate secure elements.
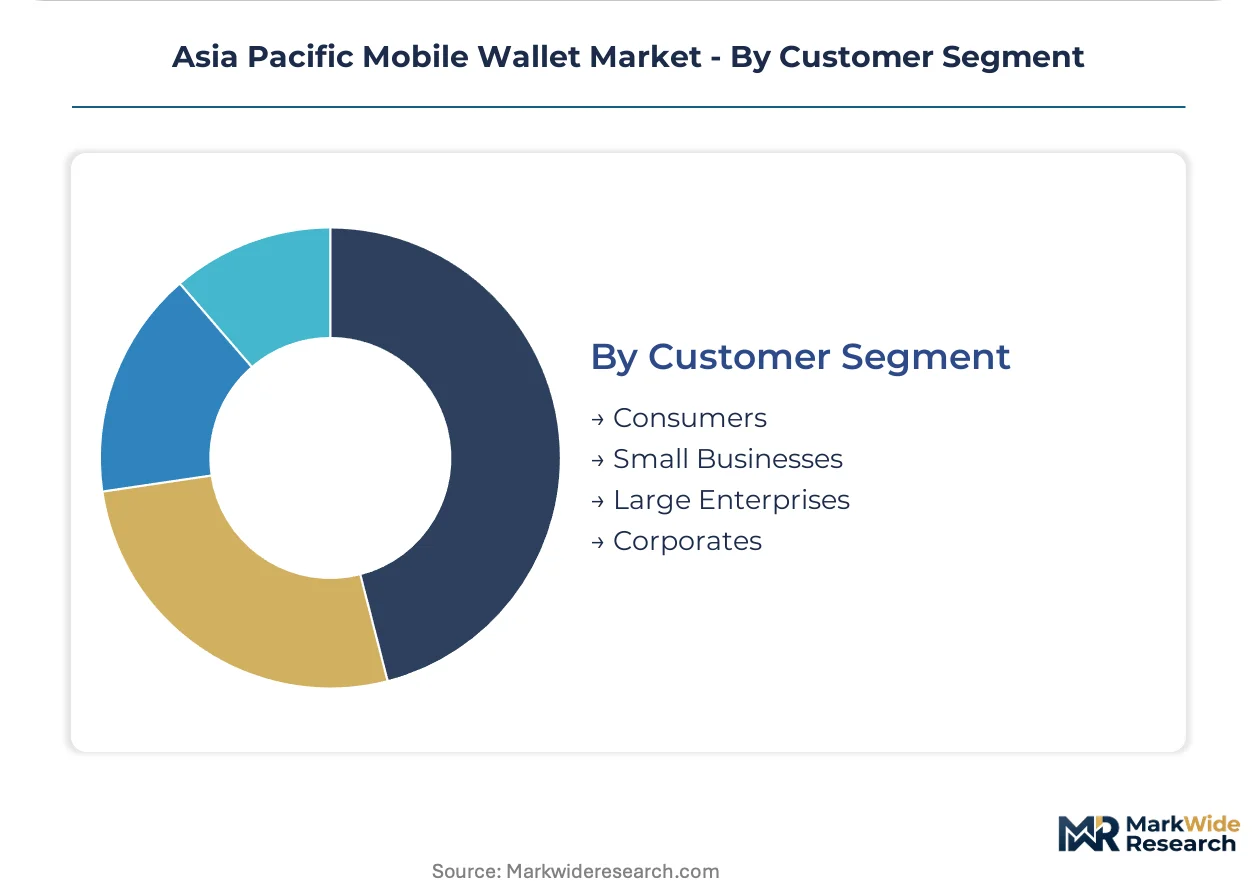
Customer Segment:
Revenue model architecture shifts from consumer transaction fees to enterprise SaaS pricing as wallet providers ascend the customer size spectrum, with compliance requirements intensifying proportionally.
- Consumers:Individual account holders executing personal transactions through mobile applications with standard KYC verification. India's RBI mandates full-KYC compliance for wallet balance limits, imposing identity-verification infrastructure burdens that raise customer acquisition expenses.
- Small Businesses:Micro-merchants and sole proprietors accepting wallet payments through simplified onboarding with revenue-share fee structures. Indonesian retail cooperatives and Malaysian convenience store chains now prefer zero-upfront terminal deployments with percentage-based fee structures.
- Large Enterprises:Mid-market companies requiring payroll disbursement, expense management, and supplier payment integration through wallet APIs. India's central bank digital currency pilot forces private wallet providers to architect float-compatible settlement layers for enterprise treasury operations.
- Corporates:Multinational and conglomerate accounts demanding customized compliance reporting, multi-entity reconciliation, and cross-border settlement orchestration. ASEAN mutual recognition agreements on digital payment licensing would enable wallet portability for regional corporate treasury operations.
Consumers generate highest transaction volume. Small Businesses represent the steepest expansion trajectory as merchant acquisition models pivot to revenue-share arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundry capacity in Taiwan anchors hardware security element production for biometric-enabled wallets across the region.
China
Real-name verification mandates from SAMR and anti-monopoly scrutiny on payment routing reshape platform operations. The central bank digital currency pilot forces private wallets to architect interoperability layers. Wallet density concentrates in the Yangtze River Delta corridor from Shanghai to Hangzhou where super-app ecosystems capture commerce and messaging flows.
India
UPI protocol standardization and full-KYC compliance requirements from RBI accelerate formal financial inclusion. Balance-limit rules impose identity-verification infrastructure burdens that raise customer acquisition costs. Transaction velocity clusters in Mumbai, Bangalore, and Delhi NCR where enterprise treasury operations demand float-compatible settlement layers.
Indonesia
Unbanked urban populations from Jakarta to Surabaya bypass traditional banking entirely for mobile-native services. QR code merchant economics eliminate hardware investment barriers for micro-merchants. Retail cooperatives across Java deploy zero-upfront tablet terminals with revenue-share arrangements tied to transaction volume.
South Korea
Open-banking APIs from the Financial Services Commission mandate interoperability between incumbent and challenger platforms. Contactless terminal density in Seoul Capital Area enables biometric-NFC convergence for reduced transaction friction. Samsung Electronics leverages hardware-software integration across its device installed base to anchor market positioning.
Japan
FSA operational risk frameworks elevate capital requirements for licensed e-money issuers. Contactless infrastructure density in Kanto and Kansai regions supports wearable form factor adoption. Corporate procurement workflows in Tokyo-Osaka corridors favor laptop-based wallet interfaces with hardware security key integration.
Asia Pacific Mobile Wallet Market Vendor Landscape
Super-app convergence dominates the current landscape as platforms bundle payments with non-financial services. The vendor base organizes around three strategic archetypes: hardware-software integrators leveraging device ecosystems, merchant ecosystem dominants locking in small-business flows, and super-app operators capturing attention across messaging and commerce. M&A activity concentrates on merchant acquisition networks, while strategic partnerships reshape payment stack assembly.
Within the hardware-software integrator tier, Samsung Electronics exemplifies device-ecosystem anchoring through its installed base penetration. Ant Group and Tencent occupy positions as merchant ecosystem and super-app archetypes respectively, representing divergent paths to transaction flow capture. These three entities illustrate how geographic origin and corporate structure correlate with strategic positioning across the region's compliance and technology layers.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Ant Group |
| PayPal |
| Kakao Corp |
| Tencent |
| Amazon.com |
| Alibaba Group Holding |
| Others |
Supply Flow & Price Mechanics
Compliance engineering talent scarcity in Bangalore and Singapore drives labor-cost differentials that widen pricing-tier spreads between premium enterprise-grade wallets and mass-market consumer offerings. India's RBI-mandated KYC infrastructure requirements impose fixed compliance costs that compress margins at lower transaction volumes, forcing providers to stratify pricing by verification tier.
Pricing Analysis
Warranty and service bundling separates premium wallet providers from commodity players, with enterprise contracts including dedicated compliance support and API uptime guarantees while consumer tiers offer self-service dispute resolution. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by KYC verification depth, transaction velocity thresholds, and merchant integration complexity. Pricing pressure stems from QR-code merchant acquisition wars in Indonesia and Vietnam where zero-upfront deployment models sacrifice near-term margins for density capture. Micro-merchants in Jakarta's retail cooperatives exhibit highest price sensitivity, while multinational corporate treasuries in Tokyo-Osaka corridors prioritize compliance certification over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Singapore and Hong Kong anchors hardware security module logistics for biometric-enabled wallet deployments across Southeast Asia. Taiwan's semiconductor foundries supply secure element chipsets while South Korean display manufacturers provide OLED panels for in-display fingerprint sensors, creating dual-source dependencies for authentication hardware. Single-source vulnerability from Taiwan-based foundry concentration elevates supply risk for mid-range smartphone biometric integration. Distribution runs through regional distribution centers in Jakarta, Bangkok, and Manila that aggregate merchant terminal shipments for last-mile deployment to Indonesian retail cooperatives and Malaysian convenience store chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element foundry capacity constraints in Taiwan prop pricing power for hardware-integrated wallet providers, with supply bottlenecks expected to persist as Indonesian and Vietnamese handset assemblers accelerate biometric adoption.
For Market Incumbents: Extend merchant ecosystem lock-in through revenue-share arrangements that tie Indonesian retail cooperatives to proprietary settlement rails, while accelerating backward integration into secure element procurement to offset Taiwan foundry allocation risk. Ant Group's merchant density advantage and Samsung Electronics' hardware-software integration demonstrate defensible positioning against super-app convergence threats from Tencent's attention-capture architectures. For New Entrants and Emerging Players: Micro-merchants in Vietnam's digital retail corridors represent the most penetrable buyer archetype, with QR-code merchant economics eliminating hardware barriers that protected incumbent wallet providers. White-space capture demands zero-upfront terminal deployment with percentage-based fee structures, mirroring Indonesian cooperative models, while open-banking API exploitation in South Korea enables interoperability-driven market entry without proprietary rail investment. For Investors and Strategic Acquirers: Re-rating potential sits with merchant acquisition network specialists given ASEAN cross-border harmonization catalysts that would enable wallet portability across Indonesia, Malaysia, Thailand, and Vietnam. Long-term viability favors platforms with float-compatible settlement layers architected for India's central bank digital currency interoperability. The signal to watch is RBI expansion of sovereign digital rupee pilots that would displace private wallet float and erode closed-loop advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Acquisition Network Expansion | Zero-upfront QR terminal deployment captures Indonesian retail cooperative density ahead of revenue-share maturation. |
| Biometric-NFC Convergence Investment | South Korea's contactless terminal density enables next-generation authentication protocols reducing transaction friction. |
| CBDC Interoperability Architecture | Float-compatible settlement layers preserve wallet relevance as India's RBI expands sovereign digital rupee pilots. |
| Open-Banking API Integration | South Korea's Financial Services Commission mandates force incumbent wallets to interoperate with challenger platforms. |
| Cross-Border Licensing Harmonization | ASEAN mutual recognition agreements would unlock wallet portability for regional corporate treasury operations. |
Methodological Framework
Multi-period observation of transaction velocity clusters, merchant terminal deployment rates, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with digital wallet platform executives, central bank regulatory interface specialists, merchant acquisition network operators, and semiconductor supply chain managers. Secondary validation drew from RBI circulars, SAMR enforcement notices, Financial Services Commission API mandates, and ASEAN payment system integration reports. Bottom-up merchant density modeling triangulated against top-down mobile device installed base estimates.
Segment-weighting applied usage-type splits across peer-to-peer, bill payment, and merchant acceptance flows, with technology-layer disaggregation by QR code, NFC, and biometric authentication penetration. Device-type modeling incorporated smartphone, wearable, and tablet form factor adoption curves across the projection horizon. CAGRs derived from regression analysis against unbanked population financial inclusion velocity, contactless terminal deployment rates, and open-banking API transaction flow redistribution.
Revisions become necessary when central bank digital currency pilots displace private wallet float, when semiconductor foundry capacity constraints ease, or when ASEAN mutual recognition agreements alter cross-border licensing economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Proximity Mobile Payment Market
Payments
Latin America Mobile Payment Market
Payments
Japan Mobile Payments Market
Payments
Japan Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
India Real Time Payments Market
Payments
Israel Credit Cards Market
Payments
Mobile Card Reader Market
Payments
Indonesia Prepaid Cards Market
Payments
Voice-Based Payments Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Consumer Mobile Payment Market
Payments
US Virtual Cards Market
Payments
MENA Digital Payments Market
Payments
Gift Card and Incentive Card Market