
 Payment Security Market | 2026-2036
Payment Security Market Size, Share, and Industry Trends Forecast 2026-2036
Payment Security Market Intelligence
PCI DSS 4.0 is decoupling vendor viability from legacy certification alone, raising the cost-of-entry calculus for new entrants. PayPal Holdings Inc. leverages its two-sided network scale to sustain merchant trust across high-velocity transaction environments. INGENICO anchors its position through dedicated hardware security module integration at the terminal edge. Broadcom, Inc. competes by extending silicon-level encryption capabilities into payment processing infrastructure.
Payment security encompasses the cryptographic protocols, tokenization engines, and fraud detection algorithms that protect transaction integrity across digital and physical channels. The field relies on AES-256 encryption standards, hardware security modules with FIPS 140-2 Level 3 certification, and real-time behavioral analytics to intercept unauthorized access before settlement completion. Encryption and tokenization technologies occupy the largest installed base, though biometric authentication is expanding fastest as issuers seek to shift liability away from static credentials. E-commerce and mobile payments applications are capturing disproportionate R&D investment, while POS systems remain a mature margin pool dominated by refresh cycles rather than net-new deployment.
The Federal Reserve's FedNow service guidelines, the EU's PSD2 strong customer authentication mandates, and the PCI Security Standards Council's evolving compliance frameworks collectively shape product roadmaps and market access conditions. These bodies enforce liability allocation rules that directly determine which security architectures qualify for insurance coverage and regulatory forbearance. Stakeholders must monitor how central bank digital currency pilots reshape authentication requirements and whether cloud deployment models can satisfy emerging data sovereignty clauses without fragmenting interoperability.
Market Dynamics
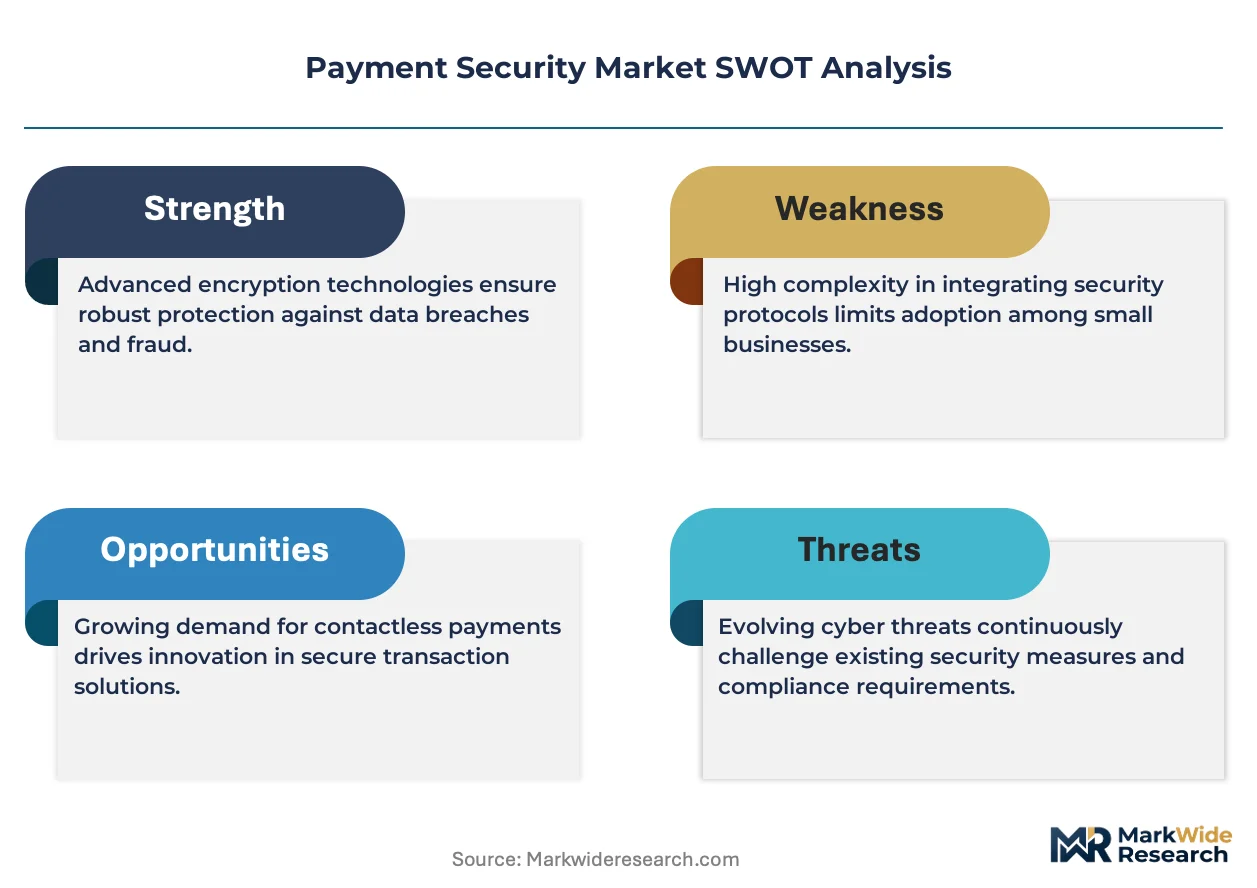
PCI DSS 4.0 compliance deadlines are compressing procurement cycles for banking infrastructure, forcing institutions to choose between costly legacy overhauls and cloud-native security stacks before certification windows close.
Growth Catalysts
- Real-time payment rails:The Federal Reserve's FedNow service mandates transaction-level encryption standards that drive hardware security module procurement across US financial institutions.
- Strong customer authentication:PSD2 requirements in Europe compel issuers to deploy biometric verification layers, expanding addressable demand for behavioral analytics engines.
- Mobile wallet proliferation:Tokenization volumes surge as smartphone-based payment apps displace card-present transactions in India and Brazil.
Market Restraints
- Silicon supply concentration:FIPS 140-2 Level 3 certified hardware security modules depend on concentrated semiconductor fabrication in Taiwan and South Korea.
- Cloud sovereignty friction:EU data localization clauses fragment interoperability for cross-border payment processors seeking unified security architectures.
- Legacy system technical debt:Mainframe-based core banking platforms in Germany and Japan resist API-native fraud detection integration without middleware layers.
Strategic Opportunities
- Central bank digital currency pilots:Authentication requirements for China's e-CNY and India's digital rupee create specification windows for quantum-resistant cryptographic modules.
- Embedded finance convergence:Non-financial platforms in the United States and United Kingdom integrate payment security via Banking-as-a-Service APIs, opening channel partnerships.
- Cross-border remittance corridors:Mexico-Philippines and UAE-India corridors lack standardized tokenization, presenting first-mover positioning for interoperable security protocols.
Industry Challenges
- Post-quantum cryptography skill scarcity:Lattice-based encryption expertise remains concentrated in academic and national laboratory settings, constraining enterprise deployment timelines.
- PCI DSS 4.0 certification bottlenecks:Qualified Security Assessor capacity limits create 12-18 month queues for compliance validation of new product releases.
- Multi-cloud orchestration complexity:Financial institutions struggle to maintain consistent key management policies across AWS, Azure, and Google Cloud environments without vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payment Security Market |
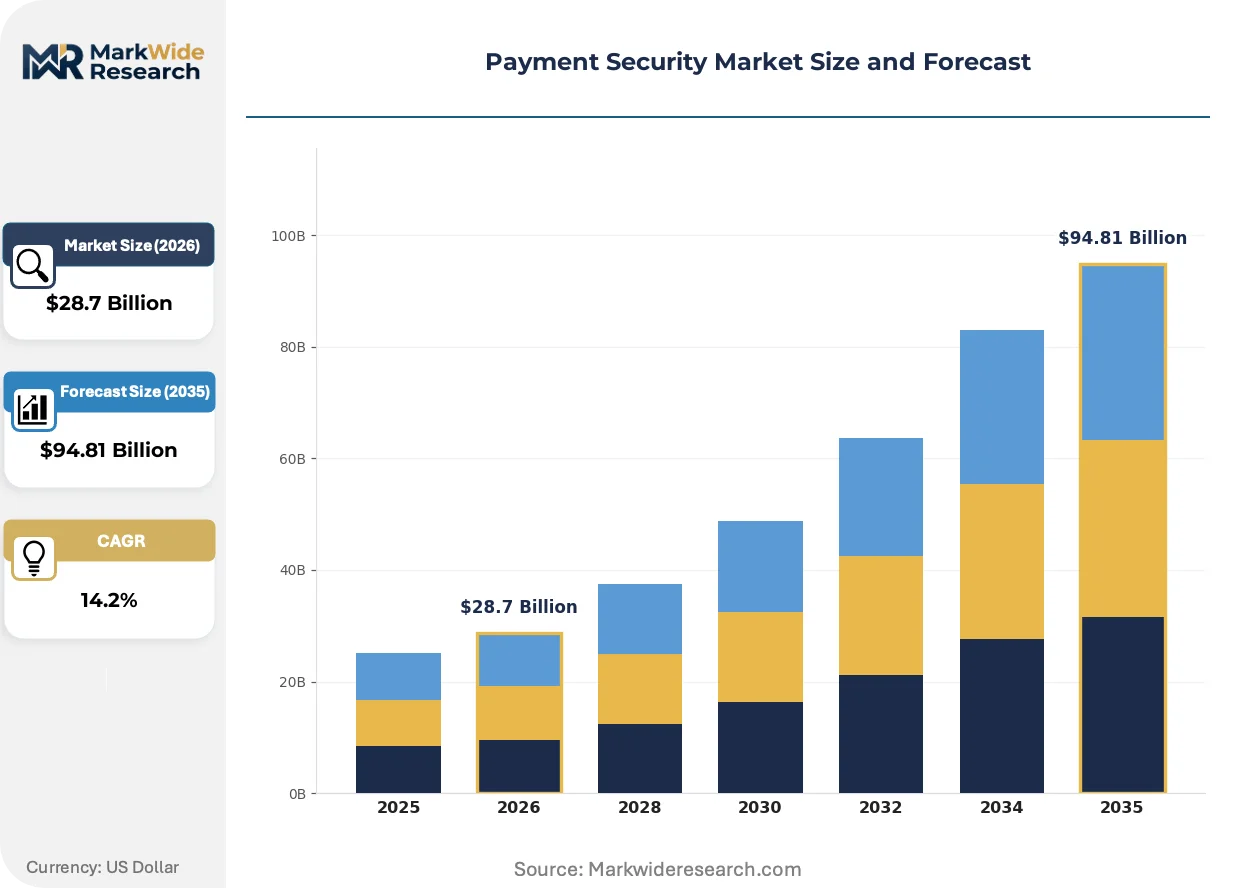
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Encryption, Tokenization, 3D Secure, Biometric Authentication Application: E-commerce, Mobile Payments, POS Systems, Banking End User: Retail, Banking Institutions, Government Agencies, Service Providers Deployment: Cloud-Based, On-Premises, Hybrid, API Integration |
| Companies Covered | Elavon, Inc., PayPal Holdings Inc., Bluefin Payment Systems LLC, Signifyd, Inc., Shift4, Broadcom, Inc., INGENICO, TokenEx, Inc., Cybersource Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payment Security Market Strategic Shifts & Innovations
Payment security architecture is fragmenting into composable components as issuers demand flexibility to swap vendors without core system replacement, accelerating API-first security service adoption.
Tokenization infrastructure is modularizing around cloud-native vaulting services that decouple credential storage from transaction processing. Mid-tier banks in the United Kingdom and Australia are adopting these services fastest, compressing the traditional 18-month procurement cycle for hardware security modules into 90-day SaaS deployments. This modularity enables faster vendor rotation and reduces stranded asset risk during compliance transitions.
GDPR Article 32 enforcement in Europe and state-level privacy statutes in California are mandating encryption-at-rest for all payment data traversing third-party processors. Retail payment acquirers face the steepest compliance costs, with many re-architecting data flows to minimize cross-border storage. The response has concentrated investment in edge-computing tokenization to keep sensitive credentials within jurisdictional boundaries.
Merchant demand for unified fraud scores across online and in-store channels is displacing siloed point solutions. Large retailers in Germany and the United States now require payment service providers to deliver omnichannel risk signals through single API connections. This consolidation preference favors platforms with proprietary transaction data lakes over specialized point-product vendors.
Payment Security Market Segmentation
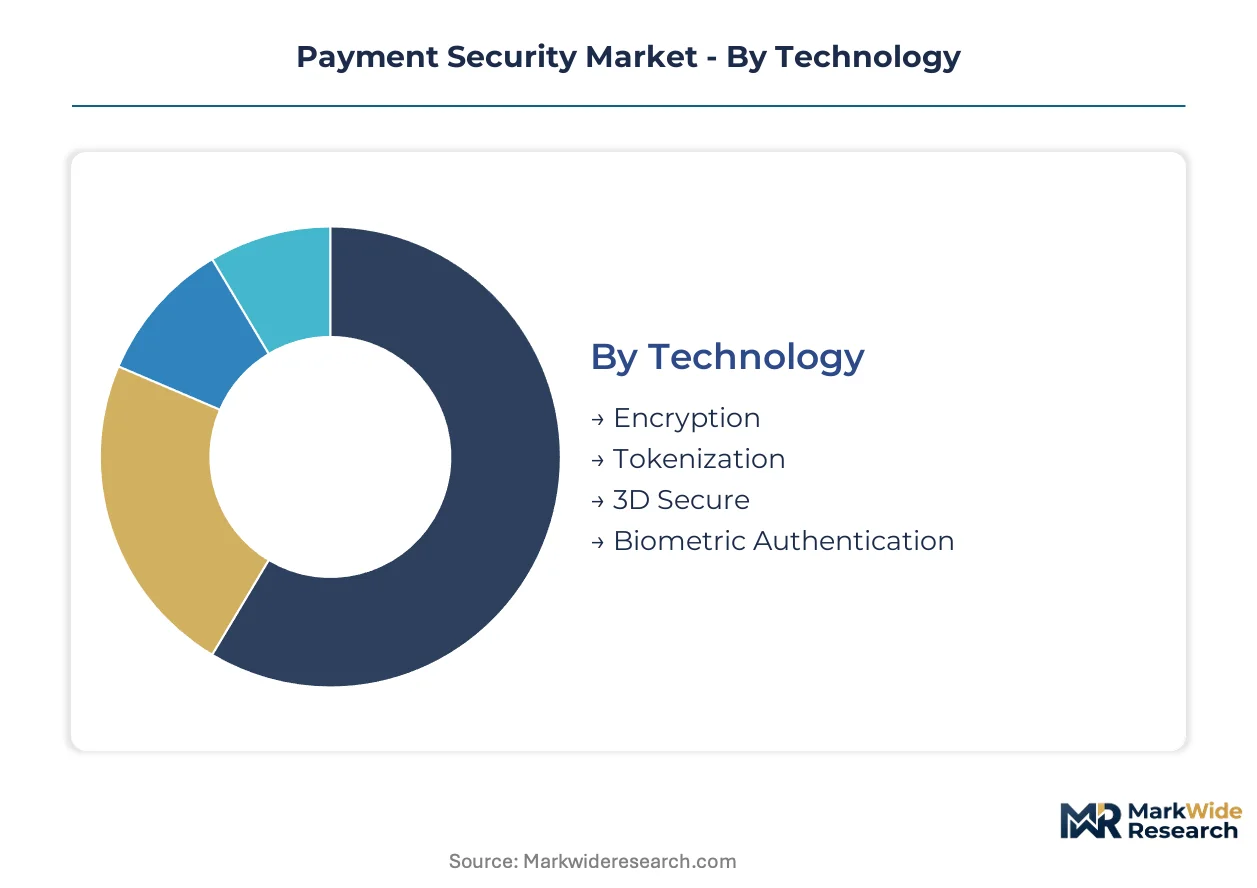
Payment security architectures fragment across four critical dimensions: cryptographic technology, transaction channel, institutional end user, and infrastructure deployment model. Each segmentation axis reveals distinct procurement patterns, compliance burdens, and vendor competitive dynamics that shape investment prioritization.
Technology:
Supply concentration in cryptographic hardware fabrication concentrates procurement leverage among semiconductor-certified vendors in Taiwan and South Korea.
- Encryption:AES-256 standards dominate transaction payload protection across FedNow and TARGET2 instant payment rails. Banking institutions in the United States and Germany absorb the majority of hardware security module procurement for end-to-end payload sealing.
- Tokenization:Cloud-native vaulting services displace on-premise credential storage as mid-tier banks in the United Kingdom compress 18-month procurement cycles into 90-day SaaS deployments. India and Brazil drive volume expansion as mobile wallet proliferation accelerates credential substitution.
- 3D Secure:PSD2 strong customer authentication mandates sustain European issuer investment in risk-based challenge flows.
- Biometric Authentication:Behavioral analytics engines gain traction as liability-shifting alternatives to static credentials.
Encryption absorbs the bulk of installed capacity; Tokenization is expanding most quickly.
Application:
Cost tier differentiation separates high-velocity cloud-native deployments from capital-intensive legacy terminal refreshes.
- E-commerce:Real-time fraud detection algorithms process transaction velocities exceeding 10,000 per second during peak retail windows in the United States. Merchant demand for unified omnichannel risk scores favors platforms with proprietary data lakes over point-product vendors.
- Mobile Payments:Smartphone-based apps displace card-present volume in India and Brazil, forcing tokenization infrastructure scaling. NFC-enabled authentication layers concentrate R&D investment among issuers seeking contactless liability reduction.
- POS Systems:Hardware refresh cycles dominate mature markets rather than net-new deployment.
- Banking:Core system API integration resists middleware-light fraud detection in Germany and Japan.
E-commerce commands the largest addressable spend; Mobile Payments is climbing the fastest.
End User:
Volume concentration among regulated financial institutions creates procurement gravity that shapes vendor product roadmaps.
- Retail:Large merchants in Germany and the United States mandate single-API omnichannel risk signals, consolidating supplier relationships.
- Banking Institutions:PCI DSS 4.0 compliance deadlines compress infrastructure procurement cycles, forcing cloud-native versus legacy overhaul decisions.
- Government Agencies:Central bank digital currency pilots in China and India specify quantum-resistant cryptographic modules.
- Service Providers:Cross-border remittance corridors between Mexico-Philippines and UAE-India lack standardized tokenization protocols.
Banking Institutions anchor procurement volume; Government Agencies are gaining share fastest on CBDC authentication requirements.
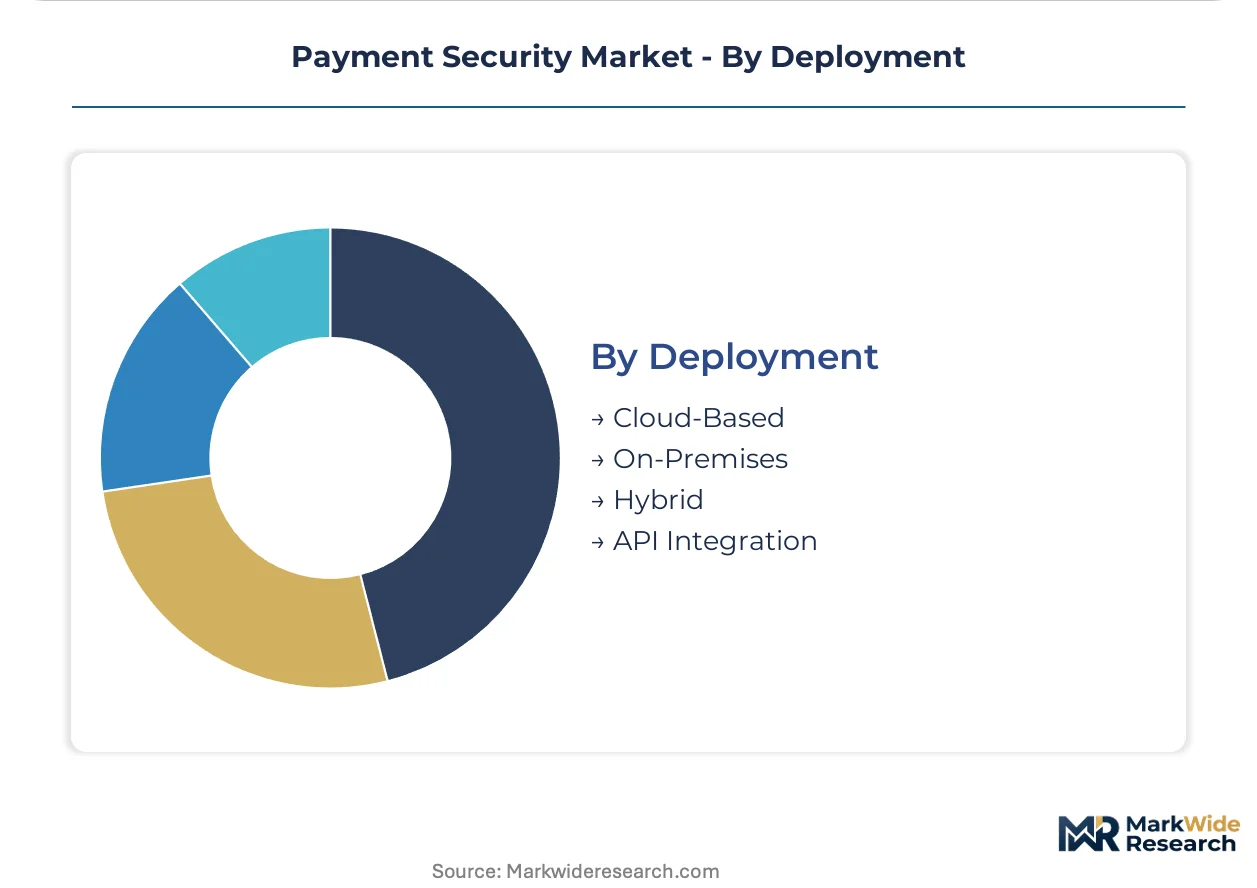
Deployment:
Customer type stratification separates regulated banks with sovereign data requirements from agile fintechs prioritizing speed-to-market.
- Cloud-Based:EU data localization clauses fragment interoperability for processors seeking unified architectures. Edge-computing tokenization investments concentrate in retail payment acquirers minimizing cross-border storage exposure.
- On-Premises:FIPS 140-2 Level 3 certified hardware security modules satisfy FedNow transaction-level encryption mandates for US financial institutions.
- Hybrid:Key management policy consistency across AWS, Azure, and Google Cloud environments challenges multi-cloud orchestration.
- API Integration:Banking-as-a-Service platforms in the United States and United Kingdom embed payment security via channel partnerships.
On-Premises retains the largest installed base; Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate payment security R&D investment through tax-advantaged structures. These zones attract semiconductor fabrication partnerships and cryptographic engineering talent pools. Regulatory divergence across jurisdictions fragments deployment architectures.
United States
FedNow service adoption drives hardware security module procurement across community banks and credit unions. The Federal Reserve mandates transaction-level encryption standards that force infrastructure refreshes. Silicon Valley clusters host cloud-native tokenization startups competing with legacy terminal vendors.
Germany
Mainframe-based core banking platforms in Frankfurt and Munich resist API-native fraud detection without middleware layers. BaFin enforcement of PSD2 strong customer authentication sustains issuer investment in behavioral analytics. The Rhine-Ruhr industrial corridor concentrates POS terminal manufacturing for European export markets.
United Kingdom
Mid-tier banks in London compress 18-month procurement cycles into 90-day SaaS deployments for tokenization vaulting. FCA guidelines on operational resilience push cloud migration timelines forward. The Cambridge-Oxford tech arc supplies lattice-based cryptography research to national security applications.
India
Mobile wallet proliferation in Mumbai and Bangalore accelerates credential substitution volumes. RBI mandates on data localization force edge-computing tokenization investments. The Hyderabad fintech corridor hosts Banking-as-a-Service platforms embedding payment security for non-financial merchants.
China
Central bank digital currency pilots in Shenzhen and Shanghai specify quantum-resistant cryptographic module requirements. PBOC authentication standards for e-CNY reshape hardware procurement specifications. The Yangtze River Delta concentrates semiconductor fabrication for FIPS 140-2 Level 3 certified components.
Payment Security Market Key Industry Players
United States-based network operators anchor one tier; European terminal hardware specialists hold adjacent positions in merchant acquisition infrastructure. Market structure tilts toward consolidated platform scale at the network layer, with fragmentation persisting among point-solution vendors serving mid-market banks. Two strategic archetypes dominate: two-sided network platforms leveraging transaction data moats, and hardware-anchored specialists integrating silicon-level encryption. Competitive moves concentrate on cloud-native stack acquisitions and qualified security assessor capacity expansion for PCI DSS 4.0 certification queues.
Within the network-platform tier, PayPal Holdings Inc. and Shift4 exemplify scale-driven positioning through merchant trust architectures. Among hardware-integrated specialists, INGENICO occupies a position representing terminal-edge security module deployment. Broadcom, Inc. anchors the semiconductor-encryption intersection, supplying chip-level capabilities to payment processing infrastructure vendors. These three company structures illustrate how vendor viability decouples from legacy certification alone under PCI DSS 4.0 compliance pressures.
| Leading Market Players |
|---|
| Elavon, Inc. |
| PayPal Holdings Inc. |
| Bluefin Payment Systems LLC |
| Signifyd, Inc. |
| Shift4 |
| Broadcom, Inc. |
| INGENICO |
| TokenEx, Inc. |
| Cybersource Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FIPS 140-2 Level 3 hardware security modules and cloud-native SaaS tokenization vaults manifests in procurement cost spreads exceeding 10x, with premium-tier HSM deployments demanding Taiwan-sourced silicon and extended validation cycles while commodity SaaS layers compress supplier margins through rapid vendor rotation.
Pricing Analysis
Short-lead-time premiums dominate procurement negotiations, with FedNow-mandated transaction-level encryption forcing US community banks to absorb expedited fulfillment surcharges for FIPS-certified hardware. Pricing stratifies across premium, standard, and economy tiers keyed to certification depth and after-sales service bundling. Cost compression in cloud-native tokenization intensifies because mid-tier banks in the United Kingdom and Australia compress 18-month procurement cycles into 90-day SaaS deployments. Banking institutions demonstrate highest price sensitivity due to PCI DSS 4.0 compliance deadline pressure, while government agencies purchasing quantum-resistant modules for CBDC pilots exhibit lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates in India's data localization rules and China's PBOC authentication standards are reshaping sourcing patterns for cryptographic hardware fabrication. Semiconductor supply concentrates in Taiwan, South Korea, and the Yangtze River Delta region of China. FIPS 140-2 Level 3 certified components draw from concentrated foundry capacity, with raw material dependencies spanning silicon wafers, specialized packaging substrates, and rare-earth magnet materials for hardware module shielding. Single-source vulnerability runs through Taiwan's leading-edge fabrication nodes. Distribution runs through tier-one terminal manufacturers, banking technology integrators, and direct cloud service provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment security functions as a cost-of-compliance market where PCI DSS 4.0 certification bottlenecks erect durable barriers to entry, privileging incumbents with established Qualified Security Assessor relationships and forcing new entrants to absorb 12-18 month validation queues before product release.
For Market Incumbents: Extend platform scale through API-first security service architectures that enable faster vendor rotation without core system replacement, defending against modular tokenization startups compressing procurement cycles. Deepen backward integration into FIPS-certified hardware security module production to secure Taiwan-sourced foundry allocation ahead of FedNow infrastructure refresh demand. For New Entrants and Emerging Players: Capture white-space opportunity in cross-border remittance corridors between Mexico-Philippines and UAE-India where standardized tokenization protocols remain absent. Target mid-tier banks in Australia seeking 90-day SaaS deployment timelines for cloud-native vaulting services. Lead with Banking-as-a-Service API partnerships that embed payment security into non-financial merchant platforms without demanding core system overhaul. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-scale acquisitions by network operators seeking transaction data moats, with long-term viability hinging on quantum-resistant cryptography readiness. Target acquisition archetypes include cloud-native tokenization specialists with proven 90-day deployment track records and established channel partnerships with mid-tier banking institutions. Watch central bank digital currency pilot specifications as the critical signal for authentication requirement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Qualified Security Assessor Capacity Expansion | PCI DSS 4.0 certification bottlenecks create 12-18 month validation queues for new product releases. |
| Cloud-Native Tokenization Vault Acquisition | Mid-tier banks in London compress 18-month procurement cycles into 90-day SaaS deployments. |
| Quantum-Resistant Cryptographic Module Development | PBOC authentication standards for China's e-CNY reshape hardware procurement specifications. |
| Cross-Border Remittance Protocol Standardization | Mexico-Philippines and UAE-India corridors lack interoperable security tokenization frameworks. |
| Banking-as-a-Service API Partnership | Non-financial platforms in the United States embed payment security via channel partnerships. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with fraud detection engineers, PCI compliance officers, banking technology procurement leads, and hardware security module manufacturing specialists with secondary validation against PCI Security Standards Council documentation, Federal Reserve FedNow service guidelines, and EU PSD2 regulatory filings. Bottom-up demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Data-stream reconciliation aligned transaction volume projections with infrastructure procurement timelines, modeling across technology type, application channel, end-user institution, and deployment architecture dimensions. CAGRs were derived through segment-level growth trajectory analysis incorporating FedNow adoption curves, mobile wallet penetration rates in India and Brazil, and CBDC pilot authentication requirement evolution. Industry-specific inputs included qualified security assessor queue duration estimates and FIPS 140-2 Level 3 hardware lead time fluctuations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to post-quantum cryptography standardization timelines and central bank digital currency specification shifts. Forecasts reflect documented assumptions regarding PCI DSS 4.0 compliance deadline adherence, Taiwan semiconductor fabrication capacity allocation, and EU data localization clause enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mobile Payment Market
Payments
Convergent Billing Market
Payments
Canada Payment Gateway Market
Payments
Spain POS Terminals Market
Payments
Mobile Wallet Market
Payments
Global Payment Gateways Market
Payments
Poland Payments Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Biometric Payment Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
United States POS Terminals Market
Payments
Recurring Payments Market
Payments
Cash Management Software Market
Payments
Payment Orchestration Platform Market
Payments
United Kingdom Real Time Payments Market
Payments
Japan Mobile Payments Market