
 Global Utility Billing Software Market | 2026-2036
Global Utility Billing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Utility Billing Software Market Foresight
The direct sales channel for enterprise utility billing suites is narrowing as SaaS marketplaces and systems integrator consortia capture mid-market procurement flows. Oracle Corporation leverages its database infrastructure dominance to bundle billing modules with enterprise resource planning contracts across North American investor-owned utilities. Hansen Technologies Ltd. anchors its position through deep specialization in water and multi-utility billing across Australia and the United Kingdom. EnergyCAP Inc. competes primarily in energy management adjacent spaces, differentiating through sustainability reporting integrations rather than pure billing functionality.
Utility billing software encompasses meter-to-cash platforms that ingest interval data from AMI, MDMS, and legacy manual read systems to generate accurate invoices, manage payment collections, and support regulatory reporting. Core functional parameters include rate engine flexibility for time-of-use and dynamic pricing structures, scalability to millions of accounts, and interoperability with CIS and workforce management systems. Cloud-based deployment leads solution type adoption among municipal corporations seeking to avoid capital-intensive on-premises infrastructure, while meter data management segments grow fastest as distributed energy resource penetration complicates interval validation. Billing and invoicing modules retain the deepest margin pools due to their regulatory compliance criticality and high switching costs for established utilities.
The US Federal Energy Regulatory Commission shapes wholesale settlement standards that cascade into retail billing accuracy requirements, while the EU F-Gas Regulation and GDPR constrain data residency architectures for European deployments. India's Central Electricity Authority mandates smart metering roadmaps that create compliance-driven procurement timelines for software vendors. Stakeholders must monitor how cybersecurity standards from ISO and IEC evolve alongside grid edge digitization, as these frameworks increasingly determine market access eligibility and insurance underwriting terms for platform providers.
Market Dynamics
AMI smart meter rollouts are compressing billing cycle times and forcing utilities to retire legacy CIS platforms that cannot process 15-minute interval data streams. Cloud-native architectures are displacing on-premises deployments as municipal corporations seek operational expenditure models over capital-intensive infrastructure builds.
Growth Catalysts
- EU Green Deal mandates:Germany and the United Kingdom face binding decarbonization deadlines that require dynamic pricing engines capable of time-of-use tariffs and demand-response billing.
- Smart metering infrastructure:India's Central Electricity Authority mandates nationwide AMI deployment timelines that create compliance-driven procurement windows for meter-to-cash platforms.
- FERC wholesale settlement standards:The US Federal Energy Regulatory Commission's accuracy requirements cascade into retail billing system upgrades across investor-owned utilities.
Market Restraints
- Data residency architectures:GDPR and EU F-Gas Regulation constrain cloud deployment options for European utilities, forcing redundant infrastructure investments.
- Cybersecurity certification costs:ISO 27001 and IEC 62351 compliance timelines extend sales cycles by 8-14 months for vendors seeking utility contracts.
- Legacy system entrenchment:High switching costs for established CIS platforms lock municipal corporations into maintenance-heavy on-premises contracts.
Strategic Opportunities
- Distributed energy resource billing:Solar-plus-storage and EV charging integrations create white space for interval validation engines that reconcile bidirectional meter flows.
- US Inflation Reduction Act incentives:Grid modernization tax credits accelerate procurement timelines for cloud-native billing platforms at municipal utilities.
- SaaS marketplace channels:Systems integrator consortia and hyperscaler marketplaces capture mid-market procurement flows that direct sales teams cannot economically serve.
Industry Challenges
- Interval data engineering talent:Scarcity of professionals skilled in MDMS integration and time-series database management constrains vendor implementation capacity.
- Multi-system interoperability:Workforce management and customer information system integrations require custom API development that balloons project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Utility Billing Software Market |
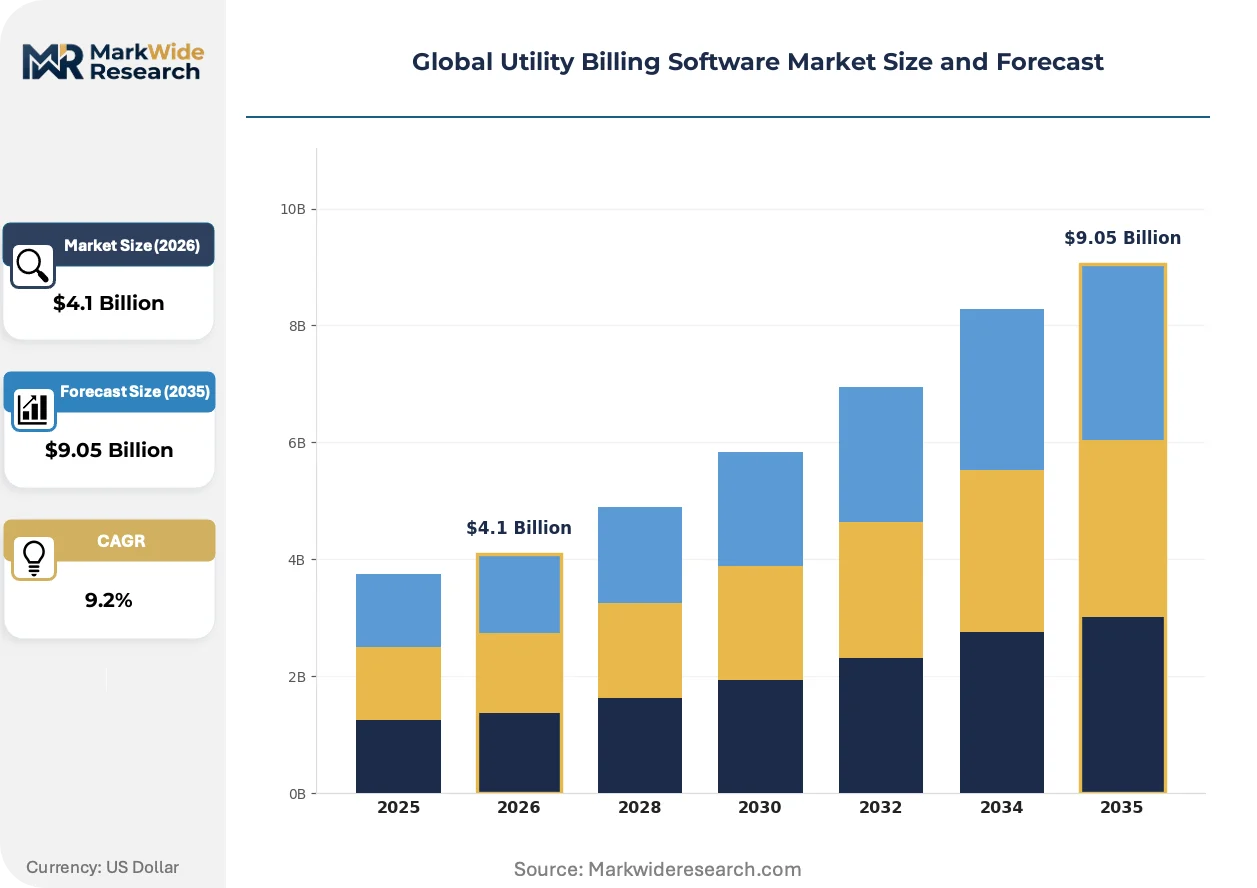
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.05 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Managed Services Solution Type: Customer Information System, Meter Data Management, Billing & Invoicing, Payment Processing, Analytics & Reporting Utility Type: Electricity, Water, Gas, District Heating, Waste Management End User: Municipal Corporations, Private Utility Operators, Cooperatives, Government Agencies |
| Companies Covered | Enghouse Networks Limited, Hansen Technologies Ltd., Oracle Corporation, Harris Computer Systems, EnergyCAP Inc., Banyon Data Systems Inc., Cogsdale Corporation, SkyBill, Continental Utility Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Utility Billing Software Market Shifts & Advancements
Cloud-native billing platforms are virtualizing core meter-to-cash functions, compressing the traditional vendor landscape while opening entry points for specialized SaaS providers. Three developments are restructuring competitive positioning.
Containerized microservices architectures are virtualizing rate engine deployment, allowing municipal utilities to spin up time-of-use and dynamic pricing models without wholesale platform replacements. Mid-market water and electric cooperatives in Australia and the United Kingdom are adopting these modular approaches fastest. The structural consequence is collapsing implementation timelines from 18 months to 90 days for standard tariff configurations.
The EU AI Act's risk classification framework is forcing billing vendors to document algorithmic transparency for automated credit scoring and collections prioritization. European deployments now require explainability audits that increase compliance overhead. German and Dutch utilities are responding by demanding pre-certified AI modules from platform providers rather than building custom solutions.
Subscription-based pricing models are displacing perpetual license structures as municipal finance departments prioritize operational expenditure classification. SaaS contracts with usage-based tiers are capturing procurement flows previously reserved for enterprise suite vendors. This shift is most visible in United States municipal corporations navigating bond rating pressures and constrained capital budgets.
Global Utility Billing Software Market Segmentation
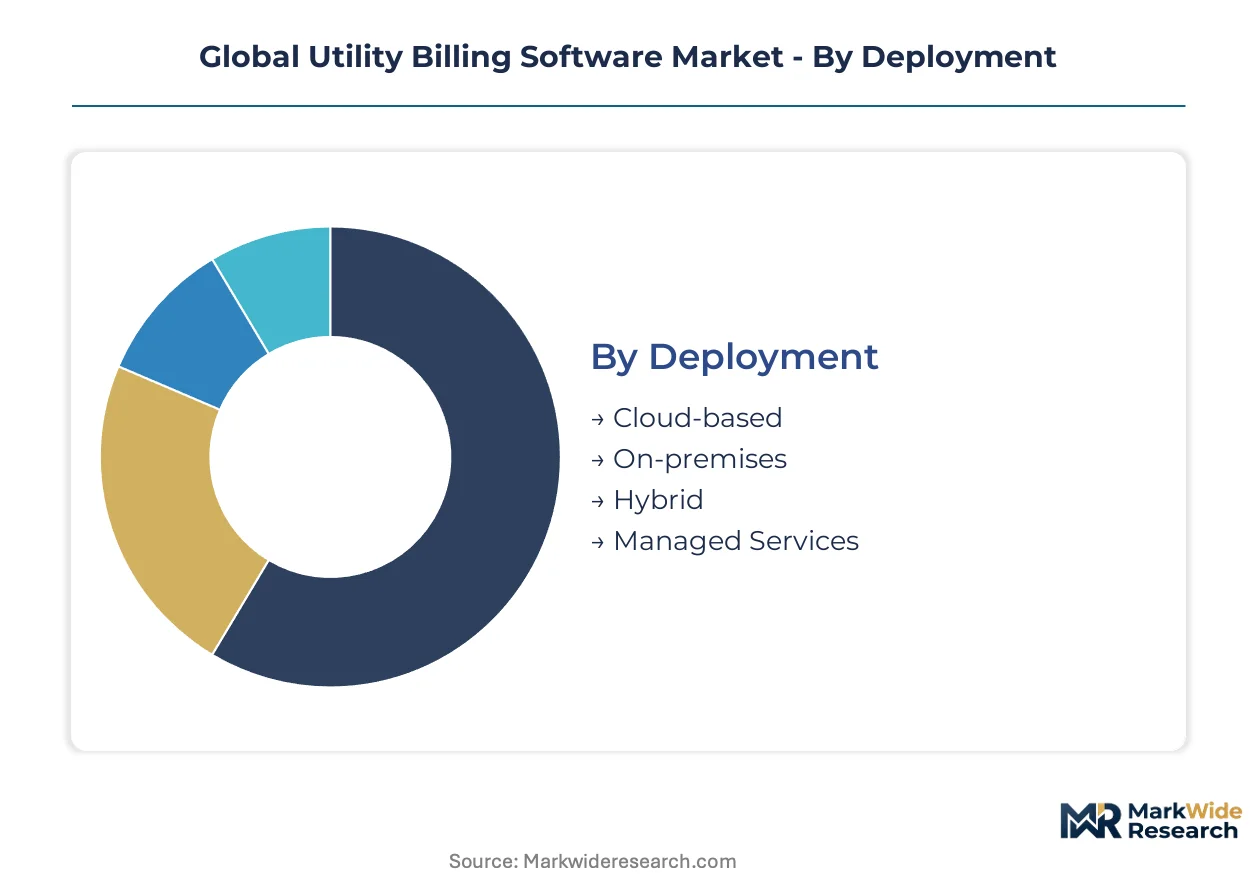
Utility billing software segmentation reveals divergent procurement cycles across deployment models and utility types. Municipal finance departments prioritize operational expenditure classification, while investor-owned utilities favor capital-intensive infrastructure with longer amortization horizons.
Deployment:
Cloud-based platforms compress implementation cycles from 18 months to 90 days, while on-premises contracts lock municipalities into decade-long maintenance relationships with legacy vendors.
- Cloud-based:Containerized microservices virtualize rate engine deployment, allowing utilities to spin up time-of-use models without wholesale replacements. Demand concentrates among United States municipal corporations navigating bond rating pressures and constrained capital budgets. Germany and the Netherlands lead European adoption as GDPR compliance frameworks mature.
- On-premises:Perpetual license structures dominate legacy CIS platforms entrenched at large investor-owned utilities. High switching costs and regulatory compliance criticality sustain these installations despite higher total cost of ownership.
- Hybrid:Split architectures preserve sensitive customer data on local servers while offloading analytics workloads to cloud environments. Australian water utilities deploy these configurations to balance data sovereignty with scalability.
- Managed Services:Third-party operations contracts transfer billing platform management to specialized vendors. United Kingdom multi-utility operators favor this model to access interval data engineering talent without direct hiring.
On-premises installations dominate installed base. Cloud-based deployment is where expansion concentrates.
Solution Type:
Margin pools vary sharply across functional modules, with regulatory compliance criticality protecting billing engines while analytics modules face pricing pressure from adjacent software categories.
- Customer Information System:Core account management platforms integrating meter-to-cash workflows with customer service interfaces. United States investor-owned utilities drive replacement demand as AMI rollouts expose legacy CIS limitations in processing 15-minute interval data.
- Meter Data Management:Time-series databases validating and storing interval consumption records from AMI, MDMS, and legacy manual read systems. Distributed energy resource penetration complicates validation logic for bidirectional meter flows. This segment is gaining share fastest as solar-plus-storage and EV charging integrations multiply data complexity.
- Billing & Invoicing:Rate engines generating accurate invoices across time-of-use, dynamic pricing, and demand-response tariff structures. Deep margin pools reflect regulatory compliance criticality and high switching costs for established utilities.
- Payment Processing:Collections platforms managing payment channels, credit scoring, and collections prioritization. EU AI Act risk classifications now mandate algorithmic transparency audits for automated decision systems.
- Analytics & Reporting:Sustainability reporting and consumption insight tools competing with adjacent energy management software. Differentiation through regulatory reporting integrations rather than pure billing functionality.
Billing & Invoicing modules command premium pricing. Meter Data Management shows the steepest expansion trajectory.
Utility Type:
Decarbonization deadlines and smart metering mandates create asynchronous procurement waves across utility sectors, with electricity leading investment intensity.
- Electricity:AMI smart meter rollouts compress billing cycle times and force platform retirements. FERC wholesale settlement standards cascade into retail accuracy requirements across United States utilities. EU Green Deal mandates in Germany and the United Kingdom require dynamic pricing engines for time-of-use tariffs and demand-response billing.
- Water:Non-revenue water reduction drives meter replacement programs. Australia and the United Kingdom show fastest adoption of multi-utility billing platforms spanning water and electricity.
- Gas:Lower meter replacement frequency sustains legacy platform longevity. European F-Gas Regulation constrains data residency architectures for cloud deployments.
- District Heating:Seasonal consumption patterns require specialized thermal billing calculations. Nordic municipal corporations pioneer interval-based heat metering.
- Waste Management:Weight-based and frequency-based pricing models demand flexible rate engines. Emerging procurement category with limited vendor specialization.
Electricity utilities anchor procurement volume. Water utilities are where multi-utility platform expansion concentrates.
End User:
Ownership structure determines procurement channel preferences, with direct sales teams serving large operators while SaaS marketplaces capture cooperative and municipal flows.
- Municipal Corporations:Finance departments prioritize operational expenditure classification for bond rating preservation. United States municipal corporations accelerate cloud-native procurement through Inflation Reduction Act grid modernization incentives.
- Private Utility Operators:Investor-owned utilities bundle billing modules with enterprise resource planning contracts. Oracle Corporation leverages database infrastructure dominance across North American accounts.
- Cooperatives:Member-owned structures favor modular SaaS approaches with shorter commitment horizons. Mid-market electric cooperatives in Australia adopt containerized microservices fastest.
- Government Agencies:Central procurement authorities mandate compliance-driven timelines. India's Central Electricity Authority smart metering roadmaps create vendor qualification windows.
Private Utility Operators dominate enterprise contract value. Municipal Corporations represent the fastest-growing procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable infrastructure underwrites North America's data exchange dominance, while the NordLink interconnector anchors Northern Europe's grid integration. These physical assets shape where utility billing software procurement concentrates.
United States
FERC wholesale settlement standards cascade into retail billing accuracy mandates across investor-owned utilities. The Inflation Reduction Act's grid modernization tax credits accelerate municipal procurement timelines for cloud-native platforms. Texas and California utilities lead AMI deployment, compressing legacy CIS replacement cycles.
Germany
Binding EU Green Deal decarbonization deadlines require dynamic pricing engines for time-of-use tariffs and demand-response billing. The national regulator enforces strict data residency requirements under GDPR and F-Gas Regulation constraints. Munich and Hamburg municipal utilities pioneer containerized microservices adoption.
United Kingdom
Ofgem price cap mechanisms and net-zero targets drive multi-utility billing platform consolidation. The country's smart metering rollout mandates compliance-driven procurement windows for meter-to-cash vendors. London and Birmingham anchor the largest cooperative utility procurement clusters.
India
The Central Electricity Authority mandates nationwide AMI deployment timelines creating vendor qualification windows. State-level discom reform programs accelerate billing system modernization. Maharashtra and Gujarat utilities lead procurement volume for cloud-based CIS replacements.
Australia
Water scarcity and non-revenue water reduction programs drive meter replacement and billing platform upgrades. The national energy market's distributed energy resource penetration complicates interval validation requirements. Sydney and Melbourne multi-utility operators favor hybrid deployment architectures.
Global Utility Billing Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in rate engine and MDMS validation niches. The vendor landscape consolidates around database infrastructure bundling and deep utility vertical specialization. Three archetypes dominate: enterprise suite bundlers, water-electric multi-utility specialists, and SaaS-native challengers. Competitive moves center on hyperscaler marketplace partnerships and containerized microservices licensing.
Within the enterprise suite tier, Oracle Corporation anchors North American positioning through database infrastructure bundling. Hansen Technologies Ltd. exemplifies the multi-utility specialist archetype with concentrated presence across Australia and the United Kingdom. EnergyCAP Inc. occupies a position among sustainability-adjacent competitors, differentiating through reporting integrations rather than pure billing functionality.
| Leading Market Players |
|---|
| Enghouse Networks Limited |
| Hansen Technologies Ltd. |
| Oracle Corporation |
| Harris Computer Systems |
| EnergyCAP Inc. |
| Banyon Data Systems Inc. |
| Cogsdale Corporation |
| SkyBill |
| Continental Utility Solutions Inc. |
| Others |
Supply & Pricing Matrix
Transatlantic fiber optic cable capacity costs shape how North American utilities absorb cloud-native platform premiums while European competitors face GDPR-mandated data residency surcharges. This logistics corridor's pricing volatility concentrates margin pressure on mid-market SaaS vendors unable to distribute infrastructure across multiple sovereign zones.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and municipal cooperative levels. Three-tier pricing separates Oracle's bundled ERP-database suites from Hansen's specialized multi-utility modules and SaaS-native challengers' usage-based subscriptions. Cost compression in the municipal tier is intensifying because Inflation Reduction Act grid modernization credits accelerate procurement timelines, compressing vendor sales cycles. Private investor-owned utilities demonstrate lowest price sensitivity due to capital budget amortization flexibility, while United States municipal corporations navigating bond rating pressures exhibit highest sensitivity to operational expenditure classification.
Supply Chain Analysis
Export-control regimes limiting cryptographic module flows constrain cloud infrastructure deployment options for European utilities under GDPR Article 44 transfer restrictions. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from United Kingdom and Australian systems integrator networks. Containerized microservices architectures rest on hyperscaler compute dependencies from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability permeates the rate-engine tier where specialized algorithm libraries face concentrated vendor control. Distribution runs through systems integrator consortia and hyperscaler marketplaces capturing mid-market procurement flows direct sales teams cannot economically serve.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as distributed energy resource penetration complicates interval validation requirements, creating specialized niches beyond incumbent CIS platform coverage. This demand-side shift rewards vendors with MDMS-billing integration depth over generalist enterprise suite providers.
For Market Incumbents: Build switching-cost moats through deep CIS-billing interoperability investments that lock municipal utilities into decade-long maintenance relationships. Prioritize ISO 27001 and IEC 62351 certification acceleration to extend sales cycle advantages over emerging SaaS challengers. Defend against containerized microservices disruption by acquiring specialized rate-engine vendors before hyperscaler marketplace channels democratize access. For New Entrants and Emerging Players: Establish a beachhead in solar-plus-storage and EV charging interval validation engines where bidirectional meter flow complexity outpaces legacy vendor adaptation capacity. Target Australian water-electric multi-utility cooperatives adopting modular SaaS approaches fastest. Pursue hyperscaler marketplace listings as primary go-to-market channel to bypass incumbent direct sales team economics. For Investors and Strategic Acquirers: Component specialists with pre-certified AI modules for EU AI Act compliance represent prime acquisition targets as German and Dutch utilities demand explainability audits. Long-term viability centers on vendors with demonstrated MDMS-time-series database integration capabilities across the next decade. Monitor FERC wholesale settlement standard revisions as inflection indicator triggering retail billing system replacement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Marketplace Partnership | Captures municipal procurement flows through AWS Marketplace and Azure Marketplace channels. |
| Containerized Microservices Licensing | Compresses implementation timelines from 18 months to 90 days for standard tariffs. |
| EU AI Act Pre-Certification | Enables German and Dutch utility sales by satisfying algorithmic transparency audit requirements. |
| MDMS Integration Acquisition | Addresses interval data engineering talent scarcity constraining vendor implementation capacity. |
| Subscription Pricing Transition | Aligns with United States municipal finance departments prioritizing operational expenditure classification. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility CIOs, billing platform product managers, municipal finance directors, and systems integrator partners; and secondary validation through FERC filings, EU regulatory databases, SEC 10-K utility disclosures, and hyperscaler capex reports. Bottom-up triangulation across deployment model, utility type, and geographic adoption patterns anchored volume estimates, while top-down cross-checks against AMI smart meter rollout timelines ensured segmentation integrity.
Forecast inputs considered cloud-native platform adoption velocity, EU Green Deal mandate compliance deadlines, and India CEA smart metering roadmap procurement windows across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type functional module, utility sector, and end-user ownership structure. CAGRs were derived from regression analysis of historical procurement cycle compression and regulatory compliance-driven replacement waves, with interval data complexity indices and distributed energy resource penetration rates serving as industry-specific demand drivers.
Stress conditions across hyperscaler pricing volatility, cybersecurity certification timeline extensions, and legacy CIS entrenchment persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding municipal bond market conditions and regulatory enforcement consistency. Material shifts in FERC wholesale settlement standards or EU AI Act risk classification enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Canada Real Time Payments Market
Payments
Contactless Payment Ring Market
Payments
Luxembourg POS Terminals Market
Payments
Tanzania Mobile Money Market
Payments
Global Accounts Payable Software Market
Payments
Biometric Payment Cards Market
Payments
Global Digital Wallets Market
Payments
Japan Prepaid Cards Market
Payments
Payment Instruments Market
Payments
Europe Payment Analytics Software Market
Payments
Sweden POS Terminals Market
Payments
Germany Gift Card and Incentive Card Market
Payments
US Virtual Cards Market
Payments
Belgium Payments Market
Payments
Payment Card Market
Payments
Master Recharge API Market