
 France Virtual Cards Market | 2026-2036
France Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
France Virtual Cards Market Insights
Digital banking distribution is rewriting how French enterprises procure payment credentials. Marqeta leverages its open-API card-issuing platform to anchor programmable virtual card programs for SaaS spend management platforms. Spendesk competes through vertical specialization in expense automation for mid-market French firms. Stripe extends its acquiring and issuing stack to occupy the developer-centric virtual card segment for marketplace payouts.
France virtual cards are tokenized, single-use or multi-use digital payment instruments generated through software APIs with 16-digit Primary Account Numbers, expiration dates, and dynamic CVV codes, designed to execute secure, auditable transactions without physical plastic issuance. Corporate cards dominate issuance volume as French enterprises prioritize centralized spend controls and real-time transaction visibility across procurement workflows. Mobile wallet integration represents the fastest-growing technology dimension, with NFC-enabled virtual credentials displacing physical corporate cards for contactless transit and hospitality spending in Paris and Lyon metropolitan corridors.
Banque de France, the French Prudential Supervision and Resolution Authority (ACPR), and PSD2 Strong Customer Authentication standards govern virtual card issuance, capital requirements, and transaction authentication protocols across French payment rails. ACPR licensing thresholds shape market access for neobank issuers seeking to deploy virtual card products to French enterprise clients. Stakeholders must monitor forthcoming European Digital Operational Resilience Act implementation timelines and their impact on cloud-hosted card management infrastructure compliance obligations.
Market Dynamics
PSD2 Strong Customer Authentication mandates are forcing French issuers to rebuild authentication stacks around tokenized virtual credentials, accelerating API-first card issuance platforms that embed spend controls directly into enterprise procurement workflows.
Growth Catalysts
- Corporate Treasury Centralization:French finance departments consolidate supplier payments onto programmable virtual rails to capture real-time transaction visibility and automated reconciliation across decentralized procurement teams.
- ACPR Licensing Framework:Neobank entrants leverage streamlined electronic money institution pathways to deploy virtual card products without full banking licenses, compressing time-to-market for B2B payment innovators.
- API Orchestration Layers:Open banking interfaces enable spend management platforms to issue tokenized credentials natively within accounting software, eliminating plastic fulfillment delays.
Market Restraints
- Cloud Infrastructure Concentration:French virtual card programs depend on hyperscale cloud providers for card management systems, creating single-point-of-failure exposure under forthcoming Digital Operational Resilience Act scrutiny.
- Interchange Cost Compression:Domestic scheme fee structures limit margin flexibility for issuers competing on programmable card features against established commercial card networks.
- Legacy ERP Integration Friction:Mid-market enterprises running on-premise financial systems face technical debt barriers when connecting API-native virtual card workflows to aged procurement modules.
Strategic Opportunities
- Île-de-France Enterprise Density:Paris-headquartered multinationals present concentrated demand for multi-currency virtual card programs supporting cross-border B2B settlements.
- Transit-Hospitality Convergence:NFC-enabled virtual credentials embedded in mobile wallets unlock closed-loop payment acceptance across Île-de-France public transport networks and Lyon metropolitan hospitality corridors.
- CSRD Reporting Alignment:Virtual card transaction data streams feed directly into sustainability reporting dashboards, positioning issuers to capture ESG-conscious corporate procurement budgets.
Industry Challenges
- SCA Implementation Complexity:PSD2 authentication exemptions for low-value recurring payments require precise risk-engineering to avoid transaction abandonment at checkout.
- Token Vault Interoperability:Proprietary tokenization schemes from network processors create lock-in effects that complicate issuer migrations between card management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Virtual Cards Market |
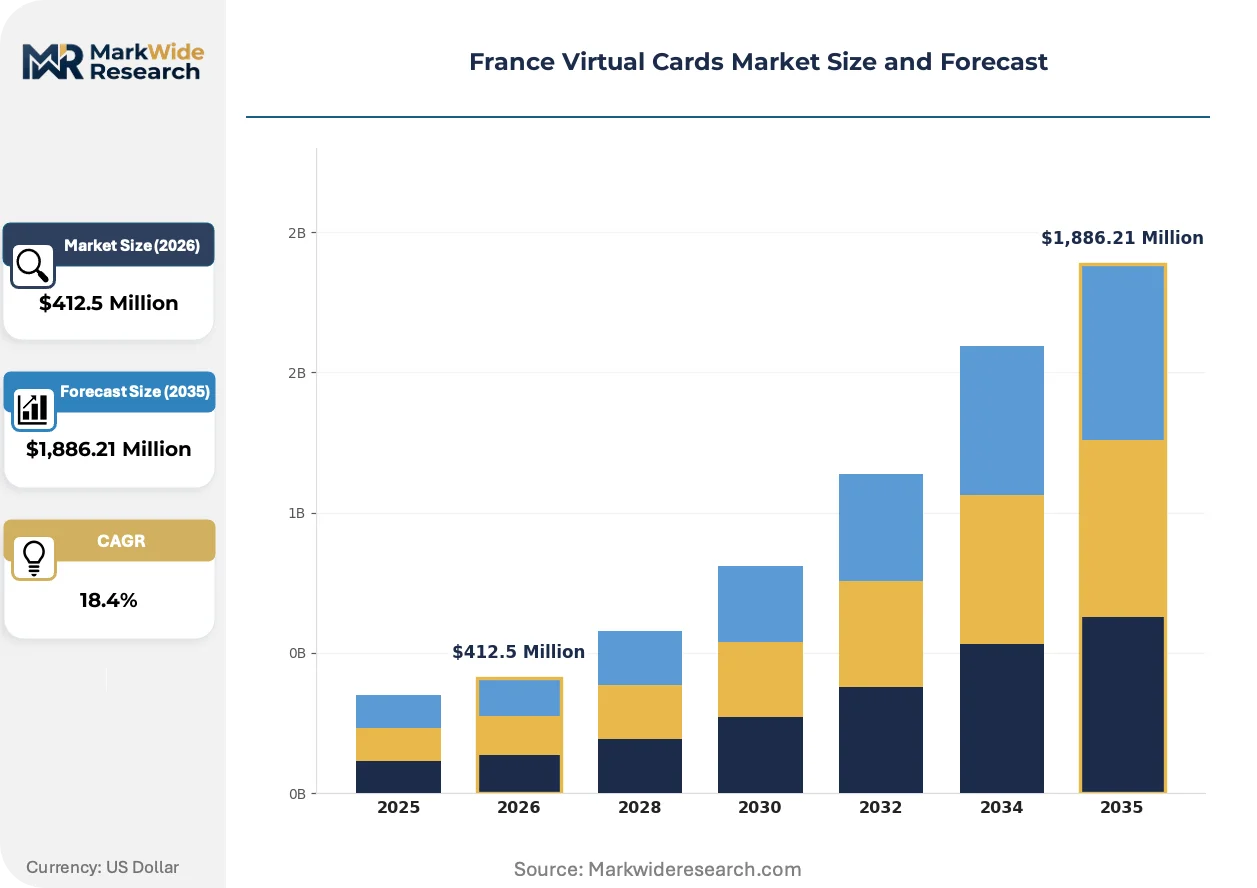
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,886.21 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepaid Cards, Corporate Cards, Gift Cards, Reloadable Cards Service Type: Online Payments, Subscription Services, E-Commerce Transactions, Travel Expenses Customer Type: Individual Users, Small Businesses, Enterprises, Government Agencies Technology: Contactless Payments, Mobile Wallet Integration, Cross-Border Transactions, Security Features |
| Companies Covered | Mastercard, Visa, American Express, Marqeta, Adyen, Revolut, Stripe, Spendesk, Airwallex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Virtual Cards Market Trends and Innovations
Virtual card infrastructure is migrating from static credential issuance toward dynamic, context-aware payment instruments that embed merchant controls and spend limits at the point of generation.
Tokenization technology is migrating from simple PAN substitution toward multi-use credential schemes with merchant-locked parameters. Large French enterprises operating SaaS procurement stacks adopt these programmable instruments to enforce pre-approved supplier spend ceilings. The shift is migrating from traditional corporate card programs toward embedded finance workflows where virtual credentials generate automatically within ERP requisition modules.
PSD2 Strong Customer Authentication rules compel French issuers to implement step-up authentication for e-commerce transactions above threshold limits. The regulation forces re-architecture of mobile banking apps to support biometric verification and device binding. Neobank challengers respond fastest, while incumbent banks face legacy authentication stack replacement costs.
Mid-market French firms abandon manual expense reimbursement cycles in favor of real-time spend management platforms that issue virtual cards per employee. Finance teams gain immediate visibility into committed spend rather than waiting for monthly statement reconciliation. The behavioral shift concentrates among technology and professional services sectors with distributed workforces.
France Virtual Cards Market Segmentation
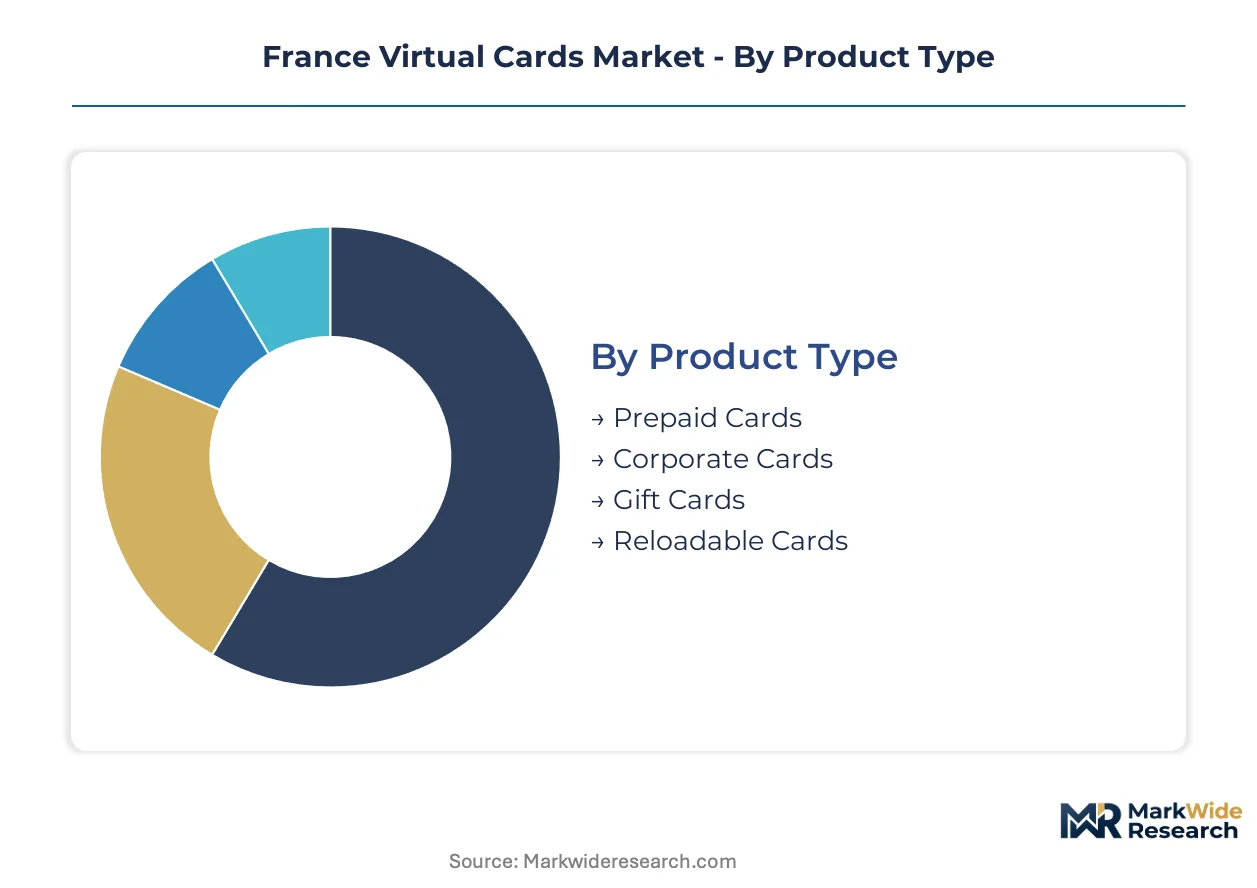
Segmentation in the France virtual cards market reveals divergent adoption velocities across product architectures and customer profiles. Cycle times vary dramatically: corporate procurement credentials refresh monthly while gift card inventories turn within seasonal windows. Understanding these temporal patterns enables issuers to calibrate capital deployment and API infrastructure capacity.
Product Type:
Cycle times separate prepaid instruments with immediate issuance from corporate programs requiring multi-week onboarding and compliance verification.
- Corporate Cards:Multi-use virtual credentials integrate directly with enterprise ERP systems through tokenized APIs. French finance departments in Paris and Lyon metropolitan corridors prioritize these instruments for real-time spend visibility across decentralized procurement teams. ACPR licensing requirements extend deployment timelines but lock in longer customer lifecycles.
- Prepaid Cards:Single-load instruments with immediate activation and no KYC friction for low-value thresholds. Demand concentrates among Île-de-France gig economy platforms seeking instant worker payout rails without recurring compliance overhead.
- Gift Cards:Closed-loop virtual instruments with merchant-locked redemption parameters and seasonal demand spikes.
- Reloadable Cards:Multi-top-up credentials requiring initial identity verification but enabling recurring fund flows.
Corporate cards anchor the volume base while prepaid cards gain share at the steepest rate.
Service Type:
Application economics separate high-frequency, low-margin transaction streams from episodic, high-value payment corridors with richer interchange yields.
- E-Commerce Transactions:Virtual credentials generated at checkout with dynamic CVV rotation and merchant-specific spend ceilings. French online retailers embed these instruments to reduce chargeback exposure on high-risk cross-border orders.
- Travel Expenses:Multi-currency virtual cards with automatic FX hedging and per-trip budget enforcement. Paris-based multinational headquarters drive adoption for employee business travel across Schengen corridors.
- Online Payments:General-purpose virtual rails for one-off digital purchases without subscription commitment.
- Subscription Services:Recurring-use credentials with merchant locking and automatic cancellation upon contract expiry.
E-commerce transactions dominate transaction velocity while travel expenses command the highest per-transaction margins.
Customer Type:
Account complexity tiers separate individual onboarding with mobile-app KYC from enterprise procurement requiring multi-stakeholder approval workflows and ERP integration.
- Enterprises:Centralized virtual card programs with department-level spend controls and automated reconciliation into accounting systems. French CAC 40 companies anchor demand through programmable card APIs that enforce pre-approved supplier budgets.
- Small Businesses:Mid-market firms with simpler procurement needs but growing appetite for real-time spend visibility over traditional commercial card programs.
- Individual Users:Consumer-facing virtual credentials for privacy-conscious online shoppers seeking merchant-specific card generation.
- Government Agencies:Public sector procurement with strict audit trail requirements and compliance with public finance regulations.
Enterprises represent the deepest revenue pool while small businesses expand most quickly as neobank challengers target this underserved tier.
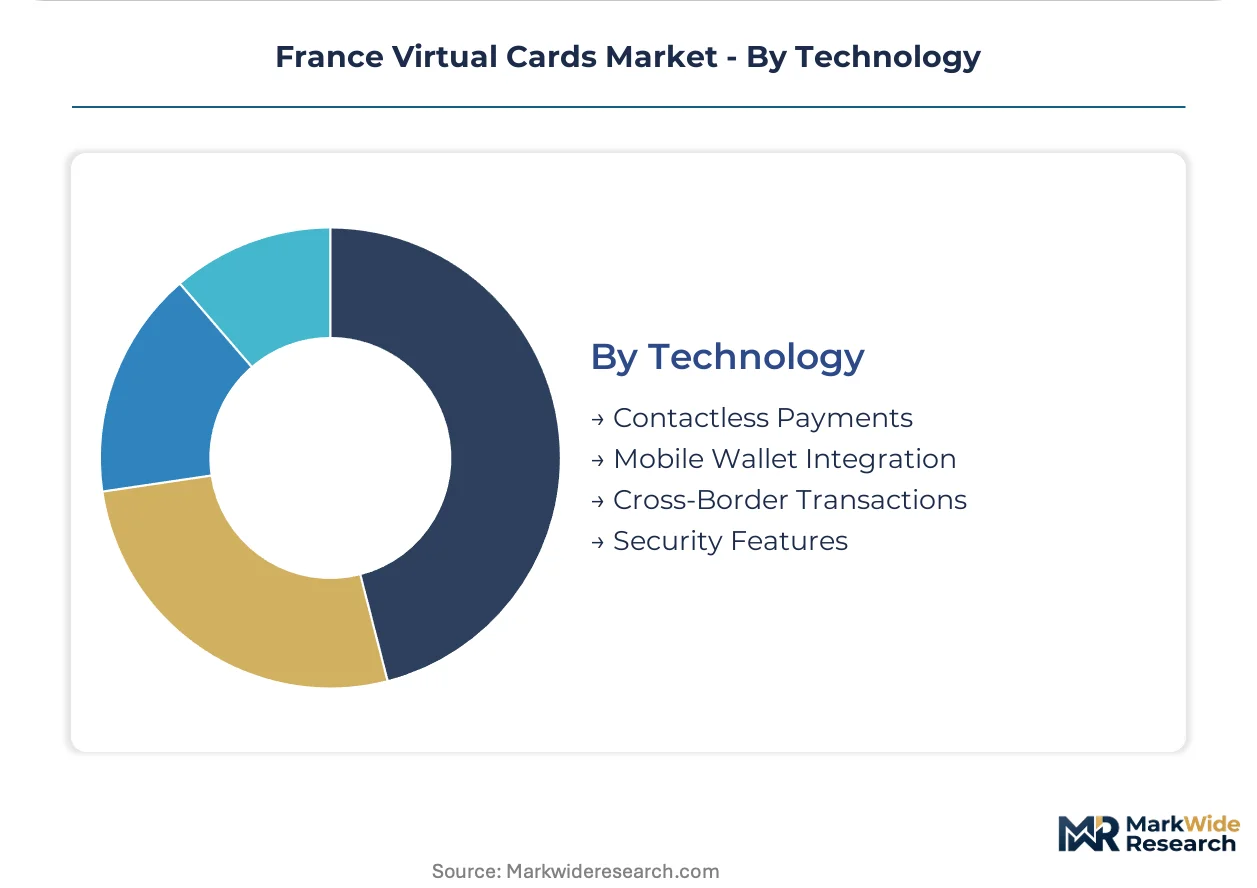
Technology:
Infrastructure maturity separates established contactless rails from emerging security protocols still navigating PSD2 certification pathways.
- Mobile Wallet Integration:NFC-enabled virtual credentials embedded in Apple Pay and Google Pay for transit and hospitality acceptance across Paris Métro and Lyon public transport networks. This layer is displacing physical corporate cards fastest among distributed workforces.
- Security Features:Token vault architectures with dynamic PAN rotation, biometric step-up authentication, and real-time fraud scoring. French issuers invest here to meet ACPR operational resilience expectations.
- Contactless Payments:Tap-to-pay virtual credentials leveraging existing POS terminal infrastructure.
- Cross-Border Transactions:Multi-currency virtual instruments with automatic FX conversion and regulatory compliance across EU payment corridors.
Mobile wallet integration leads technology investment while security features differentiate issuer positioning most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Île-de-France while peripheral French regions absorb compressed margins from standardized virtual card products. The national market fragments across metropolitan demand density and regulatory interpretation variance.
Île-de-France
Paris-headquartered multinationals drive premium virtual card adoption for multi-currency B2B settlements and programmable spend controls. ACPR licensing requirements anchor issuer operations in this region, creating regulatory proximity advantages. La Défense and Station F clusters host fintech challengers deploying API-first card issuance platforms to enterprise treasury departments.
Auvergne-Rhône-Alpes
Lyon's pharmaceutical and industrial manufacturing base generates demand for supplier payment automation through virtual card rails. PSD2 Strong Customer Authentication compliance costs weigh heavier on mid-market firms here than in Paris. The Lyon metropolitan transit authority's NFC payment infrastructure accelerates mobile wallet credential adoption across hospitality and transport corridors.
Provence-Alpes-Côte d'Azur
Tourism-dependent SMEs in Nice and Marseille adopt single-use virtual credentials for online booking platforms and cross-border supplier payments. The regional banking network's conservative technology posture delays API-native card issuance deployment. Aix-Marseille-Provence tech incubators host emerging spend management startups targeting Mediterranean trade corridors.
Hauts-de-France
Logistics and e-commerce fulfillment centers around Lille generate transaction volume for B2B procurement virtual cards. The region's industrial heritage creates ERP integration friction when connecting legacy procurement systems to modern card APIs. Cross-border Belgian and Dutch payment corridor access positions Lille-based enterprises for multi-currency virtual instrument adoption.
Nouvelle-Aquitaine
Bordeaux's wine trade and aerospace supply chains utilize virtual cards for international supplier settlements with embedded FX controls. Smaller enterprise density here favors neobank challengers offering streamlined onboarding over incumbent commercial card programs. The region's slower digital banking penetration creates whitespace for mobile-first virtual credential issuance.
France Virtual Cards Market Competitive Landscape
Global payment networks and API-native fintech platforms split the market along infrastructure-control versus software-velocity lines. Network incumbents leverage scheme dominance and regulatory relationships to anchor enterprise issuance programs. Fintech challengers compete through developer experience and vertical workflow embedding. Dominant competitive moves include strategic partnerships between card networks and spend management platforms, plus geographic expansion of API-first issuing infrastructure.
Within the network-incumbent tier, Mastercard and Visa anchor scheme-level virtual card programs with token vault infrastructure and merchant acceptance density. Marqeta exemplifies the API-native archetype, occupying the programmable card issuance layer that enables SaaS platforms to embed virtual credentials natively. Spendesk represents vertical specialization, sitting within the mid-market expense automation segment with France-specific workflow integration. These three patterns—scheme infrastructure, API orchestration, and vertical software—capture the competitive structure.
| Leading Market Players |
|---|
| Mastercard |
| Visa |
| American Express |
| Marqeta |
| Adyen |
| Revolut |
| Stripe |
| Spendesk |
| Airwallex |
| Others |
Pricing and Supply Chain Analysis
Paris-based fintech clusters concentrate API-native card issuance capacity, translating infrastructure proximity into premium pricing power for programmable virtual credential programs serving Île-de-France enterprise headquarters.
Pricing Analysis
The customization-premium spread separates standard virtual card APIs from configured-to-order enterprise deployments with embedded ERP connectors and dynamic spend controls. SaaS-tiered subscription models dominate, with price differentiation driven by API call volume tiers and PSD2 compliance certification levels. Pricing pressure stems from neobank challengers compressing onboarding costs through streamlined ACPR electronic money licensing pathways. Mid-market French firms exhibit highest price sensitivity, while CAC 40 treasury departments prioritize feature depth over unit economics.
Supply Chain Analysis
Export-control regimes on cryptographic tokenization modules limit flows of certified hardware security modules from the United States and select EU jurisdictions into French card management infrastructure. Supply concentration centers on Ireland, the Netherlands, and Germany for cloud-hosted card management systems, with dependencies on specialized token vault software, biometric authentication processors, and NFC-enabled secure elements. Single-source vulnerability runs through hyperscale cloud provider concentration under Digital Operational Resilience Act scrutiny. Distribution runs through direct API integration into enterprise spend management platforms and neobank mobile applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
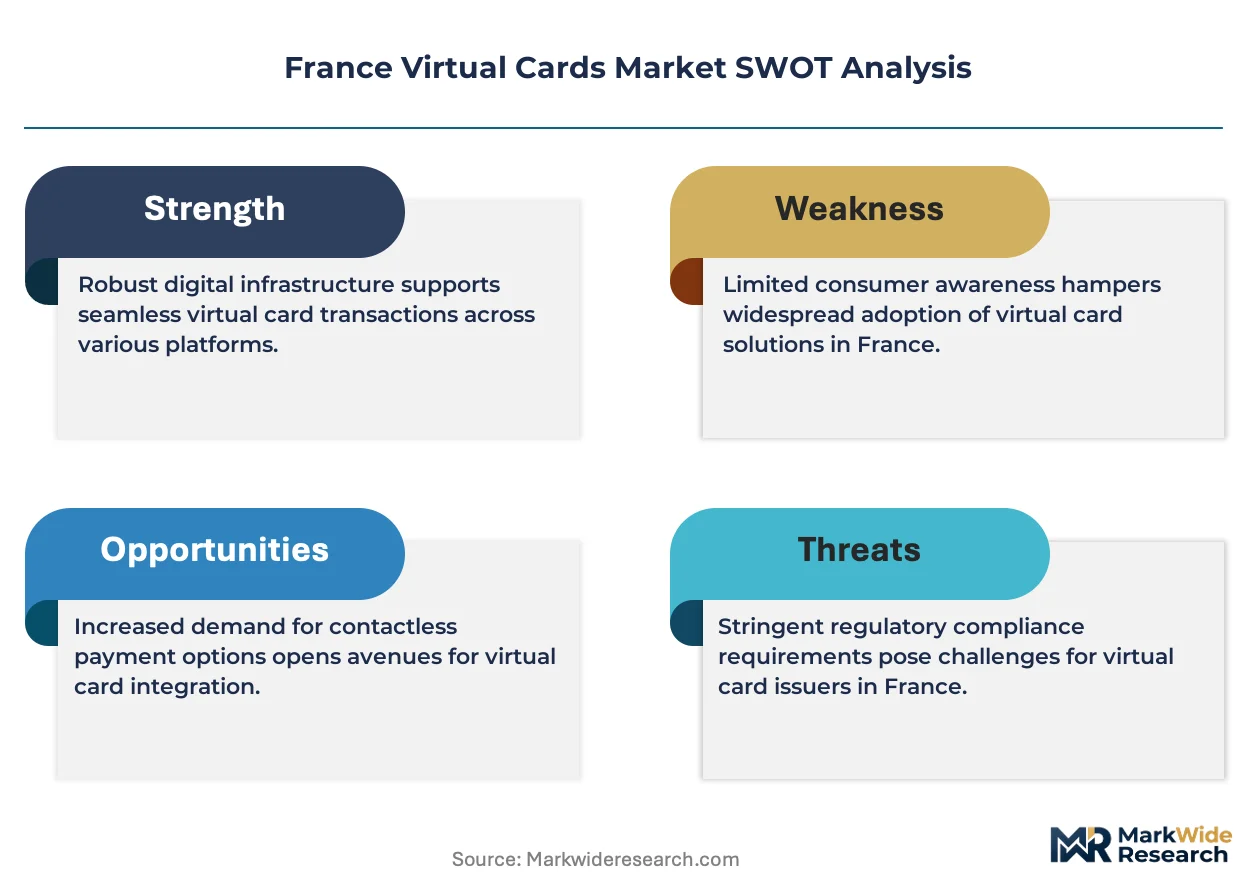
Platform-economics inflection demands interoperability investment as open banking APIs and token vault standardization reshape competitive moats around embedded finance ecosystems.
For Market Incumbents: Entrench scheme-level token vault infrastructure through exclusive partnerships with Paris-headquartered spend management platforms, while accelerating PSD2 Strong Customer Authentication stack modernization to defend against API-native challengers exploiting legacy authentication replacement costs. Prioritize certification investment in ACPR operational resilience frameworks to create regulatory friction against neobank entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in Lyon and Bordeaux mid-market corridors where legacy ERP integration friction delays incumbent virtual card deployment, targeting pharmaceutical and aerospace supply chain verticals with pre-built SAP connector modules. Lead with developer-centric documentation and rapid sandbox provisioning to differentiate against established commercial card programs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API orchestration layer specialists with established token vault integrations and ACPR licensing pathways already secured. Long-term viability hinges on embedded finance penetration into accounting software workflows. Watch for Digital Operational Resilience Act implementation timelines as inflection indicator forcing cloud infrastructure diversification investments.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedded virtual card issuance within SAP and Oracle procurement modules captures enterprise workflow lock-in. |
| ACPR Compliance Certification | Electronic money institution licensing compresses neobank time-to-market against incumbent banking charter requirements. |
| Token Vault Interoperability Investment | Multi-processor credential portability reduces issuer migration friction and platform switching costs. |
| Mobile Wallet Transit Partnership | NFC credential embedding in Île-de-France transport networks displaces physical corporate card usage. |
| CSRD Data Stream Alignment | Virtual card transaction feeds into sustainability dashboards capture ESG-conscious procurement budgets. |
Research Methodology
Cross-validation between executive interviews with French fintech product leads and secondary analysis of ACPR regulatory filings anchors the qualitative findings. Primary fieldwork engaged virtual card platform engineers, enterprise treasury managers at CAC 40 headquarters, neobank compliance officers, and spend management software CTOs. Secondary sources included Banque de France payment statistics, PSD2 implementation guidance documents, European Banking Authority technical standards, and cloud infrastructure provider security certifications. Bottom-up transaction volume modeling triangulated against top-down enterprise software penetration estimates.
Calibration against historical virtual card issuance trajectories and ERP integration adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product architecture, service type, customer tier, and technology integration depth. CAGRs derived from regression analysis of API call volume growth and mobile wallet credential activation rates, with specific inputs from NFC transit payment deployment timelines and ACPR licensing application trends.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate trajectories and enterprise software capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions around PSD2 enforcement consistency and cloud provider operational resilience compliance timelines. Material shifts in Digital Operational Resilience Act implementation scope or ACPR electronic money licensing thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Norway POS Terminals Market
Payments
Asia-Pacific Payments Market
Payments
Norway Mobile Payments Market
Payments
Latin America Mobile Payment Market
Payments
Contactless Payment Terminals Market
Payments
India RTP Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Payment Card Market
Payments
Global Gift Card Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Digital Money Transfer Market
Payments
Proximity Mobile Payment Market
Payments
Global Point of Sale Terminals Market
Payments
France Payments Market
Payments
Dual Interface Payment Card Market
Payments
Payment Security Software Market