
 Italy POS Terminals Market | 2026-2036
Italy POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Italy POS Terminals Market Foresight
Aluminum alloy housings are displacing legacy ABS plastic enclosures in next-generation terminal chassis, and this material substitution is realigning product economics toward lighter, more durable hardware with improved thermal management. Verifone leverages its European manufacturing footprint to sustain cost-competitive production of metal-clad devices. Zucchetti anchors its domestic position through deep channel relationships with Italian banking cooperatives. PAX Global Technology Ltd. competes on modular architecture that simplifies field upgrades for merchants.
A point-of-sale terminal constitutes an integrated electronic payment system comprising a secure processor, encrypted card reader, touchscreen or keypad interface, and network connectivity module, engineered to authenticate and settle card-present and card-not-present transactions through certified payment gateways. These devices serve the commercial purpose of enabling merchants to accept multiple payment instruments while maintaining PCI-DSS compliance and transaction audit trails. Mobile terminals now lead volume growth as Italian food delivery vendors and pop-up retailers prioritize untethered checkout flexibility, while fixed terminals retain dominance in supermarket and hypermarket lanes where throughput speed determines lane configuration. Contactless technology commands the fastest expansion trajectory as NFC-enabled smartphone wallets and wearable payment devices displace chip-and-pin insertion across hospitality counters.
Banca d'Italia supervises payment system stability and enforces terminal certification requirements that shape hardware procurement timelines for acquirers and merchants. The EU's GDPR framework constrains how transaction data flows through cloud-based deployment architectures, compelling vendors to engineer localized data residency features. Italy's Agenzia per l'Italia Digitale promotes interoperable e-invoicing standards that intersect with POS system design. Stakeholders must weigh whether to prioritize on-premise security architectures or accelerate cloud migration paths as regulatory scrutiny of payment data intensifies.
Market Dynamics
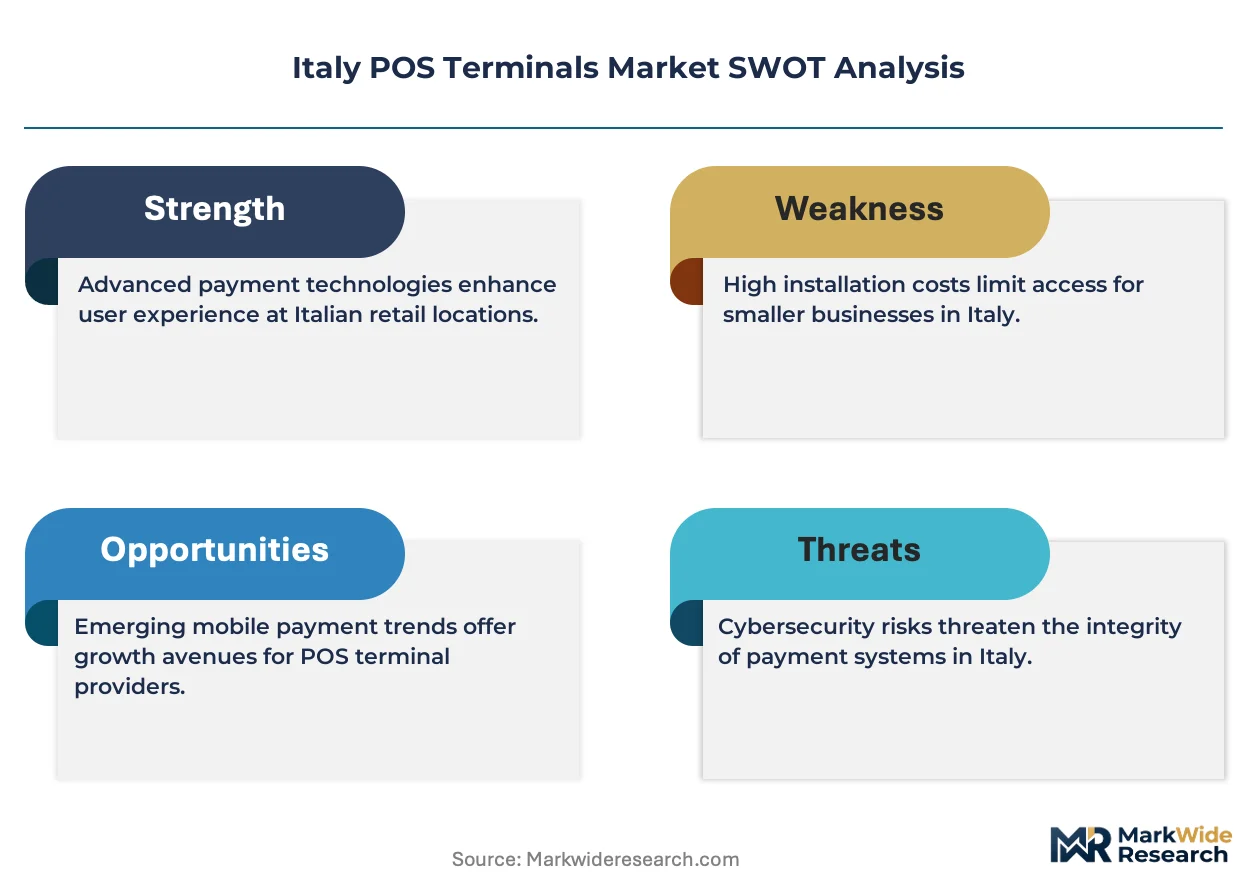
Contactless payment infrastructure expansion across Italian hospitality chains is compressing terminal refresh cycles and forcing acquirers to accelerate hardware certification timelines under PSD2 authentication mandates.
Growth Catalysts
- PSD2 Strong Customer Authentication:The EU directive mandates multi-factor verification for electronic transactions above threshold limits, compelling merchants to upgrade legacy terminals to certified hardware that supports biometric or tokenized authentication flows.
- Aluminum alloy chassis substitution:Material displacement from ABS plastic enclosures improves thermal management and durability in high-transit mobile deployments, extending field service intervals for food delivery vendors operating untethered terminals.
- Lombardy retail density:Milan's concentrated banking corridors and luxury retail clusters generate concentrated procurement volumes that sustain specialized distribution networks and accelerate technology diffusion to secondary cities.
Market Restraints
- Semiconductor supply concentration:Secure processor sourcing depends on concentrated Asian foundry capacity, exposing terminal manufacturers to allocation volatility that extends procurement lead times for encrypted card reader modules.
- GDPR data residency friction:The EU framework constrains cloud-based transaction architectures, forcing vendors to engineer localized data storage features that add hardware cost and complexity for multi-national acquirers.
- Chip-and-pin displacement lag:Older demographic segments in southern Italian provinces retain insertion-payment habits, slowing NFC adoption velocity in regions where merchant education and consumer trust-building require extended investment.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern regions exhibit lower terminal density per merchant establishment, creating whitespace for acquirers willing to build localized service infrastructure and merchant onboarding capabilities.
- Agenzia per l'Italia Digitale e-invoicing convergence:Interoperable fiscal reporting standards create integration opportunities where POS terminals automatically generate compliant transaction records, reducing merchant administrative burden and stickiness.
- SoftPOS smartphone conversion:Near-field communication enablement of standard Android devices without dedicated hardware threatens traditional terminal volumes but opens software licensing and security certification revenue streams for platform vendors.
Industry Challenges
- Banca d'Italia certification backlog:Terminal hardware approval queues extend deployment timelines for acquirers, compressing revenue recognition windows and forcing inventory pre-positioning before regulatory clearance.
- PCI-DSS compliance fragmentation:Evolving payment card industry security standards require continuous firmware validation across deployed device fleets, straining merchant IT resources and vendor support infrastructure.
- Legacy system integration complexity:Established Italian banking cooperatives operate decades-old core banking architectures that resist API-native terminal connectivity, requiring expensive middleware development for seamless transaction routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy POS Terminals Market |
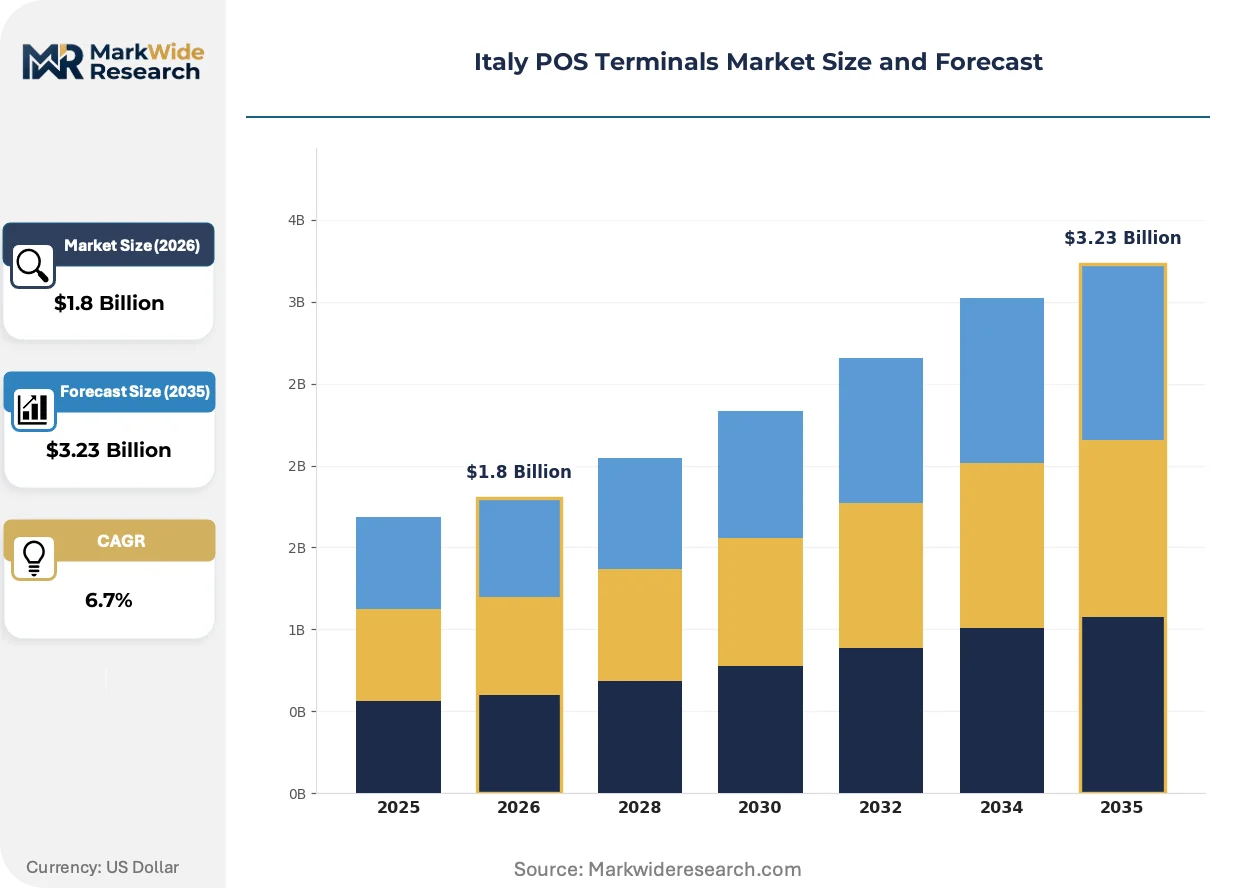
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Self-Service Kiosks, Multilane Terminals Technology: Contactless, Chip & Pin, Magnetic Stripe, QR Code End User: Retail, Hospitality, Healthcare, Entertainment Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Verifone, Zucchetti, NCR Corporation, NEC Corporation, Panasonic Corporation, Worldline SA, PAX Global Technology Ltd., POSBANK, Nexi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy POS Terminals Market Shifts & Advancements
Hardware-software convergence and regulatory data governance are restructuring how payment terminals authenticate transactions, store records, and connect to merchant back-office systems across Italian commercial establishments.
Embedded secure elements with integrated biometric sensors are unifying identity verification and payment authorization into single hardware modules. High-volume supermarket chains in Turin and Bologna are piloting fingerprint-authenticated checkout lanes that eliminate PIN entry delays. This convergence is unifying previously separate authentication infrastructure into consolidated terminal architectures that reduce countertop footprint and streamline merchant compliance.
GDPR enforcement actions by Italian data protection authorities are tightening constraints on cross-border transaction data flows. Cloud-deployed POS architectures must now demonstrate localized encryption and residency controls before Banca d'Italia certification approval. Hospitality merchants operating multi-location chains across Veneto and Emilia-Romagna are responding by demanding edge-computing terminals that process sensitive data within device memory rather than transmitting to remote servers.
Merchant acquisition patterns are fragmenting as independent software vendors bypass traditional bank channels to sell payment-enabled business management platforms directly to restaurants and specialty retailers. Vertical-specific software companies in Florence and Naples are embedding payment acceptance into inventory and reservation systems, displacing standalone terminal procurement through bundled subscription models. This channel disintermediation is most visible in the food service sector, where tablet-based ordering platforms now dominate new merchant onboarding.
Italy POS Terminals Market Segmentation
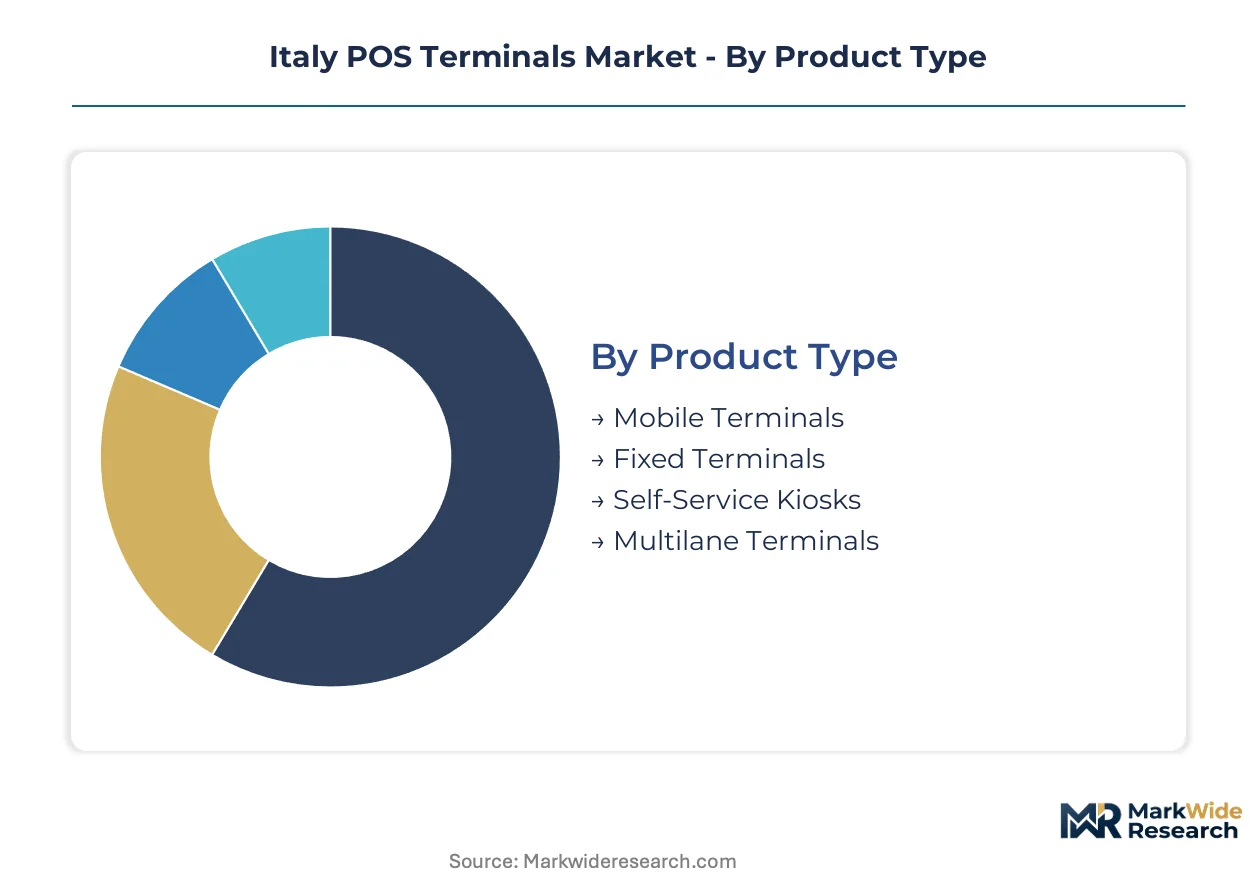
Italian acquirers and merchants configure terminal procurement around transaction velocity, mobility requirements, and PSD2 compliance obligations. Segmentation reveals how hardware specifications diverge across Lombardy's luxury retail corridors versus southern provinces with lower terminal penetration.
Product Type:
Customization versus standardization tensions shape procurement patterns across this hardware dimension, with mobile deployments demanding ruggedized chassis while fixed installations prioritize throughput engineering.
- Mobile Terminals:Battery-powered units with integrated 4G/LTE modems and aluminum alloy housings withstand field conditions for Italian food delivery vendors operating untethered checkout. Demand concentrates in Milan's dense food service clusters where pop-up retailers require lane flexibility without countertop infrastructure.
- Fixed Terminals:Counter-mounted devices with ethernet connectivity and high-speed thermal printers dominate supermarket lanes across Turin and Bologna. Procurement in these northern retail corridors prioritizes transaction-per-minute throughput over portability.
- Self-Service Kiosks:Freestanding units with touchscreen ordering interfaces expanding across quick-service restaurant chains in Rome and Florence.
- Multilane Terminals:Centralized processing hubs serving multiple checkout positions in hypermarket configurations.
Leading the category by volume: Fixed Terminals. Growing fastest: Mobile Terminals.
Technology:
Authentication method selection traces merchant customer demographics and Banca d'Italia certification timelines, with newer protocols requiring hardware refresh cycles.
- Contactless:NFC-enabled terminals supporting smartphone wallets and wearable payment devices with embedded secure elements. Lombardy hospitality chains drive replacement demand as PIN entry delays compress during peak dining hours.
- Chip & Pin:EMV-compliant insertion readers retaining dominance in southern Italian provinces where older demographic segments resist tap-to-pay adoption.
- Magnetic Stripe:Legacy swipe readers declining to residual presence in tourist-facing establishments.
- QR Code:Camera-based scanning terminals enabling alternative payment app integration.
Volume leadership sits with Chip & Pin. Steepest expansion trajectory belongs to Contactless.
End User:
Vertical-specific compliance requirements and transaction patterns create divergent hardware specifications across merchant categories.
- Retail:High-throughput fixed terminals with barcode scanning integration serving supermarket and specialty store configurations across Milan's banking corridors.
- Hospitality:Mobile and contactless-optimized devices for restaurants and hotels prioritizing tableside payment flexibility.
- Healthcare:PCI-DSS hardened terminals with audit trail capabilities for hospital and clinic payment collection.
- Entertainment:Ruggedized outdoor-rated units for cinema and event venue deployments.
Retail commands the largest installed base. Hospitality exhibits the fastest technology refresh rates.
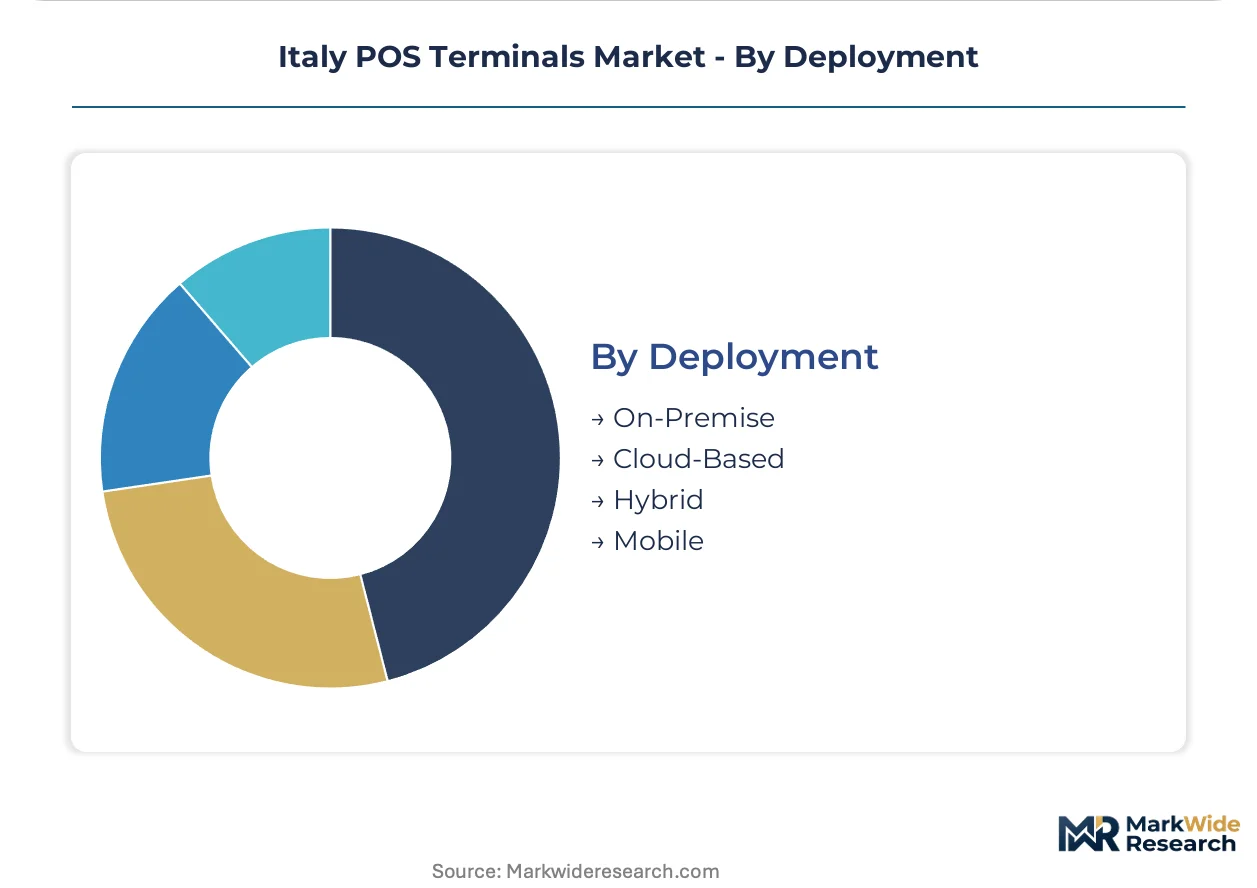
Deployment:
Data residency obligations under GDPR constrain architectural choices, pushing merchants toward localized processing or certified cloud configurations.
- On-Premise:Local server installations with dedicated transaction processing hardware meeting Banca d'Italia certification requirements for sensitive data containment.
- Cloud-Based:Remote-hosted architectures requiring demonstrated encryption and residency controls before regulatory approval.
- Hybrid:Split configurations processing authentication locally while routing settlement through cloud gateways.
- Mobile:Fully portable deployments leveraging cellular connectivity without fixed infrastructure dependency.
On-Premise retains the dominant share. Hybrid architectures are gaining merchant preference fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal procurement concentrates in northern Italy's banking corridors, where merchant density and regulatory proximity accelerate hardware refresh cycles. Southern provinces exhibit significant whitespace, with lower terminal penetration per establishment creating divergent competitive dynamics across the national market.
Lombardy
Milan's luxury retail clusters and dense financial services corridors generate concentrated demand for contactless-enabled terminals. Banca d'Italia maintains its primary certification facilities in the region, compressing hardware approval timelines for local acquirers. The city's food delivery ecosystem drives mobile terminal deployments among pop-up vendors operating across Piazza del Duomo and Navigli districts.
Piedmont
Turin's supermarket chains and automotive sector procurement sustain high-throughput fixed terminal installations. The Agenzia per l'Italia Digitale coordinates regional e-invoicing pilot programs that intersect with POS system requirements. Industrial payment corridors around the city center prioritize PCI-DSS hardened devices for B2B transaction processing.
Veneto
Hospitality merchants across Verona and Venice demand tableside payment flexibility, accelerating mobile terminal adoption in restaurant and hotel configurations. GDPR enforcement by the Garante per la Protezione dei Dati Personali shapes local data residency requirements for cloud-connected devices. The region's tourism-dependent economy drives seasonal procurement spikes aligned with peak visitor months.
Emilia-Romagna
Bologna's retail cooperatives and agricultural supply chains sustain diversified terminal deployments across fixed and mobile categories. The EU's PSD2 implementation timelines pressure local acquirers to complete authentication-compliant hardware upgrades. Food service technology clusters in Parma and Modena integrate payment acceptance into vertical-specific business management platforms.
Lazio
Rome's quick-service restaurant chains and government-facing merchants drive self-service kiosk installations with touchscreen ordering interfaces. Banca d'Italia's supervisory presence in the capital ensures stringent certification compliance for terminal deployments. The metropolitan area's entertainment venues sustain demand for ruggedized outdoor-rated units at cinema and event locations.
Italy POS Terminals Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors align with banking cooperatives and software platforms to secure distribution channels. The market exhibits moderate consolidation, with domestic specialists competing against multinational hardware manufacturers through differentiated service models. Three archetypes define competitive positioning: European manufacturing specialists with regional production footprints, domestic banking-integrated providers with deep cooperative relationships, and Asian modular architecture vendors emphasizing field upgrade flexibility. Capacity expansion and technology licensing represent the primary competitive vectors, as players seek to differentiate through manufacturing scale or software integration capabilities.
Among the established hardware manufacturers, Verifone anchors the European production archetype through its continental manufacturing footprint, while Zucchetti occupies a distinctive position as a domestic banking-integrated specialist. PAX Global Technology Ltd. exemplifies the modular architecture approach that simplifies merchant field upgrades. These three companies represent the dominant competitive positioning patterns visible across the vendor landscape, each aligning with distinct procurement priorities among Italian acquirers and merchant segments.
| Leading Market Players |
|---|
| Verifone |
| Zucchetti |
| NCR Corporation |
| NEC Corporation |
| Panasonic Corporation |
| Worldline SA |
| PAX Global Technology Ltd. |
| POSBANK |
| Nexi |
| Others |
Supply & Pricing Matrix
Italian banking cooperatives and hospitality chains concentrate procurement volumes, anchoring a subscription-leaning pricing model where acquirers bundle terminal hardware with merchant service fees rather than pure equipment sales. This buyer concentration compresses margins on standard-grade devices while sustaining premium pricing for PSD2-certified terminals with embedded biometric modules.
Pricing Analysis
High-volume acquirers extract per-unit economics through fleet-scale deployments, while specialized vendors defend margins via certification-tiered offerings. Three-tier pricing structure across premium, standard, and economy levels tracks PCI-DSS validation grade and aluminum alloy chassis specifications. Cost compression in economy-tier fixed terminals is intensifying because semiconductor allocation volatility extends procurement lead times for encrypted reader modules. Small merchant establishments in southern provinces exhibit highest price sensitivity, whereas Lombardy luxury retail clusters prioritize authentication speed over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and mainland China shape secure processor sourcing patterns for terminal manufacturers. Production draws from concentrated Asian foundry capacity for system-on-chip modules, with aluminum alloy chassis fabrication anchored in European metalworking corridors. Single-source vulnerability in secure element supply exposes vendors to allocation disruption when foundry capacity tightens. Distribution runs through banking cooperative networks and independent software vendor channels, with direct-to-merchant routes expanding among tablet-based platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy POS Terminals Market operates as a cost-of-compliance arena where Banca d'Italia certification requirements erect barrier-to-entry moats that favor incumbent vendors with established regulatory navigation capabilities.
For Market Incumbents: Hedge against SoftPOS smartphone displacement by accelerating software licensing revenue streams and embedding payment acceptance into vertical-specific business management platforms. Fortify channel control through exclusive arrangements with Italian banking cooperatives operating legacy core banking architectures. Prioritize certification investment in biometric-integrated secure elements to maintain premium positioning as PSD2 authentication mandates tighten. For New Entrants and Emerging Players: Capture whitespace in Sicily and Calabria where terminal density per merchant establishment lags northern benchmarks and localized service infrastructure remains underdeveloped. Target food service technology clusters in Parma and Modena with tablet-based ordering platforms that bundle payment acceptance into inventory and reservation systems. Pursue a direct-to-merchant go-to-market angle that bypasses traditional bank acquisition channels through vertical software partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic banking-integrated specialists with deep cooperative relationships in Lombardy and Piedmont as valuation compression hits hardware-dependent vendors. Long-term viability hinges on software-recurring revenue mix rather than terminal shipment volumes. Watch SoftPOS penetration rates among Italian food delivery vendors as the critical inflection signal distinguishing platform winners from hardware commoditization casualties.| Strategic Initiative | Industry Significance |
|---|---|
| PSD2 Certification Fast-Track | Accelerates Banca d'Italia approval timelines for biometric-enabled terminal architectures. |
| Vertical Software Integration | Embeds payment acceptance into Florence and Naples restaurant management platforms. |
| Southern Region Service Buildout | Establishes localized merchant onboarding capabilities in Sicily and Calabria corridors. |
| Aluminum Chassis Manufacturing Scale-Up | Extends field service intervals for mobile deployments among Milan food delivery vendors. |
| Edge Computing Terminal Development | Addresses GDPR data residency requirements for Veneto hospitality chain deployments. |
Research Methodology
Banca d'Italia regulatory filings, EU payment system statistics, and Italian banking cooperative annual reports formed the secondary backbone, cross-referenced against primary interviews with payment terminal procurement managers, merchant acquisition executives, and hospitality technology directors. Bottom-up and top-down triangulation validated shipment estimates against acquirer fleet deployment disclosures and merchant establishment counts across regional banking corridors.
Bottom-up modeling aggregated terminal shipments by product type, technology protocol, and end-use vertical, while top-down analysis tracked payment transaction volume growth against hardware refresh cycle assumptions. Segmentation dimensions included mobility configuration, authentication method, deployment architecture, and regional merchant density patterns. CAGRs were derived from regression analysis of historical certification timelines and replacement demand elasticity, incorporating semiconductor supply constraints and regulatory implementation schedules as exogenous variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SoftPOS adoption velocity and Banca d'Italia certification backlog resolution. Forecasts reflect documented assumptions about merchant upgrade propensity and foundry capacity allocation. Regulatory enforcement intensity around GDPR data residency and PSD2 authentication thresholds warrants ongoing watch as primary revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe POS Terminal Market
Payments
Russia Payments Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Taiwan Mobile Payments Market
Payments
Europe Prepaid Card Market
Payments
Mobile Point of Sale (POS) Market
Payments
Social Media Payment Solution Market
Payments
Netherlands Mobile Payments Market
Payments
Global Gift Card Market
Payments
Argentina Payments Market
Payments
Belgium Payments Market
Payments
Global Telecom Billing Market
Payments
Contactless Payment Ring Market
Payments
Digital Remittance Service Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Cash Management Software Market