
 Global Inspection Machines Market | 2026-2036
Global Inspection Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inspection Machines Market Foresight
Pharmaceutical-grade vision verification is rotating toward higher-resolution sensor architectures and AI-augmented defect classification. Körber AG leverages its integrated pharma handling systems to anchor European packaging line retrofits. Mettler-Toledo International Inc sustains dominance in checkweighing and metal detection through precision load-cell engineering. Cognex Corporation specializes in machine vision software layers that differentiate on algorithmic speed for high-throughput semiconductor wafer inspection.
Inspection machines encompass automated systems that detect surface flaws, dimensional deviations, and structural inconsistencies in manufactured goods using optical, X-ray, ultrasonic, or electromagnetic modalities with resolutions reaching sub-micron scales. These systems execute non-destructive evaluation to enforce specification compliance, reduce scrap rates, and satisfy traceability mandates across regulated supply chains. Optical inspection retains the largest installed base due to maturity in electronics and food quality assurance, while X-ray inspection captures the fastest expansion as pharmaceutical packaging and aerospace component verification adopt inline computed tomography for sealed-container integrity. Machine vision technology leads margin pools through software licensing and recurring algorithm updates, whereas 3D scanning grows fastest in aerospace component verification where geometric dimensioning tolerances tighten.
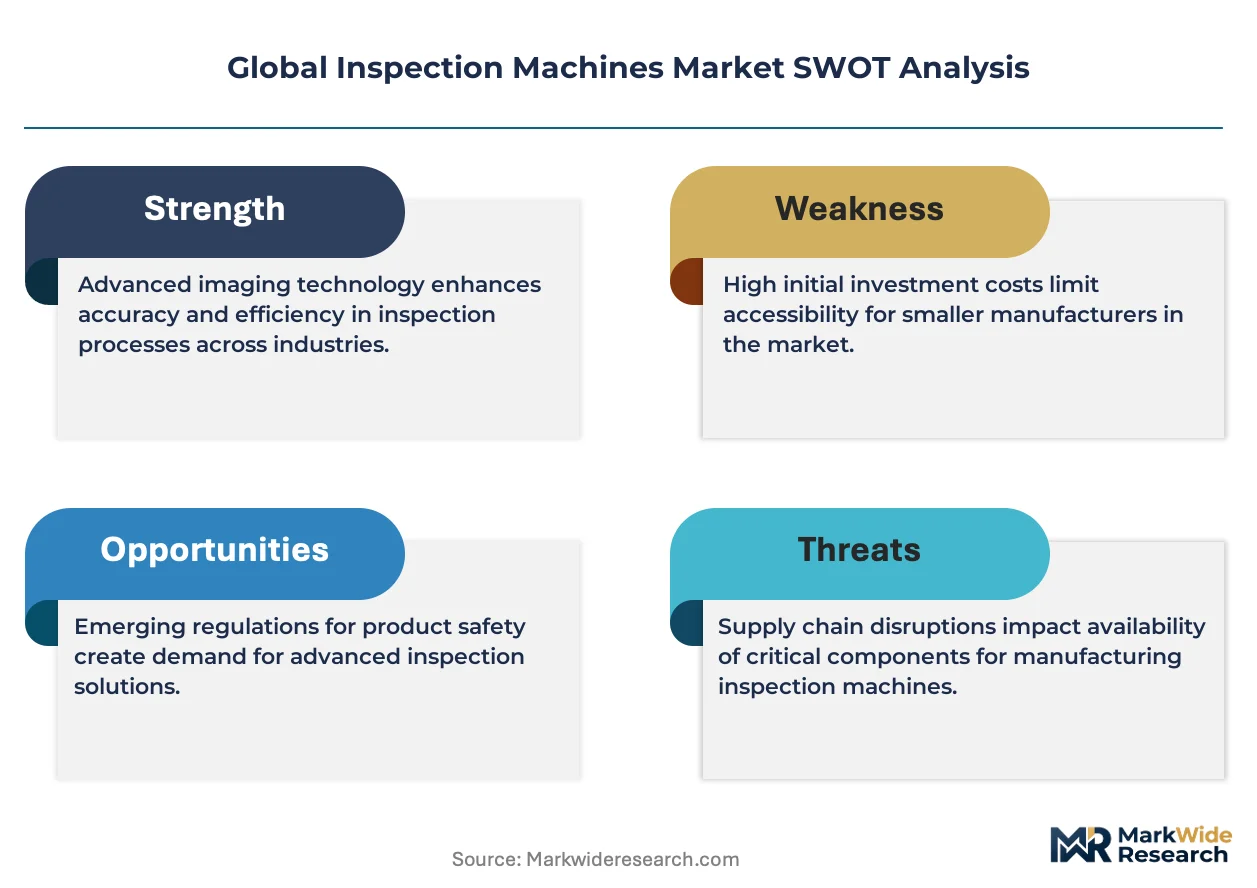
FDA cGMP guidelines, EU MDR conformity requirements, and ISO 9001 quality management standards collectively elevate baseline inspection sensitivity thresholds and documentation burdens for manufacturers. The EPA and OSHA frameworks in the United States further mandate worker-safety protocols around radiographic inspection equipment, adding compliance cost layers that favor consolidated vendor relationships. Stakeholders must monitor convergence between FDA digital validation guidance and EU AI Act risk classifications for autonomous defect-detection algorithms.
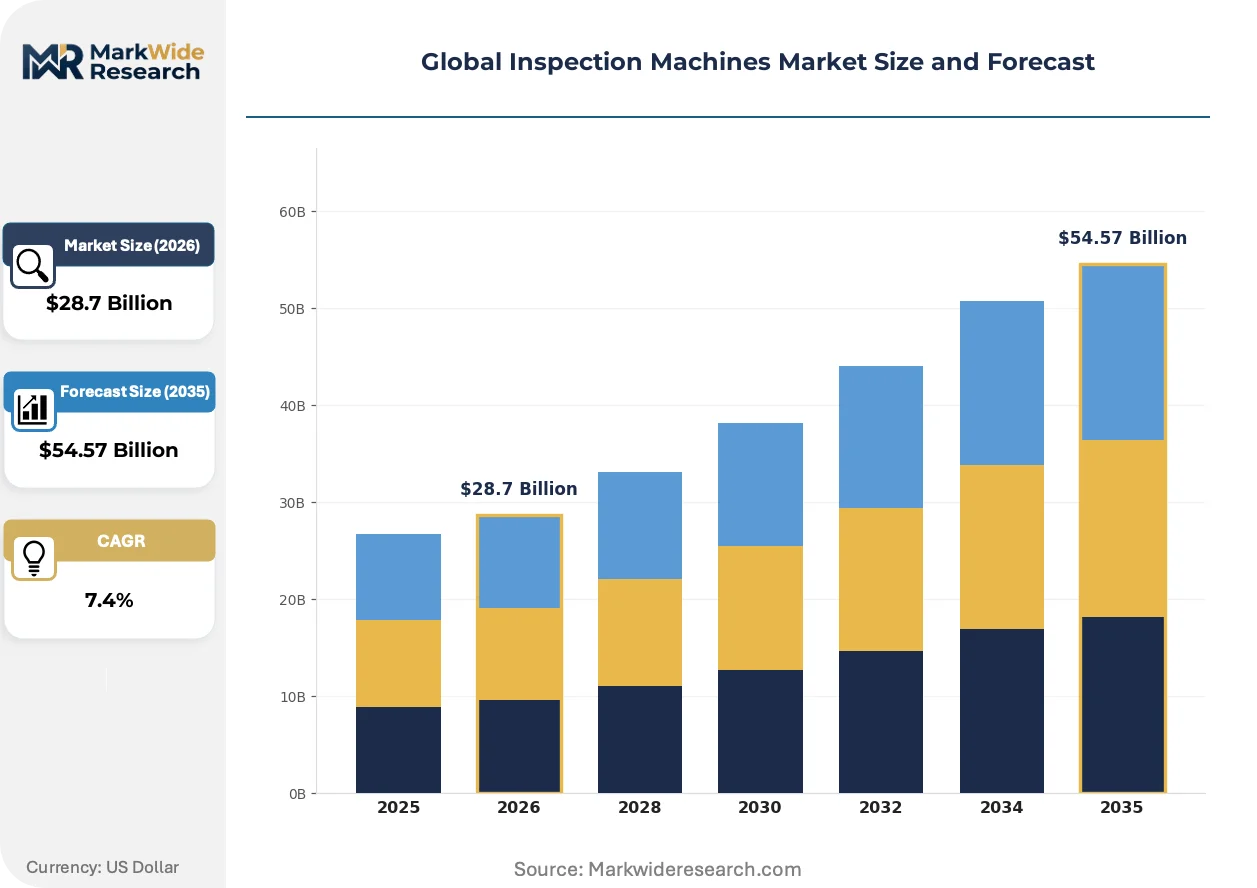
Market Dynamics
Pharmaceutical manufacturers are consolidating inspection workflows into unified vision-X-ray fusion platforms to satisfy FDA cGMP and EU MDR traceability mandates while compressing line footprint. This integration imperative is forcing equipment vendors to bundle software licensing with hardware contracts, altering margin structures across the supply base.
Growth Catalysts
- EU MDR conformity expansion:Medical device manufacturers in Germany and Ireland must deploy automated visual inspection for Class III implantable packaging, mandating system retrofits across sterile barrier lines.
- Computed tomography adoption:Aerospace suppliers in France and the United States now require inline X-ray CT for turbine blade porosity detection, displacing destructive testing protocols.
- Semiconductor wafer throughput demands:Taiwan and South Korean fabs are upgrading to sub-micron optical inspection to manage 3nm node yield complexity.
Market Restraints
- High-purity sensor supply concentration:German and Japanese suppliers dominate sCMOS and InGaAs detector fabrication, creating single-source vulnerability for vision system assemblers.
- Radiographic equipment certification friction:EPA and OSHA licensing timelines for X-ray inspection deployment extend 14-22 months, freezing capital allocation decisions.
- Machine vision software substitution:Open-source Python-based inspection libraries are eroding pricing power in mid-tier food and beverage quality assurance.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO is tightening visual inspection requirements for export-oriented formulations, creating first-mover advantage for integrated system vendors.
- AI-vision convergence:Deep learning defect classification fused with hyperspectral imaging enables real-time pharmaceutical tablet coating analysis previously requiring offline laboratory verification.
- Service contract unbundling:Predictive maintenance subscriptions for inspection line uptime are penetrating Brazilian and Mexican food processing installations.
Industry Challenges
- Multidisciplinary integration talent scarcity:Combustion of optical engineering, Python algorithm development, and FDA 21 CFR Part 11 validation expertise constrains deployment velocity.
- Legacy MES synchronization complexity:Brownfield pharmaceutical lines running 1990s-era SCADA architectures require custom middleware development for vision system data handshake.
- Patent thickets in 3D reconstruction:Structured light and photogrammetry IP portfolios held by metrology specialists complicate in-house development for mid-tier Asian equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inspection Machines Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $54.57 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Inspection, Optical Inspection, Ultrasonic Inspection, Magnetic Particle Inspection, Eddy Current Inspection Technology: Machine Vision, 3D Scanning, Infrared Thermography, Laser Profiling, Acoustic Emission Analysis Application: Electronic Component Testing, Pharmaceutical Packaging, Aerospace Component Verification, Food Quality Assurance, Semiconductor Inspection End User: Manufacturing Plants, Research Laboratories, Quality Control Departments, Testing Service Providers, Product Development Centers |
| Companies Covered | Körber AG, Mettler-Toledo International Inc, Omron Corporation, Cognex Corporation, Teledyne Technologies Incorporated, Brevetti CEA SpA, Robert Bosch GmbH, Thermo Fisher Scientific Inc, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inspection Machines Market Shifts & Advancements
Inspection modality selection is fragmenting along resolution-throughput tradeoffs as pharmaceutical and semiconductor end-uses diverge in technical requirements. Software-defined architectures are displacing fixed-function hardware, enabling algorithm updates without line revalidation.
Hyperspectral imaging is bifurcating quality assurance workflows in food and pharmaceutical packaging. This technology captures spatial and spectral data simultaneously to detect chemical composition anomalies invisible to RGB cameras. Major European dairy processors and Chinese infant formula manufacturers are deploying inline hyperspectral stations for foreign material detection. The technology is bifurcating the mid-tier inspection market into chemical-aware premium tiers versus commodity vision systems.
EU AI Act risk classification frameworks are mandating human-in-the-loop validation for autonomous defect-detection algorithms in medical device manufacturing. This regulatory architecture forces pharmaceutical packaging lines to maintain parallel manual inspection stations despite automated system deployment. German and Swiss medical device exporters are restructuring validation documentation to satisfy both EU AI Act conformity and FDA digital guidance.
After-sales service unbundling is compressing traditional equipment-plus-maintenance contract structures. Semiconductor fabs in Taiwan and South Korea now procure inspection hardware through capital expenditure while subscribing separately to algorithm update and remote diagnostic services. This bifurcation shifts vendor revenue toward recurring software streams and pressures European equipment manufacturers to build cloud-native diagnostic platforms.
Global Inspection Machines Market Segmentation
Segmentation in inspection machines reveals how modality selection diverges across precision requirements and regulatory exposure. Product type and technology choices directly determine capital intensity, compliance burden, and vendor lock-in duration for end-users.
Product Type:
Optical systems face substitution pressure from AI-augmented machine vision software layers, while X-ray platforms resist displacement due to irreplaceable penetration capabilities for sealed-container verification.
- Optical Inspection:Deploys high-resolution CCD and CMOS sensor arrays with sub-micron resolving power for surface defect detection. Electronics manufacturers in Taiwan and South Korea drive demand for 3nm node wafer verification where throughput requirements exceed 10,000 units per hour. Open-source Python libraries are eroding pricing power in mid-tier food and beverage applications.
- X-ray Inspection:Utilizes sealed-tube and open-tube configurations with computed tomography reconstruction for internal void detection. Pharmaceutical packaging lines in Germany and the United States mandate inline X-ray for EU MDR and FDA cGMP sterile barrier verification. EPA and OSHA radiographic equipment licensing timelines extending 14-22 months constrain deployment velocity.
- Ultrasonic Inspection:Employs piezoelectric transducers for subsurface flaw detection in welded structures and composite laminates.
- Magnetic Particle Inspection:Applies ferromagnetic particle suspensions for surface-breaking crack detection in ferrous aerospace forgings.
- Eddy Current Inspection:Uses electromagnetic induction for conductivity-based defect detection in heat-exchanger tubing and aircraft fastener holes.
Optical inspection anchors the volume base while X-ray inspection gains share at the steepest rate.
Technology:
Technology selection stratifies along margin capture potential, with software-heavy modalities commanding recurring revenue streams against hardware-centric alternatives trapped in one-time equipment sales.
- Machine Vision:Combines industrial cameras, lighting arrays, and algorithmic processing layers for automated defect classification. Semiconductor fabs in Taiwan and South Korea subscribe separately to algorithm updates and remote diagnostics, bifurcating traditional equipment-plus-maintenance contracts. FDA 21 CFR Part 11 validation requirements and EU AI Act risk classifications impose parallel documentation burdens.
- 3D Scanning:Deploys structured light, laser triangulation, or photogrammetry for geometric dimensioning and tolerancing verification. Aerospace suppliers in France and the United States require inline 3D scanning for turbine blade airfoil contour compliance where tolerances tighten below 25 microns. Patent thickets in structured light and photogrammetry IP complicate in-house development for mid-tier Asian equipment vendors.
- Infrared Thermography:Captures thermal emission patterns for predictive maintenance and bond-line integrity assessment in composite structures.
- Laser Profiling:Measures surface topography through triangulated laser displacement for weld seam geometry verification.
- Acoustic Emission Analysis:Detects stress-wave emissions from crack propagation for structural health monitoring in pressure vessels.
Machine vision commands the widest installed base while 3D scanning expands most quickly in aerospace component verification.
Application:
Application concentration tracks regulatory stringency gradients, with pharmaceutical and medical device packaging facing the tightest defect-detection mandates versus food quality assurance where automation penetration remains incomplete.
- Pharmaceutical Packaging:Encompasses sterile barrier integrity verification, label inspection, and container closure integrity testing. German and Irish medical device manufacturers must deploy automated visual inspection for Class III implantable packaging under EU MDR conformity expansion. CDSCO in India is tightening visual inspection requirements for export-oriented formulations, creating first-mover positioning for integrated system vendors.
- Semiconductor Inspection:Addresses wafer-level defect detection, photomask verification, and advanced packaging quality assurance. Taiwan and South Korean fabs are upgrading to sub-micron optical inspection to manage 3nm node yield complexity where defect densities directly determine fab economics. High-purity sensor supply concentration in German and Japanese sCMOS and InGaAs detector fabrication creates single-source vulnerability.
- Electronic Component Testing:Covers printed circuit board assembly verification and connector pin inspection.
- Aerospace Component Verification:Includes turbine blade porosity detection and airframe fastener hole inspection.
- Food Quality Assurance:Encompasses foreign material detection and package seal verification.
Pharmaceutical packaging anchors the value pool while semiconductor inspection climbs the fastest on node complexity escalation.
End User:
End-user structure reflects outsourcing pressures, with manufacturing plants consolidating inspection capabilities in-house while testing service providers capture specialized verification beyond routine production economics.
- Manufacturing Plants:Integrate inline inspection stations directly into production workflows for real-time quality feedback. Pharmaceutical packaging lines in Germany and the United States are consolidating vision-X-ray fusion platforms to compress line footprint while satisfying FDA cGMP and EU MDR traceability mandates. Legacy MES synchronization complexity with 1990s-era SCADA architectures constrains brownfield deployment velocity.
- Testing Service Providers:Operate centralized laboratories for destructive and non-destructive evaluation beyond routine production capacity. Aerospace suppliers in France outsource computed tomography verification for turbine blade porosity detection to specialized radiographic service bureaus. Predictive maintenance subscriptions for inspection line uptime are penetrating Brazilian and Mexican food processing installations.
- Research Laboratories:Develop next-generation inspection methodologies and calibration standards.
- Quality Control Departments:Execute incoming material inspection and final product release testing.
- Product Development Centers:Validate design-for-inspection feasibility during prototype phases.
Manufacturing plants dominate capital deployment while testing service providers expand fastest on outsourcing specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net inspection machine exports flow from Germany, Japan, and the United States toward pharmaceutical and semiconductor manufacturing hubs in China, India, and Southeast Asia. Import dependency concentrates in precision sensor components and X-ray tube assemblies. Regional regulatory divergence creates compliance arbitrage opportunities for multinational equipment vendors.
United States
Pharmaceutical packaging retrofits and aerospace CT adoption drive capital deployment. FDA cGMP guidelines and EPA radiographic equipment licensing extend procurement cycles to 14-22 months. Boston-Cambridge biotech clusters and Seattle-Boeing aerospace corridors anchor demand for sterile barrier and turbine blade inspection systems.
Germany
EU MDR conformity expansion mandates automated visual inspection for Class III implantable medical devices. KBA and BfArM oversight converges on traceability documentation requirements. Baden-Württemberg automotive suppliers and Bavarian pharmaceutical packaging lines consolidate vision-X-ray fusion platforms to compress manufacturing footprints.
China
Domestic semiconductor fabs and infant formula manufacturers accelerate import substitution in optical and hyperspectral inspection. NMPA and GB standards tighten defect-detection thresholds for export-oriented pharmaceutical packaging. Yangtze River Delta electronics clusters and Pearl River Delta dairy processors deploy inline chemical-composition verification systems.
India
CDSCO visual inspection requirements for export formulations create first-mover positioning for integrated system vendors. Maharashtra and Gujarat pharmaceutical packaging corridors retrofit sterile barrier lines to satisfy EU and US regulatory access. Government PLI schemes for medical device manufacturing amplify capital equipment demand.
Japan
Precision sensor fabrication and advanced packaging inspection anchor technological leadership. METI and PMDA standards enforce sub-micron resolution requirements for 3nm node wafer verification. Kyushu semiconductor clusters and Kansai pharmaceutical manufacturing bases sustain demand for high-purity sCMOS and InGaAs detector integration.
Global Inspection Machines Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software bundling strategies and geographic coverage depth. The vendor base stratifies into three tiers: integrated pharma handling conglomerates, precision metrology multinationals, and machine vision software specialists. Strategic moves center on algorithm licensing transitions and predictive maintenance subscription unbundling.
Within the integrated pharma handling tier, Körber AG and Syntegon Technology GmbH exemplify European bundling of inspection hardware with line integration services. Mettler-Toledo International Inc occupies a position among precision load-cell and checkweighing specialists with recurring calibration revenue streams. Cognex Corporation anchors the machine vision software layer where algorithm speed differentiates semiconductor wafer inspection offerings.
| Leading Market Players |
|---|
| Körber AG |
| Mettler-Toledo International Inc |
| Omron Corporation |
| Cognex Corporation |
| Teledyne Technologies Incorporated |
| Brevetti CEA SpA |
| Robert Bosch GmbH |
| Thermo Fisher Scientific Inc |
| Syntegon Technology GmbH |
| Others |
Supply & Pricing Matrix
Capacity utilization above 85% at German and Japanese precision sensor fabs anchors pricing power for high-purity sCMOS and InGaAs detectors, compressing margin headroom for vision system assemblers while elevating price floors for pharmaceutical-grade inspection hardware. This scale concentration simultaneously tightens supply availability and reinforces vendor lock-in through bundled software licensing contracts.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure combining capital equipment sales with recurring algorithm update subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from mid-tier food inspection units and open-source-dependent commodity vision setups. Cost compression in the mid-tier is intensifying because Python-based inspection libraries erode proprietary software pricing power. Contract manufacturing organizations in India and Mexico exhibit highest price sensitivity, while semiconductor fabs in Taiwan and South Korea prioritize throughput performance over unit cost.
Supply Chain Analysis
Inventory lead times for X-ray tube assemblies and high-purity optical sensors now extend 14-22 months, constraining deployment velocity for pharmaceutical packaging retrofits. Component fabrication concentrates in Germany, Japan, and the United States for precision detectors, while China dominates lower-tier optical module assembly. Raw material dependencies center on rare-earth phosphors for X-ray scintillators, high-resistivity silicon for CMOS sensors, and specialty gases for detector chamber fabrication. Single-source vulnerability in sCMOS and InGaAs detector supply creates structural risk for vision system vendors. Distribution runs through direct OEM relationships for pharmaceutical and semiconductor end-users, with regional integrators serving mid-tier food and beverage markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act risk classification frameworks and FDA digital validation guidance are converging to mandate human-in-the-loop inspection protocols, creating a high-growth disruption window for vendors capable of unbundling software validation from hardware deployment.
For Market Incumbents: Consolidate algorithm licensing revenue streams through cloud-native diagnostic platforms before open-source substitution erodes mid-tier pricing power. Acquire specialized hyperspectral imaging capabilities to defend against chemical-aware premium tier competition. Backward integration into high-purity sensor supply buffers single-source vulnerability from German and Japanese detector fabs. For New Entrants and Emerging Players: Differentiate on AI-vision convergence for pharmaceutical tablet coating analysis, where real-time chemical composition verification remains underpenetrated. Target CDSCO-mandated visual inspection retrofits in Maharashtra and Gujarat pharmaceutical corridors as the most penetrable geography. Pursue white-label integration partnerships with established European pharma handling conglomerates to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among machine vision software specialists with semiconductor fab algorithm update subscriptions, offering superior cash flow quality against hardware-centric equipment vendors. Long-term viability across the analysis window favors vendors with FDA 21 CFR Part 11 validation expertise and EU MDR conformity documentation capabilities. Watch for EPA and OSHA radiographic equipment licensing timeline compression as an inflection signal for X-ray inspection deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software Licensing Unbundling | Separates algorithm update subscriptions from hardware contracts, shifting revenue toward recurring streams for semiconductor fabs. |
| Hyperspectral Imaging Integration | Enables real-time pharmaceutical tablet coating analysis previously requiring offline laboratory verification under FDA cGMP. |
| Cloud-Native Diagnostic Platform | Supports predictive maintenance subscriptions penetrating Brazilian and Mexican food processing installations. |
| Vision-X-Ray Fusion Platform | Compresses pharmaceutical packaging line footprint while satisfying EU MDR traceability mandates in Germany and Ireland. |
| Backward Integration into Sensor Supply | Mitigates single-source vulnerability from German and Japanese sCMOS and InGaAs detector fabrication concentration. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical packaging engineers, semiconductor fab quality directors, aerospace component verification specialists, and FDA regulatory consultants anchors the qualitative findings against secondary validation from FDA cGMP guidance documents, EU MDR conformity assessment procedures, EPA radiographic equipment licensing records, and ISO 9001 quality management certification databases. Bottom-up equipment shipment tracking and top-down manufacturing value-added estimates complete the triangulation.
Sensitivity analysis across multiple scenario assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled include inspection modality, technology layer, application vertical, end-user archetype, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis, regulatory mandate implementation timelines, and node complexity escalation patterns in semiconductor fabrication. Industry-specific inputs encompass EU MDR Class III implantable packaging retrofit schedules and 3nm wafer yield complexity thresholds.
Forecasts assume regulatory continuity in FDA cGMP, EU MDR, and EPA radiographic equipment frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated open-source vision library substitution, extended EPA licensing timelines, or breakthrough displacement of optical inspection by X-ray CT in semiconductor packaging. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
United States Borescope Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market