
 Metrology Systems Market | 2026-2036
Metrology Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Metrology Systems Market Foresight
Buyer concentration in automotive OEM supply chains is decoupling as electric vehicle startups and battery cell producers fragment the traditional customer base. Hexagon AB leverages its software-hardware integration to sustain dominance in automated measurement lines. ZEISS Group anchors its position through R&D intensity in optical sensor architectures. Mitutoyo Corporation specializes in shop-floor dimensional gauges for mid-tier manufacturing.
Metrology systems encompass precision instruments that quantify physical dimensions, surface characteristics, and geometric tolerances through contact or non-contact methods, typically achieving sub-micron resolution for quality assurance in discrete manufacturing. These systems serve the essential industrial purpose of verifying conformance to engineering specifications before assembly integration or final shipment. Coordinate measuring machines occupy the mature core of product revenues, while optical measurement systems capture expanding margin pools in semiconductor wafer inspection. Automated measurement technology is displacing manual gauging fastest in electronics assembly, where throughput requirements exceed human operator cycle times.
FDA enforces dimensional verification standards for medical device components under 21 CFR Part 820 quality system regulations, compelling healthcare sector buyers to maintain calibrated metrology assets. CE marking under EU MDR and REACH compliance from ECHA restrict material compositions in probe assemblies and lubricants, reshaping supplier qualification criteria. ISO 10360 calibration protocols govern international equipment acceptance, creating baseline interoperability demands across export markets. Stakeholders must weigh capital deployment between inline automated stations and flexible lab-based systems as production lot sizes contract across end-use sectors.
Market Dynamics
Automotive electrification is fragmenting traditional buyer concentration as battery cell producers and EV startups displace incumbent OEM procurement hierarchies, while EU AI Act traceability mandates force metrology vendors to reengineer data architectures for algorithmic audit trails.
Growth Catalysts
- EU AI Act compliance:Automated measurement systems with embedded machine learning must demonstrate algorithmic transparency, creating replacement demand for legacy equipment lacking audit-ready data logging across German precision engineering clusters.
- Semiconductor wafer inspection:Optical coordinate measuring systems achieve sub-10 nanometer resolution for EUV lithography mask verification, pulling capital deployment from foundries in Taiwan, South Korea, and the Netherlands.
- Aerospace turbine blade geometries:Additive-manufactured cooling channel architectures exceed manual gauging capability, compelling Rolls-Royce and Safran suppliers to install automated white-light scanning cells.
Market Restraints
- Granite machine base supply:Vibration-damping substrate for high-precision CMMs concentrates in southern Indian quarries, exposing lead time volatility to geopolitical friction and export licensing delays.
- Probe assembly material constraints:REACH compliance from ECHA restricts chromium compounds in ruby stylus tips and perfluorinated lubricants in air-bearing spindles, forcing costly reformulation of consumable components.
- Technical limitation in transparent media:Confocal chromatic sensors fail on polished sapphire and diamond surfaces due to refractive index interference, excluding optical methods from certain gemstone and photonics applications.
Strategic Opportunities
- Battery cell gigafactories in Hungary and Poland:Greenfield EV battery plants lack established metrology infrastructure, creating first-mover advantage for vendors offering integrated inline electrode thickness and separator pore measurement.
- Medical device additive manufacturing:FDA 21 CFR Part 820 dimensional verification requirements for patient-specific implants create demand for CT-based volumetric measurement systems that validate internal lattice structures non-destructively.
- Convergence of photogrammetry and structured light:Portable 3D scanners combining both modalities enable shop-floor reverse engineering without climate-controlled lab environments, opening mid-tier manufacturing segments previously priced out of optical metrology.
Industry Challenges
- Calibration technician scarcity:ISO 10360-compliant artifact handling and uncertainty budgeting require specialized competencies that vocational programs in Stuttgart and Karlsruhe cannot scale to meet replacement demand.
- Legacy CMM controller integration:1990s-era coordinate measuring machines with proprietary bus architectures resist retrofit for Industry 4.0 data protocols, forcing costly controller replacement or parallel shadow IT systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metrology Systems Market |
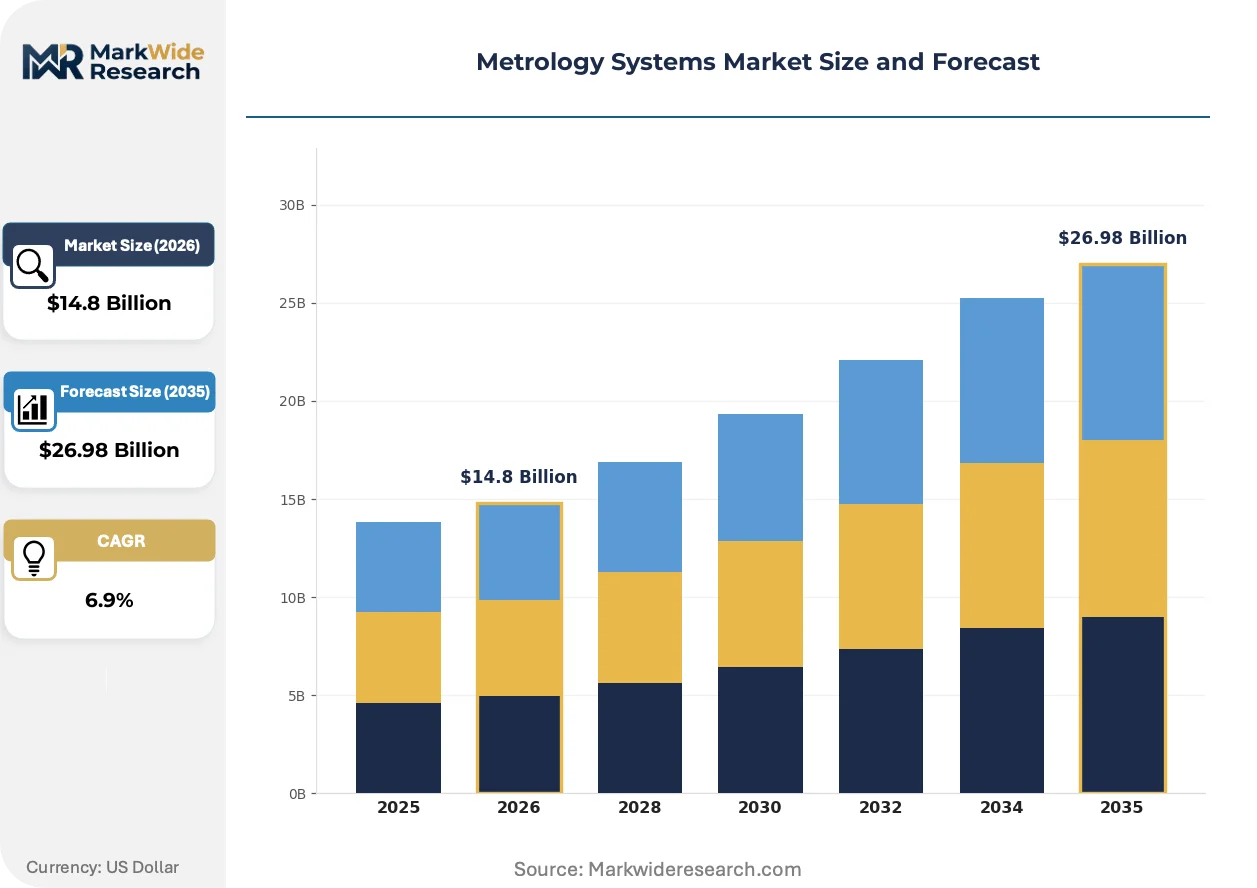
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coordinate Measuring Machines, Optical Measurement Systems, Hardness Testers, Surface Roughness Testers End User: Aerospace, Automotive, Healthcare, Electronics Application: Quality Control, Calibration Services, Research & Development, Production Technology: 3D Scanning, Laser Metrology, Optical Sensors, Automated Measurement |
| Companies Covered | Hexagon AB, ZEISS Group, Mitutoyo Corporation, Nikon Metrology, Renishaw plc, KEYENCE Corporation, KLA Corporation, FARO Technologies, Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metrology Systems Market Shifts & Advancements
Sensor fusion architectures and edge-computing analytics are compressing measurement cycle times while expanding the addressable market beyond traditional quality lab environments into production line integration.
Multisensor coordinate measuring machines combining tactile probing, chromatic confocal, and computed tomography in a single kinematic frame is modularizing capital deployment for manufacturers facing volatile product mix. Automotive suppliers in Germany adopt these configurations to switch between powertrain and battery housing inspection without dedicated single-purpose lines. The technology is modularizing how quality departments justify equipment ROI across shorter product lifecycles.
EU MDR CE marking requirements under 2017/745 mandate measurement traceability for implantable device dimensions throughout production history, not merely final inspection. This regulatory burden compels medical device manufacturers to deploy inline metrology at each machining stage rather than end-of-line sampling. Cardiovascular stent producers in Ireland and orthopaedic joint manufacturers in Switzerland now specify equipment with native audit trail generation.
Contract measurement service bureaus are unbundling after-sales calibration and artifact certification from original equipment vendors, creating independent channel competition. Tier-2 automotive suppliers in Michigan and Bavaria increasingly outsource dimensional validation to accredited third parties rather than maintaining captive metrology labs. This pattern concentrates most visibly in powertrain component manufacturing where production volumes no longer justify dedicated quality infrastructure.
Metrology Systems Market Segmentation
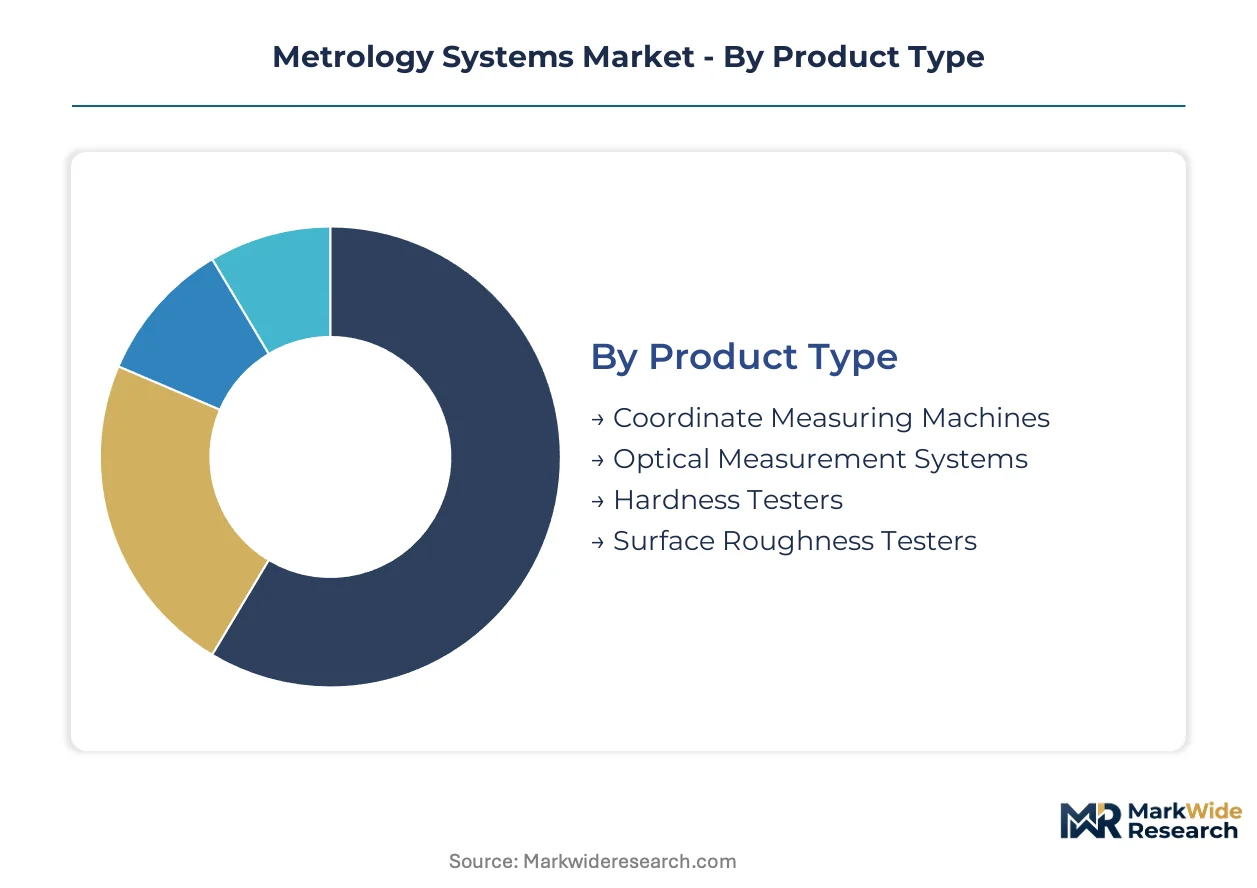
Metrology systems fragment across four structural axes that determine capital allocation patterns. Product type governs resolution capability and capital intensity. End user concentration shapes procurement hierarchies and compliance requirements. Application context dictates throughput specifications and data architecture. Technology selection determines environmental tolerance and operator skill requirements.
Product Type:
Resolution specifications and kinematic architectures differentiate equipment classes across manufacturing tiers.
- Coordinate Measuring Machines:Granite-base bridge and gantry configurations achieve sub-micron repeatability through tactile probing. Mature installed base concentrates in German automotive powertrain machining, though battery housing geometries are pulling demand toward larger envelope machines. Lead times extend when southern Indian granite quarries face export licensing friction.
- Optical Measurement Systems:Chromatic confocal and white-light interferometry eliminate mechanical contact for semiconductor wafer inspection. Taiwan and Netherlands foundries deploy these for EUV lithography mask verification where sub-10 nanometer resolution is mandatory. Refractive index interference limits utility on polished sapphire surfaces.
- Hardness Testers:Rockwell and Vickers indenters verify heat treatment conformance in aerospace fastener production.
- Surface Roughness Testers:Portable stylus profilometers serve shop-floor validation of bearing raceway finishes.
Mature deployment sits with Coordinate Measuring Machines. Newer deployment is concentrated in Optical Measurement Systems.
End User:
Compliance regimes and production geometries create divergent specification requirements across industrial sectors.
- Aerospace:Rolls-Royce and Safran suppliers deploy automated white-light scanning for additive-manufactured turbine blade cooling channels. FAA airworthiness directives mandate dimensional traceability throughout machining stages, not merely final inspection.
- Automotive:Battery cell producers in Hungary and Poland lack established metrology infrastructure, creating first-mover opportunities for inline electrode thickness measurement. EV startups fragment traditional OEM procurement hierarchies.
- Healthcare:FDA 21 CFR Part 820 compels calibrated assets for implantable device verification. EU MDR CE marking tightens traceability standards for measurement devices used in cardiovascular stent production.
- Electronics:Throughput requirements in semiconductor assembly exceed human operator cycle times, accelerating automated measurement adoption.
Established volume concentrates in Automotive. Steepest expansion trajectory is occurring in Healthcare.
Application:
Operational context determines data logging architecture and calibration frequency requirements.
- Quality Control:End-of-line sampling protocols dominate traditional discrete manufacturing. EU AI Act mandates are forcing reengineering toward algorithmic audit trails for machine learning-embedded systems.
- Calibration Services:Contract bureaus in Michigan and Bavaria unbundle artifact certification from original equipment vendors. ISO 10360-compliant uncertainty budgeting requires specialized competencies that Stuttgart vocational programs cannot scale.
- Research & Development:Laboratory environments tolerate climate-controlled coordinate measuring machines with extended cycle times.
- Production:Inline stations demand vibration tolerance and native Industry 4.0 protocol compatibility that 1990s-era CMM controllers resist.
Quality Control retains the largest installed base. Production integration is gaining share fastest.
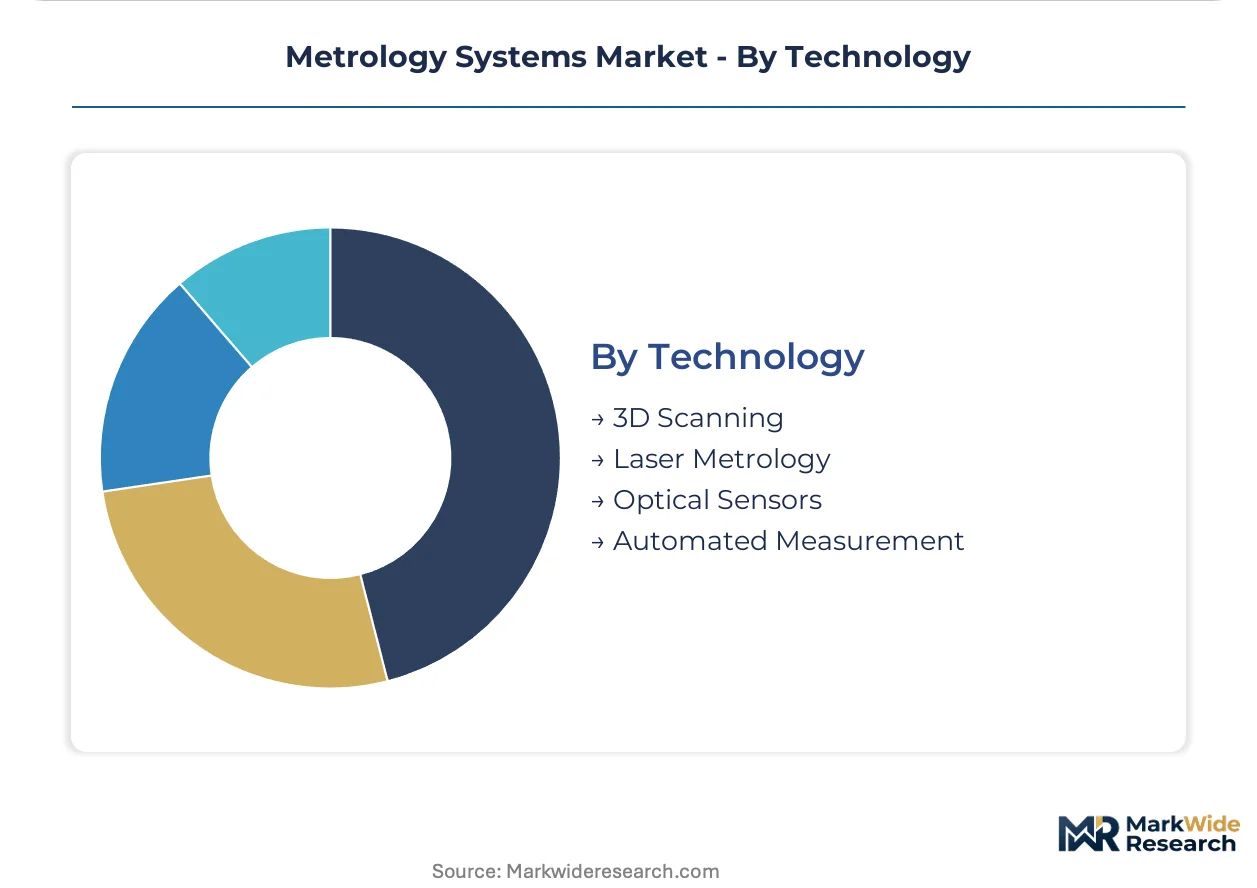
Technology:
Measurement modality determines environmental tolerance, throughput ceiling, and operator training burden.
- 3D Scanning:Portable photogrammetry and structured light convergence enables shop-floor reverse engineering without climate control. Mid-tier manufacturing segments previously priced out of optical metrology now access dimensional validation.
- Laser Metrology:Time-of-flight and triangulation configurations serve large envelope applications like wind turbine blade inspection.
- Optical Sensors:Confocal chromatic probes fail on diamond surfaces due to refractive index interference, excluding certain photonics applications.
- Automated Measurement:Multisensor architectures combining tactile probing, chromatic confocal, and computed tomography modularize capital deployment for volatile product mix.
Optical Sensors represent the most mature technology base. Automated Measurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern Indian granite quarries supply vibration-damping machine bases for precision coordinate measuring machines, anchoring raw material security for high-end metrology equipment deployed across German automotive clusters and Taiwanese semiconductor foundries.
Germany
Stuttgart and Karlsruhe precision engineering corridors drive demand for automated measurement lines serving battery housing geometries and powertrain components. EU AI Act algorithmic transparency mandates force reengineering of legacy equipment lacking audit-ready data logging. Baden-Württemberg vocational programs struggle to scale calibration technician training to meet replacement demand.
United States
FDA 21 CFR Part 820 quality system regulations compel medical device manufacturers in Massachusetts and Minnesota to maintain calibrated metrology assets for implantable component verification. Michigan Tier-2 automotive suppliers increasingly outsource dimensional validation to accredited contract bureaus rather than maintaining captive labs. FAA airworthiness directives mandate dimensional traceability throughout aerospace machining stages.
Taiwan
Foundry capital deployment for EUV lithography mask verification pulls demand for optical coordinate measuring systems achieving sub-10 nanometer resolution. ECHA REACH compliance restricts chromium compounds in probe assemblies, forcing reformulation of consumable components used in wafer inspection. Hsinchu Science Park concentrates metrology infrastructure serving TSMC and United Microelectronics.
China
SAMR metrology standard enforcement and GB calibration protocols govern equipment acceptance for export-oriented manufacturing in Jiangsu and Guangdong. Domestic battery cell producers and EV startups fragment traditional procurement hierarchies previously dominated by joint-venture OEMs. Yangtze River Delta electronics assembly lines accelerate automated measurement adoption where throughput exceeds human operator cycle times.
Hungary
Greenfield EV battery gigafactories around Debrecen and Győr lack established metrology infrastructure, creating first-mover opportunities for inline electrode thickness and separator pore measurement systems. ECHA REACH restrictions on perfluorinated lubricants reshape supplier qualification criteria for air-bearing spindle maintenance. EU MDR CE marking requirements tighten traceability standards for measurement devices used in adjacent medical device component production.
Metrology Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-hardware convergence and portable 3D scanning modalities. The vendor base concentrates around three archetypes: diversified industrial technology conglomerates with automated measurement line integration, specialized optical sensor architects, and shop-floor dimensional gauge specialists serving mid-tier manufacturing. Strategic moves center on multisensor platform modularization and unbundling of after-sales calibration services into independent channel competition.
Within the diversified technology tier, Hexagon AB and ZEISS Group exemplify contrasting approaches to sustaining market position—Hexagon through software-hardware integration dominance in automated lines, ZEISS through R&D intensity in optical sensor architectures. Mitutoyo Corporation anchors the shop-floor specialist segment, occupying a position calibrated to mid-tier manufacturing demand for dimensional gauges. These three entities collectively represent the spectrum of competitive positioning from premium automated systems through accessible shop-floor equipment.
| Leading Market Players |
|---|
| Hexagon AB |
| ZEISS Group |
| Mitutoyo Corporation |
| Nikon Metrology |
| Renishaw plc |
| KEYENCE Corporation |
| KLA Corporation |
| FARO Technologies |
| Carl Zeiss AG |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 10360-calibrated premium systems and uncertified economy alternatives manifests in pricing spreads exceeding threefold, while supply chain configurations segregate accordingly: granite-base CMM producers draw from southern Indian quarries for vibration-damping substrates, and optical sensor architects source germanium optics from specialized foundries.
Pricing Analysis
Warranty and calibration-service bundling separates premium-tier vendors from commodity competitors, with multiyear artifact-certification packages commanding substantial premiums over bare-equipment transactions. Pricing stratifies across premium, standard, and economy tiers based on resolution specification and software-hardware integration depth. Cost compression in economy tactile gauges intensifies as Chinese manufacturers scale production of bridge-type CMMs. Battery cell producers in Hungary and Poland exhibit highest price sensitivity, while semiconductor foundries in Taiwan prioritize sub-10 nanometer resolution over procurement cost.
Supply Chain Analysis
Domestic-content mandates in China's SAMR enforcement and India's phased manufacturing programs are reshaping sourcing patterns for controller electronics and granite machine bases. Vibration-damping substrates concentrate in southern Indian quarries, precision optics draw from German and Japanese specialty glassworks, and motion-control electronics rest on Taiwanese and South Korean semiconductor output. Single-source vulnerability concentrates in granite supply, where export licensing friction from Karnataka state authorities disrupts lead times. Distribution runs through authorized dealer networks for premium equipment and direct e-commerce channels for portable shop-floor gauges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metrology systems vendors face a consolidation imperative as EU AI Act compliance costs force subscale players toward exit or acquisition, concentrating competitive capacity among integrated technology conglomerates.
For Market Incumbents: Acquire calibration-service bureau networks to capture recurring revenue streams and lock in aftermarket attachment rates. Incumbents should consolidate controller-software stacks to neutralize emerging entrants offering modular, retrofit-compatible measurement nodes. Threat substitution from portable 3D scanning vendors demands defensive patent accumulation in photogrammetry-structured light fusion. Channel control through exclusive distributor agreements in Germany's precision engineering corridor anchors installed base retention.
For New Entrants and Emerging Players: Begin with battery cell gigafactories in Hungary and Poland, where greenfield infrastructure gaps eliminate incumbent switching-cost advantages. White-space concentration in mid-tier automotive suppliers previously priced out of automated measurement lines offers penetration pathways. Target medical device additive manufacturing with CT-based volumetric systems that validate internal lattice structures non-destructively. Go-to-market leverage rests on subscription-based equipment-plus-service bundling that converts capital expenditure to operational expenditure for EV startup buyers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial technology conglomerates seeking optical sensor architectures or software-defined measurement platforms. Long-term viability across the analysis window favors vendors with demonstrated EU MDR CE marking competence and native audit-trail generation capabilities. Acquisition target archetype: mid-cap specialists with installed bases in semiconductor or aerospace verticals but underdeveloped aftermarket service penetration. Signal to watch: calibration technician wage inflation in Stuttgart and Karlsruhe, indicating replacement-demand bottlenecks that service-capability acquirers can exploit.
| Strategic Initiative | Industry Significance |
|---|---|
| Multisensor Platform Modularization | Enables automotive suppliers to switch between powertrain and battery inspection without dedicated lines. |
| Calibration Service Bureau Acquisition | Captures recurring revenue from Tier-2 suppliers outsourcing dimensional validation in Michigan and Bavaria. |
| EU AI Act Data Architecture Reengineering | Forces replacement demand for legacy equipment lacking algorithmic audit trails across German clusters. |
| Battery Gigafactory First-Mover Deployment | Greenfield EV plants in Hungary and Poland lack established metrology infrastructure. |
| CT-Based Volumetric Measurement Development | FDA 21 CFR Part 820 requirements for patient-specific implant validation create defensive moat. |
Research Methodology
Trade association filings, ECHA REACH regulatory databases, and SEC 10-K equipment revenue disclosures formed the secondary backbone for market sizing. Primary interviews with quality engineering directors at automotive OEMs, calibration laboratory managers in Stuttgart and Karlsruhe, and semiconductor metrology leads at Taiwan foundries validated demand assumptions. Bottom-up triangulation across product-type shipments and top-down reconciliation against end-use capital expenditure surveys anchored volume estimates.
Bottom-up modeling of coordinate measuring machine, optical measurement system, and portable 3D scanner deployments across automotive, aerospace, healthcare, and electronics verticals generated segment-level trajectories. Analytical lenses weighted technology substitution effects, regulatory compliance deadlines, and geographic production shifts throughout the projection horizon. CAGRs derived from equipment replacement cycles, greenfield capacity announcements, and software-hardware convergence adoption curves. Industry-specific inputs incorporated EUV lithography mask verification resolution requirements and EU MDR CE marking implementation timelines.
Underlying measurement precision varies by segment; semiconductor wafer inspection and aerospace turbine blade applications carry tighter precision than shop-floor dimensional gauging. Forecasts reflect assumptions regarding granite quarry export licensing stability, calibration technician training pipeline scaling, and REACH reformulation cost pass-through. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Calibration Services Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Network Tester Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Shock Testing System Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Simulation and Test Data Management Market