

Silicon Photonics and Optical I/O Test and Measurement Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Photonics and Optical I/O Test and Measurement Systems Market Insights
The direct sales channel between test equipment vendors and semiconductor foundries is narrowing as co-packaged optics and chiplet architectures demand joint calibration protocols. Keysight Technologies leverages its PNA platform to anchor relationships with photonics packaging houses in North America. FormFactor specializes in advanced probe card designs that sustain margins at wafer-level test nodes below 7nm. Advantest competes through memory-test heritage extended into optical I/O validation for AI accelerators.
Silicon photonics and optical I/O test and measurement systems comprise instrumentation that characterizes optical transmitters, receivers, and waveguides fabricated on silicon substrates, typically operating at wavelengths near 1310nm or 1550nm with modulation rates exceeding 100 Gbaud. These systems verify bit error rates, optical signal-to-noise ratios, and eye diagram margins to guarantee interoperability in high-speed interconnects. Bit Error Rate Testers and Eye Diagram Analyzers dominate current procurement as 800G module validation intensifies, while Network Analyzer demand accelerates fastest for coherent detection subsystem characterization. Optical Spectrum Analyzers occupy a mature margin pool in telecom network commissioning, though tunable laser integration is shifting value toward combined photonic test engines.
FCC equipment authorization rules in the United States, CE marking under the EU Radio Equipment Directive, and China's GB standards for optical communication equipment each shape product compliance timelines and regional market access conditions. ISO 17025 laboratory accreditation requirements further constrain which vendors can supply calibration services to Tier 1 foundries. Stakeholders must monitor IEEE 802.3dj and OIF standards evolution to anticipate which test parameters will become mandatory for next-generation optical I/O certification.
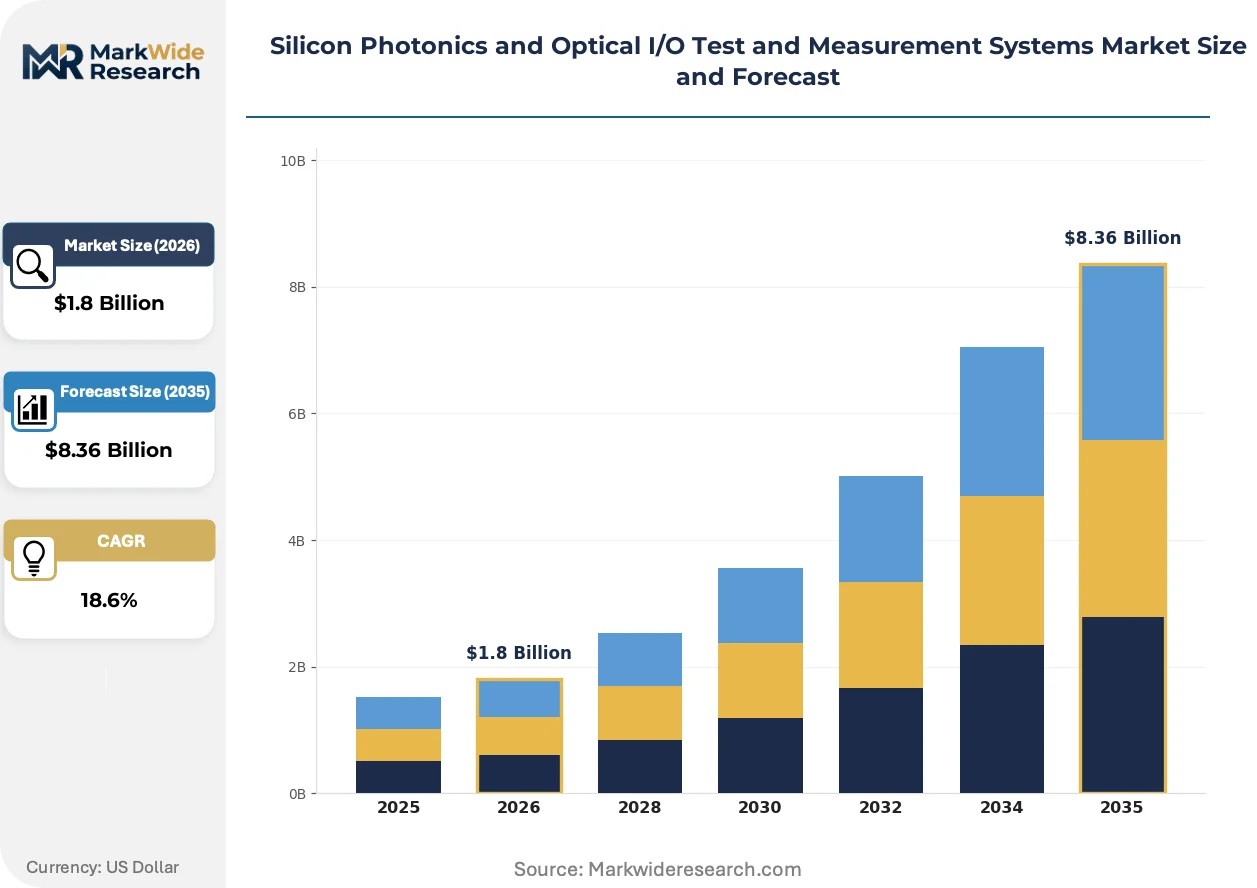
Market Dynamics
Co-packaged optical engines are compressing test cycles as hyperscale data centers demand simultaneous electrical and optical validation at the package level, forcing instrumentation vendors to merge RF and photonic measurement capabilities into unified platforms.
Growth Catalysts
- IEEE 802.3dj standards development:The draft specifications for 1.6T optical interconnects are mandating new eye diagram mask requirements that drive replacement demand for legacy Bit Error Rate Testers in North American foundries.
- AI accelerator optical I/O integration:Training clusters require coherent detection subsystems that validate polarization multiplexing at wafer probe, pulling Network Analyzer procurement from memory test heritage into photonics packaging houses.
- Taiwan photonics foundry cluster expansion:Advanced packaging capacity concentration around Hsinchu Science Park is creating captive demand for joint calibration protocols between probe card vendors and optical engine assemblers.
Market Restraints
- Tunable laser supply concentration:German and Japanese laser diode manufacturers control critical 1550nm sources, exposing test system builders to single-source risk for combined photonic test engines.
- ISO 17025 accreditation barriers:Tier 1 foundries restrict calibration service contracts to accredited laboratories, structurally excluding smaller regional service providers from high-margin recurring revenue streams.
- Legacy telecom test asset longevity:Optical Spectrum Analyzers commissioned during 100G deployment cycles remain serviceable for 800G module validation, delaying replacement cycles in price-sensitive network operator procurement.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Domestic packaging incentives are attracting test equipment vendors to establish calibration laboratories serving emerging photonics assembly operations in Gujarat and Karnataka.
- Silicon nitride waveguide convergence:Integration of silicon photonics with silicon nitride platforms for visible-light sensing applications is opening new wavelength bands requiring 780nm-850nm test instrumentation.
- Direct foundry-vendor collaboration channels:Joint development agreements for co-packaged optics calibration protocols are displacing traditional distributor relationships, enabling margin capture through embedded software licensing.
Industry Challenges
- Multi-physics simulation talent scarcity:Test system design now requires simultaneous expertise in electromagnetic, thermal, and optical modeling, with qualified engineers concentrated among a handful of North American and European research institutions.
- Wafer probe card qualification timelines:Each new optical I/O architecture requires 6-12 months of correlation studies between electrical probe measurements and packaged module performance, compressing product launch windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Photonics and Optical I/O Test and Measurement Systems Market Trends and Innovations
Instrumentation architectures are converging around software-defined measurement engines that reconfigure hardware platforms through firmware updates, reducing capital obsolescence risk for foundry buyers.
Photonic integrated circuit test cells are rendering obsolete discrete single-function instruments that sequentially characterize transmitters, receivers, and waveguides through separate mechanical handoffs. Foundry engineers in Taiwan and Germany now specify unified platforms that execute bit error rate, optical spectrum, and eye diagram analysis within a single probe touchdown sequence, collapsing test floor footprint requirements by half.
FCC equipment authorization rules for optical communications equipment are tightening electromagnetic interference documentation requirements for 800G and 1.6T modules. Test system vendors must now embed pre-compliance scanning capabilities into production floor instruments, with North American hyperscale operators demanding traceable calibration chains that satisfy both FCC Part 15 and IEEE 802.3dj specifications simultaneously.
Consolidated procurement by hyperscale data center operators is compressing vendor qualification cycles and unbundling after-sales service contracts from hardware purchases. Amazon Web Services, Microsoft Azure, and Google Cloud negotiate enterprise-wide framework agreements that specify calibration service levels separately from capital equipment acquisition, with pricing transparency requirements forcing test vendors to itemize software licensing, training, and spare parts provisioning.
Silicon Photonics and Optical I/O Test and Measurement Systems Market Segmentation
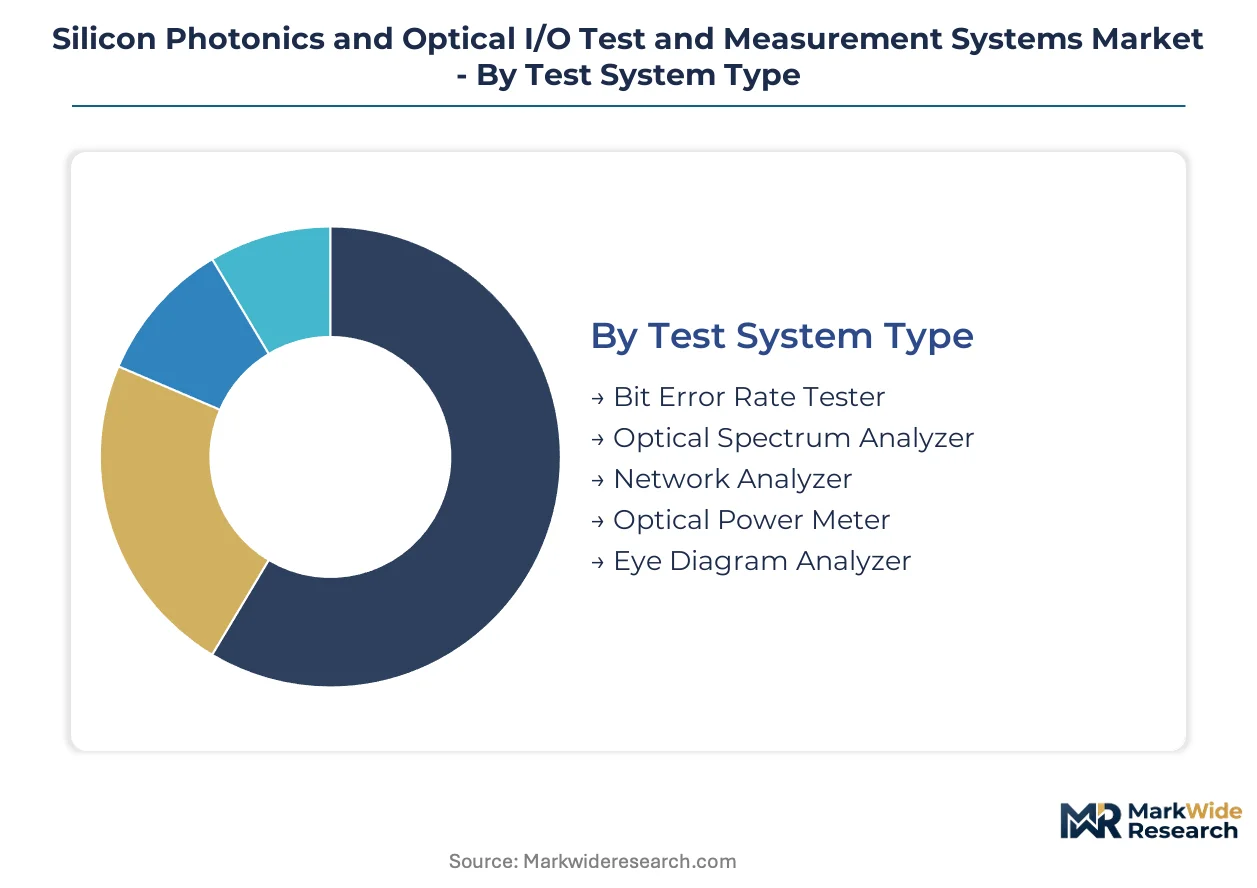
Segmentation in silicon photonics test systems reveals how instrumentation vendors align hardware architectures with distinct validation workflows. Each dimension—system type, technology, application, and end user—carries unique procurement patterns and technical specifications that shape vendor competitive positioning.
Test System Type:
Mature instrumentation categories dominate current procurement volumes while emerging platforms capture design-in momentum for next-generation interconnects.
- Bit Error Rate Tester:Core validation engines that quantify signal integrity through statistical error counting at 100+ Gbaud modulation rates. Demand concentrates in North American hyperscale data centers validating 800G optical modules, driven by IEEE 802.3dj compliance mandates for 1.6T development.
- Network Analyzer:Vector measurement platforms characterizing S-parameters and polarization-dependent loss in coherent detection subsystems. Procurement accelerates fastest among Taiwan photonics packaging houses integrating optical I/O with AI accelerators, pulled by wafer-level probe requirements for polarization multiplexing.
- Optical Spectrum Analyzer:Wavelength-selective instruments measuring optical signal-to-noise ratios and channel isolation. Legacy telecom operator assets in Germany and Japan sustain replacement deferrals despite 800G module validation needs.
- Optical Power Meter:Compact sensors providing absolute power reference calibration for production floor traceability. Semiconductor foundries in Hsinchu Science Park deploy these for rapid throughput screening.
- Eye Diagram Analyzer:Time-domain instruments visualizing signal quality margins against IEEE mask specifications. Integration into unified photonic test cells is displacing standalone procurement.
Bit Error Rate Testers handle the majority of throughput; Network Analyzers are expanding most quickly on share.
Technology:
Cost tier stratification separates high-value coherent subsystems from commodity photonic components, with pricing scaling exponentially by optical complexity.
- Coherent Detection:Advanced receivers combining local oscillator lasers with dual-polarization mixers enabling 400+ Gbps per wavelength. Taiwan foundries and North American AI accelerator designers drive premium procurement for training cluster interconnects.
- Tunable Lasers:Swept-wavelength sources enabling swept-source optical coherence tomography and WDM channel characterization. German and Japanese diode manufacturers control supply, creating single-source risk for test system builders.
- Wavelength Division Multiplexing:Parallel channel architectures multiplying fiber capacity through spectral separation. Telecom network operators in the United States deploy these for metro and long-haul capacity expansion.
- Modulators:Silicon photonic devices encoding electrical signals onto optical carriers through carrier depletion or thermal tuning. Foundry probe card vendors integrate these for wafer-level transmitter validation.
- Photodetectors:PIN and avalanche diode receivers converting optical signals to electrical domain for bit error analysis. Volume procurement tracks 800G module production ramps.
Coherent Detection commands premium pricing; Tunable Lasers face supply concentration constraints.
Application:
Customer type differentiation separates capital-intensive hyperscale deployments from regulated telecom infrastructure with divergent procurement cycles and compliance requirements.
- Data Centers:Hyperscale facilities requiring simultaneous electrical and optical validation at the package level for co-packaged engines. United States-based cloud operators compress test cycles through unified platform procurement.
- High Performance Computing:Exascale systems demanding optical I/O for node-to-node bandwidth scaling. Research institutions in Germany and the United States specify coherent detection subsystems for next-generation supercomputers.
- Telecommunication Networks:Carrier infrastructure with extended asset lifecycles and price-sensitive replacement decisions. FCC equipment authorization rules and CE marking requirements shape compliance timelines.
- Sensor Systems:Emerging silicon nitride waveguide applications spanning visible-light sensing and LiDAR. 780nm-850nm test instrumentation opens new wavelength bands beyond traditional telecom windows.
- Aerospace Communications:Radiation-hardened optical interconnects for satellite and deep-space platforms. Lower procurement volumes with stringent environmental qualification requirements.
Data Centers absorb the largest equipment volumes; Sensor Systems present the steepest expansion trajectory as wavelength bands diversify.
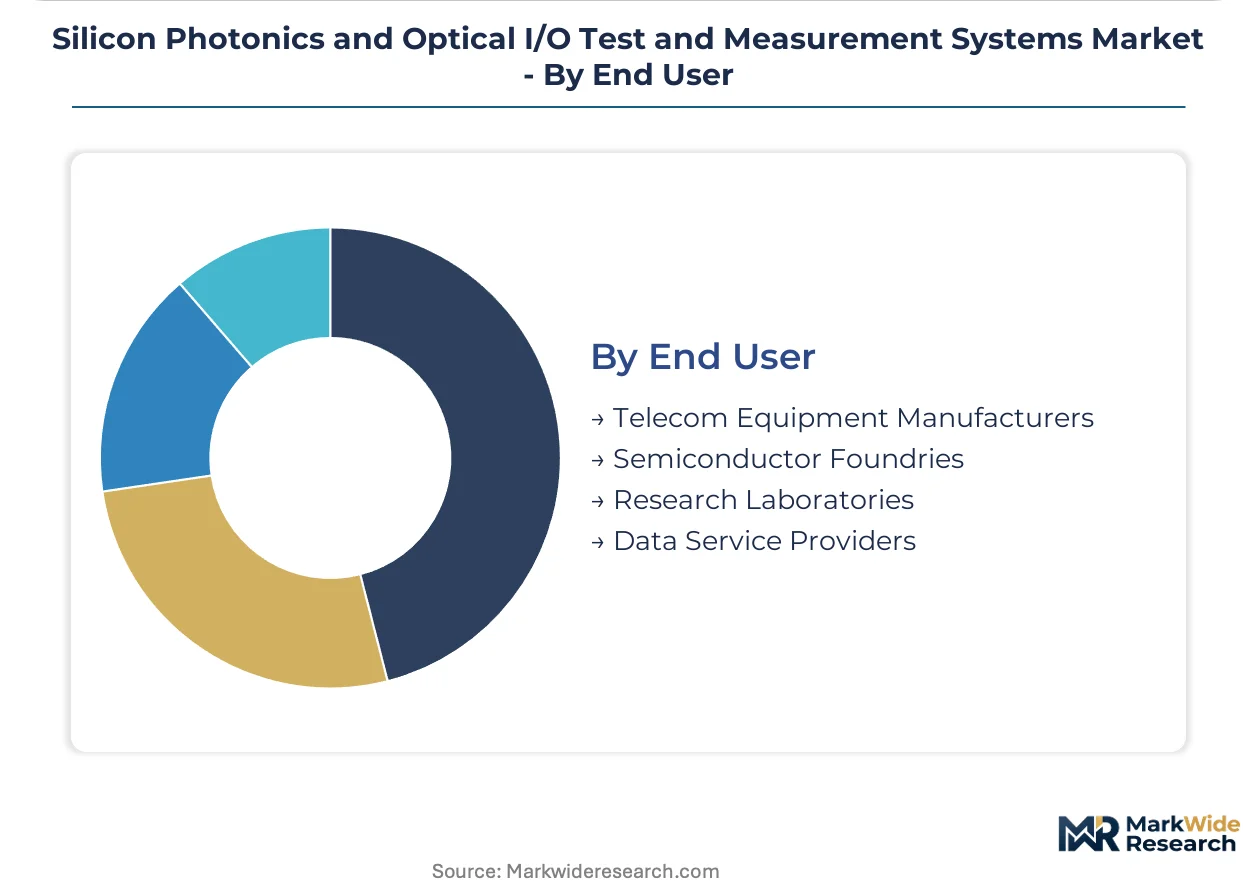
End User:
Supply concentration maps directly onto geographic clustering of advanced packaging capability, with procurement authority consolidating among vertically integrated foundry operations.
- Semiconductor Foundries:Wafer-level test cell operators requiring joint calibration protocols between probe cards and optical engines. Taiwan's Hsinchu Science Park concentration creates captive demand for integrated measurement platforms.
- Telecom Equipment Manufacturers:Module assemblers validating 800G coherent pluggables against IEEE 802.3dj specifications. ISO 17025 accreditation requirements restrict calibration service contracts to qualified laboratories.
- Data Service Providers:Hyperscale operators negotiating enterprise-wide framework agreements with unbundled service contracts. Amazon Web Services, Microsoft Azure, and Google Cloud demand pricing transparency across software licensing, training, and spare parts.
- Research Laboratories:Academic and government facilities advancing photonic integrated circuit architectures. Procurement emphasizes flexibility over throughput for exploratory device characterization.
Semiconductor Foundries drive the majority of capital deployment; Data Service Providers are restructuring vendor relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific submarine cable systems landing at Los Angeles, San Francisco, and Seattle anchor United States demand for 800G and 1.6T optical interconnect validation equipment. These fiber links carry intercontinental traffic for hyperscale data centers requiring co-packaged optical engine test capacity.
United States
FCC equipment authorization rules under Part 15 tighten electromagnetic interference documentation for 800G modules. Hyperscale operators in Northern California negotiate enterprise-wide framework agreements with unbundled calibration service contracts. The Silicon Valley photonics packaging corridor concentrates probe card qualification activity for AI accelerator optical I/O.
Taiwan
Hsinchu Science Park hosts the densest concentration of advanced packaging capacity for silicon photonics foundry operations. The National Science and Technology Council funds photonics integrated circuit test cell standardization initiatives. Joint calibration protocols between probe card vendors and optical engine assemblers operate as captive demand within vertically integrated foundry ecosystems.
Germany
The European Metrology Research Programme establishes traceable calibration chains for coherent detection subsystems used in high-performance computing interconnects. Fraunhofer Heinrich Hertz Institute facilities in Berlin validate polarization multiplexing at wafer probe for research supercomputers. Munich-area laser diode manufacturers control critical 1550nm tunable sources for combined photonic test engines.
Japan
METI's semiconductor revitalization strategy prioritizes domestic optical I/O test equipment production for AI training cluster exports. Yokohama and Osaka house precision instrumentation heritage concentrated among legacy bit error rate tester manufacturers. JIS standards for optical communication equipment shape compliance timelines for module validation workflows.
India
The PLI scheme for semiconductor manufacturing attracts calibration laboratory establishment in Gujarat and Karnataka. Domestic packaging incentives target photonics assembly operations in Dholera and Bengaluru. BIS certification requirements for optical communication equipment constrain which foreign vendors qualify for government-backed fab projects.
Silicon Photonics and Optical I/O Test and Measurement Systems Market Competitive Landscape
On the supply side, the industry is consolidating around instrumentation vendors capable of merging RF and photonic measurement capabilities into unified platforms. Three archetypes dominate: heritage electronic test equipment manufacturers extending into optical domains, specialized probe card designers capturing wafer-level margins, and memory-test heritage players repurposing platforms for AI accelerator validation. Competitive moves center on joint development agreements for co-packaged optics calibration protocols and software-defined measurement engines that reduce capital obsolescence risk.
Within the heritage electronic test tier, Keysight Technologies and Anritsu occupy positions anchored by vector network analyzer platforms serving North American hyperscale procurement cycles. Advantest represents the memory-test heritage archetype extending validation capabilities into optical I/O for training cluster interconnects. These three exemplify how vendor qualification cycles compress as consolidated hyperscale procurement demands simultaneous electrical and optical validation at the package level.
| Leading Market Players |
|---|
| Keysight Technologies |
| FormFactor |
| Advantest |
| MPI Corporation |
| Yokogawa Test & Measurement |
| EXFO |
| Anritsu |
| Teradyne |
| Cohu |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in German and Japanese tunable laser diode manufacturing is compressing availability for 1550nm sources, forcing test system builders to accept longer lead times and ceding pricing power to specialized component suppliers serving North American and Taiwanese foundry demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers capturing coherent detection subsystem validation and economy tiers serving optical power meter commoditization. Price differentiation rests on ISO 17025 calibration certification and volume scale, with hyperscale framework agreements extracting steepest discounts. Cost compression in mid-tier Network Analyzer segments is intensifying because memory-test heritage vendors are repurposing platforms for photonics. Telecom equipment manufacturers exhibit highest price sensitivity due to legacy asset longevity, while semiconductor foundries prioritize throughput over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwan packaging houses are reshaping supplier cash flow dynamics across the ecosystem. Manufacturing concentrates in Taiwan, Germany, and the United States, with critical 1550nm laser diodes drawing from Munich-area and Yokohama producers. Single-source vulnerability pervades tunable laser procurement, while distribution runs through direct foundry-vendor collaboration channels displacing traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as unified photonic test cells displace discrete instruments, with interoperability mandates from IEEE 802.3dj and OIF standards creating winner-take-most dynamics among vendors capable of joint calibration protocol development.
For Market Incumbents: Build switching-cost moats through embedded software licensing in co-packaged optics calibration protocols. Deepen backward integration into probe card design to capture wafer-level margins below 7nm nodes. Defend against memory-test heritage entrants by accelerating firmware-defined measurement engine roadmaps that reduce customer capital obsolescence risk. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-backed semiconductor packaging corridor before incumbent calibration laboratory saturation. Target sensor systems applications spanning silicon nitride waveguide platforms at 780nm-850nm wavelengths, where test instrumentation supply gaps persist. Pursue joint development agreements with Gujarat and Karnataka photonics assembly operations as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across coherent detection subsystem validation as polarization multiplexing requirements multiply hardware complexity. Five-to-ten year viability favors vendors with software-defined architectures that amortize R&D across multiple IEEE standard generations. Acquisition targets should display probe card-electrical test integration capabilities. The signal to watch is OIF standards evolution timing for 1.6T optical interconnect certification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Calibration Protocol Development | Keysight and FormFactor anchor relationships with photonics packaging houses through shared IEEE 802.3dj compliance frameworks. |
| Firmware-Defined Measurement Engine Launch | Software-reconfigurable hardware platforms reduce foundry capital obsolescence risk and extend vendor recurring revenue streams. |
| India Calibration Laboratory Establishment | PLI scheme incentives in Gujarat and Karnataka attract test equipment vendors to serve emerging domestic packaging capacity. |
| Silicon Nitride Waveguide Test Cell Expansion | 780nm-850nm instrumentation opens visible-light sensing and LiDAR applications beyond traditional telecom wavelength windows. |
| Hyperscale Framework Agreement Negotiation | Amazon Web Services and Microsoft Azure unbundle service contracts from hardware, forcing pricing transparency across software licensing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capital expenditure disclosures, IEEE standards documentation, and trade customs data. Primary interviews engaged test equipment product managers, photonics packaging house engineers, semiconductor foundry procurement leads, and calibration laboratory technical directors. Bottom-up instrument shipment analysis triangulates against top-down hyperscale data center infrastructure spending projections.
Forecast inputs include test system type adoption curves, technology node migration timelines, and regional packaging capacity buildouts across the projection horizon. Segmentation dimensions span system type, technology tier, application vertical, and end-user category with geographic production cluster overlays. CAGRs derive from instrument replacement cycle compression analysis and standards-driven compliance mandate timing. Co-packaged optical engine penetration rates and AI accelerator optical I/O integration intensity serve as industry-specific demand drivers.
Sensitivities concentrate around IEEE 802.3dj finalization schedules, tunable laser supply disruptions, and PLI scheme implementation pace in India. Forecasts reflect documented assumptions regarding hyperscale capital expenditure continuity and foundry advanced packaging yield trajectories. Macroeconomic contraction, regulatory restriction on semiconductor equipment exports, or technological disruption in coherent detection architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.