
 Marine Electronics Tester Market | 2026-2036
Marine Electronics Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Electronics Tester Market Outlook
Silicon carbide is consolidating as the preferred semiconductor substrate in high-voltage marine tester architectures, cutting thermal losses by half against traditional silicon IGBTs. Keysight Technologies leverages its RF instrumentation heritage to dominate signal integrity validation for radar and sonar systems. Rohde & Schwarz anchors European demand through calibrated EMC test suites that satisfy naval procurement specifications. Fluke Corporation sustains its position in portable diagnostic tools for dockside marine technicians.
A marine electronics tester is a calibrated measurement instrument designed to verify signal integrity, power quality, and electromagnetic compatibility in vessel-borne electronic systems, typically operating across frequency ranges from DC to 40 GHz with salt-spray-resistant enclosures rated IP67 or higher. Its primary purpose is to certify that navigation, communication, and control electronics perform reliably in corrosive maritime environments before commissioning or after repair. Oscilloscope segments lead in revenue contribution due to their indispensability in waveform analysis for propulsion control systems, while wireless technology represents the fastest-expanding category as shipyards adopt over-the-air diagnostic protocols to reduce cable harness complexity. Digital multimeter applications in marine maintenance form a mature, high-volume pool where margin compression pushes suppliers toward bundled service contracts.
The International Maritime Organization enforces performance standards for navigation equipment through SOLAS Chapter V, directly mandating periodic tester verification of ECDIS and AIS transponders. IEC 60945 and IEC 61162 set electromagnetic and data interface benchmarks that tester manufacturers must embed to achieve type approval. Classification societies including DNV and Lloyd's Register incorporate these standards into their rules for electronics installation surveys. Stakeholders must monitor how the EU Marine Equipment Directive's alignment with updated IEC editions reshapes product certification pathways and aftermarket service obligations.
Market Dynamics
The transition from analog to digital wireless testing architectures constitutes the dominant structural force reshaping marine electronics verification, as shipyards in Germany, Japan, and South Korea retire legacy cable-based diagnostic systems in favor of over-the-air protocols that reduce harness complexity and accelerate commissioning timelines.
Growth Catalysts
- IMO SOLAS Chapter V Mandates:The International Maritime Organization's navigation equipment standards require periodic tester verification of ECDIS and AIS transponders, creating recurring demand for calibrated instruments across commercial fleets.
- Silicon Carbide Semiconductor Adoption:Shipbuilders are specifying SiC-based testers for high-voltage propulsion diagnostics, as the material cuts thermal losses by half against traditional silicon IGBTs in demanding maritime environments.
- Commercial Shipping Fleet Expansion:Operators are adding diagnostic capabilities to meet stricter emissions monitoring protocols under IMO conventions, driving instrument procurement for engine control and exhaust scrubber systems.
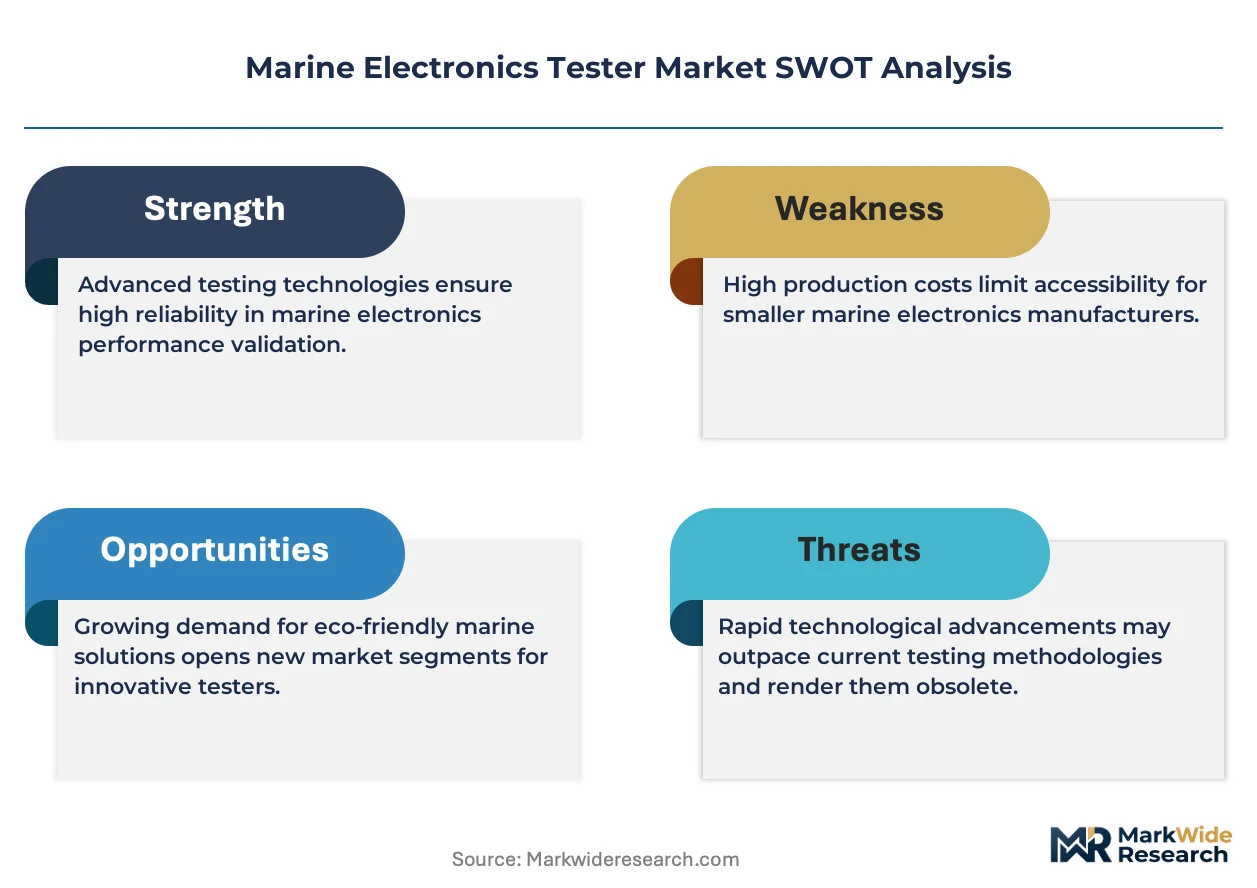
Market Restraints
- Raw Material Concentration:High-purity silicon carbide substrates face supply bottlenecks concentrated among specialized wafer foundries, creating input cost volatility for tester manufacturers.
- Technical Calibration Drift:Salt-spray-resistant IP67 enclosures degrade sensor accuracy over repeated thermal cycling, necessitating frequent recertification that extends total cost of ownership.
- Regulatory Fragmentation:Divergent type-approval pathways between IEC 60945, IEC 61162, and classification society rules from DNV and Lloyd's Register force redundant testing investments.
Strategic Opportunities
- Autonomous Vessel Diagnostics:Uncrewed surface vessels require continuous remote monitoring systems, opening demand for satellite-linked testers that operate without onboard technicians.
- EU Marine Equipment Directive Alignment:Updated IEC edition harmonization is streamlining certification pathways, reducing time-to-market for compliant instruments in European yards.
- Battery-Electric Propulsion Testing:Convergence of high-voltage battery management systems with traditional marine electronics is creating integrated tester demand for hybrid ferry operators.
Industry Challenges
- RF Engineering Talent Scarcity:Shipyards struggle to recruit technicians proficient in 40 GHz signal integrity validation for radar and sonar systems, slowing deployment of advanced wireless platforms.
- Legacy System Integration Friction:Digital wireless testers must interface with decades-old analog navigation equipment still operational in existing fleets, complicating retrofit protocols.
- Extended Certification Timelines:Type approval from classification societies averages 18-24 months for new tester architectures, compressing product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Electronics Tester Market |
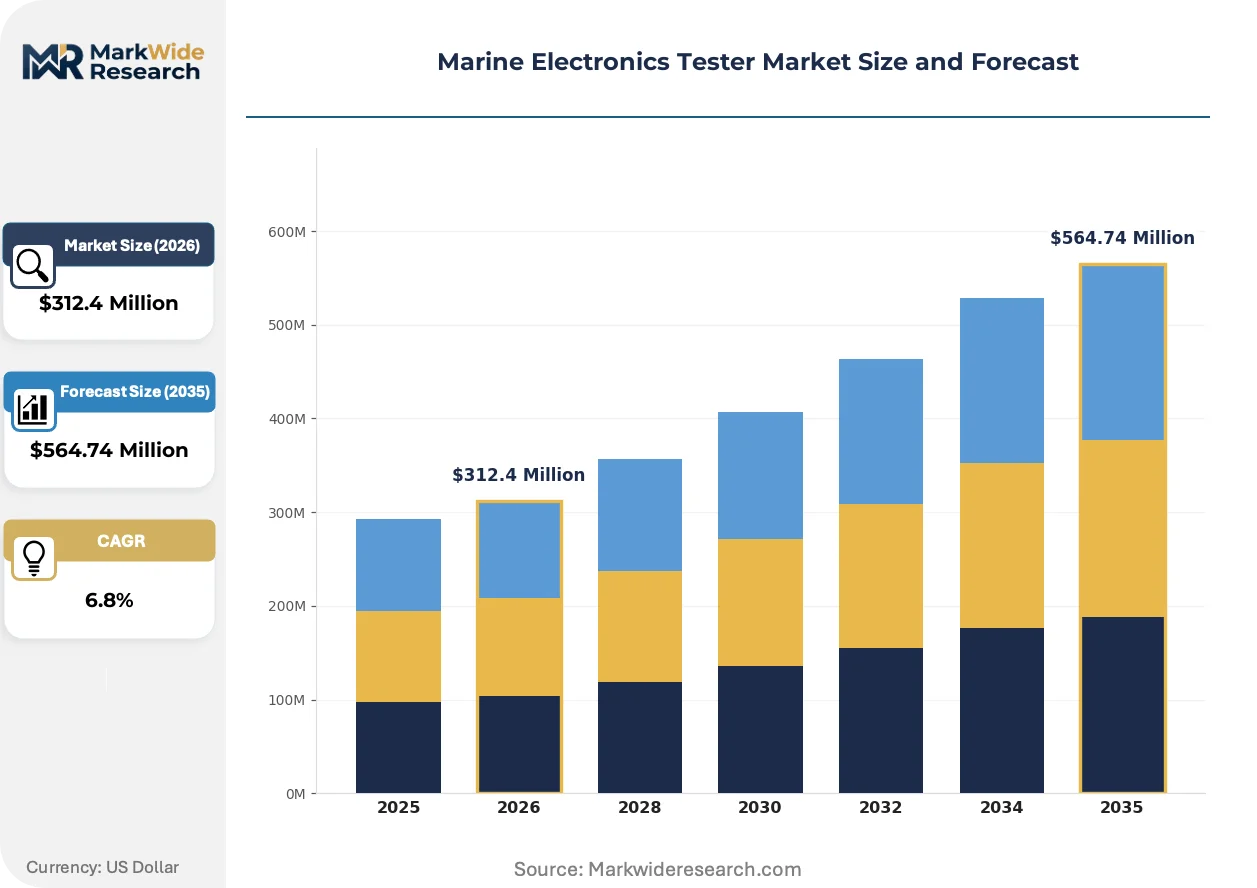
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Multimeter, Signal Generator, Oscilloscope, Data Logger Application: Boat Manufacturing, Marine Maintenance, Research & Development, Calibration Services End User: Shipbuilders, Marine Technicians, Research Institutes, Regulatory Bodies Technology: Analog, Digital, Wireless, Hybrid |
| Companies Covered | Fluke Corporation, Keysight Technologies, Rohde & Schwarz, Teledyne Technologies, Furuno Electric, Parker Hannifin Manufacturing, Kongsberg Gruppen, IKM Instrutek, Nemko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Electronics Tester Market Strategic Shifts
Wireless diagnostic protocols and wide-bandgap semiconductor architectures are converging to redefine how marine electronics verification is performed, shifting value capture from hardware sales toward integrated service ecosystems.
Silicon carbide is consolidating as the preferred semiconductor substrate in high-voltage marine tester architectures. Shipyards in South Korea and Japan are specifying SiC-based instruments for electric propulsion diagnostics. This material transition is consolidating supplier power among specialized wafer foundries while compressing margins for traditional silicon IGBT assemblers.
REACH and RoHS amendments in Europe are tightening substance restrictions on marine electronic components. Tester manufacturers must now document full material declarations for salt-spray-resistant coatings and connector plating. European naval procurement specifications from EDA member states are driving fastest compliance adoption, with yards in Norway and the Netherlands leading verification system upgrades.
Service unbundling is reshaping how dockside technicians access diagnostic capabilities. Independent maintenance contractors are replacing bundled OEM service contracts with pay-per-test arrangements using portable Fluke and Keysight instruments. This pattern is most visible in Mediterranean cruise ship hubs where third-party technical managers handle multi-vessel fleets.
Marine Electronics Tester Market Segmentation
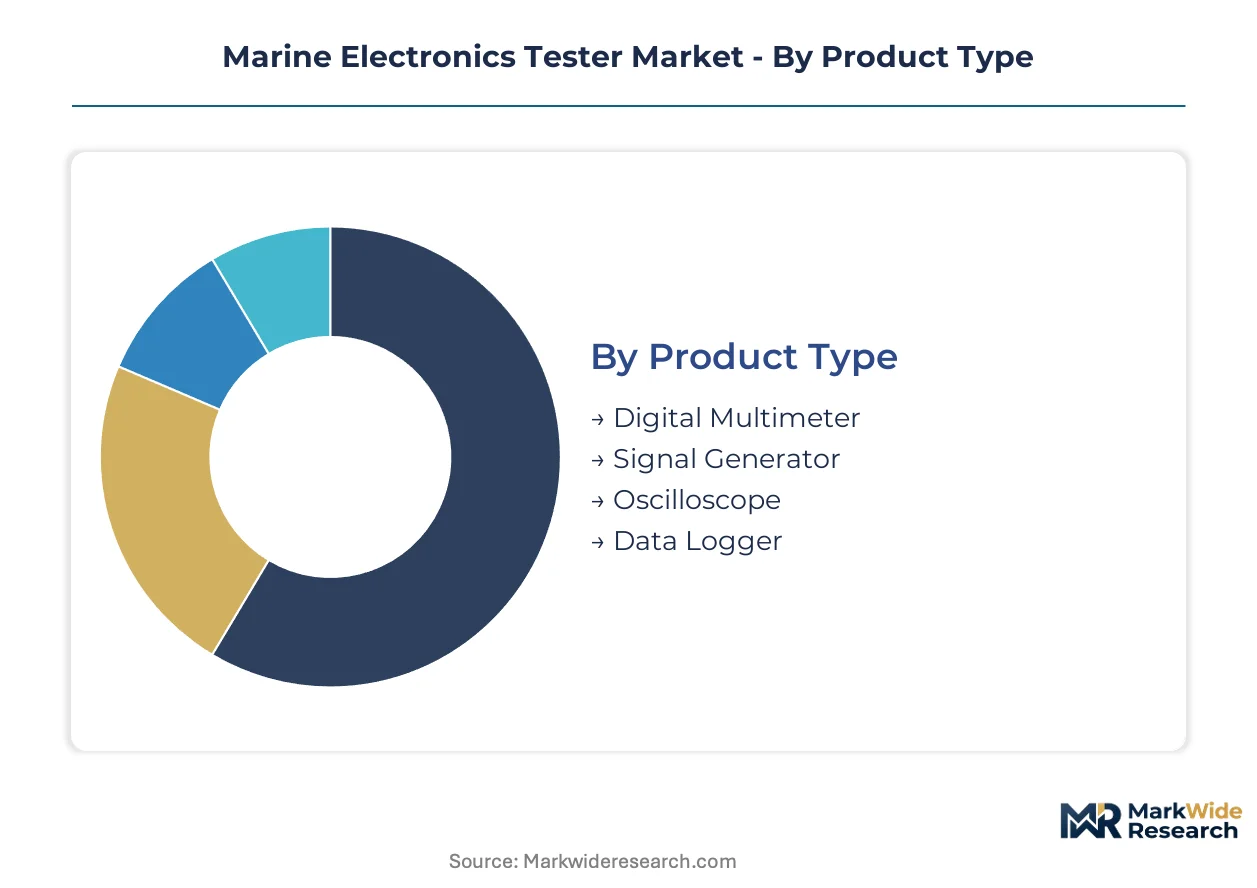
Segmentation in marine electronics testing reveals how technical specifications, regulatory mandates, and end-user workflows fragment procurement patterns. Shipyards prioritize ruggedized instruments for commissioning, while fleet operators favor portable diagnostics for maintenance cycles.
Product Type:
Standardization dominates entry-level instruments, but high-voltage propulsion diagnostics demand customized configurations with SiC architectures.
- Oscilloscope:These instruments capture waveform anomalies in propulsion control systems with sampling rates exceeding 1 GSa/s. German and Japanese shipyards specify four-channel units for integrated electric drive verification. Demand concentrates where IMO emissions protocols mandate continuous engine monitoring.
- Digital Multimeter:Handheld units rated CAT III 1000V serve dockside technicians performing routine circuit validation. Mediterranean cruise hubs drive replacement cycles through third-party maintenance contractors seeking pay-per-test flexibility.
- Signal Generator:RF sources up to 40 GHz validate radar and sonar integrity before sea trials.
- Data Logger:Multi-channel recorders track environmental and electrical parameters during extended vessel operations.
Leading the category by volume: Digital Multimeter. Growing fastest: Oscilloscope.
Application:
Volume concentrates in maintenance workflows, but margin pools in specialized calibration services requiring traceable standards.
- Marine Maintenance:Dockside technicians perform preventive diagnostics on navigation and communication systems using portable instruments. South Korean ports deploy wireless testers to reduce harness replacement costs during turnaround windows.
- Boat Manufacturing:Shipyards integrate automated test stations into production lines for ECDIS and AIS verification. Japanese builders specify EMC-compliant suites to satisfy Lloyd's Register type approval before delivery.
- Research & Development:Naval laboratories prototype next-generation propulsion controls requiring specialized measurement bandwidth.
- Calibration Services:Accredited laboratories maintain reference standards for fleet-wide instrument traceability.
Highest throughput: Marine Maintenance. Steepest expansion trajectory: Calibration Services.
End User:
Procurement authority separates between capital expenditure owners and operational expenditure managers.
- Shipbuilders:Yards in Germany and South Korea specify integrated test benches during new construction. These buyers prioritize IEC 60945 pre-compliance to accelerate classification society approval.
- Marine Technicians:Independent contractors serving Mediterranean and Baltic fleets favor ruggedized handheld units with IP67 ratings for salt-spray environments.
- Research Institutes:Academic and government laboratories secure funding for specialized high-frequency validation systems.
- Regulatory Bodies:Port state control authorities maintain reference instruments for spot-checking vessel compliance.
Dominant procurement volume: Shipbuilders. Gaining share fastest: Marine Technicians.
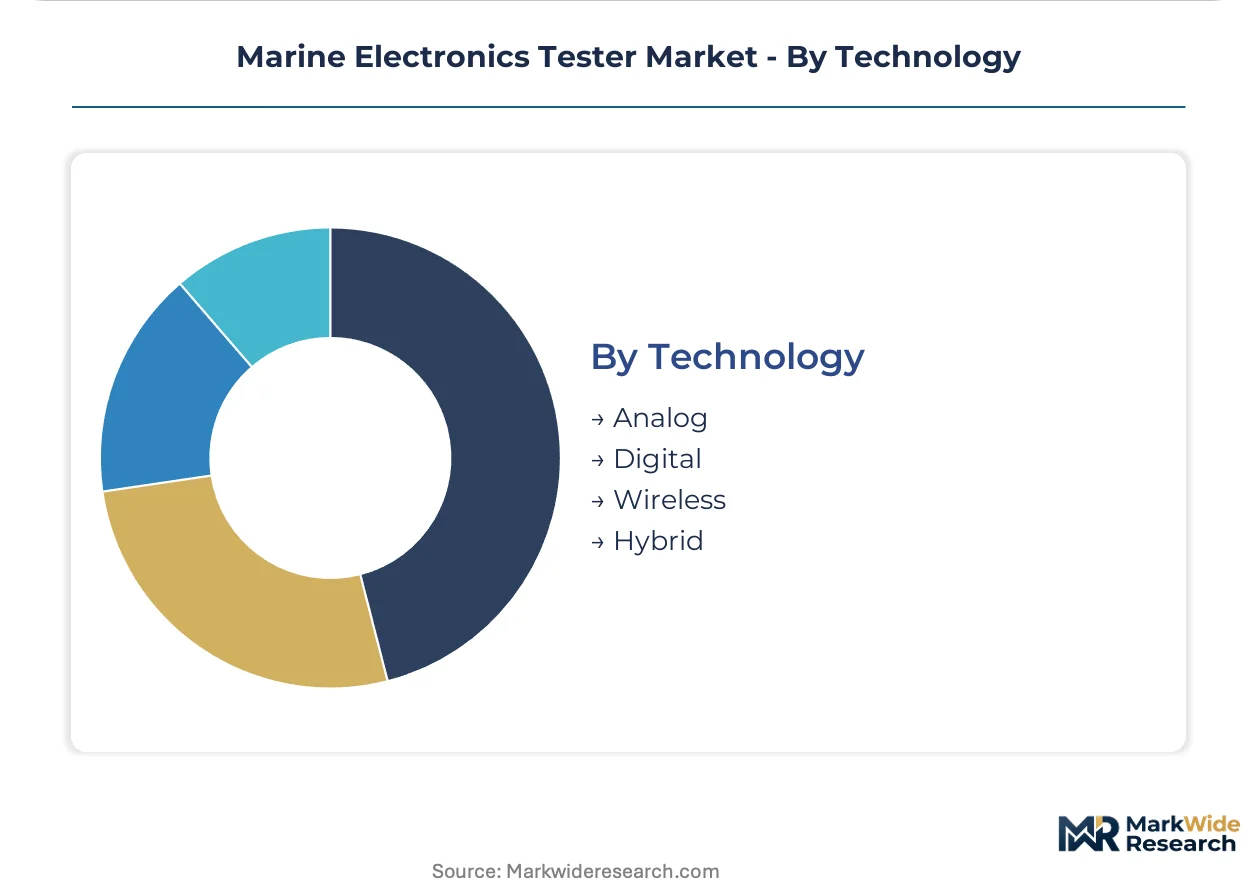
Technology:
Architecture choices determine thermal performance, connectivity protocols, and total cost of ownership across deployment scenarios.
- Wireless:Over-the-air diagnostic platforms eliminate cable harness complexity in confined engine rooms. South Korean yards lead adoption of Bluetooth and Wi-Fi-enabled testers for remote monitoring of uncrewed surface vessel systems.
- Digital:Sampling-based instruments with embedded processing automate pass-fail determination for SOLAS-mandated equipment checks. German naval specifications require digital architectures for EMC test suites.
- Analog:Legacy pointer instruments persist in developing fleet segments where replacement cycles extend decades.
- Hybrid:Combined architectures bridge retrofit scenarios connecting digital acquisition to analog display systems.
Widest installed base: Digital. Expanding most quickly: Wireless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping operators in Germany, Japan, and South Korea account for the densest concentration of marine electronics tester procurement, driven by newbuild programs and emissions compliance retrofit cycles across major shipyard clusters.
Germany
Shipbuilders in Hamburg and Bremerhaven specify IEC 60945-compliant EMC test suites for Lloyd's Register type approval. The EU Marine Equipment Directive alignment with updated IEC editions is compressing certification timelines for domestic manufacturers. Industrial automation suppliers in Bavaria are integrating SiC-based diagnostic benches into electric ferry production lines.
Japan
IMO SOLAS Chapter V mandates drive recurring demand for ECDIS and AIS tester verification across the commercial fleet. METI procurement specifications for naval platforms require calibrated RF instrumentation up to 40 GHz. Shipyards in Nagoya and Kobe are retiring legacy analog diagnostic systems in favor of over-the-air wireless protocols.
South Korea
DSME and HHI yard complexes in Geoje and Ulsan deploy wireless testers to reduce cable harness complexity during vessel commissioning. The country's national shipping regulator enforces periodic emissions monitoring protocol verification under IMO conventions. Battery-electric propulsion testing demand is accelerating from hybrid ferry operators in Incheon.
United States
Coast Guard port state control authorities maintain reference instruments for spot-checking SOLAS equipment compliance. FCC maritime radio certification requirements create aftermarket demand for signal integrity validation tools. Gulf Coast ship repair clusters in Houston and New Orleans favor portable diagnostic units for turnaround maintenance windows.
Norway
Naval procurement specifications from EDA member states drive REACH and RoHS compliance adoption for salt-spray-resistant coatings. Yards in Bergen and Stavanger lead verification system upgrades for autonomous surface vessel programs. The country's maritime cluster is specifying satellite-linked testers for uncrewed fleet remote monitoring.
Marine Electronics Tester Market Competitive Environment
Portfolio diversification dominates the current landscape as established instrumentation groups extend marine-specific calibration capabilities. The vendor base separates into three distinct tiers: diversified electronics conglomerates with RF heritage, specialized maritime equipment suppliers, and regional service contractors. Two strategic archetypes predominate: technology licensors leveraging semiconductor substrate advantages, and integrated service providers bundling hardware with recertification contracts. M&A activity and technology licensing agreements constitute the primary competitive vectors.
Among diversified instrumentation groups, Keysight Technologies and Rohde & Schwarz exemplify the RF heritage archetype, leveraging signal integrity validation capabilities into naval procurement channels. Fluke Corporation occupies a position within the portable diagnostic tier, serving dockside technician workflows through ruggedized handheld platforms. These three entities represent distinct competitive positioning vectors without overlapping segment focus.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Rohde & Schwarz |
| Teledyne Technologies |
| Furuno Electric |
| Parker Hannifin Manufacturing |
| Kongsberg Gruppen |
| IKM Instrutek |
| Nemko |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in South Korea and Japan anchor tier-one supply for high-purity silicon carbide substrates, translating concentrated wafer foundry ownership into disciplined pricing power for marine-grade testers while compressing margins for legacy silicon IGBT assemblers facing input cost volatility.
Pricing Analysis
Volume concentrates in handheld digital multimeters where Mediterranean third-party contractors drive replacement cycles, while margin pools oscilloscope segments serving German and Japanese shipyards with four-channel propulsion diagnostics. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60945 pre-compliant EMC suites from basic dockside units. Pricing pressure stems from REACH and RoHS compliance documentation costs for salt-spray-resistant coatings. Marine technicians exhibit highest price sensitivity, whereas naval procurement specifications from EDA member states tolerate premium positioning for calibrated RF instrumentation.
Supply Chain Analysis
Freight costs for specialized semiconductor substrates from Taiwanese and South Korean foundries feed into landed cost structures for SiC-based tester architectures, with Japanese suppliers commanding logistics premiums for naval-grade 40 GHz RF components. High-purity silicon carbide wafers, IP67-rated salt-spray-resistant enclosures, and calibrated reference standards constitute critical input dependencies. Single-source vulnerability concentrates among specialized wafer foundries serving propulsion diagnostic applications. Distribution runs through shipyard-integrated test bench providers in Germany and South Korea, with aftermarket service contractors in Mediterranean cruise hubs capturing portable instrument flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where raw material concentration and extended type-approval timelines force capital-constrained regional service contractors toward exit or acquisition.
For Market Incumbents: Lock in captive supply arrangements with Taiwanese and South Korean wafer foundries before silicon carbide substrate bottlenecks intensify. Deepen backward integration into salt-spray-resistant enclosure manufacturing to deflect REACH compliance cost pressure from European coating suppliers. Prioritize IEC 60945 pre-certification investments that compress Lloyd's Register approval windows against emerging wireless platform competitors. For New Entrants and Emerging Players: Capture uncrewed surface vessel diagnostic demand in Norwegian and South Korean autonomous fleet programs where incumbent RF heritage players lack satellite-linked remote monitoring portfolios. Target battery-electric propulsion testing integration for hybrid ferry operators in Incheon and Bergen as the most penetrable white-space segment. Lead with pay-per-test service unbundling to displace bundled OEM contracts in Mediterranean cruise ship hubs. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional calibration service contractors in Baltic and Mediterranean port clusters facing margin compression from wireless platform displacement. Long-term viability hinges on positioning for autonomous vessel infrastructure buildout across the analysis window. Monitor type-approval timeline compression from EU Marine Equipment Directive harmonization as the inflection signal for certification-capable asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Supply Agreement | Secures thermal performance advantage for high-voltage propulsion diagnostics against silicon IGBT competitors. |
| IEC 60945 Pre-Certification Investment | Accelerates Lloyd's Register type approval for German and Japanese shipyard procurement cycles. |
| Wireless Platform Integration | Eliminates cable harness complexity for South Korean yard commissioning and uncrewed vessel applications. |
| Calibration Service Unbundling | Captures Mediterranean third-party contractor demand shifting from bundled OEM service contracts. |
| Autonomous Vessel Diagnostic Partnership | Positions for Norwegian satellite-linked remote monitoring specifications in uncrewed surface vessel programs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted with shipyard procurement directors, marine electronics calibration laboratory managers, dockside maintenance contractors, and naval platform engineering leads. IMO SOLAS convention documentation, IEC 60945 and IEC 61162 standard editions, Lloyd's Register type approval records, and EU Marine Equipment Directive alignment notices supplied regulatory traceability. Bottom-up vessel fleet instrumentation counts reconciled against top-down manufacturer shipment disclosures.
Data-stream reconciliation across product type, application workflow, end-user procurement authority, and technology architecture dimensions generated segment-level projections over the analysis window. CAGRs derived from elasticity-adjusted adoption curves for wireless diagnostic protocols and SiC semiconductor penetration rates. Shipyard newbuild schedules from DSME and HHI complexes, hybrid ferry electrification timelines from Incheon operators, and autonomous vessel program milestones from Norwegian maritime clusters informed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon carbide substrate supply disruptions, REACH substance restriction amendments, and classification society type-approval timeline variability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
United States Borescope Market
Test and Measurement
LAN Tester Market
Test and Measurement
Calorimeters Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Failure Analysis Equipment Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Reverberation Chambers Market