

Battery Cell, Module, and Pack Swelling Measurement Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cell, Module, and Pack Swelling Measurement Systems Market Insights
Silicon-anode material substitution is expanding the addressable need for in-situ swelling measurement as electrode volume fluctuation intensifies during charge cycling. ZwickRoell leverages its materials testing heritage to dominate mechanical characterization protocols for next-generation cells. Instron sustains competitive position through precision load-frame integration with displacement sensors. Maccor specializes in battery cyclers that embed thickness monitoring for R&D environments.
Battery cell, module, and pack swelling measurement systems comprise precision instrumentation that quantifies dimensional change in electrochemical energy storage components under operational stress, typically resolving thickness variation to sub-micron accuracy through non-contact sensing modalities. These systems serve critical quality assurance and safety validation functions by detecting electrode delamination, gas evolution, and structural deformation that precede thermal runaway. Laser displacement technology anchors the highest-precision tier for cell-level gauging, while ultrasonic sensing occupies expanding share in module and pack applications where multi-point arrays prove cost-advantaged. Pack expansion detectors command premium pricing due to integration complexity with battery management systems, whereas thickness measurement units face margin compression from commoditization in consumer electronics.
FDA device regulations and NHTSA battery safety protocols in the United States, alongside China's GB standards administered by SAMR, mandate dimensional stability documentation for cells entering transportation and medical applications. The EU Battery Regulation's forthcoming due diligence requirements will extend swelling documentation obligations across the full cell lifecycle. Stakeholders must decide whether to invest in multi-technology platforms or deepen specialization in single-modality systems as application requirements diverge between automotive and stationary storage sectors.
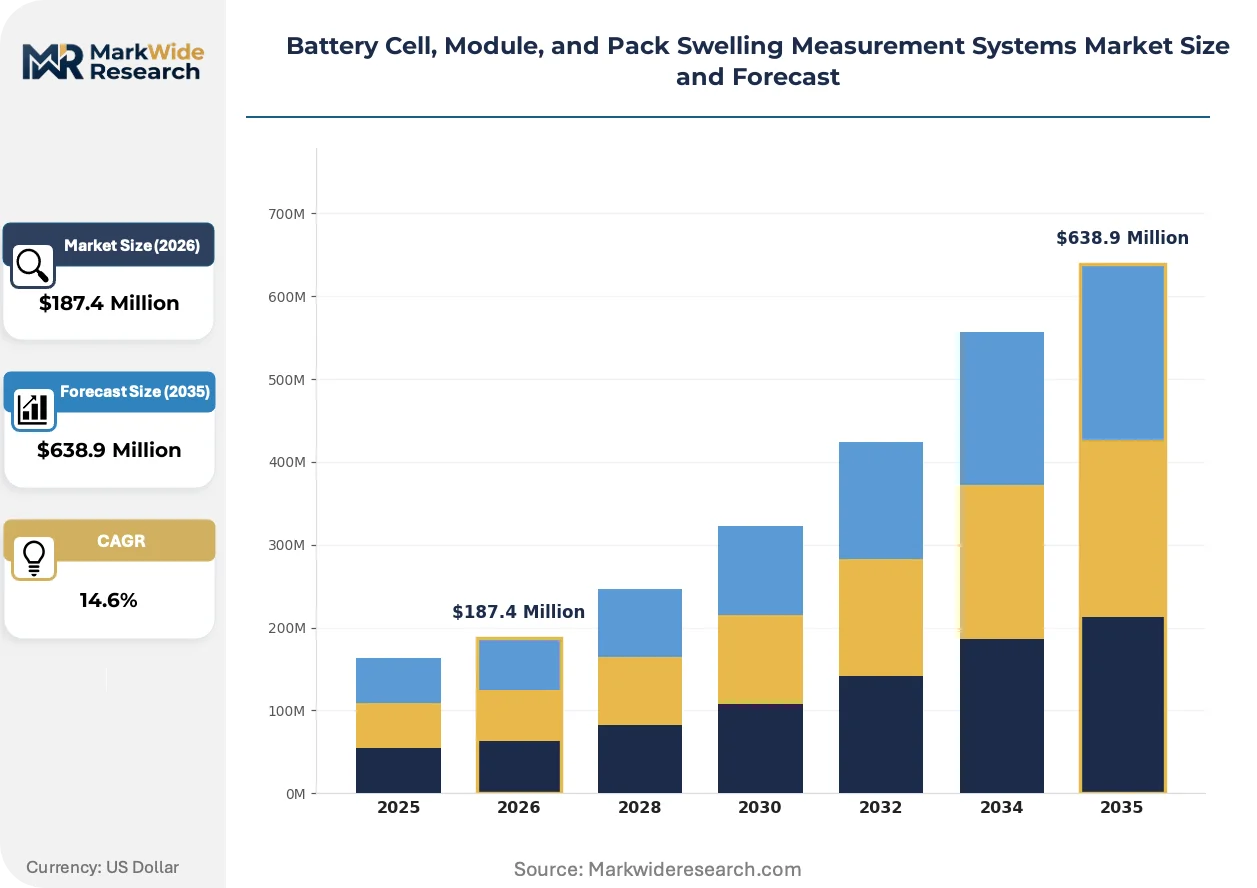
Market Dynamics
Silicon-anode adoption is intensifying dimensional instability in lithium-ion cells, forcing manufacturers to embed real-time swelling monitoring deeper into qualification protocols and production lines.
Growth Catalysts
- EU Battery Regulation:Due diligence mandates extending across full cell lifecycles are compelling manufacturers to document dimensional stability from R&D through end-of-life, expanding instrumentation procurement.
- Electric vehicle testing laboratories:Expansion of validation facilities around Stuttgart and Munich is concentrating demand for multi-point measurement arrays capable of module-level characterization.
- Silicon-anode material substitution:Electrode volume fluctuation during charge cycling is creating addressable need for in-situ thickness monitoring that legacy equipment cannot satisfy.
Market Restraints
- High-precision sensor cost structure:Laser displacement components and sub-micron calibration standards impose capital barriers for mid-tier battery manufacturers scaling pilot lines.
- Supply concentration in German automotive testing:Procurement gravity clustering around Stuttgart-Munich corridor creates geographic dependency risk for instrument vendors without regional service infrastructure.
- Technical limitation in pack integration:Battery management system interfacing complexity slows deployment of expansion detectors despite premium pricing availability.
Strategic Opportunities
- China GB/T standards administration:SAMR's tightening dimensional stability requirements for lithium-ion cells entering transportation applications are opening compliance-driven replacement cycles.
- Stationary storage sector:Grid-scale battery deployments are emerging as a distinct application requiring modified ultrasonic sensing arrays optimized for containerized pack geometries.
- Technology convergence:Integration of mechanical testing load frames with electrochemical cycling equipment is enabling unified R&D workflows that reduce capital duplication.
Industry Challenges
- Metrology talent scarcity:Battery manufacturers face acute shortages of engineers capable of interpreting sub-micron displacement data within electrochemical degradation contexts.
- Certification timeline compression:NHTSA battery safety protocols and FDA device regulations impose overlapping documentation requirements that strain qualification resources.
- Standardization delays:Divergence between ISO mechanical testing standards and IEC battery-specific guidelines creates protocol fragmentation across customer sites.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cell, Module, and Pack Swelling Measurement Systems Market Trends and Innovations
Measurement modalities are bifurcating as automotive qualification demands diverge from stationary storage requirements, with sensing technology selection increasingly determined by integration depth rather than standalone precision.
Laser displacement technology is consolidating its position as the dominant modality for cell-level gauging where sub-micron resolution remains non-negotiable. Automotive OEM qualification laboratories are standardizing on multi-axis laser triangulation systems for silicon-anode validation. This consolidation is compressing market space for contact-based mechanical probes in high-value R&D segments.
REACH substance restrictions and the EU Battery Regulation's carbon footprint disclosure rules are reshaping instrument material selection and supply chain documentation obligations. Manufacturers must now certify sensor housings and cabling for restricted substance compliance. Pack-level system vendors serving European automotive customers are restructuring procurement to capture full material provenance data.
Equipment-as-a-service arrangements are displacing capital purchase models among mid-scale battery startups facing cyclical funding environments. Leasing structures with embedded calibration and software update provisions are gaining traction in North American and European markets. This shift is most visible among solid-state battery ventures prioritizing operational expenditure flexibility over asset ownership.
Battery Cell, Module, and Pack Swelling Measurement Systems Market Segmentation
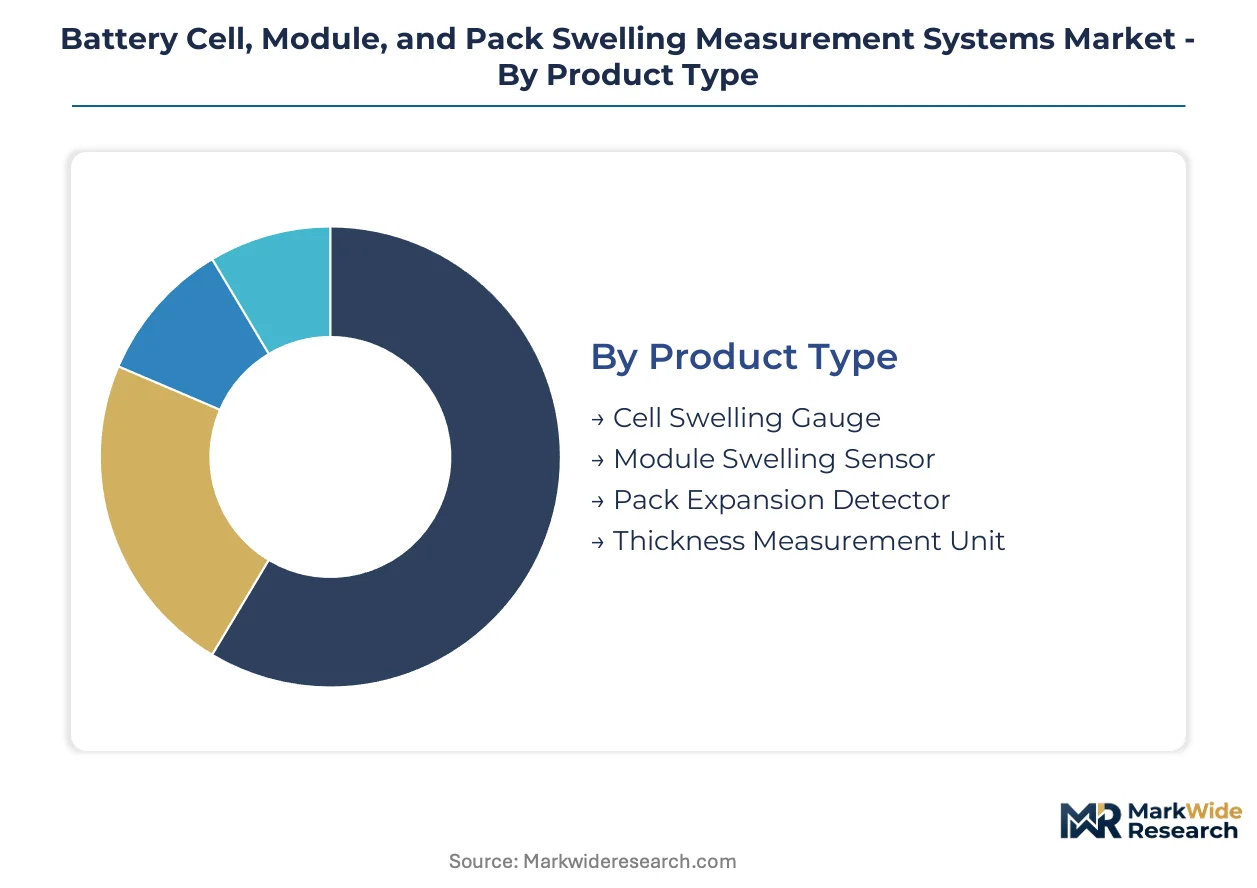
Measurement system selection in this market hinges on integration depth—standalone instruments for R&D qualification versus embedded sensors for production-line monitoring. Procurement patterns diverge sharply between these deployment modes, with pricing and service structures following distinct logics.
Product Type:
Integration depth varies dramatically across product tiers, from benchtop laboratory units to factory-embedded process sensors.
- Cell Swelling Gauge:Benchtop instruments employing laser triangulation or confocal chromatic sensing resolve sub-micron thickness variation in individual cells during formation cycling. Demand clusters in German automotive testing corridors around Stuttgart and Munich, where silicon-anode validation protocols require precise electrode expansion quantification.
- Pack Expansion Detector:Multi-point sensor arrays integrated with battery management systems monitor structural deformation across entire pack architectures. NHTSA battery safety protocols and EU Battery Regulation due diligence requirements are accelerating procurement for transportation applications, though BMS interfacing complexity extends deployment timelines.
- Module Swelling Sensor:Intermediate-scale arrays bridge cell and pack measurement, typically deploying ultrasonic sensing for cost efficiency across 10-20 cell groupings.
- Thickness Measurement Unit:Commoditized displacement sensors for consumer electronics face margin compression as smartphone and laptop manufacturers prioritize cost over precision.
Volume placements concentrate in Cell Swelling Gauge; the faster expansion belongs to Pack Expansion Detector.
Technology:
Cost tier segmentation separates premium metrology from mid-market process control, with modality selection driven by resolution requirements versus integration economics.
- Laser Displacement:Triangulation and confocal chromatic systems deliver sub-micron resolution for R&D and high-value automotive qualification. China's GB/T battery safety standards administered by SAMR are tightening calibration documentation requirements, favoring vendors with traceable metrology chains.
- Ultrasonic Sensing:Piezoelectric arrays penetrate module and pack geometries where optical line-of-sight proves impractical, offering cost-advantaged multi-point monitoring for production environments. Grid-scale energy storage deployments are emerging as a distinct demand vector.
- Capacitive Sensing:Proximity-based measurement suits clean-room cell manufacturing where particulate generation from contact probes is prohibited.
- Optical Imaging:Machine vision approaches extract dimensional data from surface texture analysis, occupying niche applications in defect detection rather than precision gauging.
Revenue gravity sits with Laser Displacement; Ultrasonic Sensing is climbing the fastest.
Application:
Customer maturity varies by application, with electric vehicle testing laboratories demanding full metrology packages while energy storage procurement favors simplified process sensors.
- Electric Vehicle Testing:Validation facilities require multi-axis measurement systems capable of correlating mechanical expansion with electrochemical performance. Equipment-as-a-service arrangements are displacing capital purchases among battery startups facing cyclical funding.
- Energy Storage Systems:Containerized grid-scale batteries need modified ultrasonic arrays optimized for large-format pack geometries and extended operational lifetimes.
- Aerospace Battery Monitoring:FAA and EASA certification protocols impose stringent documentation requirements for aviation-qualified swelling instrumentation.
- Consumer Electronics:High-volume, low-margin procurement of thickness measurement units from smartphone and laptop manufacturers.
Contract value peaks in Electric Vehicle Testing; Energy Storage Systems shows the steepest expansion trajectory.
End User:
Supply concentration shapes vendor strategies, with battery manufacturers representing integrated production demand and research laboratories driving premium instrument specifications.
- Battery Manufacturers:Integrated production environments require inline process sensors with statistical process control integration. REACH substance restrictions and EU Battery Regulation carbon footprint rules are restructuring material provenance documentation obligations.
- Research Laboratories:Academic and national laboratory procurement prioritizes measurement flexibility and publication-grade precision over throughput.
- Quality Control Facilities:Third-party testing houses serving multiple battery customers favor modular platforms with rapid reconfiguration capabilities.
- Automotive Tier-1 Suppliers:Pack integrators demand expansion detectors with pre-validated BMS interfaces to compress qualification timelines.
Installed base dominance rests with Battery Manufacturers; Research Laboratories command the highest per-unit pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle testing laboratories in Germany's automotive corridor concentrate procurement gravity for swelling measurement instrumentation. Chinese battery manufacturers drive volume demand through compliance with tightening GB/T safety standards. Regulatory divergence across major economies is fragmenting vendor certification requirements.
Germany
Stuttgart and Munich anchor Europe's densest cluster of battery validation facilities serving automotive OEMs. The EU Battery Regulation's due diligence mandates are compelling manufacturers to document dimensional stability across full cell lifecycles. Equipment-as-a-service arrangements are displacing capital purchases among mid-scale battery startups in the Baden-Württemberg region.
China
SAMR-administered GB/T battery safety standards are tightening dimensional stability requirements for lithium-ion cells entering transportation applications. Shenzhen and Shanghai host the largest concentrations of cell manufacturers procuring inline process sensors. Domestic vendors are capturing share in mid-tier thickness measurement units as price competition intensifies.
United States
NHTSA battery safety protocols and FDA device regulations impose overlapping documentation requirements that strain qualification resources. Michigan and California concentrate demand from automotive and medical device battery manufacturers. Silicon-anode ventures in the San Francisco Bay Area are driving premium instrument procurement for R&D validation.
South Korea
MFDS pharmaceutical regulations and KSA automotive standards are extending swelling documentation obligations to medical and transportation battery applications. Seoul and Gyeonggi Province host integrated production environments requiring statistical process control integration. Chaebol-affiliated battery manufacturers are deepening backward integration into metrology equipment supply.
Japan
METI industrial standards and JIS certification requirements favor vendors with traceable metrology chains for high-precision applications. Nagoya and Osaka manufacturing belts concentrate demand from automotive Tier-1 suppliers. Solid-state battery ventures are prioritizing operational expenditure flexibility through leasing structures.
Battery Cell, Module, and Pack Swelling Measurement Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision metrology vendors commanding premium positioning in automotive qualification while Asian fabricators capture volume in production-line sensors. The vendor base organizes into three tiers: heritage materials testing houses, battery-specific instrument specialists, and diversified electronics test equipment conglomerates. Dominant competitive moves include technology convergence through load-frame integration and geographic expansion through regional service infrastructure.
Within the heritage testing equipment tier, ZwickRoell and Instron occupy positions exemplifying mechanical characterization heritage applied to electrochemical systems. Maccor represents the battery-specialist archetype, embedding thickness monitoring within cyclers for R&D environments. Among Asia-Pacific-based test equipment fabricators, Chroma ATE and NEWARE sit within the volume-production segment, supplying cost-optimized arrays for manufacturing lines. The competitive dynamic between European precision heritage and Asian manufacturing scale is reshaping procurement patterns across validation and production environments.
| Leading Market Players |
|---|
| ZwickRoell |
| Instron |
| Maccor |
| Chroma ATE |
| HORIBA FuelCon |
| NEWARE |
| IEST |
| Keysight Technologies |
| Arbin Instruments |
| Others |
Pricing and Supply Chain Analysis
German automotive testing laboratories concentrate procurement gravity for high-precision instrumentation, anchoring project-based contracting with embedded calibration service bundles as the dominant pricing model across the swelling measurement systems market.
Pricing Analysis
Volume placements concentrate in commoditized thickness measurement units for consumer electronics, while margins expand in pack expansion detectors where BMS integration complexity supports value-based pricing. Price differentiation separates automotive OEM qualification tiers requiring ISO/IEC traceable metrology chains from mid-tier battery manufacturers sourcing cost-optimized ultrasonic arrays. Pricing pressure stems from domestic vendor competition in China's mid-market segment, where SAMR compliance documentation requirements are standardizing. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement flexibility.
Supply Chain Analysis
China's GB/T standards administration and the EU Battery Regulation's carbon footprint disclosure rules are reshaping sourcing decisions, compelling instrument vendors to certify sensor housings and cabling for restricted substance compliance. Component fabrication concentrates in Germany, Japan, and China, with laser displacement sensors drawing from specialized optical component suppliers in Stuttgart and Nagoya manufacturing belts. Single-source vulnerability persists in sub-micron calibration standards. Distribution runs through direct sales teams for automotive qualification laboratories and regional distributors for production-line sensor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU Battery Regulation's due diligence mandates create a barrier-to-entry moat for vendors with pre-validated metrology chains and full lifecycle documentation capabilities.
For Market Incumbents: Anticipate margin compression in benchtop cell swelling gauges as Chinese domestic vendors capture mid-tier share through price competition. Defend positioning by deepening backward integration into optical component supply and expanding service infrastructure across the Stuttgart-Munich corridor. Certification investment in SAMR-administered GB/T standards documentation represents the priority lever for China market access. For New Entrants and Emerging Players: Digital channel partnerships with battery testing equipment aggregators offer lowest-friction customer acquisition pathways. White-space targets include equipment-as-a-service arrangements for solid-state battery ventures prioritizing operational expenditure flexibility, and modified ultrasonic sensing arrays for grid-scale stationary storage deployments. The most penetrable segment spans mid-scale North American battery startups facing cyclical funding environments. For Investors and Strategic Acquirers: The window for entry favors heritage materials testing houses with electrochemical system adaptation capabilities over pure-play battery instrument specialists. Long-term viability hinges on technology convergence through load-frame integration that reduces capital duplication for R&D customers. The signal to monitor is silicon-anode commercialization velocity, which would accelerate replacement cycles for legacy thickness monitoring equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Convergence Through Load-Frame Integration | Unifies mechanical testing with electrochemical cycling workflows for German automotive laboratories. |
| Regional Service Infrastructure Expansion | Addresses geographic dependency risk in the Stuttgart-Munich procurement corridor. |
| Equipment-as-a-Service Model Deployment | Captures mid-scale battery startups facing cyclical funding in North American markets. |
| Carbon Footprint Supply Chain Documentation | Satisfies EU Battery Regulation material provenance requirements for European automotive customers. |
| Ultrasonic Sensing Array Modification | Targets containerized pack geometries in grid-scale stationary storage deployments. |
Research Methodology
Multi-period observation of silicon-anode validation protocol adoption, equipment procurement patterns at electric vehicle testing laboratories, and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with instrument vendor product managers, battery manufacturer quality directors, automotive OEM validation engineers, and metrology calibration specialists. Secondary validation drew from SAMR GB/T standard publications, EU Battery Regulation draft texts, NHTSA battery safety protocol documentation, SEC filings of listed test equipment manufacturers, and trade customs data for optical component imports. Bottom-up unit placement estimates triangulated against top-down market sizing derived from automotive battery formation capacity expansion announcements.
The input-output matrix framed volume projections across product type, technology modality, application vertical, and end-user segment dimensions, with growth rates derived from elasticity modeling against automotive battery production capacity and stationary storage deployment pipelines. Industry-specific forecast inputs incorporated silicon-anode material substitution curves and EU Battery Regulation implementation phasing across member states.
The model holds under steady regulatory enforcement intensity and continued silicon-anode R&D investment; deviation in standardization timeline delays or commodity lithium pricing collapse would shift instrumentation procurement cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.