
 Latin America Measurement and Test Equipment Market | 2026-2036
Latin America Measurement and Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Measurement and Test Equipment Market Insights
ISO/IEC 17025 accreditation is bifurcating the competitive landscape into certified laboratories and uncertified equipment vendors across Brazil and Mexico. Keysight Technologies leverages its calibration services network to anchor premium positioning in São Paulo's aerospace testing corridors. Rohde & Schwarz GmbH competes through localized spectrum analyzer support for Mexican telecommunications infrastructure rollouts. National Instruments Corporation differentiates via software-defined instrumentation platforms targeting Brazilian educational institutes and research laboratories.
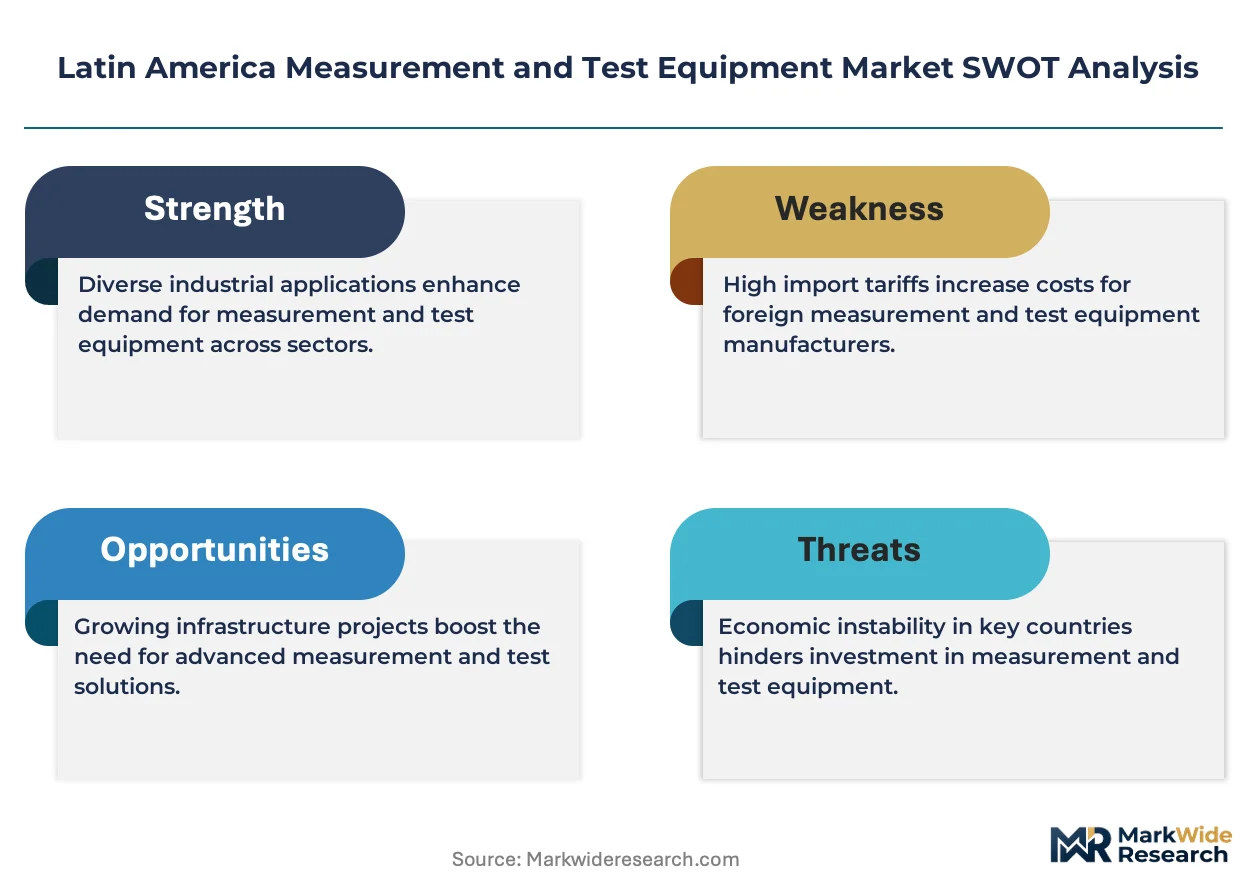
Measurement and test equipment encompasses instruments that quantify electrical, physical, or RF parameters with specified accuracy ranges, including vector network analyzers operating to 110 GHz and digital multimeters with microvolt resolution. These systems verify compliance, debug designs, and certify product performance across manufacturing and R&D workflows. Analyzers and digital technology segments command the deepest margin pools where 5G deployment and semiconductor validation requirements concentrate procurement budgets. Wireless testing applications within the telecommunications vertical represent the fastest-expanding demand category as Brazilian and Mexican carriers expand mid-band infrastructure. Calibrators and analog instruments retain stable replacement cycles among energy sector contractors maintaining grid instrumentation standards.
Brazil's national metrology institute INMETRO mandates traceability chains for industrial measurement devices, while Mexico's ECOCE certification requirements shape electronics waste handling for obsolete test equipment. ANATEL spectrum allocation rules in Brazil and IFT licensing frameworks in Mexico directly determine RF analyzer feature specifications and upgrade cycles. Stakeholders must monitor evolving electromagnetic compatibility mandates and local content requirements as procurement criteria tighten across major Latin American infrastructure programs.
Market Dynamics
ISO/IEC 17025 accreditation requirements are fragmenting the Latin American competitive landscape into certified laboratories and uncertified equipment vendors, forcing procurement criteria shifts across Brazilian aerospace corridors and Mexican electronics clusters.
Growth Catalysts
- 5G Infrastructure Mandates:Brazilian ANATEL spectrum allocations and Mexican IFT licensing frameworks are accelerating RF analyzer upgrade cycles across telecommunications carriers.
- Automotive Emissions Compliance:Brazilian INMETRO traceability chains for industrial measurement devices are compelling metrology investments from vehicle manufacturers adapting to evolving protocols.
- Semiconductor Validation Demand:Precision oscilloscope procurement is concentrating near Tijuana and Guadalajara electronics manufacturing clusters serving North American supply chains.
Market Restraints
- Import Tariff Volatility:Brazilian industrial equipment import duties create cost unpredictability for vector network analyzers above 50 GHz frequency ranges.
- Calibration Infrastructure Gaps:Certified metrology laboratories remain concentrated in São Paulo and Mexico City, limiting service accessibility for interior manufacturing zones.
- Technical Obsolescence Cycles:Digital multimeter and analog instrument replacement demand is compressing as software-defined platforms extend functional lifespans.
Strategic Opportunities
- Educational Institute Modernization:Brazilian federal university laboratories represent underpenetrated demand for software-defined instrumentation platforms with integrated curriculum support.
- Grid Instrumentation Standards:Energy sector contractors across Argentina and Chile are initiating calibrator procurement for smart meter validation programs.
- Remote Calibration Services:Cloud-connected calibration workflows are enabling service delivery to Colombian and Peruvian industrial zones lacking local metrology infrastructure.
Industry Challenges
- RF Engineer Scarcity:Spectrum analyzer operation and mmWave testing expertise remains concentrated among São Paulo and Mexico City technical workforces, constraining deployment velocity.
- Legacy System Integration:Brazilian aerospace testing corridors face protocol translation complexity when interfacing modern vector network analyzers with 1990s-era test fixtures.
- ECOCE Certification Timelines:Mexican electronics waste handling requirements for obsolete test equipment create disposal documentation burdens extending procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Measurement and Test Equipment Market |
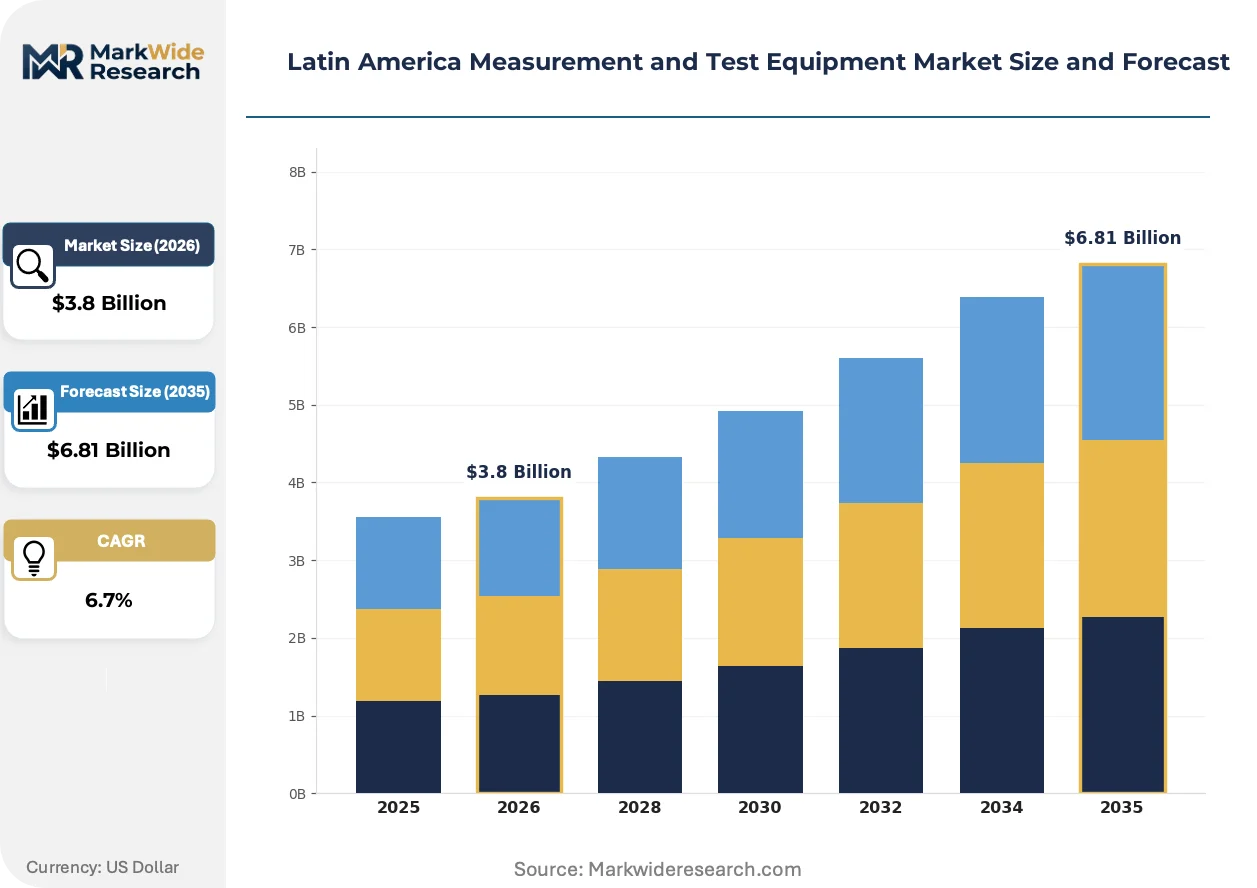
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calibrators, Analyzers, Sensors, Multimeters Industry Vertical: Telecommunications, Aerospace, Electronics, Energy Technology: Analog, Digital, Wireless, Optical End User: Manufacturers, Laboratories, Contractors, Educational Institutes |
| Companies Covered | Anritsu Corporation, Fortive Corporation, Keysight Technologies, Uni-T, Rigol, National Instruments Corporation, Yokogawa Electric Corporation, Instek, Rohde & Schwarz GmbH, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Measurement and Test Equipment Market Trends and Innovations
Software-defined architectures are dissolving traditional hardware boundaries in test equipment, while accreditation mandates and channel consolidation are restructuring how buyers access precision instrumentation across the region.
Modular PXI-based test systems are supplanting benchtop instruments in high-mix manufacturing environments. Mexican electronics contract manufacturers near Tijuana are adopting these platforms for rapid test fixture reconfiguration between product generations. The shift is compressing capital equipment cycles while expanding software licensing revenue pools for instrumentation vendors.
ANATEL electromagnetic compatibility mandates in Brazil are mandating expanded shielding effectiveness testing for telecommunications infrastructure components. Industrial consequence includes accelerated procurement of reverberation chambers and anechoic test facilities among São Paulo-based certification laboratories. Aerospace testing corridors are responding by integrating mmWave antenna characterization into existing environmental test workflows.
Calibration service unbundling from equipment purchase contracts is altering vendor-customer relationships. Brazilian automotive manufacturers are separating initial hardware acquisition from multi-year metrology support agreements, treating calibration as a distinct procurement category. The pattern is most visible among Tier 1 suppliers in São Paulo state seeking ISO/IEC 17025 traceability without vendor lock-in.
Latin America Measurement and Test Equipment Market Segmentation
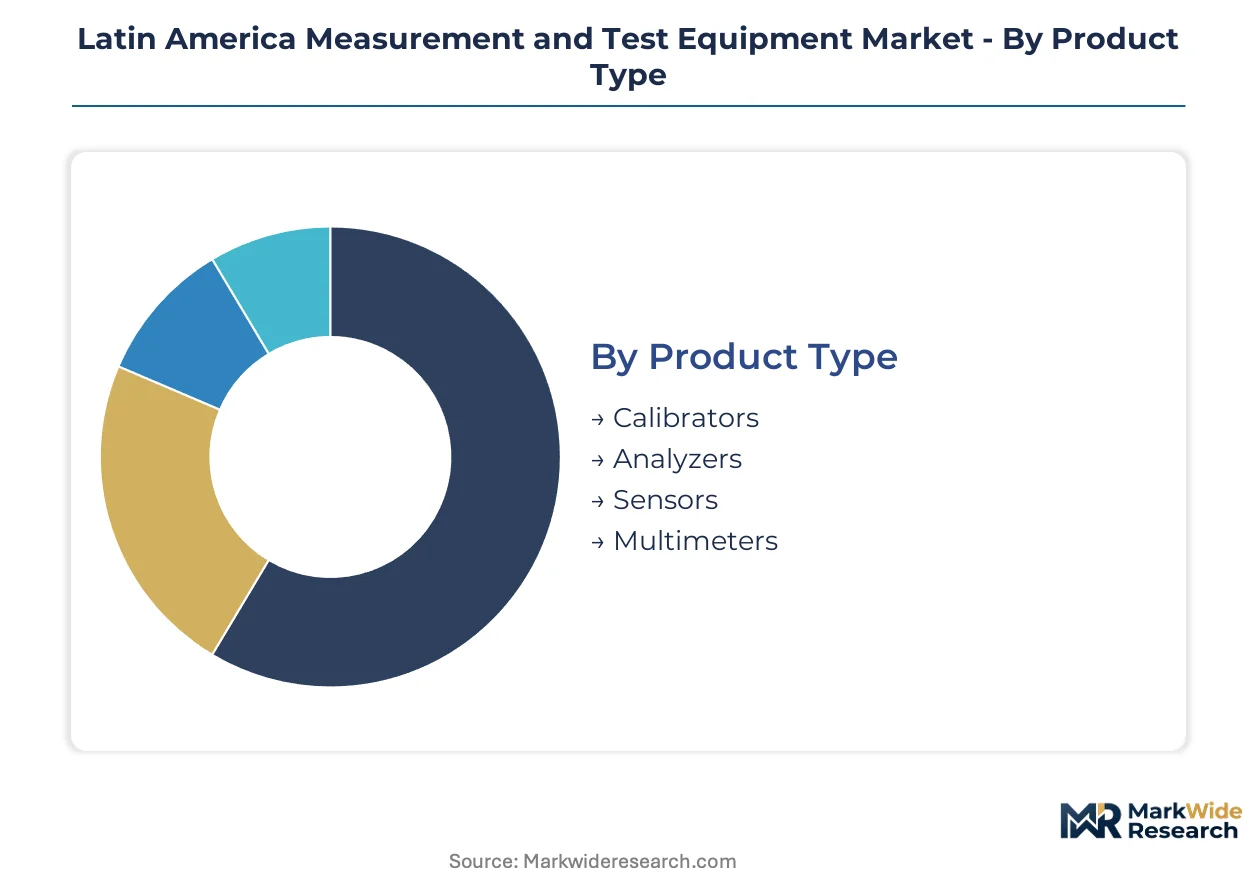
Channel configuration in Latin American test equipment varies sharply by segment complexity. Analyzers and wireless systems flow through certified distributor networks, while calibrators and analog instruments reach buyers via direct manufacturer relationships.
Product Type:
Distribution channels bifurcate between high-service distributors for precision analyzers and volume dealers for replacement-grade instruments.
- Analyzers:Vector network analyzers and spectrum analyzers operate across 9 kHz to 110 GHz ranges with automated calibration routines. São Paulo aerospace testing corridors and Tijuana electronics clusters concentrate procurement as ANATEL and IFT mandates accelerate RF infrastructure validation.
- Calibrators:Precision voltage, current, and temperature reference standards maintain traceability chains for ISO/IEC 17025 accredited laboratories. Brazilian INMETRO mandates and Mexican ECOCE disposal rules shape replacement cycles among energy sector contractors.
- Sensors:Pressure, temperature, and vibration transducers with digital output protocols serve industrial automation retrofits.
- Multimeters:Handheld and benchtop units with microvolt resolution address maintenance workflows across manufacturing floors.
Analyzers dominate installed base value. Calibrators are where expansion concentrates as accreditation requirements tighten.
Industry Vertical:
Application intensity varies by vertical maturity, with telecommunications and electronics commanding premium procurement budgets.
- Telecommunications:5G mid-band deployment and mmWave backhaul testing drive spectrum analyzer and signal generator procurement. Brazilian carriers expanding under ANATEL spectrum allocations and Mexican operators under IFT licensing frameworks represent concentrated demand pockets.
- Electronics:Contract manufacturers near Guadalajara and Tijuana deploy precision oscilloscopes for semiconductor validation serving North American supply chains. High-mix production environments favor modular PXI-based test systems over discrete benchtop instruments.
- Aerospace:Environmental test chambers and antenna characterization systems serve certification laboratories in São Paulo state corridors.
- Energy:Smart meter validation programs and grid instrumentation standards drive calibrator demand among Argentine and Chilean contractors.
Telecommunications anchors current procurement volume. Electronics manufacturing is climbing the fastest as nearshoring accelerates.
Technology:
Technology selection tracks customer sophistication, with digital and wireless platforms displacing legacy analog architectures.
- Digital:Software-defined instrumentation platforms with FPGA-based signal processing enable remote reconfiguration without hardware replacement. Brazilian federal university laboratories and Mexican research institutes represent underpenetrated demand for curriculum-integrated systems.
- Wireless:RF test systems spanning sub-6 GHz and mmWave bands address 5G NR validation requirements. Brazilian ANATEL electromagnetic compatibility mandates and Mexican IFT infrastructure rules directly determine feature specifications.
- Analog:Traditional benchtop instruments with discrete component architectures retain stable replacement cycles in cost-sensitive maintenance applications.
- Optical:Fiber optic test equipment with OTDR and power meter functionality serves telecommunications infrastructure deployment.
Digital platforms command the steepest expansion trajectory. Analog retains residual share in interior manufacturing zones with limited technical workforce depth.
End User:
Buyer type determines service bundling preferences, with laboratories separating calibration contracts and manufacturers seeking integrated support.
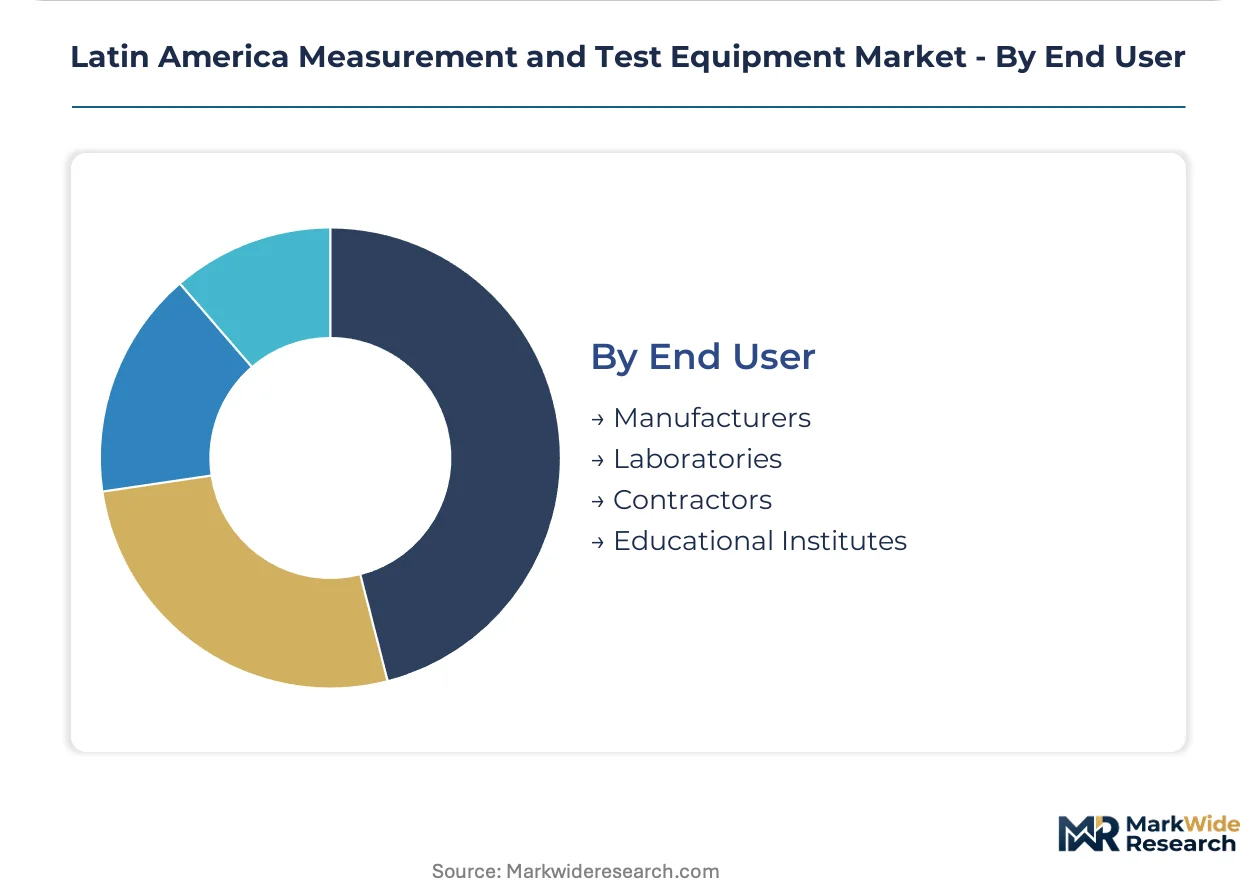
- Manufacturers:Automotive OEMs and Tier 1 suppliers in São Paulo state pursue ISO/IEC 17025 traceability without vendor lock-in, unbundling hardware acquisition from multi-year metrology agreements. Emissions compliance investments dominate capital allocation.
- Laboratories:Certification bodies and independent testing facilities concentrate in São Paulo and Mexico City, creating calibration infrastructure gaps for interior zones.
- Contractors:Energy sector field service organizations across Argentina and Chile initiate calibrator procurement for smart meter deployment programs.
- Educational Institutes:Brazilian federal universities represent modernization demand for software-defined platforms with integrated curriculum modules.
Manufacturers dominate current procurement value. Educational institutes are where greenfield expansion concentrates as federal laboratory budgets release.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANATEL spectrum allocation rules and IFT licensing frameworks are redirecting capital toward telecommunications testing infrastructure across the region's two largest economies.
Brazil
Automotive emissions compliance investments from São Paulo-based OEMs are accelerating metrology procurement. INMETRO mandates traceability chains for industrial measurement devices used in vehicle certification. Aerospace testing corridors in São Paulo state concentrate demand for vector network analyzers serving environmental test laboratories.
Mexico
Electronics contract manufacturers near Tijuana and Guadalajara are deploying precision oscilloscopes for semiconductor validation. ECOCE certification requirements shape disposal protocols for obsolete test equipment. Northern border manufacturing clusters favor modular PXI-based systems for rapid test fixture reconfiguration between product generations.
Argentina
Energy sector contractors are initiating calibrator procurement for smart meter validation programs. The national electricity regulator enforces grid instrumentation standards for distribution network modernization. Buenos Aires and Córdoba industrial zones concentrate demand for precision voltage reference standards.
Chile
Mining automation retrofits are driving sensor procurement for pressure and vibration monitoring applications. The national energy commission mandates calibration protocols for grid-connected renewable generation assets. Santiago metropolitan region anchors demand for industrial automation test equipment.
Colombia
Telecommunications infrastructure rollout is creating demand for spectrum analyzers serving mid-band 5G deployment. The national spectrum agency regulates RF equipment certification for carrier network expansion. Bogotá and Medellín technical service providers are adopting cloud-connected calibration workflows to address interior zone accessibility gaps.
Latin America Measurement and Test Equipment Market Competitive Landscape
Player mix skews toward diversified instrumentation conglomerates with calibration service networks. Market structure concentrates around three tiers: premium-tier vendors with accreditation-anchored positioning, mid-tier specialists in modular platforms, and value-tier suppliers of replacement-grade instruments. Strategic moves center on unbundling calibration contracts from hardware sales and expanding software licensing revenue pools.
Among diversified technology conglomerates, Keysight Technologies and Fortive Corporation exemplify premium-tier positioning through service-network density. Rohde & Schwarz GmbH occupies a specialist position in RF test systems. National Instruments Corporation represents the modular platform archetype targeting educational and research laboratory modernization. These three anchors illustrate how vendor strategies diverge across certification-heavy versus software-defined market vectors.
| Leading Market Players |
|---|
| Anritsu Corporation |
| Fortive Corporation |
| Keysight Technologies |
| Uni-T |
| Rigol |
| National Instruments Corporation |
| Yokogawa Electric Corporation |
| Instek |
| Rohde & Schwarz GmbH |
| Others |
Pricing and Supply Chain Analysis
ISO/IEC 17025 accreditation requirements gate both supplier qualification and price differentiation across Latin American test equipment markets, compressing margins for uncertified vendors while anchoring premium positioning for accredited laboratories in São Paulo and Mexico City corridors.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO/IEC 17025-accredited instruments commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects traceability chain depth, after-sales calibration bundling, and brand-origin positioning. Cost compression in economy-tier multimeters is intensifying because Brazilian import tariff volatility erodes landed cost predictability. Contract manufacturers in Tijuana electronics clusters exhibit highest price sensitivity, while aerospace certification laboratories in São Paulo state demonstrate lowest sensitivity due to mandate-driven procurement.
Supply Chain Analysis
Extended lead times for vector network analyzers above 50 GHz frequency ranges have compressed inventory buffers across Brazilian distribution channels. Manufacturing concentration rests on Germany, United States, and Japan for precision RF instrumentation, with China supplying replacement-grade handheld multimeters and portable oscilloscopes. Critical component dependencies include GaAs semiconductors for mmWave front-ends, precision voltage references for calibrator accuracy, and FPGA modules for software-defined platforms. Single-source vulnerability for 110 GHz test heads creates procurement risk for São Paulo aerospace corridors. Distribution runs through certified distributor networks for analyzers and direct manufacturer relationships for calibrators and analog instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where ISO/IEC 17025 accreditation creates switching costs that lock buyers into established calibration service networks and resist vendor displacement.
For Market Incumbents: Fortify service-network density in secondary Brazilian manufacturing zones beyond São Paulo state, where calibration infrastructure gaps create vulnerability to remote calibration challengers. Deepen backward integration into software-defined platform development to capture recurring licensing revenue from educational institute modernization programs. Prioritize certification investment ahead of anticipated electromagnetic compatibility mandate expansions under ANATEL and IFT frameworks.
For New Entrants and Emerging Players: Remote calibration service gaps in Colombian and Peruvian interior zones offer white-space entry points where cloud-connected workflows bypass fixed laboratory infrastructure requirements. Target Argentine and Chilean energy sector contractors initiating smart meter validation programs, as these buyers prioritize cost efficiency over brand heritage. Deploy direct-to-contractor digital channels with rapid turnaround guarantees to differentiate from incumbent distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined instrumentation sub-segments, shifting value capture toward recurring revenue models and away from hardware-heavy balance sheets. Acquisition target archetype: modular PXI-platform specialists with established curriculum integration in Brazilian federal university systems. Signal to watch: ANATEL and IFT spectrum allocation announcements indicating RF analyzer upgrade cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Unbundling | São Paulo automotive Tier 1 suppliers now treat metrology as distinct procurement category separate from hardware. |
| Modular PXI Platform Adoption | Tijuana contract manufacturers compress capital cycles through rapid test fixture reconfiguration capabilities. |
| Remote Calibration Workflow Deployment | Bogotá technical service providers address interior zone accessibility gaps via cloud-connected infrastructure. |
| Educational Institute Curriculum Integration | Brazilian federal universities represent underpenetrated demand for software-defined instrumentation with embedded training modules. |
| RF Shielding Effectiveness Testing Expansion | ANATEL electromagnetic compatibility mandates accelerate reverberation chamber procurement among certification laboratories. |
Research Methodology
A standing panel of metrology laboratory directors, OEM test engineers, distributor technical sales leads, and calibration service managers provided ongoing calibration against secondary data trends. Primary fieldwork combined structured interviews with procurement officers at São Paulo aerospace testing corridors and Tijuana electronics manufacturing clusters. Secondary validation drew from INMETRO regulatory filings, ANATEL spectrum allocation records, IFT licensing databases, and customs trade data for industrial equipment imports. Bottom-up demand aggregation across product segments and top-down macroeconomic constraint checks ensured analytical consistency.
External benchmark validation against semiconductor capital expenditure cycles and telecommunications infrastructure deployment timelines confirmed projection coherence across the analysis window. Segmentation modeling spanned product type, industry vertical, technology architecture, and end-user category, with additional dimensioning by accreditation status and geographic cluster. CAGRs derived from fitted growth curves applied to base-year sizing, cross-referenced against carrier 5G rollout schedules and automotive emissions compliance deadlines.
Underlying assumptions cover regulatory mandate enforcement continuity, import tariff regime stability, and technical workforce availability, with deviation risk concentrated in electromagnetic compatibility standard acceleration and ECOCE certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Signal Generator Market
Test and Measurement
Metrology Services Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Handheld Digital Multimeter Market