
 Digital Depth Gauges Market | 2026-2036
Digital Depth Gauges Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Depth Gauges Market Insights
Precision-grade digital depth gauges is bifurcating the competitive landscape between metrology specialists and diversified industrial toolmakers. Mitutoyo leverages its Japanese manufacturing scale to dominate high-accuracy electronic gauge supply for automotive quality control. Starrett sustains brand strength across North American distribution channels for mechanical and hybrid depth measurement instruments. Hexagon competes through technology leadership in laser-based depth sensing integrated with its broader coordinate measurement ecosystems.
Digital depth gauges are electromechanical or optoelectronic instruments that measure vertical displacement, recess depth, or step height with resolutions typically reaching 0.01 mm or finer, employing capacitive, inductive, or time-of-flight sensing principles for dimensional verification in machined components. Electronic product types lead unit shipments in manufacturing quality control where ISO 9001 traceability requirements mandate calibrated digital readouts, while ultrasonic variants represent the fastest-growing category in construction material testing due to their non-destructive penetration of concrete and composite substrates. Smart technology integration is displacing analog gauges in aerospace surface inspection applications where Bluetooth-enabled data logging feeds directly into statistical process control systems.
FDA device manufacturing standards and ISO 17025 calibration accreditation shape product specifications for medical implant machining suppliers in the United States. EMA quality system regulations and EU AI Act documentation requirements are accelerating smart gauge adoption among European pharmaceutical equipment manufacturers. Japan's METI standards for measurement traceability and South Korea's MFDS medical device production rules reinforce demand for certified digital depth measurement across precision industries. Stakeholders must monitor how evolving cybersecurity mandates for connected industrial instruments affect smart gauge certification pathways and retrofit timelines.
Market Dynamics
Bluetooth-enabled smart depth gauges are compressing replacement cycles across aerospace and automotive quality control networks, forcing metrology vendors to reconfigure service revenue models around data subscriptions rather than hardware replacement.
Growth Catalysts
- EMA Quality System Mandates:European pharmaceutical equipment manufacturers face accelerated documentation requirements under EU AI Act provisions, pulling certified digital gauges into validation protocols for implant machining lines.
- Non-Destructive Testing Expansion:Ultrasonic depth sensing penetrates concrete and composite substrates in construction material testing, opening unit demand beyond traditional machined-metal applications.
- Japan-South Korea Precision Clusters:METI traceability standards and MFDS medical device rules concentrate procurement authority in certified gauge suppliers serving automotive and semiconductor equipment tiers.
Market Restraints
- Calibration Infrastructure Concentration:ISO 17025-accredited laboratories cluster in Germany, Japan, and the United States, creating logistics friction for buyers in Brazil, India, and Southeast Asia.
- Silicon Supply Tightness:Capacitive sensing chips face allocation pressure from automotive and consumer electronics demand, compressing margins on entry-level electronic gauge models.
- Analog Gauge Substitution Resilience:Mechanical depth gauges retain cost advantage in construction and maintenance applications where battery dependency creates field-reliability concerns.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO medical device rules and PLI scheme incentives attract gauge suppliers to serve domestic implant machining capacity expansion.
- Laser-Bluetooth Convergence:Time-of-flight sensing integrated with wireless data logging creates premium positioning for aerospace surface inspection applications requiring real-time SPC feed.
- Direct OEM Channel Development:Gauge vendors bypass distribution layers to embed calibration and firmware update services into long-term machining center supply contracts.
Industry Challenges
- Cybersecurity Certification Complexity:Connected industrial instruments face evolving documentation requirements under EU AI Act and FDA software validation guidance, extending product launch timelines.
- Metrology Technician Scarcity:ISO 17025 calibration competency gaps in emerging manufacturing regions constrain aftermarket service expansion and customer training revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Depth Gauges Market |
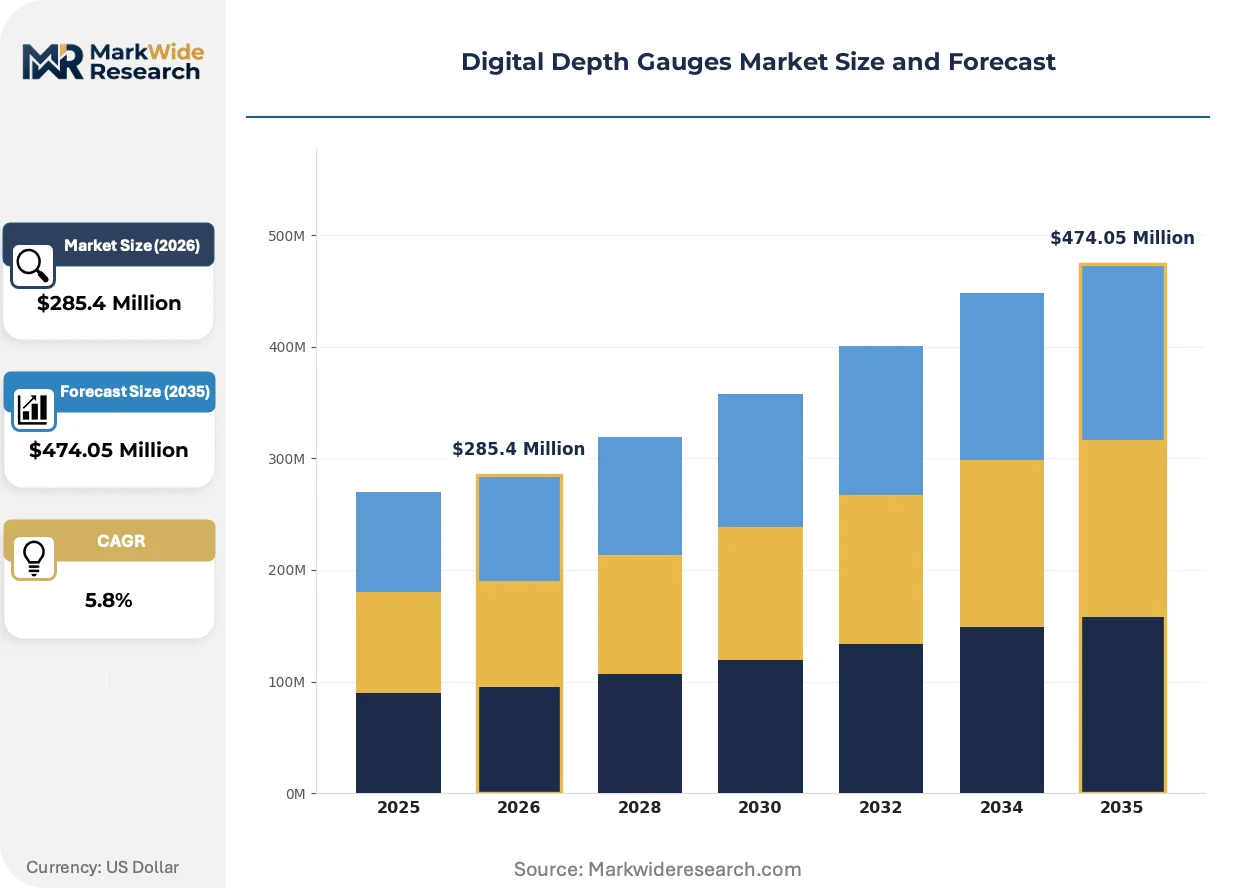
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Ultrasonic, Laser, Mechanical End User: Manufacturing, Construction, Automotive, Aerospace Technology: Digital, Analog, Hybrid, Smart Application: Quality Control, Depth Measurement, Surface Inspection, Material Testing |
| Companies Covered | Mitutoyo, Starrett, Hexagon, Mahr, MICROTECH, Beijing TIME High Technology, Sylvac, Tesa, FACOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Depth Gauges Market Trends and Innovations
Sensor fusion architectures and wireless connectivity protocols are redefining how depth measurement data flows into manufacturing execution systems, collapsing the boundary between standalone gauges and integrated quality infrastructure.
Bluetooth-enabled smart depth gauges is displacing analog and basic electronic models in aerospace surface inspection workflows. Boeing and Airbus tier suppliers in Germany and France now specify wireless data logging as standard for statistical process control integration. This displacement compresses the addressable market for mechanical gauge specialists while expanding software and calibration service attach rates for electronics-capable vendors.
EU AI Act documentation requirements and EMA quality system regulations are tightening validation protocols for pharmaceutical equipment manufacturers. Smart gauges with embedded audit trails and encrypted data transmission now qualify as critical subcomponents in implant machining lines. European gauge suppliers are reengineering firmware architectures to satisfy algorithmic transparency mandates before 2025 enforcement deadlines.
After-sales service unbundling is fragmenting procurement decisions across automotive quality departments. German and Japanese OEMs now separate gauge hardware acquisition from calibration contract negotiation, compressing upfront equipment margins while extending vendor-customer relationship duration. Tier-one suppliers favor multi-year metrology service agreements that bundle depth gauge maintenance with coordinate measurement machine calibration.
Digital Depth Gauges Market Segmentation
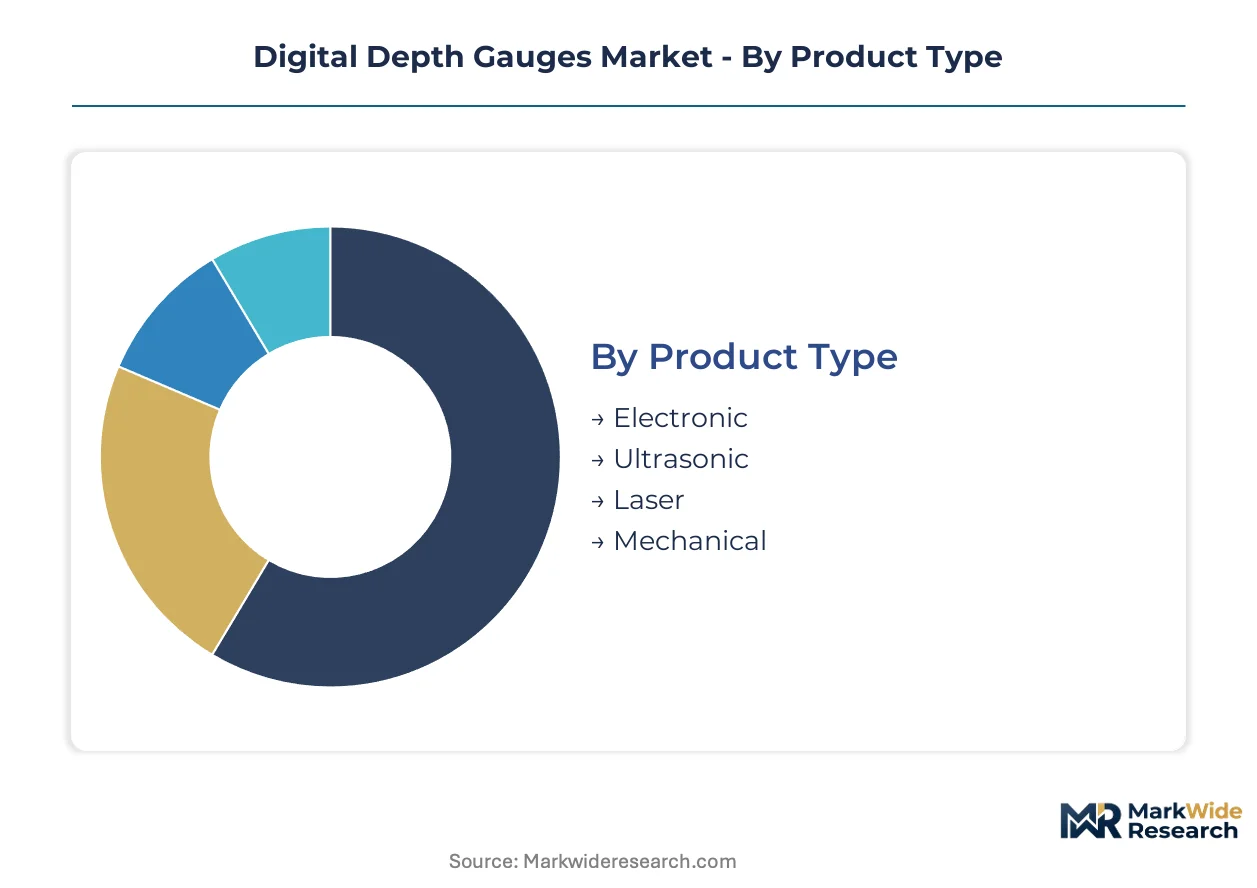
Segmentation in digital depth gauges reveals how sensing technology and end-use requirements fragment procurement patterns. Buyers in precision manufacturing prioritize traceable digital readouts, while construction operators balance cost against field durability.
Product Type:
Mechanical gauges face the most acute substitution pressure as Bluetooth-enabled alternatives capture aerospace and automotive validation workflows.
- Electronic:Capacitive and inductive sensing architectures deliver 0.01 mm resolution for ISO 9001-compliant dimensional verification. Demand concentrates in German automotive quality control networks where EMA documentation mandates calibrated digital readouts for implant machining suppliers.
- Ultrasonic:Time-of-flight principles penetrate concrete and composite substrates without surface contact. Construction material testing in Japan and South Korea drives procurement as METI traceability standards extend to non-destructive evaluation protocols.
- Laser:Triangulation and confocal methods achieve sub-micron accuracy for semiconductor wafer step height measurement.
- Mechanical:Vernier and dial mechanisms retain cost advantage in maintenance applications where battery dependency creates field-reliability concerns.
Electronic variants retain volume leadership; Ultrasonic holds the steepest expansion curve.
End User:
Cost tier stratification separates premium metrology investment from commoditized measurement procurement.
- Manufacturing:Machining centers and fabrication lines require continuous in-process depth verification. Japanese precision clusters under METI standards concentrate demand for certified gauges serving automotive and semiconductor equipment tiers.
- Automotive:Powertrain and chassis quality departments mandate SPC-integrated measurement for ISO/TS 16949 compliance. German OEMs now separate hardware acquisition from multi-year calibration contracts, compressing upfront equipment margins.
- Aerospace:Surface inspection for turbine blades and airframe components demands laser-based depth sensing with real-time data logging.
- Construction:Concrete thickness and rebar cover measurement favors ultrasonic penetration over mechanical contact methods.
Manufacturing commands the largest procurement volume; Aerospace exhibits the most rapid technology upgrade cycles.
Technology:
Application maturity determines where hybrid architectures displace pure analog or fully digital implementations.
- Smart:Bluetooth-enabled gauges with encrypted audit trails feed directly into manufacturing execution systems. EU AI Act and FDA software validation requirements are redefining firmware architecture for pharmaceutical equipment manufacturers.
- Digital:Standalone electronic readouts without wireless connectivity serve cost-sensitive quality departments. South Korean MFDS medical device rules reinforce demand for certified digital measurement across precision industries.
- Hybrid:Mechanical sensing with electronic display bridges calibration infrastructure gaps in emerging manufacturing regions.
- Analog:Pure mechanical indicators persist where electromagnetic interference or extreme temperatures compromise electronic reliability.
Digital technology maintains installed base dominance; Smart configurations are climbing the fastest as connectivity mandates proliferate.
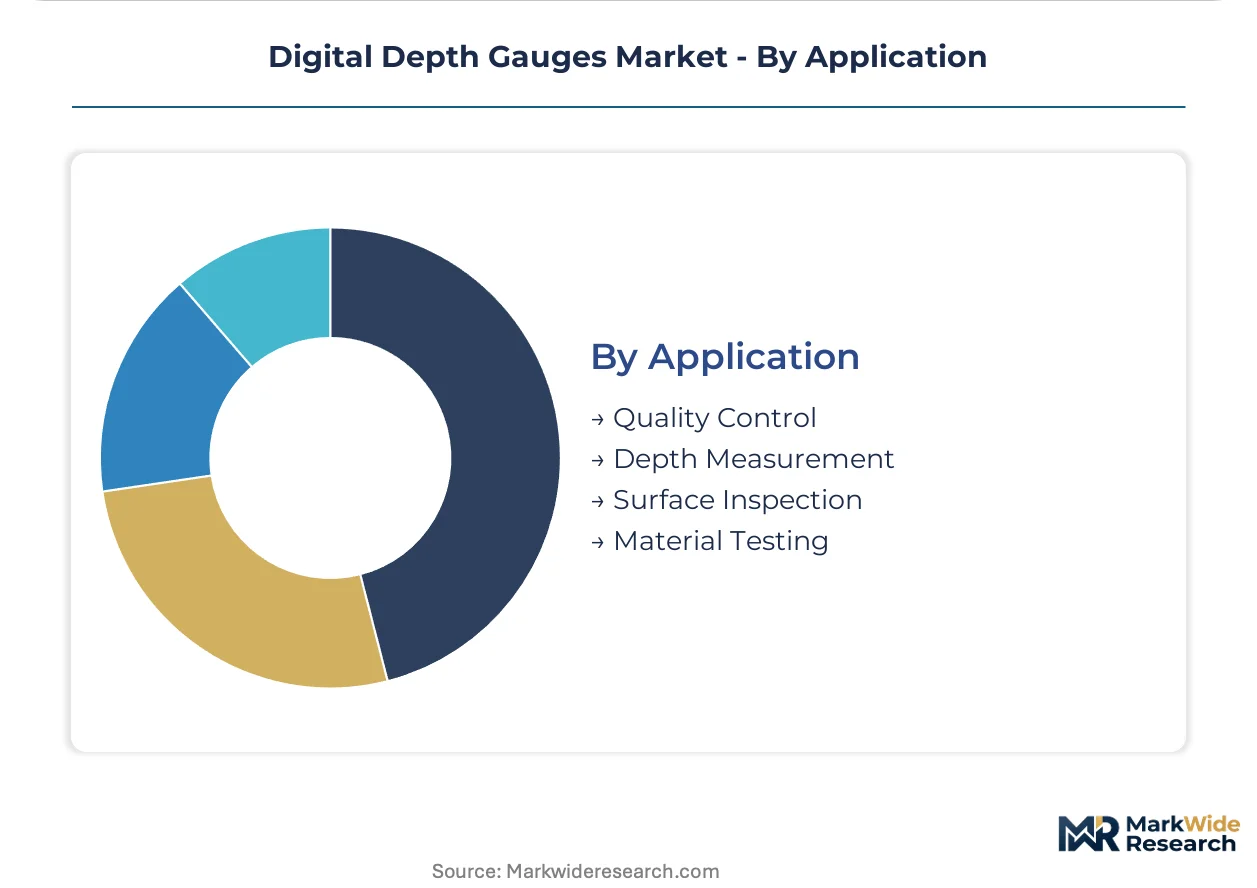
Application:
Customer type fragmentation separates capital-intensive inline systems from portable spot-check instrumentation.
- Quality Control:Statistical process control integration demands calibrated, traceable measurement with automated data capture. Boeing and Airbus tier suppliers in Germany specify wireless logging as standard for aerospace surface inspection workflows.
- Material Testing:Non-destructive evaluation of concrete, composites, and coatings requires penetration capabilities beyond contact methods. Ultrasonic depth sensing is expanding unit demand beyond traditional machined-metal applications.
- Surface Inspection:Step height and recess depth verification for semiconductor and medical implant machining.
- Depth Measurement:General-purpose vertical displacement reading across maintenance and field service contexts.
Quality Control anchors revenue concentration; Material Testing shows the strongest growth momentum as construction applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace manufacturers export precision-machined turbine components to French and Spanish final assembly lines, creating cross-border demand for certified measurement instruments that satisfy EMA documentation requirements.
Germany
Automotive powertrain quality departments and pharmaceutical equipment manufacturers drive procurement of smart depth gauges with encrypted audit trails. EMA quality system regulations and EU AI Act provisions mandate algorithmic transparency in firmware architectures. Stuttgart and Munich precision machining clusters anchor demand from tier-one suppliers serving Airbus and automotive OEMs.
United States
Medical implant machining suppliers and FDA-regulated device manufacturers require ISO 17025-calibrated digital readouts for dimensional verification. FDA software validation guidance shapes specifications for connected industrial instruments. Greater Boston and Minneapolis-St. Paul medical device corridors concentrate procurement authority among certified gauge vendors.
Japan
Automotive and semiconductor equipment tiers under METI traceability standards demand high-accuracy electronic gauges for in-process quality control. JIS standards and national measurement traceability rules reinforce procurement of certified instruments. Nagoya and Osaka precision manufacturing belts dominate domestic consumption of capacitive and inductive sensing architectures.
South Korea
Semiconductor wafer fabrication and automotive quality networks require SPC-integrated measurement under MFDS medical device production rules. National standards for measurement traceability extend to non-destructive evaluation protocols. Suwon and Gwangju precision clusters concentrate demand for ultrasonic depth sensing in construction material testing applications.
India
Domestic pharmaceutical manufacturing expansion under CDSCO medical device rules and PLI scheme incentives attracts gauge suppliers to implant machining capacity buildouts. Central government production-linked incentives reshape procurement patterns for certified digital measurement. Ahmedabad and Hyderabad pharmaceutical corridors emerge as concentrated demand nodes for traceable depth verification instruments.
Digital Depth Gauges Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and calibration service bundling. The vendor base separates into three tiers: multinational metrology platforms with coordinate measurement ecosystems, diversified industrial toolmakers with distribution scale, and regional specialists serving national certification requirements. Dominant competitive moves include M&A to acquire sensor fusion capabilities and long-term service contract bundling that compresses upfront hardware margins.
Within the precision metrology tier, Mitutoyo and Starrett exemplify contrasting geographic anchoring strategies. Mitutoyo occupies a position representing Japanese manufacturing scale in high-accuracy electronic gauge supply. Starrett anchors North American distribution strength across mechanical and hybrid depth measurement instruments. Hexagon sits within the technology-integrated archetype, competing through laser-based depth sensing convergence with broader coordinate measurement ecosystems.
| Leading Market Players |
|---|
| Mitutoyo |
| Starrett |
| Hexagon |
| Mahr |
| MICROTECH |
| Beijing TIME High Technology |
| Sylvac |
| Tesa |
| FACOM |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for ISO 17025-certified capacitive sensing modules concentrate pricing power among German and Japanese suppliers serving automotive quality networks. Inventory buffers at Stuttgart and Nagoya precision clusters insulate tier-one gauge vendors from silicon allocation volatility while compressing margins on entry-level electronic models sourced from distributed Asian assembly.
Pricing Analysis
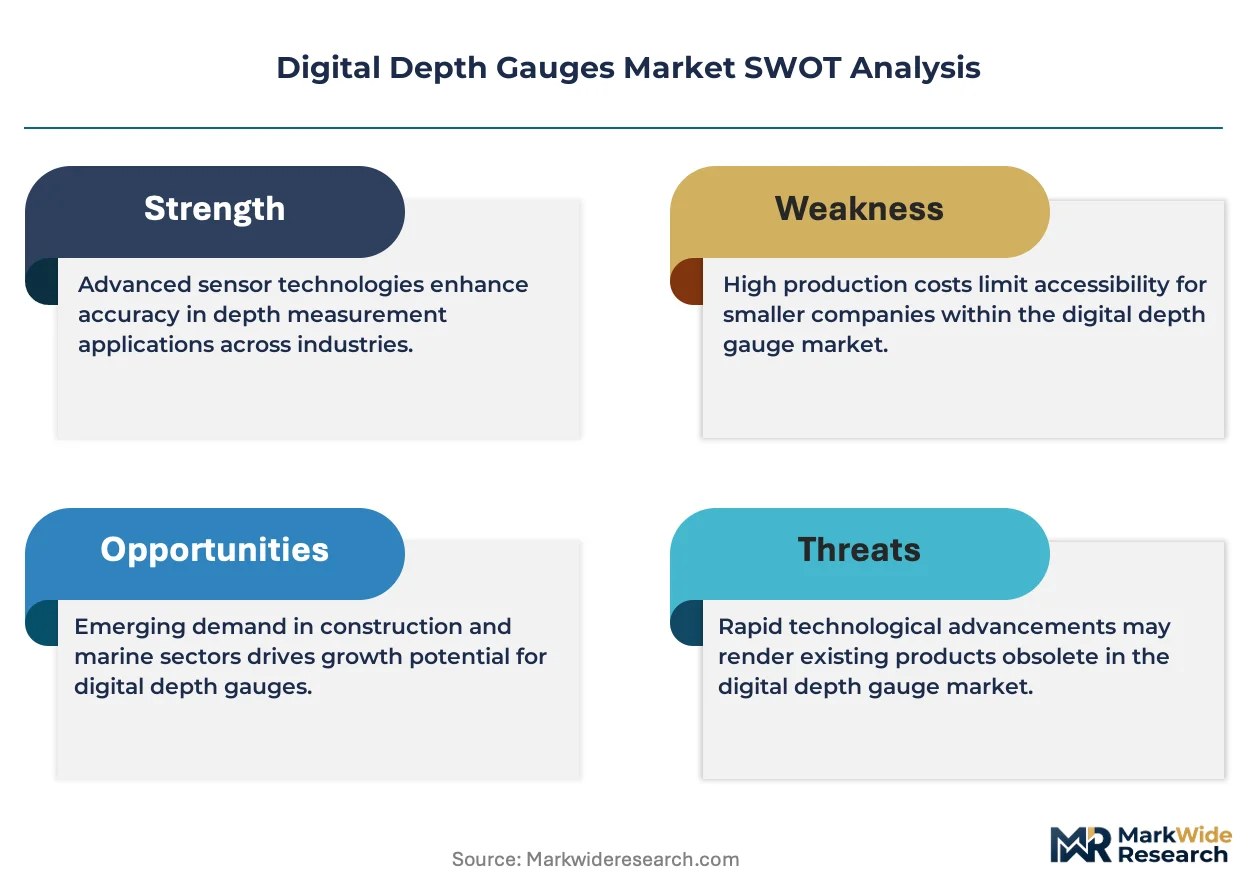
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in digital depth gauge procurement. Price differentiation rests on certification grade—ISO 17025-accredited units command substantial premiums over factory-calibrated alternatives—and after-sales service bundling that extends contract duration. Pricing pressure stems from silicon supply tightness redirecting foundry capacity toward automotive and consumer electronics. Small machine shops and maintenance contractors exhibit highest price sensitivity, while aerospace tier suppliers prioritize traceability over unit cost.
Supply Chain Analysis
Shanghai-to-Rotterdam container transit chokepoints amplify logistics friction for calibration equipment imports into European pharmaceutical manufacturing corridors. Component sourcing concentrates in Japan, Germany, and Taiwan for capacitive sensing chips, precision-ground measuring rods, and Bluetooth module assemblies. Supply chain risk centers on single-source vulnerability for sub-micron inductive sensor substrates. Distribution runs through authorized metrology distributors with ISO 17025-accredited service depots, though direct OEM channel development is displacing traditional wholesale layers in automotive and aerospace procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled smart gauges are accelerating substitution cycles that compress hardware replacement revenue for analog and basic electronic specialists. Incumbents must navigate this displacement by reconfiguring business models around data subscriptions and calibration services rather than unit sales.
For Market Incumbents: Fortify firmware architecture investment to satisfy EU AI Act algorithmic transparency mandates before enforcement deadlines tighten. Acquire ultrasonic sensing capabilities through targeted technology licensing to capture construction material testing expansion. Vertical integration into captive calibration laboratory networks in India and Southeast Asia defends against ISO 17025 infrastructure concentration risks.
For New Entrants and Emerging Players: Aftermarket service unbundling in German and Japanese automotive quality departments creates entry space for calibration-only specialists without gauge manufacturing assets. Target Indian pharmaceutical manufacturing corridors under CDSCO rules where domestic implant machining capacity lacks certified measurement infrastructure. Pursue direct OEM channel partnerships that embed firmware update services into long-term machining center supply contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart gauge sub-segments as software development displaces precision mechanical fabrication. Five-to-ten-year viability favors vendors with installed base scale for recurring calibration revenue rather than hardware shipment dependence. Acquire sensor fusion specialists with time-of-flight laser capabilities integrated into coordinate measurement ecosystems. Monitor EU AI Act cybersecurity certification timelines as inflection indicator for product launch velocity spreads between compliant and non-compliant vendor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Firmware Architecture Investment | EU AI Act compliance separates viable aerospace suppliers from excluded legacy vendors. |
| Calibration Laboratory Network Expansion | ISO 17025 infrastructure in India and Brazil captures pharmaceutical manufacturing localization. |
| Ultrasonic Sensing Capability Acquisition | Non-destructive testing protocols under METI standards open construction material testing demand. |
| Direct OEM Channel Development | Bypassing distribution layers embeds vendors into long-term automotive quality contracts. |
| Sensor Fusion Technology Licensing | Laser-triangulation convergence with Bluetooth data logging secures aerospace surface inspection positioning. |
Research Methodology
Operator-level perspectives from quality control managers, metrology laboratory directors, OEM procurement specialists, and aftermarket service heads anchored the qualitative base. Primary interview data combined with secondary validation from FDA device manufacturing guidance, EMA quality system documentation, METI measurement traceability standards, and MFDS medical device production rules. Bottom-up shipment analysis across sensing technology tiers triangulated against top-down expenditure estimates from precision manufacturing clusters in Germany, Japan, and South Korea.
Sensitivity analysis tested forecast robustness across silicon allocation scenarios, regulatory enforcement timing variations, and substitution elasticity parameters. The analytical framework modeled product type, end user industry, technology configuration, and application context across the projection horizon. CAGRs derived from segment-level growth differentials weighted by installed base evolution and replacement cycle compression. Industry-specific inputs included aerospace tier supplier specification surveys and pharmaceutical equipment manufacturer validation protocol audits.
Forecasts assume regulatory continuity in EMA quality systems, FDA device manufacturing standards, and METI traceability regimes; material policy shifts would require re-modeling. Cybersecurity mandate evolution for connected industrial instruments and ISO 17025 laboratory accreditation expansion timelines represent specific revision triggers. Practitioners should keep alternative scenarios live as EU AI Act enforcement granularity and semiconductor foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
State Transition Testing Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Test and Measurement Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Digital Weighing Machine Market