

Satellite Communications and Direct-to-Device RF Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communications and Direct-to-Device RF Test Platforms Market Insights
India is tilting toward indigenous satcom test capacity through ISRO-aligned manufacturing zones and specialized RF foundries. Boeing sustains dual-use technology leadership by bridging military waveform validation with commercial direct-to-device protocols. Airbus dominates European ground station certification through its integrated signal analyzer and network simulator portfolios. Lockheed Martin anchors North American defense demand with classified-band RF test systems for resilient satellite communications.
Satellite Communications and Direct-to-Device RF Test Platforms encompass calibrated instrumentation that validates radio frequency performance across L-band through Ka-band spectra, measuring parameters including phase noise below -100 dBc/Hz, error vector magnitude, and spurious emissions compliance for non-terrestrial network integration. These systems enable manufacturers to verify that terrestrial chipsets and antennas maintain link budget integrity when handed off to orbiting constellations without dedicated ground infrastructure. Spectrum analyzers and signal generators command the largest revenue share within product type segmentation due to their ubiquity across aerospace testing and maritime connectivity validation workflows. Millimeter wave and MIMO technology segments are expanding fastest as mobile network operators pressure equipment vendors to certify beamforming arrays for dense urban direct-to-device coverage.
FCC Part 25 rules govern US market access for earth station equipment, while the EU AI Act and CE marking frameworks impose conformity assessment burdens on automated test sequences deployed within European aerospace laboratories. India's TRAI spectrum recommendations and BIS electromagnetic compatibility standards shape procurement specifications for domestic network integration firms serving defense accounts. Stakeholders must monitor how fragmented national licensing timelines for satellite-to-device spectrum bands affect capital deployment planning for test platform refresh cycles.
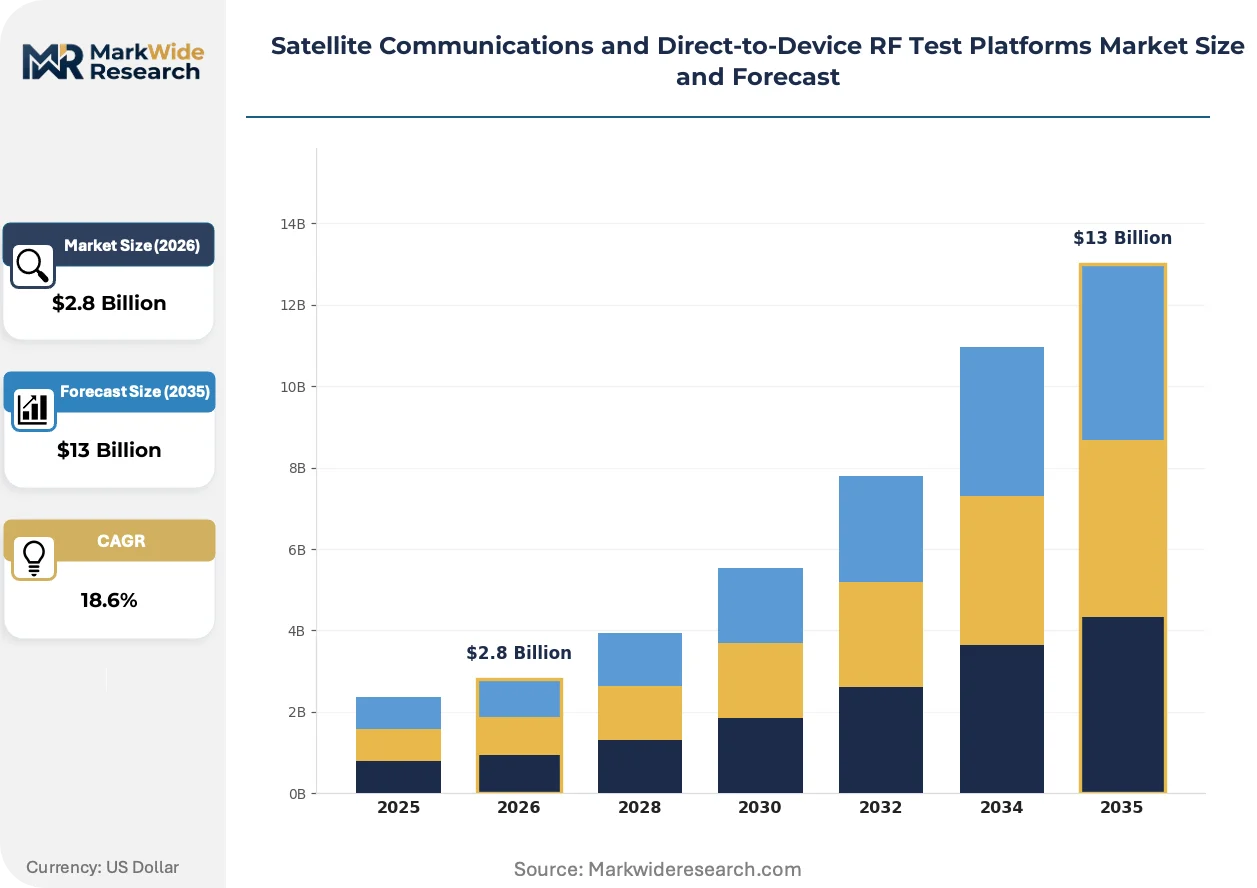
Market Dynamics
Defense procurement cycles for direct-to-device satellite links are compressing validation timelines, forcing test platform vendors to recalibrate hardware-software architectures for multi-band certification. Equipment manufacturers now face simultaneous pressure from NATO waveform standardization and commercial 5G NR-over-satellite integration requirements.
Growth Catalysts
- FCC Part 25 Recertification Mandates:Updated earth station equipment rules in the United States are accelerating replacement of legacy RF validation benches. Test platform vendors are capturing upgrade revenue from satellite chipset manufacturers seeking rapid market access.
- 5G NR-over-Satellite Protocol Adoption:Mobile network operators in Germany are demanding beamforming array validation for dense urban coverage. Aerospace laboratories are procuring millimeter-wave test systems to certify handoff integrity between terrestrial and orbital networks.
- India's ISRO-Aligned Manufacturing Zones:Domestic RF foundry capacity expansion is reducing import dependency for defense-grade spectrum analyzers. Specialized test equipment production is concentrating near Bangalore and Hyderabad satellite integration facilities.
Market Restraints
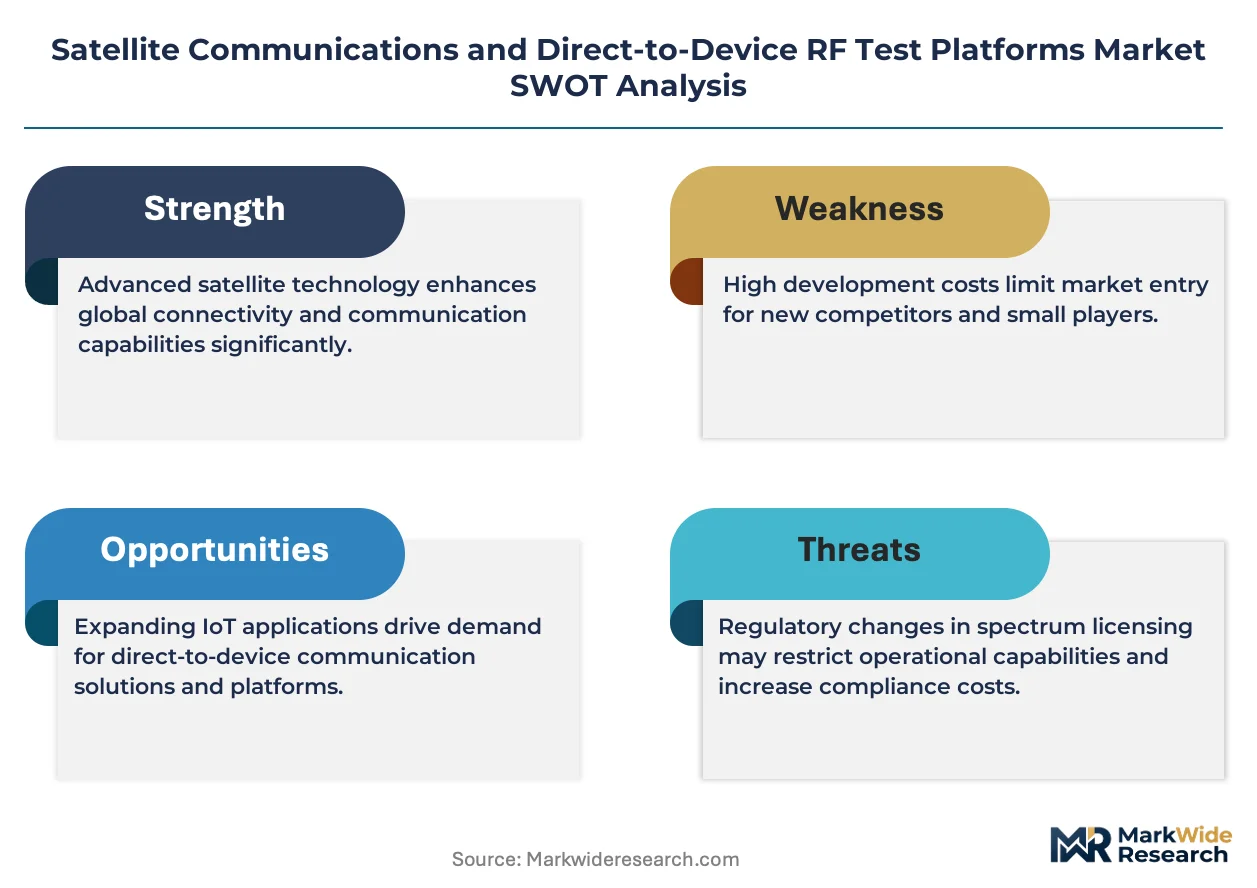
- Gallium Nitride Substrate Volatility:Power amplifier components for Ka-band test systems face input cost swings from limited semiconductor foundry capacity. RF signal generator margins compress when substrate procurement extends beyond six-month horizons.
- European CE Marking Burden:Automated test sequence conformity assessment under EU AI Act frameworks adds documentation overhead. Small-scale aerospace laboratories in France and Italy delay capital expenditure due to uncertain certification timelines.
- Terrestrial 5G Infrastructure Substitution:Dense fiber and small-cell deployments in urban corridors reduce satellite-to-device addressable market for certain mobility applications. Test platform demand softens where ground-based alternatives achieve comparable latency.
Strategic Opportunities
- Maritime and Aeronautical Connectivity Gaps:Uncerved oceanic routes and polar flight corridors present untapped demand for L-band direct-to-device validation. Test platform vendors can anchor long-term service contracts with constellation operators targeting these verticals.
- EU Green Deal Semiconductor Incentives:Carbon-neutral manufacturing mandates are channeling public capital into domestic RF component foundries. Equipment vendors securing green certification for test benches gain preferential access to European defense procurement frameworks.
- Digital Twin Convergence with RF Simulation:Virtualized test environments are merging with physical hardware-in-the-loop systems. Vendors offering integrated digital-physical validation workflows capture premium positioning against standalone instrument competitors.
Industry Challenges
- Multi-Band Calibration Expertise Scarcity:Phase noise measurement below -100 dBc/Hz across L-band through Ka-band spectra requires specialized microwave engineering talent. Defense contractors in the United States and Germany compete for limited pools of qualified RF metrologists.
- Legacy Satcom Test Bench Integration:Aerospace laboratories face technical debt from 1990s-era ground station certification equipment. Hybrid validation workflows combining obsolete hardware with modern direct-to-device protocols create interoperability failures and extended commissioning periods.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communications and Direct-to-Device RF Test Platforms Market Trends and Innovations
Software-defined instrumentation is displacing fixed-function hardware across RF validation workflows, compressing capital cycles and enabling remote calibration services. This architectural shift reconfigures vendor competitive positioning around firmware update velocity rather than hardware refresh rates.
Vector signal analysis hardware is virtualizing through FPGA-based reconfigurable computing platforms. Satellite chipset manufacturers in Germany and the United States are adopting these systems to compress multi-protocol certification timelines from months to weeks. The technology is virtualizing traditional spectrum analyzer market segmentation by collapsing discrete instrument categories into unified software-configurable benches.
EU AI Act conformity requirements for automated test sequences are mandating algorithmic transparency documentation. European aerospace laboratories must now maintain audit trails for machine-learning-assisted spurious emissions detection. RF test platform vendors serving France, Germany, and Italy are reengineering firmware architectures to satisfy CE marking frameworks for artificial intelligence-enabled instrumentation.
Defense procurement offices are consolidating validation contracts under multi-year managed service agreements. Prime contractors in the United States and NATO member states now prefer outcome-based test platform subscriptions over capital purchase models. This pattern concentrates vendor relationships around integrated service capabilities rather than discrete equipment transactions, with Germany's Bundeswehr laboratories leading contract structure innovation.
Satellite Communications and Direct-to-Device RF Test Platforms Market Segmentation
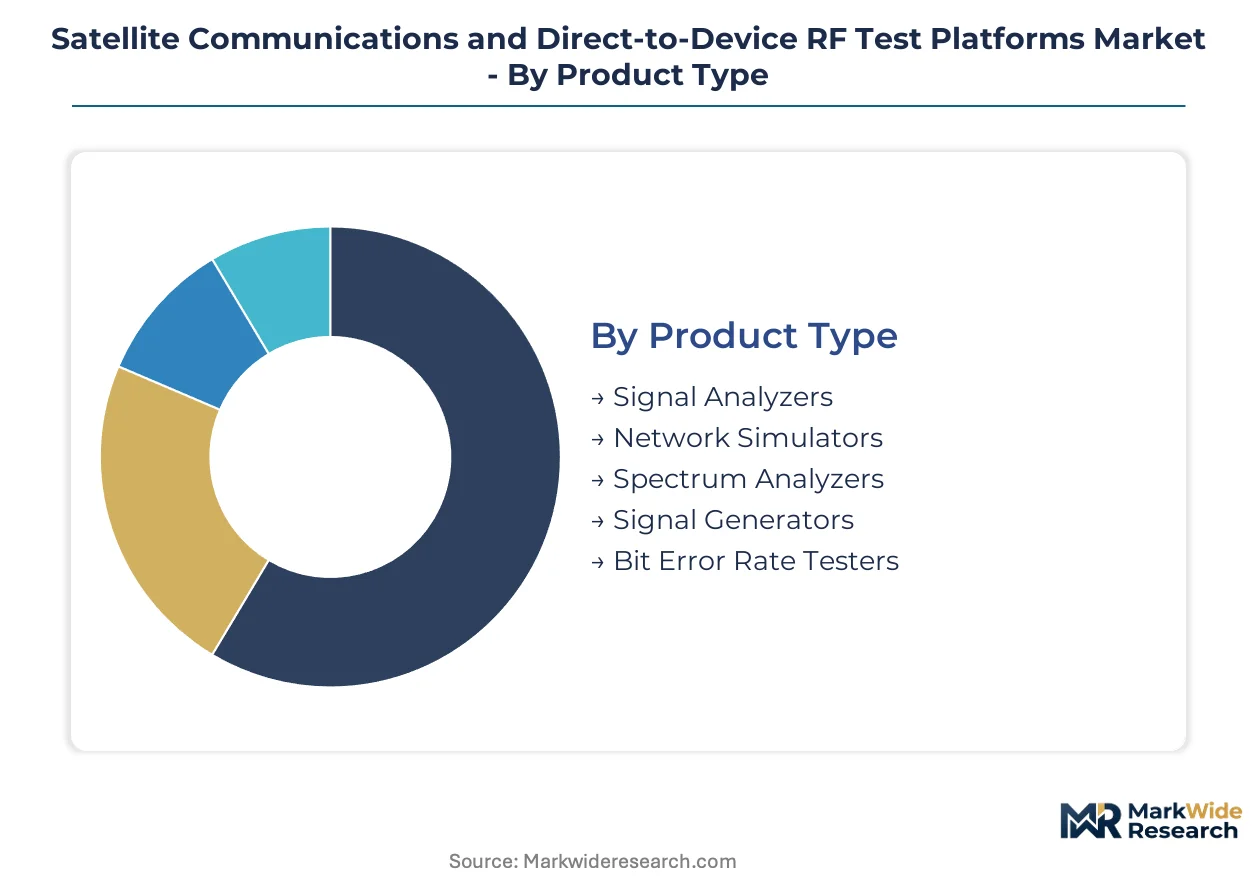
RF test platform procurement patterns diverge sharply across instrumentation categories, with replacement cycles ranging from three-year software-defined upgrades to decade-long hardware installations. Understanding these temporal dynamics helps vendors align R&D pipelines with predictable refresh windows across defense, commercial, and research accounts.
Product Type:
Calibration-intensive instruments face shorter replacement cycles as 5G NR-over-satellite protocols demand continuous firmware evolution, while hardware-dominant platforms exhibit extended depreciation schedules in budget-constrained aerospace laboratories.
- Signal Analyzers:Vector-capable architectures measuring modulation accuracy and spurious emissions across L-band through Ka-band spectra. German aerospace laboratories in Munich and Bremen are upgrading these systems to validate beamforming integrity for dense urban direct-to-device coverage.
- Network Simulators:Hardware-in-the-loop platforms emulating orbital constellation dynamics and atmospheric channel impairments. NATO defense procurement offices in Belgium and Norway are consolidating multi-year managed service agreements around these systems to compress waveform validation timelines.
- Spectrum Analyzers:Ubiquitous instrumentation for regulatory compliance verification and interference hunting. India's ISRO-aligned manufacturing zones near Bangalore are expanding domestic production capacity to reduce import dependency.
- Signal Generators:Precision sources for stimulus-response testing of satellite chipsets and antenna arrays. Phase noise specifications below -100 dBc/Hz drive premium positioning in defense-grade procurement.
- Bit Error Rate Testers:Dedicated systems for link budget validation under degraded signal conditions. Maritime connectivity providers specify these for oceanic route certification.
Spectrum analyzers dominate installed base across commercial and research accounts. Signal generators and network simulators are where expansion concentrates as defense procurement cycles compress validation timelines.
Technology:
Protocol-layer technologies command premium pricing due to certification complexity, while physical-layer innovations face margin pressure from rapid standardization cycles.
- 5G NR:Non-terrestrial network extensions of 3GPP Release 17 and 18 specifications requiring beam management and timing advance validation. Mobile network operators in Germany are demanding these capabilities for urban direct-to-device coverage.
- LTE:Legacy satellite-terrestrial integration protocols with established certification pathways. Maritime operators maintain installed base for L-band connectivity continuity.
- Satellite Modem:Proprietary waveform implementations from constellation operators requiring custom validation environments. Defense organizations specify these for resilient communications in contested spectrum.
- Millimeter Wave:E-band and W-band test capabilities for next-generation high-throughput satellites. Aerospace laboratories face technical debt integrating these with 1990s-era ground station equipment.
- MIMO:Multi-antenna beamforming validation for spatial multiplexing gains. FCC Part 25 recertification mandates are accelerating replacement of legacy single-channel test benches.
- OFDM:Orthogonal frequency-division multiplexing analysis for broadband satellite links. India's TRAI spectrum recommendations shape procurement specifications for domestic network integration firms.
Millimeter wave and MIMO technologies are climbing the fastest as mobile network operators pressure equipment vendors to certify beamforming arrays. LTE maintains largest installed base among maritime and aeronautical connectivity providers.
Application:
Defense-adjacent applications sustain premium pricing through classified-band requirements, while commercial connectivity segments face cost pressure from terrestrial 5G infrastructure substitution.
- Satcom Ground Stations:Earth station certification encompassing antenna pattern measurement and interference coordination. EU AI Act conformity requirements are mandating algorithmic transparency documentation for automated test sequences in France and Italy.
- Mobile Network Operators:Direct-to-device protocol validation for smartphone-integrated satellite chipsets. Germany's Bundeswehr laboratories are leading contract structure innovation toward outcome-based subscriptions.
- Aerospace Testing:Environmental qualification and flight-heritage verification for space-rated RF components. Gallium nitride substrate volatility compresses margins for Ka-band power amplifier test systems.
- Public Safety Communications:Resilient satellite backup for terrestrial network failures. India's BIS electromagnetic compatibility standards shape procurement for domestic defense accounts.
- Maritime Connectivity:L-band validation for uncerved oceanic routes. Test platform vendors anchor long-term service contracts with constellation operators targeting these verticals.
Satcom ground stations represent the most mature revenue pool. Mobile network operator demand is gaining share fastest as 5G NR-over-satellite protocols commercialize.
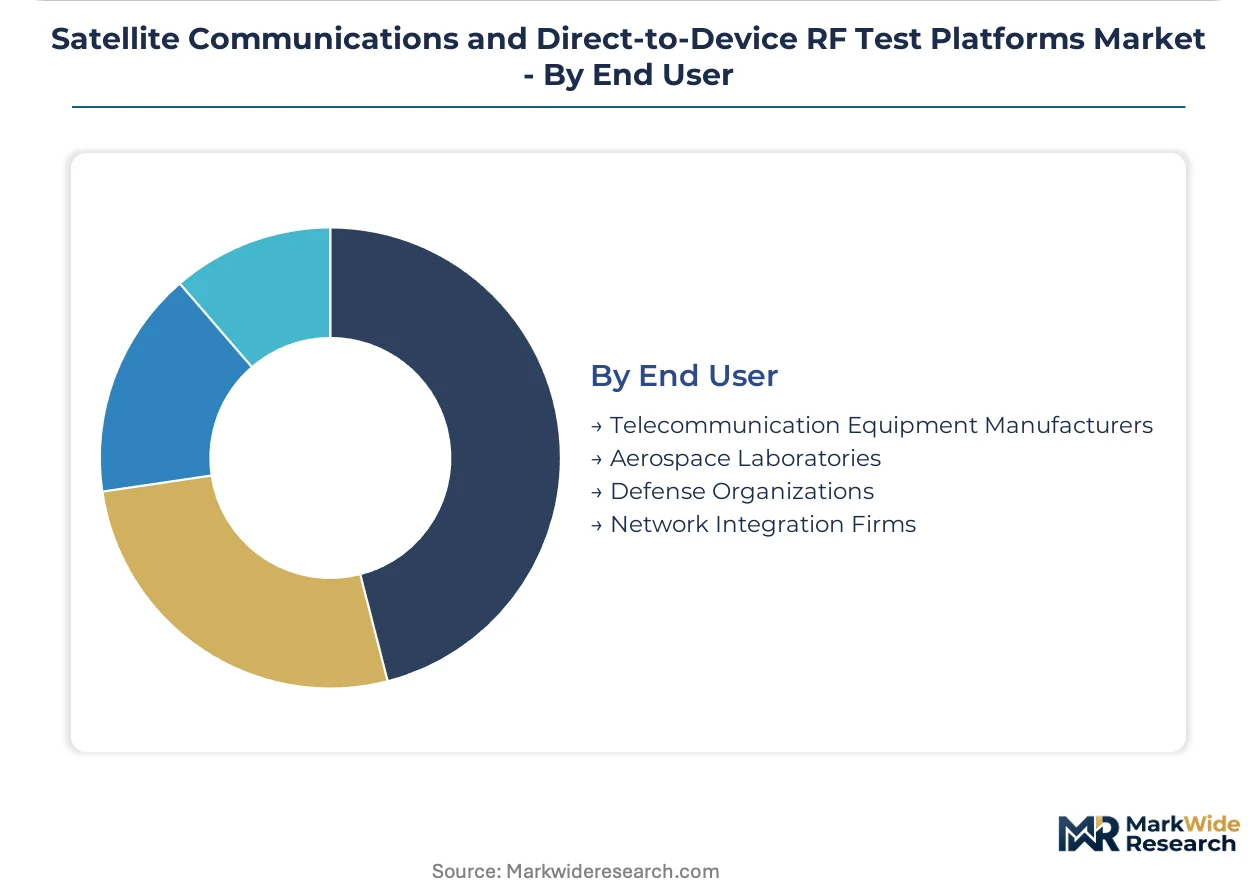
End User:
Defense procurement offices consolidate validation contracts under multi-year agreements, while commercial equipment manufacturers prioritize capital efficiency through software-defined instrumentation.
- Telecommunication Equipment Manufacturers:Chipset and antenna vendors requiring rapid multi-protocol certification. FPGA-based reconfigurable computing platforms are compressing timelines from months to weeks.
- Aerospace Laboratories:Research institutions and satellite integrators in Germany, France, and Italy. CE marking burden under EU AI Act frameworks delays capital expenditure due to uncertain certification timelines.
- Defense Organizations:Classified-band RF test systems for resilient satellite communications. Lockheed Martin anchors North American demand with specialized waveform validation requirements.
- Network Integration Firms:System integrators serving hybrid terrestrial-satellite deployments. India's PLI scheme channels public capital into domestic RF component foundries near Hyderabad.
Telecommunication equipment manufacturers command largest volume. Defense organizations sustain highest margin positioning through security-cleared service requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 25 recertification mandates are accelerating equipment replacement cycles across the United States. Defense procurement offices in NATO member states are compressing validation timelines for direct-to-device satellite links. Manufacturing zones aligned with national space agencies are expanding domestic RF foundry capacity in Asia-Pacific.
United States
Lockheed Martin anchors classified-band RF test system demand for resilient satellite communications. FCC Part 25 rules govern earth station equipment market access and accelerate replacement of legacy validation benches. Greater Boston and Colorado Springs host aerospace laboratories upgrading multi-band certification capabilities.
Germany
Bundeswehr laboratories are leading contract structure innovation toward outcome-based test platform subscriptions. EU AI Act and CE marking frameworks impose conformity assessment burdens on automated test sequences. Munich and Bremen aerospace clusters are procuring millimeter-wave systems for 5G NR-over-satellite protocol validation.
India
ISRO-aligned manufacturing zones are expanding domestic RF foundry capacity to reduce import dependency. TRAI spectrum recommendations and BIS electromagnetic compatibility standards shape procurement specifications for defense accounts. Bangalore and Hyderabad satellite integration facilities are concentrating specialized test equipment production.
France
Thales represents European ground station certification capabilities through integrated signal analyzer portfolios. EU AI Act algorithmic transparency requirements mandate audit trails for machine-learning-assisted emissions detection. Aerospace laboratories in Toulouse and Paris-Saclay delay capital expenditure due to uncertain certification timelines.
United Kingdom
Airbus maintains integrated network simulator positioning for European defense procurement frameworks. CE marking documentation overhead affects small-scale aerospace laboratories in England and Scotland. Harwell and Farnborough clusters are consolidating validation contracts under multi-year managed service agreements.
Satellite Communications and Direct-to-Device RF Test Platforms Market Competitive Landscape
Defense prime contractors and commercial aerospace conglomerates split the market between classified-band security requirements and commercial direct-to-device protocol certification. The vendor base concentrates around dual-use technology leadership and integrated signal analyzer portfolios. Two strategic archetypes dominate: vertically integrated defense primes with security-cleared service capabilities, and commercial aerospace specialists bridging military waveform validation with 5G NR-over-satellite integration. Competitive moves center on multi-year managed service contract consolidation and FPGA-based reconfigurable computing platform development.
Among United States-based defense primes, Lockheed Martin and Boeing exemplify the security-cleared archetype, anchoring North American demand through classified-band RF test systems and dual-use technology bridges. Airbus occupies a position representing European commercial-aerospace integration, dominating ground station certification through signal analyzer and network simulator portfolios. These three entities sit within the premium-tier vendor segment where outcome-based subscription models are displacing capital purchase structures.
| Leading Market Players |
|---|
| Lockheed Martin |
| Boeing |
| Airbus |
| Northrop Grumman |
| Thales |
| RTX |
| Hughes Network Systems |
| Viasat |
| Iridium Communications |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate volatility determines both pricing tier spreads and supply chain shape across RF test platform manufacturing. Defense-grade signal generators drawing from limited semiconductor foundry capacity command premium positioning against commercial spectrum analyzers sourced through diversified Asian component networks.
Pricing Analysis
Geographic price spreads widen between German aerospace laboratories procuring CE-marked automated test sequences and Indian network integration firms sourcing BIS-compliant equipment through domestic ISRO-aligned manufacturing zones. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from gallium nitride input cost swings compressing Ka-band power amplifier margins. Telecommunication equipment manufacturers exhibit highest price sensitivity due to rapid multi-protocol certification cycles, while defense organizations sustain lowest sensitivity through security-cleared service requirements.
Supply Chain Analysis
International Traffic in Arms Regulations and export control regimes limit flows of classified-band RF test systems between NATO member states and non-aligned procurement offices. Component manufacturing concentrates in Germany for precision signal analyzers, the United States for FPGA-based reconfigurable computing platforms, and India for ISRO-aligned spectrum analyzer production. Raw material dependencies center on gallium nitride substrates for Ka-band power amplifiers, specialized microwave connectors for millimeter-wave systems, and radiation-hardened FPGAs for space-rated validation equipment. Single-source vulnerability from limited qualified RF metrologist pools creates bottlenecks in multi-band calibration expertise. Distribution runs through direct sales channels for defense accounts and authorized distributor networks for commercial equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FCC Part 25 recertification mandates and EU AI Act conformity requirements create structural barriers that favor incumbents with established certification pathways and security-cleared service capabilities.
For Market Incumbents: Insulate installed base relationships by anchoring multi-year managed service agreements with NATO defense procurement offices facing compressed waveform validation timelines. Deepen backward integration into gallium nitride substrate sourcing to buffer margin compression from semiconductor foundry capacity constraints. Acquire specialized RF metrology talent pools in Munich and Colorado Springs to defend against emerging entrants targeting multi-band calibration expertise scarcity.
For New Entrants and Emerging Players: India's underpenetrated domestic RF foundry capacity presents white-space opportunity for ISRO-aligned manufacturing zone partnerships. Maritime connectivity gaps across uncerved oceanic routes offer service contract entry points with constellation operators seeking L-band direct-to-device validation. Target outcome-based subscription models for small-scale aerospace laboratories in France and Italy delaying capital expenditure due to EU AI Act uncertainty.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated defense primes with dual-use technology bridges. Long-term viability rests on sustained defense procurement cycle compression and 5G NR-over-satellite protocol commercialization. Acquisition targets should exhibit FPGA-based reconfigurable computing platform development capabilities and established CE marking documentation frameworks. Watch FCC Part 25 rule amendments as the signal indicating accelerated equipment replacement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Managed Service Agreement | Bundeswehr laboratories are consolidating validation contracts under outcome-based subscription structures. |
| FPGA-based Reconfigurable Computing Platform | German satellite chipset manufacturers compress multi-protocol certification timelines from months to weeks. |
| ISRO-aligned Manufacturing Zone Partnership | Domestic RF foundry capacity expansion near Bangalore reduces import dependency for defense-grade spectrum analyzers. |
| EU AI Act Conformity Certification | Algorithmic transparency documentation mandates reengineer firmware architectures for France, Germany, and Italy. |
| Digital Twin Convergence with RF Simulation | Virtualized test environments merge with hardware-in-the-loop systems for premium positioning against standalone instruments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry technical documentation. Interviews with RF test platform engineering directors, defense procurement officers, aerospace laboratory managers, and satellite chipset validation leads informed demand-side perspectives. Secondary sources encompassed FCC Part 25 rule dockets, EU AI Act implementation guidance, TRAI spectrum recommendations, and BIS electromagnetic compatibility standards. Bottom-up equipment shipment analysis triangulated against top-down defense budget allocation reviews across NATO member states.
Forecast inputs span product type segmentation across signal analyzers, network simulators, spectrum analyzers, signal generators, and bit error rate testers. Technology dimensions include 5G NR, millimeter wave, MIMO, and satellite modem protocols. Application coverage encompasses satcom ground stations, mobile network operators, aerospace testing, public safety communications, and maritime connectivity. End-user modeling separates telecommunication equipment manufacturers, aerospace laboratories, defense organizations, and network integration firms. CAGRs were derived from regression analysis of historical procurement cycles against projected FCC recertification mandates and 5G NR-over-satellite protocol adoption curves. Industry-specific inputs incorporated gallium nitride substrate pricing volatility indices and qualified RF metrologist labor market tightness metrics.
Macroeconomic conditions sit as an overlay; deviation in defense budget trajectories, semiconductor foundry capacity expansion, or satellite-to-device spectrum licensing timelines would shift the trajectory. Forecasts reflect assumptions regarding sustained NATO waveform standardization pressure and commercial 5G NR integration requirements. Material shifts in FCC Part 25 rule amendments or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.