
 One-Box Testers Market | 2026-2036
One-Box Testers Market Size, Share, and Industry Trends Forecast 2026-2036
One-Box Testers Market Outlook
Semiconductor fabrication is pivoting toward consolidated metrology workflows that reduce floor-space and calibration overhead. Keysight Technologies leverages its instrumentation heritage to dominate high-frequency signal analysis within one-box architectures. Rohde & Schwarz anchors European demand through precision electromagnetic compliance testing. Anritsu competes aggressively in Asia-Pacific 5G device certification, where single-instrument throughput determines contract wins.
One-box testers integrate multiple measurement functions—spectrum analysis, vector network analysis, power metering, and protocol testing—into a single chassis with unified software control, eliminating cable routing errors and reducing test-cell footprint by half. Lab-Based Testers capture the deepest margin pools where R&D budgets fund configurable multi-domain platforms; Portable Testers represent the fastest-expanding category as field maintenance teams abandon van-loaded instrument stacks. Automated Analyzers sustain structural growth in clinical diagnostics, where ELISA and PCR modules now share fluidic handlers and optical readheads within unified enclosures.
The FDA's 21 CFR Part 820 Quality System Regulation shapes design controls for diagnostic one-box systems sold into US hospitals, while the EU In Vitro Diagnostic Regulation (IVDR) imposes clinical evidence requirements that favor established CE-marked platforms over novel entrants. China's NMPA accelerates review timelines for domestically manufactured biosensor-integrated analyzers under its innovation device pathway. Stakeholders must monitor how divergent post-market surveillance obligations between jurisdictions affect platform architecture decisions and service revenue models.
Market Dynamics
Semiconductor fabs are consolidating test-cell footprints to reclaim cleanroom space, compressing multi-instrument racks into unified chassis architectures that slash calibration cycles and cable-induced measurement uncertainty.
Growth Catalysts
- Fab Consolidation:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding 3nm capacity in Hsinchu and Pyeongtaek, creating procurement pull for single-chassis RF-parametric testers that halve floor-space requirements.
- EU IVDR Compliance:The In Vitro Diagnostic Regulation's 2027 enforcement deadline forces European clinical labs to replace fragmented ELISA workstations with integrated analyzers bearing unified CE-marking.
- 5G mmWave Certification:South Korea's spectrum auction of 28GHz bands for private networks is accelerating demand for one-box vector network analyzers capable of protocol and signal integrity testing.
Market Restraints
- GaN Substrate Costs:Gallium nitride wafers for high-frequency test heads remain 3-4x pricier than silicon alternatives, constraining margin expansion in sub-6GHz portable tester segments.
- Japanese Component Concentration:Precision attenuators and directional couplers source predominantly from Osaka-based suppliers, exposing chassis manufacturers to single-source disruption risks.
- Thermal Management Limits:Dissipating 400W+ from multi-domain modules within sealed 2U enclosures requires exotic heat-pipe assemblies that extend development timelines by 8-12 months.
Strategic Opportunities
- India PLI Incentives:The Production Linked Incentive scheme for telecom equipment manufacturing offers 4-6% duty credit on domestic assembly of 5G test instruments, attracting chassis integrators to Bengaluru and Hyderabad.
- Quantum Device Characterization:Cryogenic probe stations require microwave vector network analysis at millikelvin temperatures, opening white space for specialized one-box platforms with integrated dilution refrigerator interfaces.
- US FDA Breakthrough Device Pathway:Streamlined premarket review for multi-analyte infectious disease panels is shortening time-to-revenue for consolidated diagnostic platforms targeting hospital central labs.
Industry Challenges
- Multi-Physics Simulation Talent:Designing thermal-electromagnetic co-simulation models for dense chassis layouts requires expertise in both COMSOL and HFSS toolchains that pools narrowly in Munich, Boston, and Tokyo metro areas.
- Legacy GPIB Integration:Defense and aerospace test facilities in the United States maintain decades-old instrument ecosystems, forcing one-box vendors to support obsolete bus architectures that consume 15-20% of firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Box Testers Market |
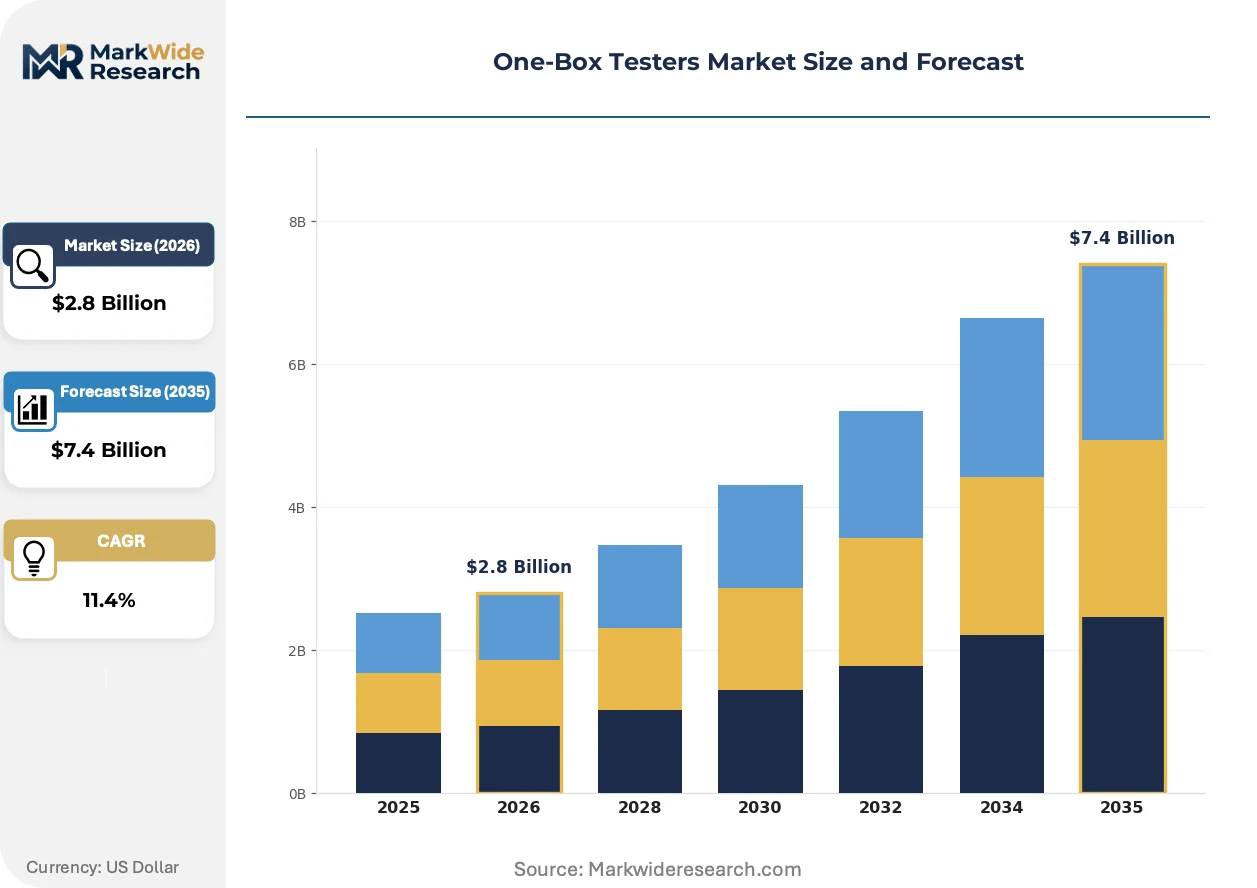
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Lab-Based Testers, Automated Analyzers, Handheld Devices Application: Clinical Diagnostics, Environmental Testing, Food Safety, Industrial Quality Control Technology: Enzyme-Linked Immunosorbent Assay, PCR, Lateral Flow, Biosensors End User: Hospitals, Laboratories, Food Manufacturers, Agriculture Providers |
| Companies Covered | Keysight Technologies, Anritsu, Rohde & Schwarz, National Instruments, Viavi Solutions, Tektronix, Teradyne, Chroma ATE, Teledyne LeCroy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Box Testers Market Strategic Shifts
Modular software-defined instrumentation is collapsing traditional hardware boundaries, enabling firmware-upgradable measurement personalities that extend chassis utility across product generations without physical retrofit.
Software-defined radio architectures are consolidating spectrum analysis, vector signal generation, and real-time protocol decoding into reprogrammable FPGA fabrics. 5G baseband chipset vendors in South Korea and Taiwan are deploying these platforms for regression testing across 3GPP release iterations, compressing capital equipment refresh cycles from five years to eighteen months.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing thermal design teams to abandon compressor-based cooling in favor of thermoelectric and liquid-loop systems. Clinical diagnostic OEMs serving European hospital networks are requalifying instrument enclosures for passive convection, trading measurement density for refrigerant compliance.
Service unbundling is fragmenting traditional capital-sale contracts into hardware-as-a-service arrangements with per-test metering. North American contract research organizations are piloting subscription models where one-box chassis remain vendor-owned, with laboratories paying only for validated measurement hours consumed during drug stability studies.
One-Box Testers Market Segmentation
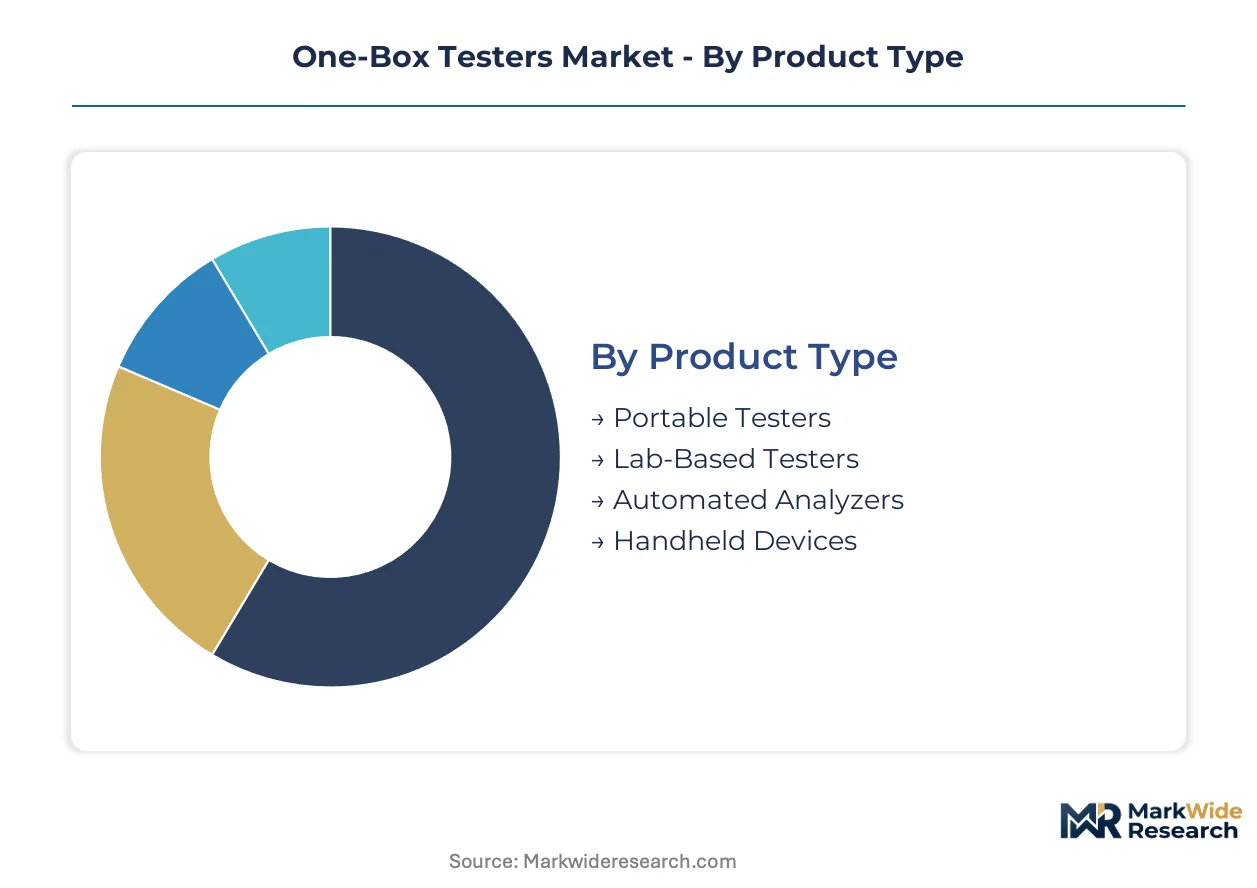
One-box tester procurement decisions pivot on throughput requirements, regulatory validation burdens, and physical deployment constraints. Buyers trade configurability against footprint, creating distinct margin pools across stationary and mobile form factors.
Product Type:
Capital allocation intensity separates buyers seeking permanent installation from those prioritizing field mobility.
- Portable Testers:Battery-powered chassis integrate spectrum analysis and power metering for 5G base station commissioning crews. South Korean telecom contractors deploy these units for rooftop antenna alignment, cutting van-loaded instrument counts by two-thirds.
- Lab-Based Testers:19-inch rack-mount platforms with unified software control dominate semiconductor R&D facilities in Germany and the United States. These systems command premium pricing through multi-domain measurement personalities that eliminate cable-induced uncertainty.
- Automated Analyzers:Clinical diagnostic platforms with shared fluidic handlers and optical readheads consolidate ELISA and PCR workflows within single enclosures.
- Handheld Devices:Single-purpose units target environmental field teams requiring immediate contaminant screening without laboratory logistics.
Lab-Based Testers lead on scale; Portable Testers lead on momentum.
Application:
Regulatory validation timelines and reimbursement pathways determine adoption velocity across use cases.
- Clinical Diagnostics:Multi-analyte infectious disease panels face FDA 21 CFR Part 820 design controls and EU IVDR clinical evidence requirements. Hospital central labs in the United States favor consolidated platforms that streamline CAP accreditation audits.
- Environmental Testing:Field crews prioritize battery endurance and ingress protection over measurement precision. German industrial hygiene contractors deploy one-box units for workplace air quality monitoring under ECHA REACH obligations.
- Food Safety:Rapid pathogen detection at processing lines demands lateral flow and PCR modules within washdown-rated enclosures.
- Industrial Quality Control:Manufacturing floors integrate RF-parametric testers for component screening without cleanroom infrastructure.
Clinical Diagnostics commands the deepest margins; Environmental Testing is climbing the fastest.
Technology:
Detection chemistry and readout mechanism dictate instrument architecture and service revenue potential.
- Enzyme-Linked Immunosorbent Assay:Colorimetric endpoint detection with automated plate handling dominates high-throughput serology screening. European laboratories migrating from fragmented workstations drive replacement demand ahead of IVDR enforcement.
- PCR:Thermal cycling with real-time fluorescence quantification enables pathogen load measurement. South Korean reference laboratories deploy integrated extraction-to-detection platforms for respiratory panel validation.
- Lateral Flow:Immunochromatographic strips with optical readers support point-of-care deployment without cold chain logistics.
- Biosensors:Electrochemical and optical transducers enable continuous monitoring applications with minimal reagent consumption.
PCR leads on scale; Biosensors lead on momentum.
End User:
Procurement authority and technical staffing levels shape configuration complexity and service contract terms.
- Hospitals:Central laboratory directors prioritize CAP-compliant platforms with unified validation documentation. US health systems consolidate vendor relationships through IDN purchasing agreements that favor established CE-marked analyzers.
- Laboratories:Independent reference labs balance test menu breadth against capital constraints, driving interest in firmware-upgradable chassis.
- Food Manufacturers:Quality assurance teams require HACCP-aligned documentation and rapid turnaround for production hold decisions.
- Agriculture Providers:Cooperative extension services and large-scale growers deploy portable units for soil and crop residue screening without laboratory infrastructure.
Hospitals lead on scale; Laboratories lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting one-box tester assembly toward jurisdictions where compliance costs compress margins less severely. India's PLI incentives and China's NMPA fast-track pathways are pulling manufacturing investment away from higher-cost validation regimes.
United States
Defense contractors and semiconductor R&D facilities drive demand for multi-domain chassis with legacy GPIB compatibility. The FDA's 21 CFR Part 820 Quality System Regulation shapes design controls for diagnostic platforms sold into hospital central labs. Austin and Boston metro areas concentrate RF-parametric tester development for 5G baseband validation.
Germany
Automotive EMC testing laboratories and industrial automation OEMs procure precision electromagnetic compliance platforms. The EU F-Gas Regulation's refrigerant phasedown forces thermal design requalification for sealed chassis. Munich and Stuttgart host concentrated metrology engineering talent pools for dense multi-physics simulation.
South Korea
Samsung Foundry and SK Hynix fab expansions in Pyeongtaek and Icheon generate procurement pull for single-chassis RF testers. The MFDS accelerates review timelines for domestically manufactured biosensor-integrated analyzers. Seoul Capital Area contract manufacturers assemble 5G mmWave certification units for private network deployments.
China
Domestic fab construction and clinical laboratory consolidation create dual demand streams for consolidated testing systems. The NMPA innovation device pathway shortens approval timelines for multi-analyte platforms. Yangtze River Delta chassis integrators leverage local supply chains for precision attenuators and directional couplers.
India
Telecom equipment PLI schemes attract 5G test instrument assembly to Bengaluru and Hyderabad facilities. The CDSCO aligns with streamlined premarket pathways for infectious disease diagnostic platforms. Domestic integrators capture 4-6% duty credits on local chassis production for export markets.
One-Box Testers Market Competitive Environment
Capacity expansion dominates the current landscape as chassis manufacturers add cleanroom assembly lines to capture fab procurement cycles. The vendor base stratifies across three tiers: diversified instrumentation conglomerates with unified software ecosystems, specialized RF/microwave houses with electromagnetic compliance heritage, and emerging Asia-Pacific integrators leveraging component proximity. Strategic archetypes include full-stack platform vendors, modular subsystem suppliers, and firmware-defined personality specialists. Geographic expansion and technology licensing represent the dominant competitive moves, with players securing regional service networks and FPGA-based measurement IP.
Among diversified instrumentation conglomerates, Keysight Technologies and Rohde & Schwarz exemplify full-stack platform vendors with heritage in high-frequency signal analysis and precision electromagnetic testing. Anritsu occupies a position within the specialized RF/microwave tier, representing Asia-Pacific-centric competitive positioning around 5G device certification throughput. These three companies anchor the premium chassis segment where unified software control and multi-domain measurement personalities command pricing premiums against modular alternatives.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu |
| Rohde & Schwarz |
| National Instruments |
| Viavi Solutions |
| Tektronix |
| Teradyne |
| Chroma ATE |
| Teledyne LeCroy |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation's hydrofluorocarbon refrigerant phasedown gates qualified thermal-system supply and premium-tier pricing access for sealed chassis designs, forcing OEMs to absorb thermoelectric cooling cost premiums or surrender measurement density. Buyers seeking refrigerant-compliant platforms face extended lead times and tiered qualification premiums that stratify accessible supply.
Pricing Analysis
Distributor margin layers compress 12-18 points before chassis reach hospital central labs and semiconductor fabs. Three-tier pricing structure across premium, standard, and economy levels separates unified-software platforms from modular alternatives and refurbished legacy units. Cost compression in portable sub-6GHz segments intensifies because gallium nitride substrate premiums persist against silicon alternatives. Contract research organizations exhibit highest price sensitivity through hardware-as-a-service pilots, while defense contractors absorb premiums for GPIB backward compatibility.
Supply Chain Analysis
India's Production Linked Incentive scheme and China's NMPA innovation pathway are reshaping sourcing toward Bengaluru, Hyderabad, and Yangtze River Delta assembly clusters. Precision attenuators and directional couplers draw predominantly from Osaka-based suppliers, creating single-source vulnerability for chassis manufacturers. Distribution runs through authorized instrumentation distributors with factory-trained calibration capabilities, bypassing generic electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The one-box tester market compounds steadily as fab consolidation and clinical laboratory integration sustain replacement cycles across semiconductor and diagnostic end uses.
For Market Incumbents: Anticipate margin compression from Asia-Pacific chassis integrators by deepening firmware-defined measurement personalities that lock in software recurring revenue. Prioritize CE-marking investment ahead of EU IVDR enforcement to defend hospital central lab positions against emerging modular subsystem suppliers. For New Entrants and Emerging Players: Enter via cryogenic probe station interfaces for quantum device characterization, where established vendors lack integrated dilution refrigerator architectures. Target South Korean 5G private network certification labs with portable mmWave chassis that undercut rack-mount alternatives on footprint. For Investors and Strategic Acquirers: Roll-up economics work for specialized RF/microwave houses with electromagnetic compliance heritage because hospital and fab procurement favors unified vendor relationships over fragmented instrument stacks. Watch NMPA fast-track approval velocity for domestic Chinese biosensor-integrated analyzers as inflection indicator for Asia-Pacific manufacturing migration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Software-Defined Instrumentation | Firmware-upgradable measurement personalities extend chassis utility across 5G release iterations without physical retrofit. |
| Hardware-as-a-Service Transition | Per-test metering contracts with North American contract research organizations shift capital risk to vendors. |
| Refrigerant-Free Thermal Design | Thermoelectric and liquid-loop systems requalify sealed enclosures for EU F-Gas Regulation compliance. |
| Legacy Bus Architecture Support | GPIB compatibility maintains defense and aerospace test facility access despite 15-20% firmware overhead. |
| Regional Assembly Localization | India PLI and China NMPA pathways capture 4-6% duty credits and accelerated approval timelines. |
Study Parameters
Coverage spans the United States, Germany, South Korea, China, and India, with primary inputs from each combining interviews with fab test-cell engineers, clinical laboratory directors, biomedical procurement managers, and RF instrumentation channel partners against secondary validation through FDA 510(k) filings, NMPA innovation device registrations, EU IVDR technical documentation, semiconductor capital expenditure disclosures, and hospital GPO contract databases. Bottom-up chassis shipment triangulation against top-down fab and diagnostic lab capital budget aggregation anchors value estimates.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift and pricing trajectory across portable, lab-based, and automated analyzer form factors. Modeled segmentation spans product type, application, detection technology, and end-user procurement authority. CAGR derivation incorporates semiconductor fab capacity expansion schedules, EU IVDR workstation replacement deadlines, and 5G spectrum auction timing.
Inputs from regulatory filing databases and capital expenditure disclosures were available through the study window; gaps in private hospital procurement contract terms introduce uncertainty bands around diagnostic platform pricing assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Burst Strength Tester Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Semiconductor Curve Tracer Market